
 Indonesia Ready-Mix Concrete Market | 2026-2036
Indonesia Ready-Mix Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Ready-Mix Concrete Market Foresight
Skilled batch-plant technicians is rotating from Java's saturated corridors toward Sulawesi and Kalimantan as new smelter and port construction accelerates. Heidelberg Materials leverages its integrated cement-to-concrete network to dominate supply chains across Sumatra. PT Waskita Beton Precast Tbk anchors government-backed infrastructure tenders through its precast and ready-mix dual capabilities. Semen Indonesia Group extends its clinker logistics advantage into downstream ready-mix distribution in secondary cities.
Ready-mix concrete consists of cement, aggregates, water, and admixtures batched under controlled conditions for specified slump and compressive strength, typically delivered within ninety minutes of mixing to preserve workability. Its primary purpose is to eliminate on-site variability and accelerate construction schedules for large-scale builds. Infrastructure application claims the largest volume share as toll roads, dams, and rail projects specify high-strength grades for structural longevity. Truck-mixed delivery mode leads operational deployment due to flexibility across Indonesia's fragmented geography and remote project sites. Self-consolidating concrete commands premium positioning where dense rebar configurations and accelerated pour schedules justify the admixture cost.
BIS, Indonesia's national standards body, mandates concrete strength classification and quality testing protocols that shape product certification and project eligibility. The Ministry of Public Works and Housing enforces green building criteria through its Greenship rating system, pushing admixture suppliers toward lower-carbon formulations. Contractors and developers must monitor how BIS revisions to earthquake-resistant design standards will reshape mix-design requirements across the archipelago's seismic zones.
Market Dynamics
The Indonesia ready-mix concrete market is being fundamentally restructured by BIS certification tightening, which is forcing batch-plant consolidation and eliminating informal suppliers across Java's saturated corridors. This regulatory compression is redrawing competitive boundaries while megaproject procurement scales concentrate demand among certified operators.
Growth Catalysts
- IKN Nusantara Relocation:The new capital megaproject is absorbing millions of cubic meters of high-strength concrete, creating sustained procurement pull for certified suppliers through 2035.
- Smelter Construction Acceleration:Battery-grade nickel processing facilities in Sulawesi and Halmahera are specifying sulfate-resistant concrete grades, expanding addressable demand beyond traditional infrastructure.
- Ministry of Public Works Greenship Mandates:Green building rating requirements are pushing admixture innovation toward lower-carbon formulations, creating premium positioning for compliant suppliers.
Market Restraints
- Clinker Import Dependency:Domestic cement capacity constraints force reliance on Vietnamese and Chinese clinker shipments, exposing margins to shipping rate volatility and currency fluctuation.
- Java Supply Saturation:Batch-plant density in the Jakarta-Bandung corridor has compressed utilization rates below viable thresholds for independent operators without captive cement supply.
- Technical Limitation on Remote Delivery:The ninety-minute workability window restricts viable supply radius to forty kilometers, fragmenting effective market addressability across Indonesia's archipelagic geography.
Strategic Opportunities
- Kalimantan Industrial Estates:Greenfield smelter and petrochemical zones offer first-mover positioning for integrated cement-concrete operators establishing captive batch plants.
- Self-Consolidating Concrete:Dense rebar configurations in high-rise construction and accelerated pour schedules are creating premium application demand that justifies admixture cost premiums.
- Digital Batching Integration:IoT-enabled moisture sensors and automated slump control are converging with fleet telematics, enabling predictive quality assurance that differentiates certified suppliers.
Industry Challenges
- Technician Migration Gap:Skilled batch-plant operators are rotating from Java toward eastern opportunities faster than training pipelines can replenish, creating operational continuity risks for established plants.
- BIS Certification Timeline Compression:Revised earthquake-resistant design standards are requiring rapid mix-design recertification across seismic zones, straining laboratory capacity and extending project qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Ready-Mix Concrete Market |
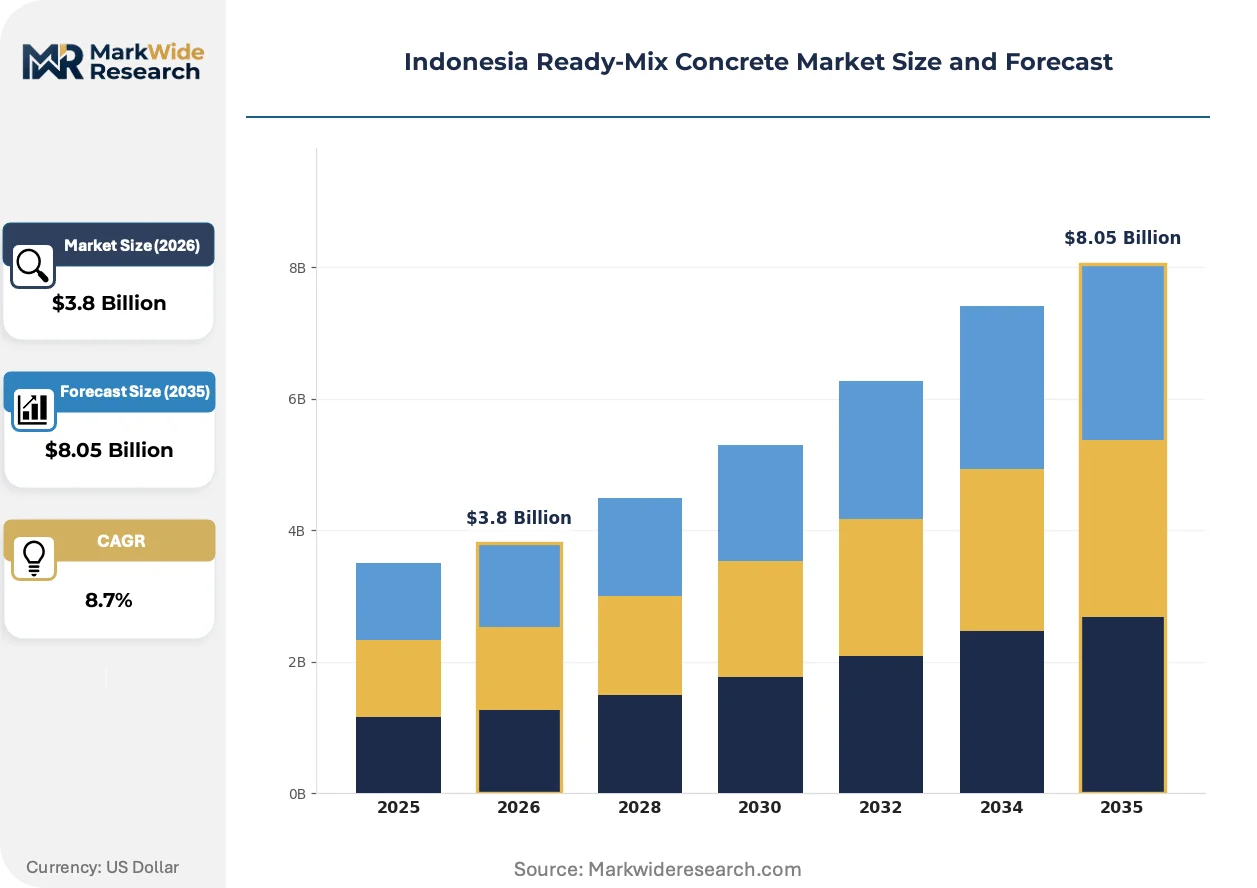
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
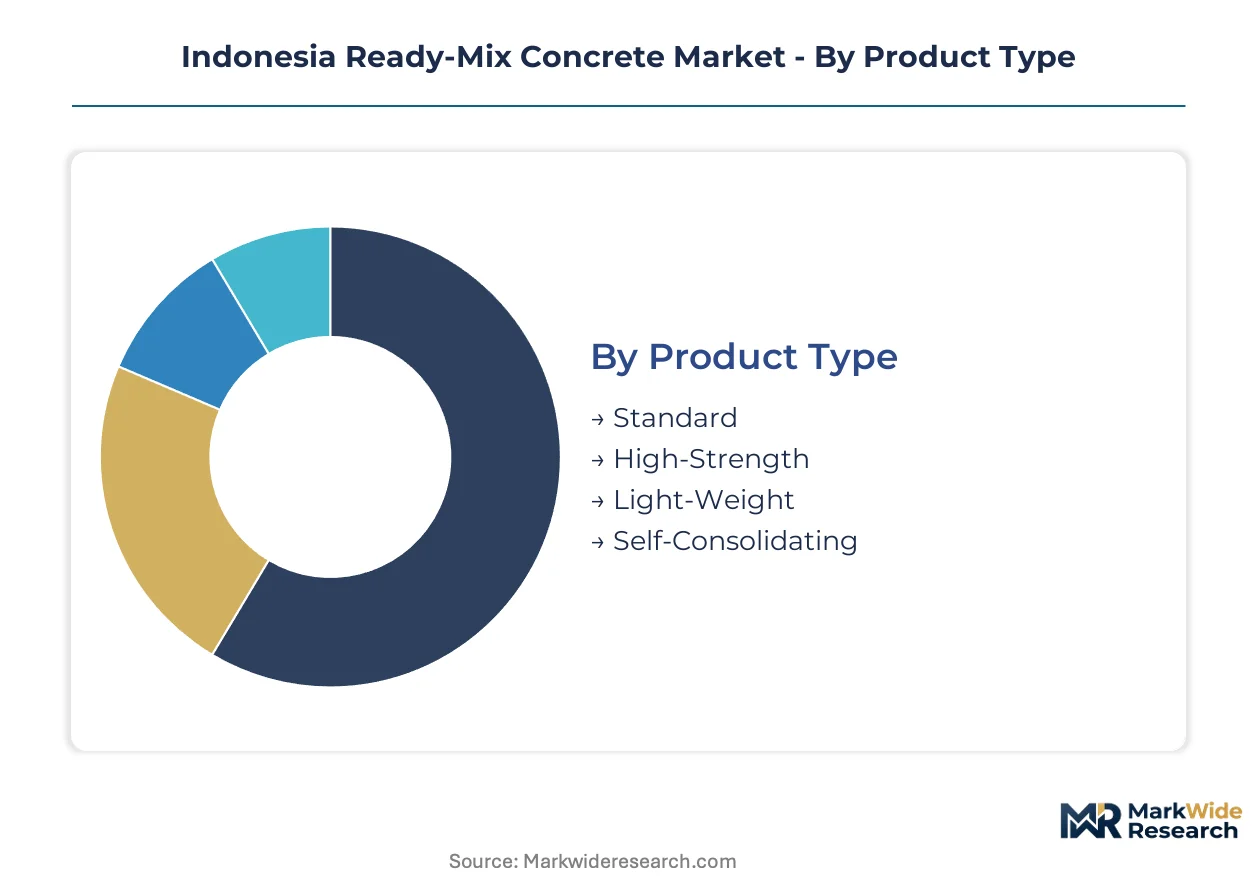
| Segmentation | Product Type: Standard, High-Strength, Light-Weight, Self-Consolidating Application: Residential, Commercial, Industrial, Infrastructure Delivery Mode: Truck-Mixed, Stationary, Centralized, On-Site End User: Construction Companies, DIY Builders, Government Agencies, Contractors |
| Companies Covered | PT Beton Indotama Surya, Kalla Group, Heidelberg Materials, PT Fresh Beton Indonesia, PT Waskita Beton Precast Tbk, PT Cemindo Gemilang Tbk, PT Adhimix Precast Indonesia, Semen Indonesia Group, SCG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Ready-Mix Concrete Market Shifts & Advancements
Digital quality assurance systems and low-carbon admixture formulations are converging to redefine supplier competitiveness, while procurement centralization among megaproject consortia is compressing vendor qualification cycles.
Self-consolidating concrete admixture technology is miniaturizing the labor component in complex pours, eliminating mechanical vibration requirements in dense rebar configurations. Toll road and high-rise contractors are adopting these formulations for accelerated segment casting, compressing project schedules by twenty to thirty percent on critical path activities. The technology is miniaturizing the traditional workforce intensity of concrete placement, shifting value capture toward chemical suppliers and automated batching systems.
BIS revisions to concrete strength classification protocols are mandating enhanced quality documentation and third-party testing verification. The Ministry of Public Works and Housing is enforcing these standards through project eligibility criteria, eliminating informal suppliers from government tender participation. High-strength grade specifications for dam and rail applications are most affected, with contractors consolidating procurement among vertically integrated cement-concrete operators capable of in-house laboratory certification.
Consortium-led procurement is displacing fragmented contractor purchasing across IKN Nusantara and Jakarta-Bandung corridor megaprojects. State-owned developers are centralizing concrete supply contracts with certified batch-plant networks, compressing vendor count and extending contract durations. This concentration is most visible in Java, where procurement scale thresholds now exclude independent batch-plant operators without captive raw material supply or multi-site operational capability.
Indonesia Ready-Mix Concrete Market Segmentation
Indonesia's ready-mix concrete market fragments across product specifications, project scales, and logistical constraints that dictate supplier viability. Each segmentation dimension carries distinct margin profiles and certification requirements that reshape competitive positioning across Java's saturated corridors and eastern frontier markets.
Product Type:
Domestic demand concentrates on grades serving infrastructure megaprojects, while export-oriented specifications remain minimal given clinker import dependency and BIS certification barriers.
- Standard:Composed of Portland cement, natural aggregates, and basic plasticizers for 20-30 MPa compressive strength applications. Demand concentrates in Java's residential subdivisions and secondary city commercial builds where BIS baseline certification suffices, though margin compression from oversupply limits independent operator viability.
- High-Strength:Incorporates silica fume and superplasticizers to achieve 50-80 MPa grades for structural columns and bridge decks. IKN Nusantara toll road specifications and Jakarta-Bandung corridor rail projects are absorbing volumes from integrated cement-concrete operators with captive laboratory certification.
- Light-Weight:Uses expanded clay or pumice aggregates to reduce structural dead loads in high-rise construction. Demand clusters in Surabaya and Makassar commercial towers where seismic design requirements favor mass reduction.
- Self-Consolidating:High-range water reducers enable flowability without mechanical vibration. Dense rebar configurations in smelter foundations and accelerated pour schedules justify admixture cost premiums in Sulawesi industrial zones.
Standard grades command the established base. The steepest expansion runs through Self-Consolidating formulations.
Application:
Volume distribution correlates with government procurement concentration, where state-backed infrastructure absorbs premium grades and private development cycles drive standard specification demand.
- Infrastructure:Dams, toll roads, and rail projects specify sulfate-resistant and high-strength grades for structural longevity. IKN Nusantara and Trans-Java toll network extensions are consolidating procurement among BIS-certified batch-plant networks with multi-site capability.
- Industrial:Smelter foundations, petrochemical containment structures, and port facilities require specialized mix designs. Battery-grade nickel processing facilities in Halmahera and North Maluku are specifying chloride-resistant grades for coastal exposure conditions.
- Commercial:High-rise cores and retail podiums drive mid-strength demand in Jakarta, Surabaya, and Medan central business districts. Greenship rating mandates are pushing admixture selection toward lower-carbon formulations.
- Residential:Low-rise housing and subdivision infrastructure consumes standard grades through fragmented contractor purchasing. Java's corridor saturation has compressed utilization rates below viable thresholds for non-integrated suppliers.
Infrastructure commands the established base. The steepest expansion runs through Industrial applications.
Delivery Mode:
Logistical configuration determines effective supply radius and quality control capability, with archipelagic geography fragmenting viable operational models.
- Truck-Mixed:Dry cement and aggregates batch in transit with water added at project site, extending viable radius to forty kilometers. Flexibility across Indonesia's fragmented project geography makes this the dominant operational deployment for remote sites.
- Centralized:Fixed batch plants with automated quality control serve dense urban construction clusters. Jakarta-Bandung corridor megaprojects and Surabaya industrial estates concentrate procurement among certified centralized operators.
- Stationary:Project-dedicated plants for sustained high-volume pours eliminate transit variability. IKN Nusantara and Kalimantan smelter zones are attracting captive plant investments from integrated cement-concrete networks.
- On-Site:Mobile batching units for isolated projects beyond viable truck-mixed radius. Technical limitation on workability window restricts deployment to exceptional circumstances with accelerated pour schedules.
Truck-Mixed commands the established base. The steepest expansion runs through Stationary configurations.
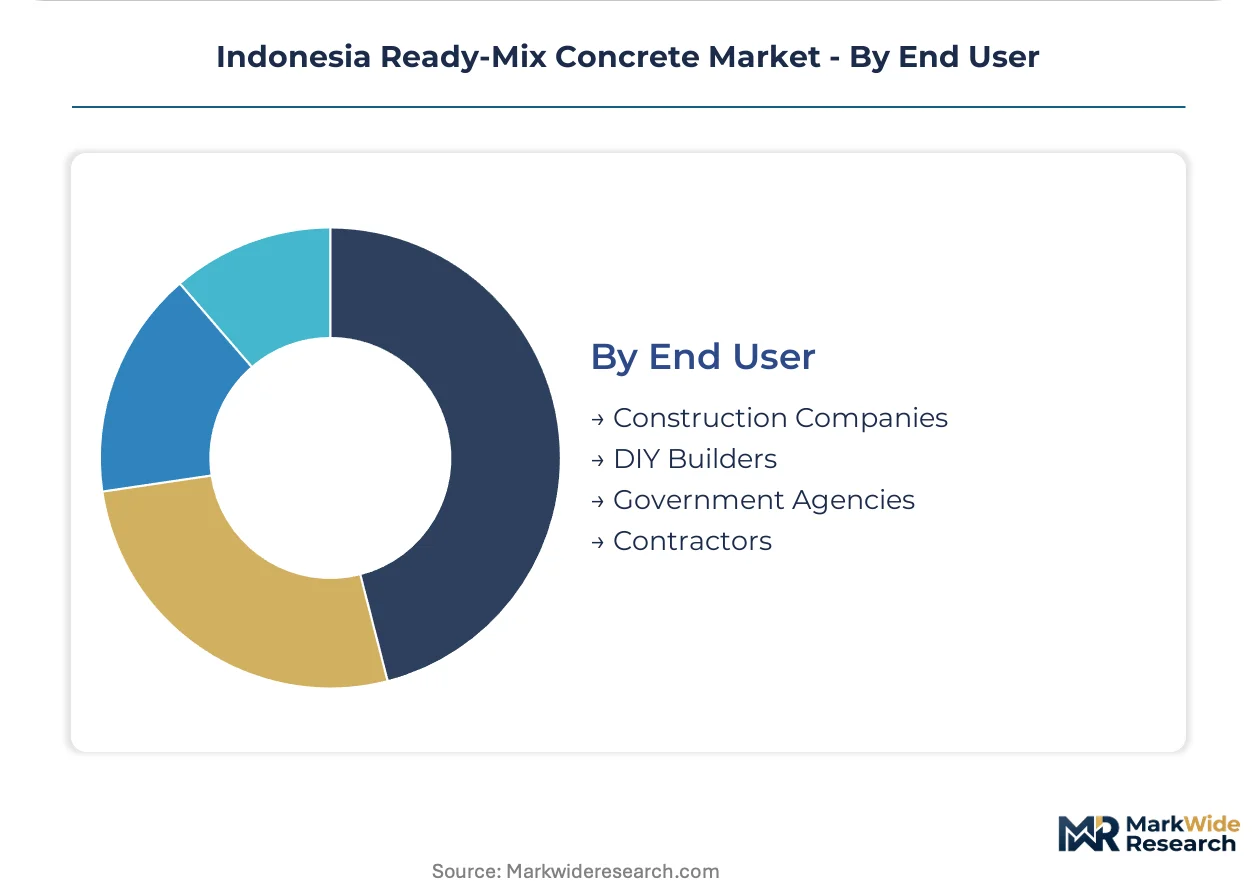
End User:
Procurement sophistication varies sharply by buyer type, with state-owned developers centralizing supply contracts and fragmenting vendor access for smaller contractors.
- Government Agencies:Ministry of Public Works and Housing projects enforce BIS certification and Greenship compliance through tender eligibility criteria. Procurement centralization across IKN Nusantara and national rail programs excludes informal suppliers.
- Construction Companies:Tier-one contractors with multi-project portfolios negotiate volume contracts with certified batch-plant networks. Waskita and state-linked developers anchor demand through precast and ready-mix dual capabilities.
- Contractors:Fragmented mid-tier builders purchase spot volumes through distributor channels, facing qualification barriers to megaproject participation without captive cement supply.
- DIY Builders:Small-scale residential and renovation projects source bagged cement for on-site mixing. This segment remains outside ready-mix distribution economics due to minimum volume thresholds and delivery cost structures.
Government Agencies command the established base. The steepest expansion runs through Construction Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
BIS certification requirements and megaproject procurement concentration are redrawing regional demand patterns across Indonesia's archipelago. Java retains volume dominance while eastern frontier markets absorb skilled labor migration and new capacity investment.
Java
The Jakarta-Bandung corridor anchors national demand through IKN Nusantara relocation and Trans-Java toll extensions. BIS enforcement eliminates informal batch-plant operators from government tender eligibility. Surabaya industrial estates concentrate high-strength grade procurement among certified networks with captive laboratory capability.
Sumatra
Medan and Palembang corridors drive infrastructure renewal through Ministry of Public Works highway programs. Heidelberg Materials leverages integrated cement-to-concrete logistics across the island's northern and southern development axes. Batam-Bintan industrial zones specify sulfate-resistant grades for port and smelter foundations facing coastal exposure.
Sulawesi
Battery-grade nickel processing facilities in Morowali and Konawe specify chloride-resistant and self-consolidating concrete grades. Technician migration from Java outpaces local training pipeline replenishment, creating operational continuity gaps. Kendari and Makassar anchor batch-plant network expansion for mining-industrial hybrid demand.
Kalimantan
Greenfield smelter and petrochemical zones in North Kalimantan attract captive stationary plant investments from integrated cement-concrete operators. The ninety-minute workability window restricts viable supply radius, fragmenting effective market addressability across the island's dispersed project geography. Balikpapan-Samarinda corridor concentrates government-backed infrastructure procurement.
Bali and Nusa Tenggara
Tourism infrastructure and geothermal energy projects drive intermittent high-specification demand. Remote project sites rely on truck-mixed delivery flexibility given batch-plant density limitations. Mataram and Kupang face supply constraints from Java-centric logistics networks and clinker import dependency.
Indonesia Ready-Mix Concrete Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure compressing around BIS certification barriers and megaproject procurement scale thresholds. Vertically integrated cement-concrete operators with captive laboratory capability capture government tender concentration, while independent batch-plant operators face utilization rate compression below viable thresholds. Strategic archetypes include integrated materials networks, precast-ready-mix dual-capability contractors, and regional specialist batch-plant operators. Competitive dynamics center on backward integration into clinker supply and multi-site operational certification to qualify for consortium-led procurement.
Among Indonesia-based operators, PT Waskita Beton Precast Tbk and PT Cemindo Gemilang Tbk represent the precast-ready-mix dual-capability archetype, occupying positions that anchor government-backed infrastructure tenders. Heidelberg Materials exemplifies the integrated materials network model, with geographic naming indicating German-origin multinational structure extending cement-to-concrete logistics across Sumatra and Java. Semen Indonesia Group anchors the state-linked integrated tier, with naming convention indicating national-scale clinker logistics advantage translating into downstream ready-mix distribution capability in secondary cities.
| Leading Market Players |
|---|
| PT Beton Indotama Surya |
| Kalla Group |
| Heidelberg Materials |
| PT Fresh Beton Indonesia |
| PT Waskita Beton Precast Tbk |
| PT Cemindo Gemilang Tbk |
| PT Adhimix Precast Indonesia |
| Semen Indonesia Group |
| SCG |
| Others |
Supply & Pricing Matrix
BIS certification protocols gate both supplier qualification and price differentiation simultaneously, compressing informal operators from government tenders while enabling certified networks to command structural premiums across Java's saturated corridors and eastern frontier markets.
Pricing Analysis
Java's Jakarta-Bandung corridor shows the widest price spread, with certified high-strength grades carrying admixture cost premiums against standard formulations in residential subdivisions. Three-tier pricing structure across premium self-consolidating, standard infrastructure-grade, and economy residential tiers separates suppliers by certification depth and laboratory capability. Cost compression in standard grades is intensifying because clinker import dependency exposes margins to shipping rate volatility. Residential contractors exhibit highest price sensitivity, while IKN Nusantara megaproject consortia prioritize certification compliance over unit cost.
Supply Chain Analysis
Vietnamese and Chinese clinker shipments through Singapore Strait transit underwrite domestic cement capacity, creating single-source vulnerability for integrated concrete operators. Indonesia's batch-plant network draws from imported clinker, domestic limestone aggregates, and specialty chemical admixtures from South Korea and Japan. Tariff exposure on Vietnamese clinker imports threatens margin stability for non-integrated suppliers. Distribution runs through vertically integrated cement-concrete networks with captive fleet operations, supplemented by independent truck-mixed operators serving remote project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's ready-mix concrete market is entering a cyclical recovery phase as IKN Nusantara construction absorbs record volumes and smelter investment accelerates across Sulawesi and Kalimantan.
For Market Incumbents: Secure backward integration into clinker supply to insulate margins from import volatility and shipping rate swings. Anchor multi-site BIS certification across Java, Sulawesi, and Kalimantan to qualify for consortium-led megaproject procurement that excludes single-plant operators. For New Entrants and Emerging Players: Differentiate on digital batching integration with IoT-enabled quality assurance to bypass certification timeline barriers that strain established laboratory capacity. Target Kalimantan greenfield industrial estates where captive stationary plant investments face limited incumbent saturation and first-mover positioning remains open. For Investors and Strategic Acquirers: Carve-out targets emerge from state-linked construction conglomerates seeking to monetize non-core ready-mix assets amid balance sheet restructuring. Long-term viability hinges on consolidation plays that aggregate fragmented batch-plant networks into certified multi-site platforms. Watch BIS recertification backlogs as signal for operational disruption creating acquisition windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Supply | Captive raw material sourcing insulates Heidelberg Materials and Semen Indonesia Group from Vietnamese import tariff exposure. |
| Multi-Site BIS Certification Investment | Laboratory capability expansion qualifies operators for IKN Nusantara and Trans-Java toll network procurement concentration. |
| Digital Batching Platform Deployment | IoT-enabled moisture sensors and automated slump control differentiate certified suppliers through predictive quality assurance. |
| Kalimantan Captive Plant Establishment | Greenfield smelter zones in North Kalimantan attract first-mover stationary plant investments from integrated networks. |
| Self-Consolidating Concrete Formulation Scale-Up | High-range water reducer production for Sulawesi nickel processing facilities captures premium admixture positioning. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Ministry of Public Works procurement databases, BIS certification registries, and clinker import customs records. Interviews with batch-plant operations managers, cement procurement leads at integrated networks, admixture supplier technical directors, and Ministry of Public Works project engineers informed demand modeling. Secondary validation drew from construction industry association reports, state-owned enterprise disclosures, and regional infrastructure development tracking. Bottom-up project pipeline analysis triangulated against top-down cement consumption forecasts.
Segmentation dimensions modeled span product type, application, delivery mode, and end user across the projection horizon. Concrete strength grade specifications, Greenship compliance tiers, and regional logistics constraints shaped volume allocation. CAGRs derived from project-level procurement timelines and capacity utilization trajectories. Forecast inputs incorporated smelter construction acceleration curves and BIS enforcement phase-in assumptions.
Forecasts assume regulatory continuity in BIS certification protocols and Ministry of Public Works tender eligibility criteria; material policy shifts would require re-modeling. Clinker import tariff adjustments, earthquake-resistant design standard revisions, and IKN Nusantara funding allocation changes represent specific revision triggers. Practitioners should keep alternative scenarios live as Greenship mandate enforcement intensity and nickel processing investment cycles evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
North America Insulated Concrete Form (ICF) Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Glazed Tiles Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Canada Asphalt Shingles Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Commercial Glazing Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Ball Iron Rods Market