
 Plumbing Fixtures and Fittings Manufacturing Market | 2026-2036
Plumbing Fixtures and Fittings Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Plumbing Fixtures and Fittings Manufacturing Market Analytics
Vietnam is narrowing its cost gap with Chinese production for brass and ceramic fixture assembly. LIXIL Group leverages regional supply chain partnerships to sustain volume leadership across Asia-Pacific. Masco Corporation anchors North American distribution through wholesale channel control. Kohler Co competes on design-intensive premium positioning in residential renovations.
Plumbing fixtures and fittings encompass water delivery and drainage devices manufactured from brass alloys, stainless steel, engineered polymers, or vitreous ceramic, typically rated for pressure tolerance between 150 and 600 psi depending on application. These products regulate water flow, temperature mixing, and waste removal across built environments. Brass fixtures retain the largest share of value owing to machinability and regulatory acceptance, while plastic fittings gain ground in cost-sensitive residential segments where corrosion resistance outweighs thermal durability. The commercial end-user channel commands higher per-unit margins due to specification-driven procurement and extended warranty requirements.
EPA WaterSense certification, NSF/ANSI 61 lead content standards, and EU Drinking Water Directive thresholds constrain material selection and surface treatment processes across export-oriented manufacturers. California's Proposition 65 enforcement has tightened disclosure obligations for brass alloy compositions in faucet assemblies. Stakeholders must monitor evolving state-level plumbing codes and building efficiency mandates to anticipate specification shifts before they disrupt existing product lines.
Market Dynamics
EPA WaterSense specifications and lead-free brass mandates are compressing allowable material compositions while Southeast Asian manufacturing relocation accelerates cost-based supplier selection. Fixture producers must simultaneously reformulate alloys and relocate assembly capacity to maintain margin structures.
Growth Catalysts
- WaterSense Certification Thresholds:EPA specifications for flow-rate efficiency are mandating redesign of faucet aerators and showerheads across US residential new construction. Builders face code compliance deadlines that accelerate fixture replacement cycles.
- Vietnam Production Relocation:Brass machining and ceramic firing operations are migrating from coastal China to northern Vietnamese industrial zones. Labor cost differentials and tariff positioning are pulling assembly capacity southward.
- Lead-Free Alloy Mandates:California Proposition 65 enforcement and NSF/ANSI 61 standards are eliminating traditional brass compositions. Smelters are accelerating bismuth and silicon bronze formulations to satisfy disclosure obligations.
Market Restraints
- Copper-Zinc Price Volatility:Brass alloy feedstock costs swing with London Metal Exchange copper pricing and zinc concentrate availability. Foundries lack pass-through mechanisms in fixed-price municipal contracts.
- Single-Source Ceramic Sanitaryware:Vitreous china firing requires specialized tunnel kilns concentrated in Guangdong and Vinh Phuc provinces. Earthquake or energy disruption risks concentrate supply vulnerability.
- Thermal Expansion Mismatch:Polymer PEX fittings face temperature cycling failures in hydronic heating applications. Code officials in cold-climate jurisdictions restrict plastic-to-metal transitions.
Strategic Opportunities
- India Affordable Housing Stock:Jal Jeevan Mission rural water connections and PMAY-Urban toilet construction are creating volume demand for cost-optimized plastic fixtures. Domestic molding capacity is scaling to displace imports.
- Smart Sensor Convergence:Touchless activation systems are integrating infrared proximity detection with ceramic disc valve cartridges. Hospitality and healthcare facilities are specifying sensor-embedded lavatory sets.
- EU Drinking Water Directive Revision:Updated metallic release thresholds are accelerating nickel-free stainless steel adoption. Polish and Turkish producers are certifying 304L and 316L grades for potable contact.
Industry Challenges
- CAD-CAM Programming Shortage:Five-axis CNC machining centers for complex faucet bodies require skilled operators conversant in Mastercam and Esprit platforms. Vietnamese technical institutes are trailing equipment installation.
- NSF/ANSI 61 Certification Timelines:Lead leachate testing protocols extend product approval cycles to 18-24 months. Reformulated alloys trigger retesting requirements that stall inventory positioning.
- Legacy Casting Integration:Sand-cast brass foundries in Moradabad and Birmingham lack furnace telemetry for real-time composition monitoring. Quality variance creates downstream machining waste.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plumbing Fixtures and Fittings Manufacturing Market |
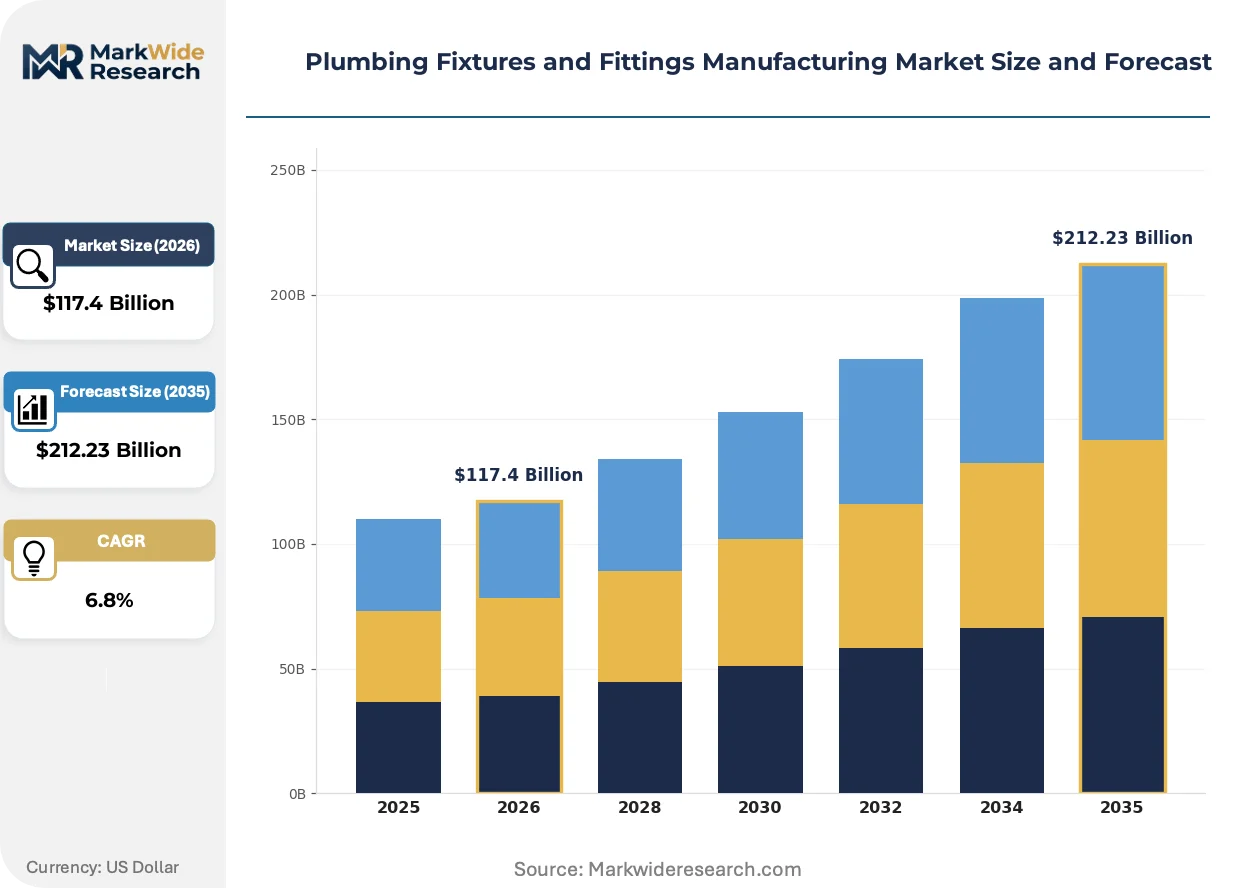
| Market Size in 2026 | $117.4 Billion |
| Market Size in 2035 | $212.23 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faucets, Showerheads, Toilets, Sinks Material: Brass, Stainless Steel, Plastic, Ceramic End User: Residential, Commercial, Industrial, Institutional Distribution Channel: Online Retail, Wholesale, Direct Sales, Showrooms |
| Companies Covered | LIXIL Group, Roca Sanitario, Masco Corporation, American Standard, Moen, Kohler Co, Geberit, Elkay Manufacturing Company, TOTO Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plumbing Fixtures and Fittings Manufacturing Market Evolving Landscape
Digital manufacturing tools and sensor-embedded hardware are collapsing traditional production timelines while regulatory chemistry constraints force material science breakthroughs. Specification-driven procurement is compressing supplier qualification windows.
3D-printed sand casting patterns are collapsing prototype-to-production lead times for complex valve body geometries. Italian and German fixture designers are adopting binder jetting to validate ergonomic forms before hard tooling commitment. This technology is collapsing the traditional six-month mold fabrication cycle into three-week iterations.
REACH Annex XVII nickel release restrictions are tightening surface plating specifications for bathroom accessories. German KBA-equivalent consumer safety regulators are extending scrutiny to decorative PVD coatings. Scandinavian markets are responding with accelerated brushed stainless steel finishes that eliminate electroplated layers entirely.
Specification bundling is consolidating procurement authority among multi-site facility managers. Hospital systems and hotel chains are centralizing lavatory standard selection through preferred manufacturer agreements. This concentration is most visible across US acute care networks consolidating under regional health system umbrellas.
Plumbing Fixtures and Fittings Manufacturing Market Segmentation
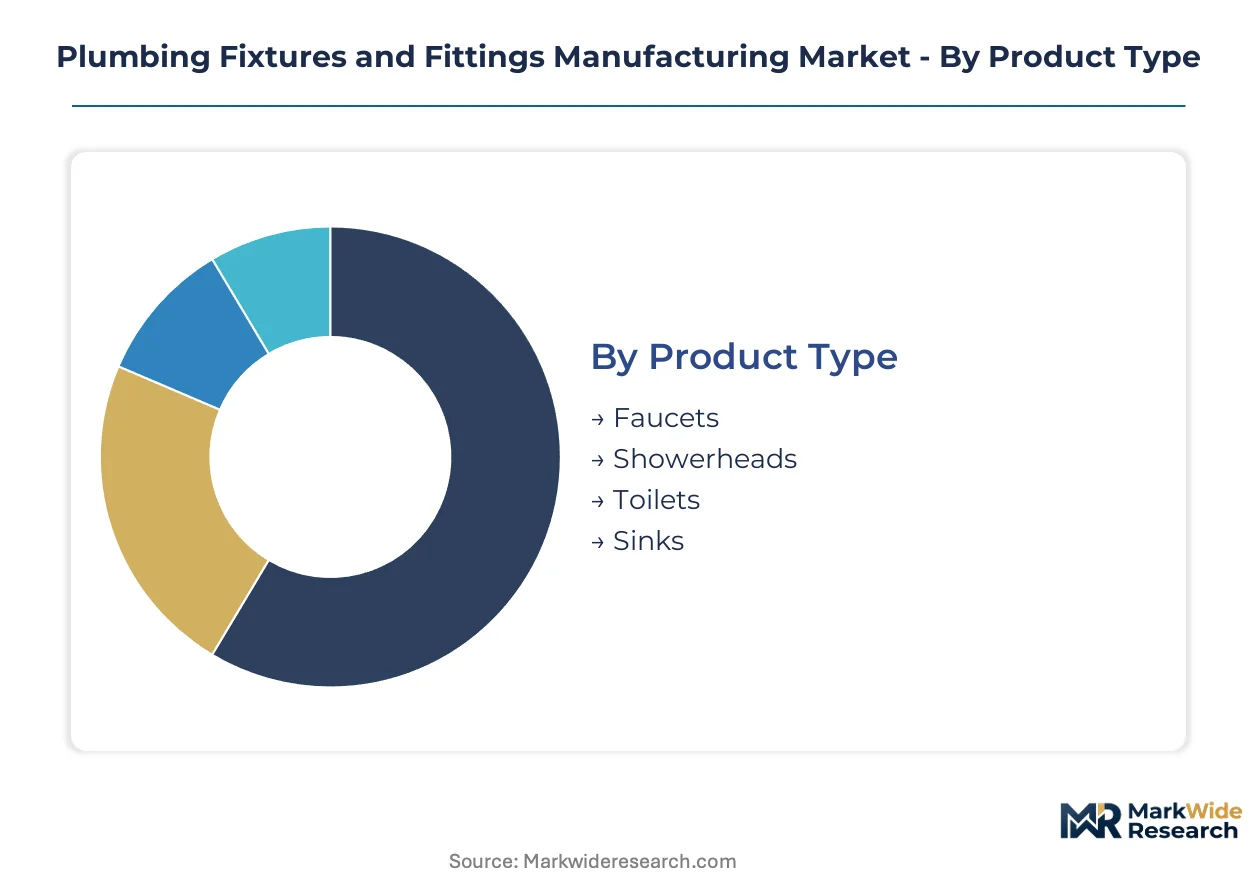
Segmentation in plumbing fixtures reveals how specification requirements, material chemistry constraints, and channel economics fragment procurement patterns. Manufacturers must align alloy formulations and certification investments against distinct margin and volume profiles.
Product Type:
Cost tier differentiation separates specification-heavy commercial installations from price-sensitive residential retrofits, with flow-rate regulations and warranty obligations driving portfolio allocation decisions.
- Faucets:Brass-bodied lavatory and kitchen mixers dominate value capture, with ceramic disc cartridges rated for 500,000-cycle endurance. California Title 20 and EPA WaterSense flow-rate mandates are forcing aerator redesigns across US residential new construction.
- Showerheads:Multi-function spray faces with pressure-compensating flow restrictors face divergent code treatment—2.5 gpm federal maximum versus 1.8 gpm California threshold. Hospitality specification bundles favor thermostatic valve integration.
- Toilets:Vitreous china gravity-flush units retain volume leadership in replacement markets.
- Sinks:Stainless steel undermount and fireclay apron-front formats split residential renovation demand.
Faucets hold installed capacity. Showerheads are rotating up the share rankings.
Material:
Application severity dictates material selection, with potable water contact regulations and thermal cycling requirements filtering options across end-use environments.
- Brass:Copper-zinc alloys (C36000, C37700) remain the machinable standard for valve bodies and faucet castings, though lead-free reformulations with bismuth or silicon substitutes are elevating raw material costs. Foundries in Vietnam and India are scaling capacity to serve export markets facing NSF/ANSI 61 compliance deadlines.
- Stainless Steel:Austenitic 304L and 316L grades are displacing nickel-plated brass in EU markets under REACH Annex XVII nickel release restrictions. Polish and Turkish mills are certifying cold-rolled sheet for pressed sink fabrication and tubular faucet spouts.
- Plastic:Engineering polymers—POM, PPS, reinforced PEX—penetrate cost-optimized residential segments.
- Ceramic:Vitreous china and fireclay retain fixture body dominance for sanitaryware.
Brass holds installed capacity. Stainless steel is rotating up the share rankings.
End User:
Customer type determines specification authority, warranty duration, and the balance between first-cost sensitivity and lifecycle operating expense.
- Residential:Single-family and multifamily new construction absorb high-volume, standard-catalog fixtures with builder-grade pricing. Big-box retail and online channels dominate procurement, with WaterSense certification serving as a purchase filter in drought-prone US states.
- Commercial:Office, retail, and hospitality facilities specify through design-build contracts with extended warranty requirements. Sensor-activated lavatory sets and low-flow urinals feature prominently in LEED-targeted projects.
- Industrial:Manufacturing and processing plants demand heavy-duty brass and stainless steel rated for chemical exposure and high-cycle operation.
- Institutional:Healthcare and education facilities centralize procurement through group purchasing organizations.
Residential holds installed capacity. Commercial is rotating up the share rankings.
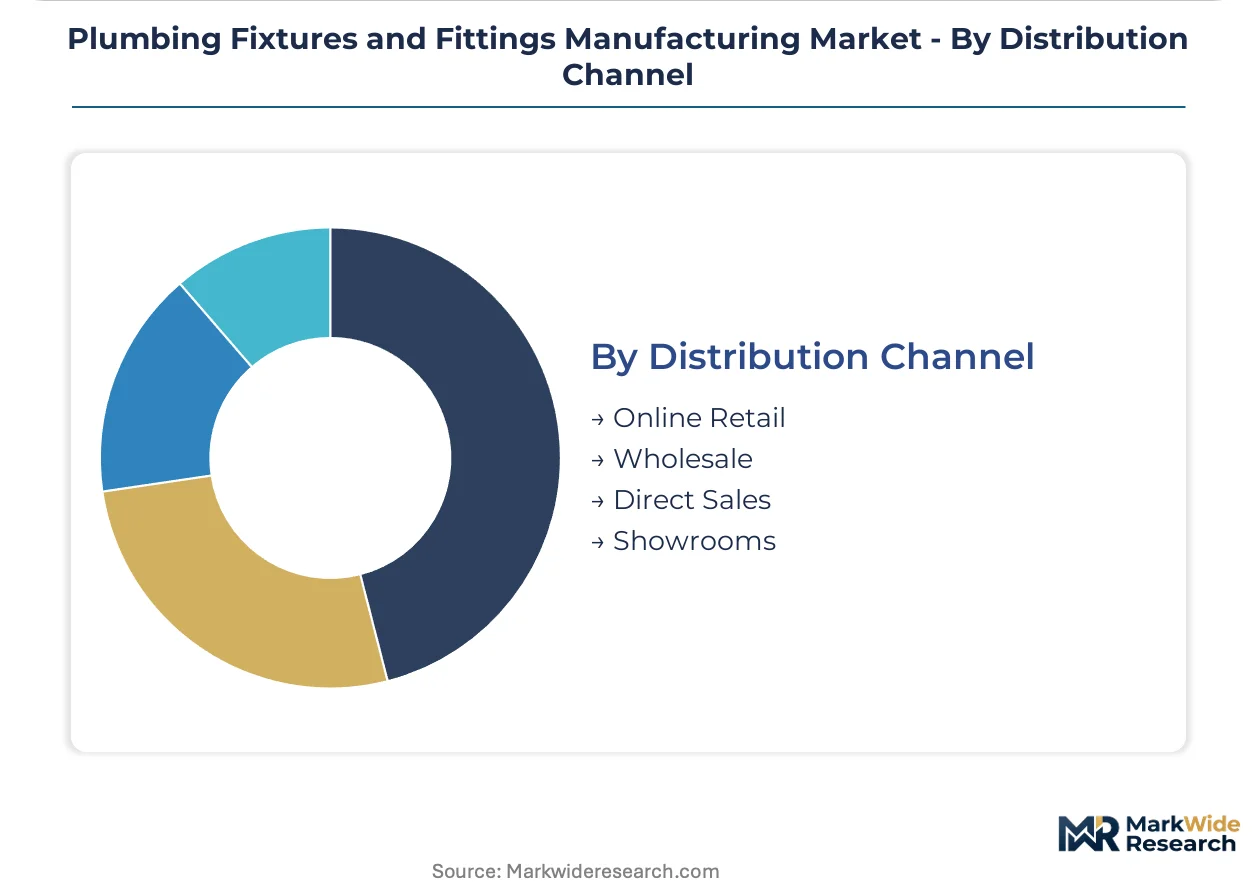
Distribution Channel:
Volume concentration shapes channel economics, with project scale and specification complexity determining route-to-market efficiency.
- Wholesale:Plumbing supply houses and distributor networks control commercial and residential pro-channel flow, maintaining inventory depth for same-day contractor pickup. LIXIL and Masco anchor relationships through exclusive territory agreements and private-label programs.
- Online Retail:Amazon, Wayfair, and direct-to-consumer sites are capturing residential replacement demand, though bulky ceramic sanitaryware faces freight damage and returns complexity.
- Direct Sales:Large project accounts and national facility managers negotiate factory-direct pricing.
- Showrooms:Design centers and manufacturer galleries serve renovation contractors and affluent homeowners.
Wholesale holds installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA WaterSense specifications and lead-free brass mandates in North America are redefining material compliance thresholds for plumbing fixtures and fittings manufacturers worldwide.
United States
Residential construction in drought-prone states absorbs higher volumes of water-efficient fixtures. California Proposition 65 enforcement tightens disclosure obligations for brass alloy compositions in faucet assemblies. Masco Corporation anchors North American distribution through wholesale channel control.
Vietnam
Manufacturing relocation from China is concentrating brass machining and ceramic firing operations in northern Vietnamese industrial zones. Labor cost differentials and tariff positioning pull assembly capacity southward. Foundries in Vinh Phuc province scale capacity to serve export markets facing compliance deadlines.
Germany
REACH Annex XVII nickel release restrictions tighten surface plating specifications for bathroom accessories. German regulators extend scrutiny to decorative PVD coatings. Polish and Turkish producers certify 304L and 316L stainless steel grades for potable contact.
India
Jal Jeevan Mission rural water connections and PMAY-Urban toilet construction create volume demand for cost-optimized plastic fixtures. Domestic molding capacity scales to displace imports. Moradabad sand-cast brass foundries lack furnace telemetry for real-time composition monitoring.
Japan
Design-intensive premium positioning drives residential renovation demand for sensor-embedded lavatory sets. METI standards influence regional efficiency specifications. TOTO Ltd. leverages regional supply chain partnerships to sustain volume leadership across Asia-Pacific.
Plumbing Fixtures and Fittings Manufacturing Market Competitive Landscape
Integrated bathroom solution providers and component specialists split the market into distinct competitive spheres. The vendor base clusters around three strategic archetypes: full-suite sanitaryware conglomerates, faucet-centric hardware specialists, and regional private-label fabricators. Dominant competitive moves include exclusive territory agreements with plumbing supply houses and accelerated bismuth bronze formulation investments to satisfy disclosure obligations.
Within the full-suite sanitaryware tier, LIXIL Group and Kohler Co exemplify integrated positioning across fixture categories. Masco Corporation occupies a position among North American wholesale-anchored operators. These three entities represent divergent geographic emphases—Japanese, American, and similarly American—while collectively illustrating how channel control and alloy reformulation capabilities separate scale leaders from regional competitors.
| Leading Market Players |
|---|
| LIXIL Group |
| Roca Sanitario |
| Masco Corporation |
| American Standard |
| Moen |
| Kohler Co |
| Geberit |
| Elkay Manufacturing Company |
| TOTO Ltd. |
| Others |
Value Network & Pricing Analysis
The Shanghai-to-Long Beach container corridor's freight volatility compresses margin buffers for brass fixture importers while simultaneously amplifying price spreads between Vietnam-assembled and China-origin product lines. This logistics cost dynamic concentrates procurement authority among distributors with multi-origin sourcing flexibility, forcing tiered pricing stratification across premium certified, standard catalog, and economy private-label tiers.
Pricing Analysis
Geographic price spreads between Vietnamese and Chinese export quotations have widened as EPA WaterSense certification premiums attach to compliant brass formulations. Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 61-certified lead-free alloys from transitional bismuth bronze compositions and uncertified legacy brass. Pricing pressure stems from copper-zinc feedstock volatility that foundries cannot fully pass through to municipal contractors locked in fixed-price agreements. Residential big-box buyers exhibit highest price sensitivity, while commercial specification-driven procurement absorbs premium positioning for extended warranty coverage.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions, accelerating relocation to Vietnam, India, and Mexico for final assembly and testing operations. Brass alloy feedstock draws from Chilean copper concentrate and Australian zinc smelter output, with ceramic sanitaryware dependent on Guangdong and Vinh Phuc tunnel kiln capacity. Single-source vulnerability concentrates in vitreous china firing infrastructure exposed to seismic and energy disruption risks. Distribution runs through plumbing supply houses and wholesale distributor networks controlling same-day contractor fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart sensor convergence with ceramic disc valve cartridges signals a platform-economics inflection, as interoperability between touchless activation systems and building management software redefines competitive moats beyond physical manufacturing scale.
For Market Incumbents: Insulate specification authority by deepening NSF/ANSI 61 certification pipelines ahead of state-level plumbing code deadlines, while anchoring wholesale channel relationships through exclusive territory agreements that block private-label substitution. Sensor-embedded lavatory sets represent the priority defensive perimeter against Silicon Valley hardware entrants.
For New Entrants and Emerging Players: India's Jal Jeevan Mission rural water connections offer the most penetrable volume opportunity, as cost-optimized plastic fixture demand outpaces domestic molding capacity expansion. PMAY-Urban toilet construction programs create white-space entry points for injection-molding specialists with BIS certification capabilities. Direct procurement partnerships with state water boards bypass entrenched distributor networks.
For Investors and Strategic Acquirers: Brass foundries with real-time furnace telemetry and automated composition monitoring represent the acquisition target archetype most exposed to quality-premium repricing. Long-term viability hinges on regulatory compliance infrastructure rather than labor cost arbitrage alone. Watch for EPA enforcement acceleration against Proposition 65 disclosure violations as the inflection signal for alloy reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brass Smelting | Vietnamese foundries with captive bismuth bronze supply secure NSF/ANSI 61 compliance timelines. |
| Sensor-Embedded Product Line Launch | TOTO and LIXIL leverage infrared proximity detection to capture hospitality specification bundles. |
| WaterSense Certification Fast-Track | California Title 20 compliance opens drought-state residential new construction procurement channels. |
| Wholesale Distributor Partnership | Masco's exclusive territory agreements block competitor access to pro-channel contractor relationships. |
| India Manufacturing Footprint Expansion | Domestic molding capacity near Moradabad reduces import dependency for Jal Jeevan Mission tenders. |
Research Methodology
Cross-validation between trade customs data and EPA WaterSense certification registries anchors the qualitative findings on manufacturing relocation patterns. Primary interviews with brass foundry operations managers, plumbing supply house procurement directors, commercial contractor specification writers, and state plumbing code officials combined with secondary validation against U.S. Census Bureau construction spending data, LME copper pricing archives, and NSF International product listings. Bottom-up facility capacity assessments and top-down construction flow analysis triangulate volume estimates.
Calibration against historical WaterSense adoption curves and lead-free alloy transition timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material chemistry grade, end-user channel, and regional regulatory cluster. CAGRs derived from fitted diffusion curves for efficiency mandates and manufacturing relocation elasticities. Industry-specific forecast inputs incorporate tunnel kiln capacity utilization in Vinh Phuc province and bismuth bronze smelter commissioning schedules.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts and copper-zinc price volatility would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and supply chain relocation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
North America Roofing Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Concrete Floating Floors System Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Customized Shopfitting Materials Market
Building & Construction Materials
Manufactured Sand Market
Building & Construction Materials
TMT Steel Bar Market
Building & Construction Materials
Autoclave Aerated Concrete Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Bed Headwall Systems Market