
 Poland Construction Market | 2026-2036
Poland Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Construction Market Analytics
Private developers is rotating toward larger-scale residential and commercial portfolios as government procurement stabilizes. Budimex leverages its vertically integrated concrete supply chain to secure margins on transport infrastructure. Strabag anchors its position through specialized tunneling and rail electrification expertise. Skanska competes via its controlled development-to-construction pipeline in Warsaw and Kraków office markets.
Poland construction encompasses the physical assembly of buildings and infrastructure using concrete, steel, wood, and glass, governed by Eurocode-aligned structural standards and thermal performance thresholds for envelope assemblies. Its primary purpose is creating habitable, productive, and connective assets for public and private end users. Residential buildings leads volume as mortgage subsidy programs channel demand into multi-family units, while green technology captures expanding margin pools through energy certification requirements. Prefabrication grows fastest as labor scarcity and quality consistency pressures mount across the Silesian and Tri-City building basins.
Polish Ministry of Development and Funds technical conditions, EU Green Deal performance standards, and BIS-aligned product certification shape material specifications and market access for imported building systems. The national regulator enforces nearly zero-energy building thresholds that redirect specification decisions toward high-performance envelope assemblies. Stakeholders must monitor whether EU cohesion fund disbursement rhythms synchronize with contractor backlog capacity to avoid procurement bottlenecks in priority rail and road corridors.
Market Dynamics
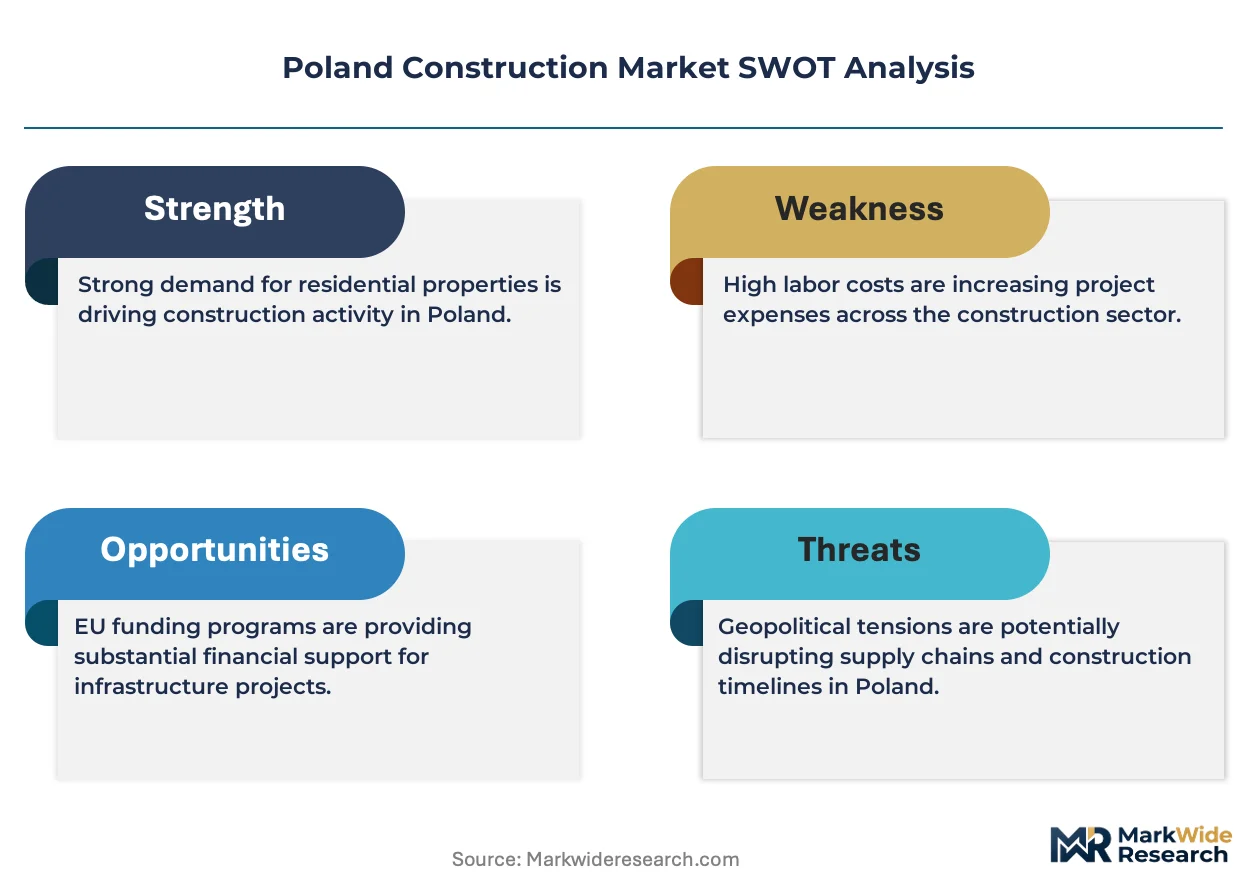
EU cohesion fund disbursement rhythms are synchronizing with contractor backlog capacity across priority rail and road corridors, creating procurement bottlenecks that reshape bidding strategies and prefabrication investment timing.
Growth Catalysts
- EU Green Deal performance standards:Nearly zero-energy building thresholds redirect specification decisions toward high-performance envelope assemblies, expanding margin pools for certified contractors.
- Mortgage subsidy programs:Government-backed financing channels demand into multi-family residential units, sustaining volume leadership in Warsaw and Kraków metropolitan basins.
- Transit-linked mixed-use development:Warsaw metropolitan corridor absorption of premium concrete and prefabrication capacity concentrates demand in transport-adjacent zones.
Market Restraints
- Labor scarcity across Silesian and Tri-City building basins:Skilled trades shortages compress project timelines and elevate wage pressure beyond material cost inflation.
- Imported building system certification friction:BIS-aligned product certification requirements delay market access for non-EU envelope and mechanical system suppliers.
- Energy input cost volatility:Natural gas and electricity price swings destabilize cement and steel production economics, forcing index-linked contract renegotiations.
Strategic Opportunities
- Tri-City underpenetration:Gdańsk-Gdynia-Sopot corridor offers absorption capacity for prefabricated residential modules as logistics infrastructure matures.
- EU Green Deal regulatory tailwind:Energy certification requirements create sustained specification pull for green technology integration across public procurement.
- Rail electrification convergence:Tunneling expertise and overhead catenary system deployment combine in corridor modernization programs.
Industry Challenges
- BIM implementation skill gaps:Digital design-to-fabrication workflows outpace workforce retraining capacity in mid-tier regional contractors.
- Prefabrication quality certification timelines:Factory production control approvals delay module deployment, compressing effective construction windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Construction Market |
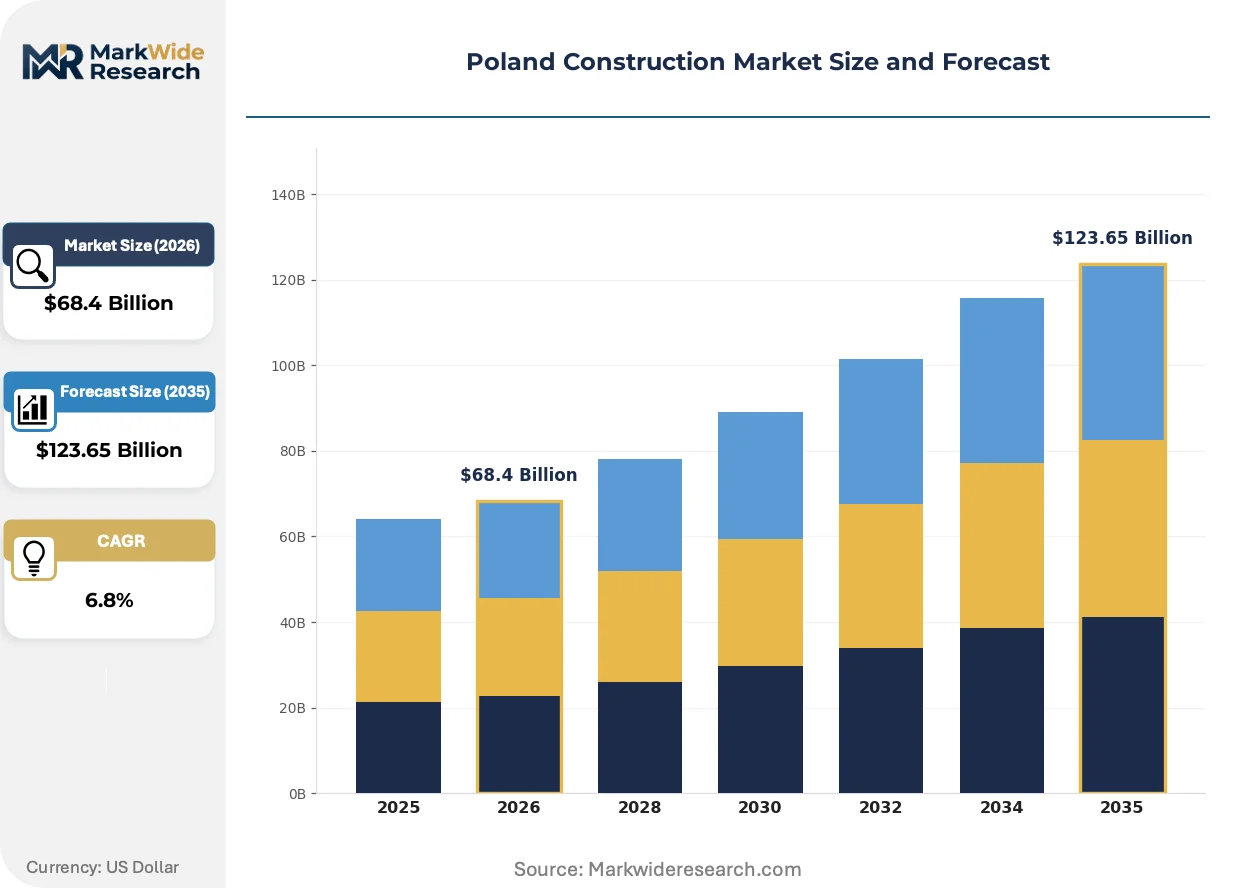
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Buildings, Commercial Structures, Infrastructure Projects, Industrial Facilities Material: Concrete, Steel, Wood, Glass Technology: Building Information Modeling, Prefabrication, Smart Construction, Green Technology End User: Government, Private Developers, Contractors, Real Estate Investors |
| Companies Covered | Mirbud, Polimex-Mostostal, Budimex, Warbud, Skanska, Strabag, Trakcja PRKiI, Torpol, PORR, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Construction Market Evolving Landscape
Construction methodology is pivoting toward controlled-environment manufacturing as labor constraints and quality consistency pressures mount across Polish building basins.
Cross-laminated timber (CLT) is miniaturizing structural element dimensions while maintaining load-bearing performance. Residential developers in Warsaw and Kraków are specifying CLT floor and wall panels for mid-rise multi-family projects. The technology is miniaturizing on-site crew requirements and compressing weather-dependent construction windows.
Polish Ministry of Development and Funds technical conditions now mandate thermal bridge-free envelope detailing for new public buildings. Contractors must recalculate insulation continuity at structural penetrations, adding design-phase coordination overhead. Municipal housing agencies in Lower Silesia and Mazovia are responding by bundling envelope performance guarantees into design-build contracts.
Direct procurement between institutional investors and prefabrication factories is bypassing traditional general contractor intermediation. Warsaw-based real estate investment trusts are contracting directly with Silesian module producers for repetitive residential typologies. This channel compression is most visible in rental housing developments where standardized unit counts justify dedicated production lines.
Poland Construction Market Segmentation
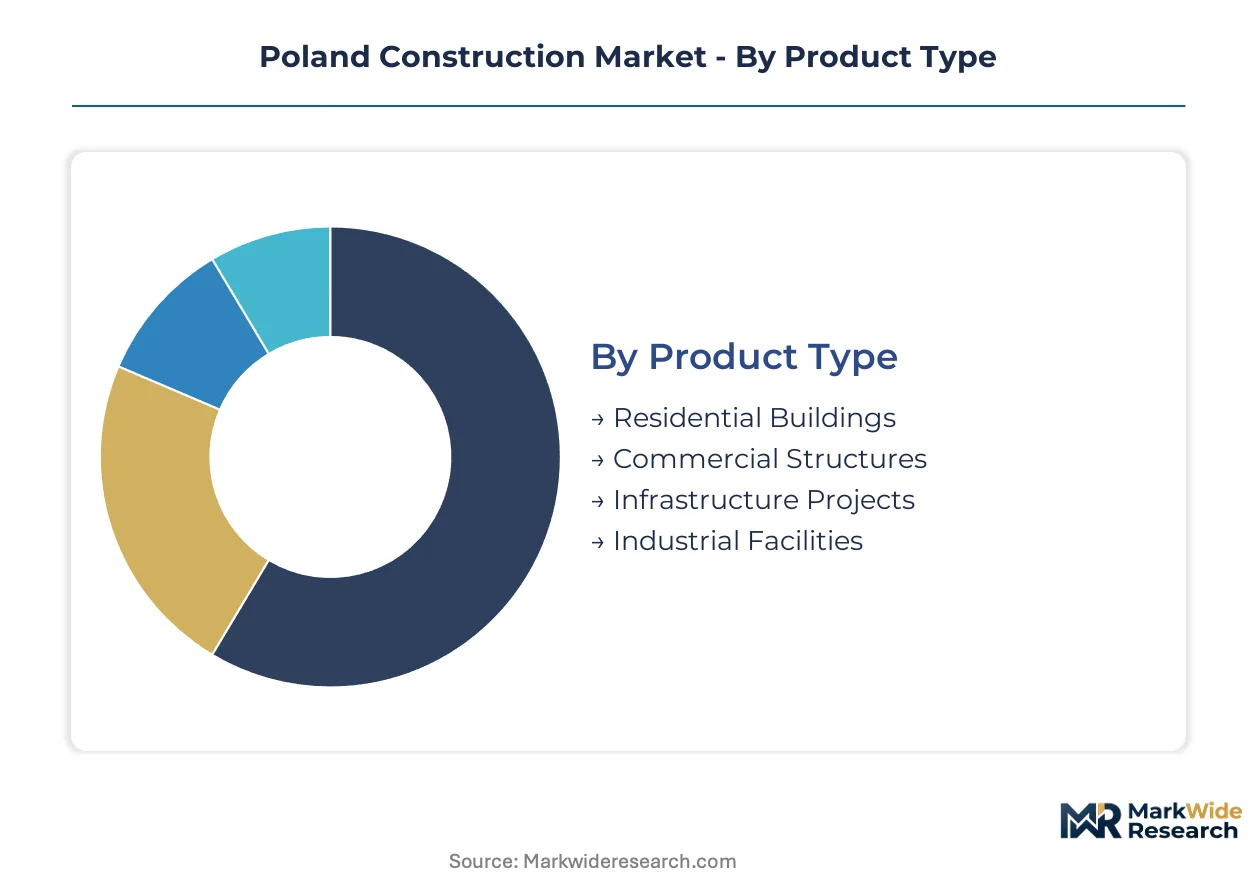
Construction output in Poland fragments across distinct procurement channels, each with diverging specification standards and margin profiles. Understanding how segments map to government, institutional, and private capital flows clarifies where prefabrication capacity and green technology integration concentrate.
Product Type:
Channel mix varies sharply by asset class, with government procurement dominating infrastructure while private developers control residential and commercial pipelines.
- Residential Buildings:Multi-family units absorb the majority of mortgage subsidy program flows, concentrating demand in Warsaw and Kraków metropolitan basins. Energy-efficiency mandates under Polish Ministry of Development and Funds technical conditions redirect specification toward high-performance envelope assemblies. Government-backed financing channels sustain volume leadership despite interest rate volatility.
- Commercial Structures:Office and retail developments in Warsaw's central business district attract institutional capital seeking certified green building stock. Transit-linked mixed-use projects absorb premium concrete and prefabrication capacity, with logistics infrastructure maturity determining feasible floor area ratios.
- Infrastructure Projects:Rail electrification and corridor modernization programs depend on EU cohesion fund disbursement rhythms. Tunneling and overhead catenary deployment combine in priority corridors where contractor backlog capacity constrains procurement timing.
- Industrial Facilities:Manufacturing and warehouse construction concentrates in Silesian and Tri-City logistics basins. Direct procurement between institutional investors and module producers is bypassing traditional general contractor intermediation for repetitive typologies.
Residential Buildings dominates installed base. Infrastructure Projects is where expansion concentrates.
Material:
Cost tier stratification separates premium-specification imports from domestically produced commodity grades, with certification friction shaping market access.
- Concrete:Vertically integrated supply chains anchor transport infrastructure margins, with cement production economics exposed to natural gas and electricity price swings. Index-linked contract renegotiations are destabilizing project budgeting across public procurement.
- Steel:Structural and reinforcement grades face energy input cost volatility that compresses fabrication margins. BIS-aligned product certification requirements delay market access for non-EU suppliers, protecting domestic mill capacity.
- Wood:Cross-laminated timber miniaturizes structural element dimensions while maintaining load-bearing performance for mid-rise multi-family projects in Warsaw and Kraków.
- Glass:High-performance glazing specifications escalate under nearly zero-energy building thresholds, with thermal bridge-free envelope detailing mandated for new public buildings.
Concrete commands the largest volume share. Wood is climbing the fastest as labor scarcity pressures mount.
Technology:
Application maturity separates established design tools from emerging fabrication methods, with workforce retraining gaps determining adoption velocity.
- Building Information Modeling:Digital design-to-fabrication workflows outpace workforce retraining capacity in mid-tier regional contractors. Municipal housing agencies are bundling envelope performance guarantees into design-build contracts to manage coordination overhead.
- Prefabrication:Factory production control approvals delay module deployment, compressing effective construction windows. Controlled-environment manufacturing is pivoting methodology as quality consistency pressures mount across building basins.
- Smart Construction:Sensor integration and automated site monitoring remain nascent outside flagship commercial developments.
- Green Technology:Energy certification requirements create sustained specification pull across public procurement, expanding margin pools for certified contractors.
Building Information Modeling penetrates deepest among design-phase stakeholders. Prefabrication is gaining share fastest as labor constraints intensify.
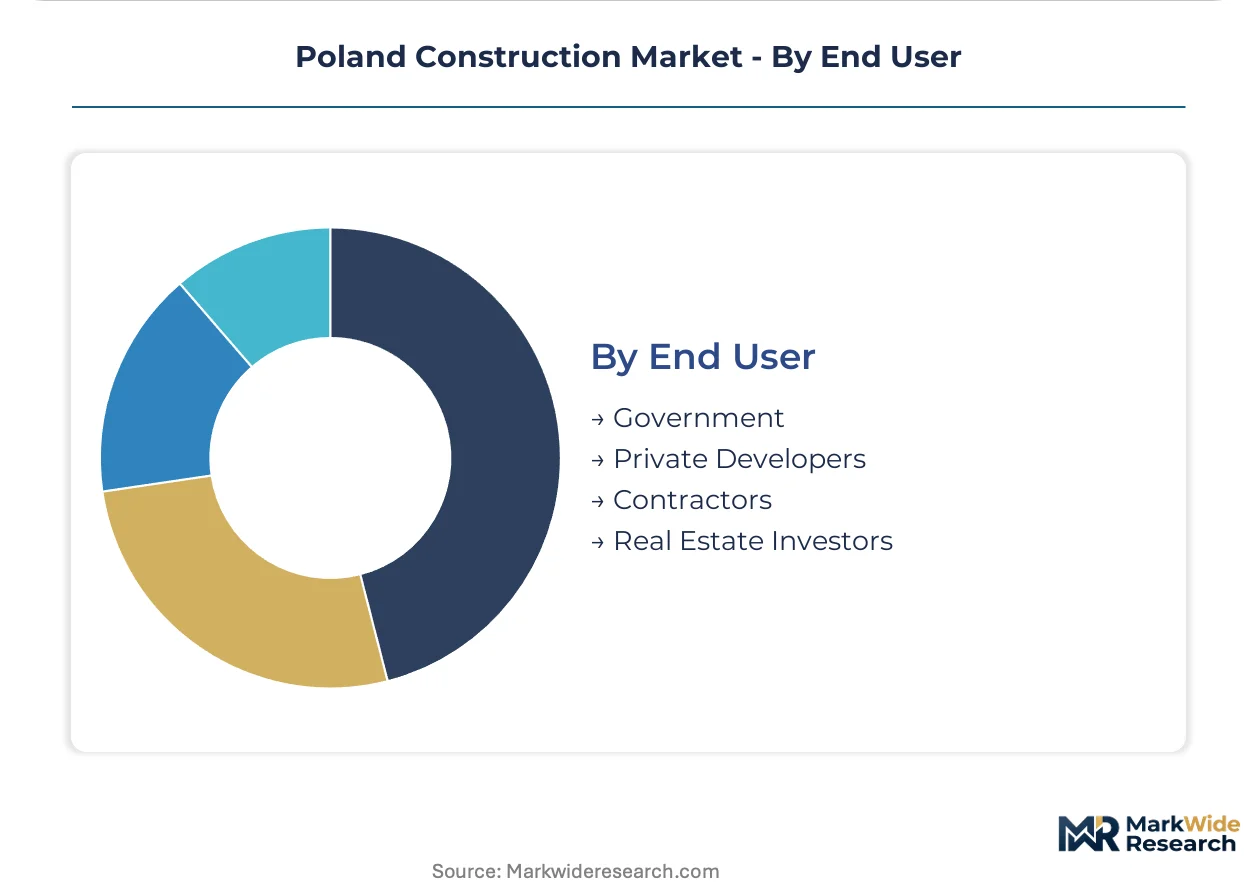
End User:
Customer type determines contract structure, with public procurement stabilizing as private developers rotate toward larger-scale portfolios.
- Government:Polish Ministry of Development and Funds technical conditions and EU Green Deal performance standards shape material specifications. Procurement bottlenecks emerge where cohesion fund disbursement rhythms misalign with contractor backlog capacity.
- Private Developers:Warsaw-based real estate investment trusts are contracting directly with Silesian module producers for standardized rental housing typologies. This channel compression is most visible where repetitive unit counts justify dedicated production lines.
- Contractors:Mid-tier regional players face BIM implementation skill gaps that disadvantage them in design-build competitions.
- Real Estate Investors:Institutional capital seeks yield in certified green commercial stock, with thermal performance thresholds redirecting specification decisions.
Government anchors public infrastructure procurement. Private Developers is where channel compression and direct factory contracting are advancing most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German cement and prefabrication exports flow eastward into Poland's Silesian and Tri-City building basins, while Polish contractors bid southward into Czech and Slovak transport corridors. This cross-border trade pattern concentrates specification influence in EU-aligned regulatory frameworks.
Masovian Voivodeship
Warsaw metropolitan corridor demand absorbs premium concrete and prefabrication capacity through transit-linked mixed-use developments. Polish Ministry of Development and Funds technical conditions enforce nearly zero-energy building thresholds for public buildings. Municipal housing agencies in Warsaw bundle envelope performance guarantees into design-build contracts.
Silesian Voivodeship
Industrial facility construction and logistics warehouse development concentrate contractor deployment in the Katowice-Gliwice corridor. EU Green Deal performance standards redirect specification toward high-performance envelope assemblies for manufacturing assets. Direct procurement between institutional investors and module producers bypasses traditional general contractor intermediation.
Pomeranian Voivodeship
Tri-City logistics infrastructure maturity unlocks absorption capacity for prefabricated residential modules in Gdańsk-Gdynia-Sopot. Labor scarcity across building basins compresses project timelines and elevates wage pressure. Gdańsk port expansion supports imported building system flows despite BIS-aligned certification friction for non-EU suppliers.
Lesser Poland Voivodeship
Kraków office markets attract institutional capital seeking certified green building stock alongside residential multi-family absorption. Mortgage subsidy programs channel demand into urban core units. Rail electrification convergence with tunneling expertise positions the region for corridor modernization subcontracts.
Lower Silesian Voivodeship
Wrocław metropolitan basin construction balances residential volume with industrial facility demand from German supply chain relocations. Energy input cost volatility destabilizes cement and steel production economics. Prefabrication quality certification timelines delay module deployment, compressing effective construction windows.
Poland Construction Market Competitive Landscape
Listed leaders compete with private specialists across procurement channel access and vertical integration depth. The vendor base clusters around three tiers: state-linked infrastructure incumbents with concrete supply chain control, international engineering groups with tunneling and rail electrification expertise, and mid-tier regional players facing BIM implementation skill gaps. Consolidation pressure operates through M&A activity targeting prefabrication capacity and strategic partnerships securing EU cohesion fund pipeline access.
Among Polish-listed contractors, Budimex and Polimex-Mostostal occupy positions anchored in public infrastructure procurement and vertically integrated material supply. International engineering specialists Skanska and Strabag exemplify the design-build and specialized civil works archetype, competing through controlled development pipelines and rail corridor expertise. These four names represent the competitive tension between domestic incumbents and cross-border engineering groups.
| Leading Market Players |
|---|
| Mirbud |
| Polimex-Mostostal |
| Budimex |
| Warbud |
| Skanska |
| Strabag |
| Trakcja PRKiI |
| Torpol |
| PORR |
| Others |
Value Network & Pricing Analysis
Cross-laminated timber substitution for steel and concrete in Warsaw mid-rise developments simultaneously shifts sourcing geography toward Austrian and Czech sawmill clusters and compresses installed-cost premiums against traditional frame construction. This material pivot redirects contractor procurement patterns while reconfiguring margin pools across envelope assembly tiers.
Pricing Analysis
Current-generation prefabrication modules command substantial premiums over stick-built equivalents, while next-generation BIM-integrated factory systems are pricing at pilot-scale economics and prior-generation cast-in-place concrete faces structural cost compression. Three-tier pricing structure across premium certified, standard code-compliant, and economy-grade envelope assemblies separates Warsaw institutional investors from Silesian logistics developers from municipal housing agencies. Cost compression in standard-grade concrete supply is intensifying because cement producers pass through natural gas and electricity volatility via index-linked escalation clauses. Municipal housing agencies exhibit highest price sensitivity due to fixed-budget procurement protocols, while Warsaw-based REITs demonstrate lowest sensitivity given yield-focused holding-period calculations.
Supply Chain Analysis
Gdańsk port throughput capacity functions as the dominant chokepoint for non-EU building system imports, with customs clearance velocity determining effective lead times for mechanical and envelope component deployment. Manufacturing concentration in Germany, Czech Republic, and domestic Silesian basin feeds the Polish construction pipeline with prefabricated modules, cement clinker, and engineered timber products. Raw material flows draw from Ukrainian steel semifinished products, Scandinavian timber feedstock, and domestic limestone deposits for cement production. Single-source vulnerability concentrates in German prefabrication factory capacity for complex modular assemblies. Distribution runs through general contractor intermediation for public infrastructure, while direct factory contracting is compressing channel layers in institutional residential development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Envelope performance guarantee bundling into design-build contracts represents a service-attach opportunity expanding faster than base construction hardware, as municipal housing agencies outsource thermal bridge risk management to contractors with certified quality control systems.
For Market Incumbents: Shield core margin pools in Warsaw transit-linked mixed-use development by securing captive prefabrication capacity through Silesian module producer partnerships or backward integration into factory production control certification. Energy input cost volatility in cement and steel supply chains threatens project budgeting stability; index-linked contract structures and strategic inventory positioning at Gdańsk port buffer this exposure. Reinforce specification influence by embedding BIM-to-fabrication workflows that mid-tier regional competitors cannot replicate. For New Entrants and Emerging Players: Post-construction envelope performance monitoring and thermal bridge remediation services constitute a service-layer gap where incumbents under-serve municipal housing agencies with limited in-house technical capacity. Tri-City corridor prefabricated residential module deployment offers the most penetrable geography as logistics infrastructure matures and labor scarcity intensifies. Pursue direct procurement relationships with Gdańsk-Gdynia-Sopot institutional investors seeking standardized rental housing typologies with performance guarantees. For Investors and Strategic Acquirers: EU Green Deal nearly zero-energy building threshold enforcement reshapes the acquisition landscape by privileging contractors with certified envelope assembly capabilities and factory production control approvals. Long-term viability centers on positioning for sustained regulatory specification pull across public procurement rather than cyclical private development volume. Acquisition targets should demonstrate BIM-integrated prefabrication workflows and established relationships with cohesion fund disbursement channels. Monitor EU cohesion fund rhythm synchronization with contractor backlog capacity as the critical inflection signal for procurement bottleneck severity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabrication Capacity | Captive module supply secures margins on Warsaw transit-linked mixed-use projects against labor scarcity. |
| Envelope Performance Guarantee Bundling | Municipal housing agencies in Mazovia outsource thermal bridge risk to certified design-build contractors. |
| BIM-to-Fabrication Workflow Investment | Digital design coordination compresses quality certification timelines for factory production control approvals. |
| Tri-City Corridor Market Entry | Gdańsk-Gdynia-Sopot logistics maturity unlocks absorption capacity for standardized residential modules. |
| EU Cohesion Fund Pipeline Access Partnership | Rail electrification and corridor modernization programs depend on synchronized disbursement rhythms. |
Research Methodology
Desk research of Polish Ministry of Development and Funds technical condition filings, EU cohesion fund disbursement records, and BIS-aligned product certification databases preceded structured interviews with project directors at tier-one contractors, procurement leads at Warsaw-based real estate investment trusts, envelope engineering specialists, and municipal housing agency technical officers. Secondary validation drew from cement producer energy cost disclosures, prefabrication factory production control audit reports, and cross-border trade flow documentation. Bottom-up project pipeline aggregation and top-down sector output estimates were triangulated to establish market sizing boundaries.
Variance decomposition across product type, material specification tier, technology adoption stage, and end-user procurement channel informed the analytical framework over the projection horizon. Segmentation dimensions modeled encompass residential-commercial-infrastructure-industrial asset classes, concrete-steel-wood-glass material splits, BIM-prefabrication-smart construction-green technology application maturity, and government-private developer-contractor-real estate investor customer archetypes. CAGRs were derived from installed base growth trajectories and replacement cycle analysis, with EU Green Deal regulatory compliance timelines and mortgage subsidy program flows serving as construction-specific forecast inputs.
Forecasts assume regulatory continuity in Polish Ministry of Development and Funds technical conditions and EU Green Deal performance standards; material policy shifts would require re-modeling of specification decision pathways and certified contractor margin pools. Energy input cost volatility, labor scarcity severity, and cohesion fund disbursement rhythm misalignment represent specific risk factors that could revise trajectory assumptions. Practitioners should keep alternative scenarios live as EU fund allocation priorities and building code enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Latin America Construction Market
Building Construction
Africa Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
Kuwait Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Italy Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Oman Construction Market
Building Construction
Dominican Republic Construction Market
Building Construction
South Korea Data Center Construction Market
Building Construction
China Modular Construction Market
Building Construction
Honduras Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Energy-Efficient Building Market
Building Construction
France Prefab Homes Market