
 Pocket Door Market | 2026-2036
Pocket Door Market Size, Share, and Industry Trends Forecast 2026-2036
Pocket Door Market Analysis
The pocket door market is decoupling along hardware quality and installation complexity lines. Crown Industrial leverages its specialization in heavy-duty commercial-grade track systems to command premium positioning. Hafele sustains broad geographic coverage through its architectural hardware distribution network across Europe and North America. Johnson Hardware anchors the North American residential renovation segment with accessible DIY-ready framing kits.
A pocket door is a sliding door panel that disappears into a compartment recessed within an adjacent wall, typically requiring a finished wall cavity depth of 3.5 to 6 inches depending on panel thickness and track configuration. Its primary purpose is to reclaim floor and swing space in constrained residential, commercial, and hospitality interiors where conventional hinged doors would obstruct circulation patterns or furniture placement. Single pocket doors dominate residential new construction for bedroom and bathroom applications where space economy matters most. Glass pocket doors represent the fastest-expanding material segment in hospitality and high-end commercial fit-outs, driven by daylighting mandates and visual connectivity requirements. Custom pocket doors concentrate margin pools in luxury residential and boutique hotel projects where millwork integration and acoustic ratings justify substantial price premiums over standard units.
ISO 9001 quality management frameworks govern manufacturing consistency for major European producers exporting into multiple jurisdictions. The EPA Lead-Safe Renovation, Repair and Painting Rule shapes demand in the United States by adding compliance costs to retrofit installations in pre-1978 housing stock. Stakeholders must monitor evolving building energy codes in California, New York, and Germany that increasingly credit space-efficient layouts toward floor-area-ratio bonuses and thermal envelope performance targets.
Market Dynamics
Residential open-concept renovations are forcing hardware manufacturers to engineer slimmer track systems that fit within standard 2x4 wall cavities without compromising load ratings. This spatial constraint is compressing margins for suppliers unable to retool for shallow-depth configurations.
Growth Catalysts
- ANSI/BHMA A156.14 tightening:The updated sliding door hardware standard mandates higher cycle-life testing, pushing commercial builders toward certified track systems in hospitality and healthcare fit-outs.
- Urban housing densification:Tokyo, New York, and London developers are specifying pocket doors in micro-unit residential towers to reclaim circulation space for rentable floor area.
- Glass panel technology:Tempered low-iron glass with integrated track channels is enabling frameless pocket door installations in daylighting-focused commercial interiors.
Market Restraints
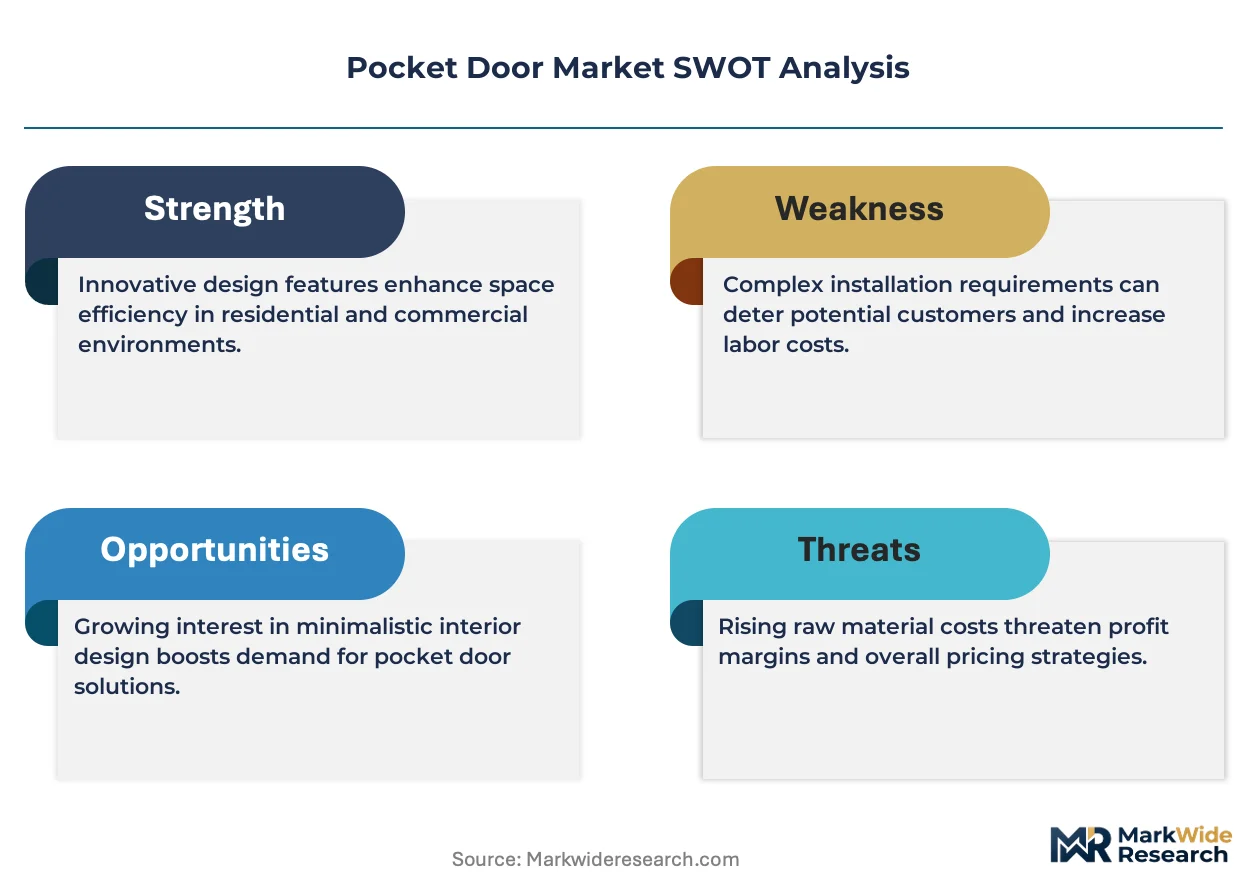
- Steel input cost volatility:Cold-rolled steel price swings directly compress hardware manufacturer margins, as track systems require high-tensile alloys for cycle durability.
- Installation skill concentration:Proper pocket door framing demands carpentry expertise that concentrates in specialized millwork contractors, limiting DIY market penetration.
- Acoustic performance ceiling:Standard pocket door assemblies struggle to achieve STC 40+ ratings without substantial cost adders, constraining adoption in multi-family housing.
Strategic Opportunities
- California Title 24 energy code:Floor-area-ratio bonuses for space-efficient layouts create regulatory tailwinds for pocket door specification in residential new construction.
- Modular construction integration:Prefabricated wall panels with factory-installed pocket door cassettes are opening channel partnerships with offsite builders in Germany and Scandinavia.
- Smart home convergence:Motorized pocket door systems with occupancy sensors and voice control integration are penetrating luxury residential and assisted living segments.
Industry Challenges
- Field measurement variability:Rough opening tolerances in renovation projects force custom fabrication delays, compressing project schedules and eroding contractor margins.
- Warranty claim complexity:Track misalignment from structural settling creates ambiguous liability between hardware suppliers, installers, and general contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pocket Door Market |
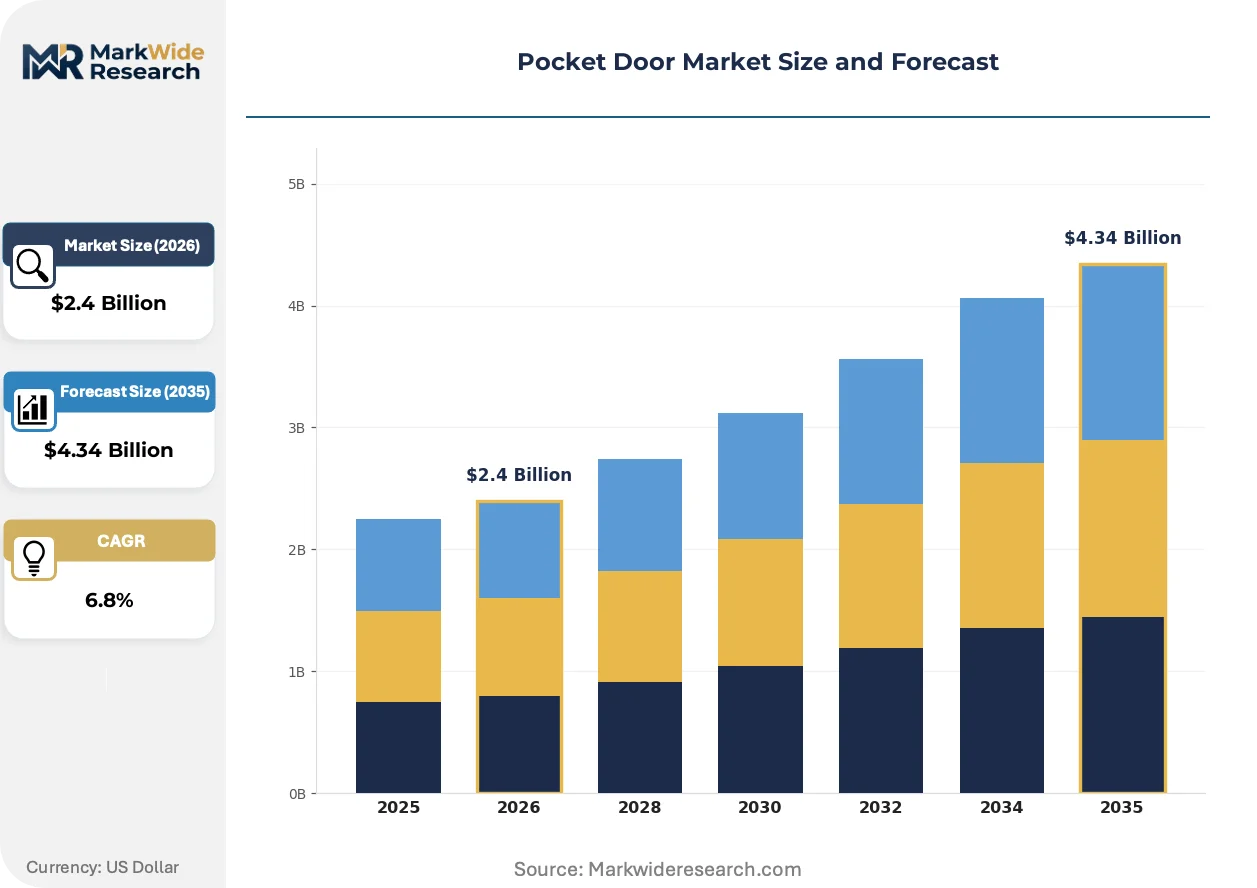
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Pocket Doors, Double Pocket Doors, Bi-Fold Pocket Doors, Custom Pocket Doors Material: Wood, Metal, Glass, PVC Application: Residential, Commercial, Industrial, Hospitality Installation Type: New Construction, Renovation, Retrofit, DIY |
| Companies Covered | Crown Industrial, Hafele, Amba Products, Raydoor, Johnson Hardware, Andersen Windows & Doors, Eclisse, Cavity Sliders USA Inc., Colonial Elegance Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pocket Door Market Emerging Trajectories
Hardware miniaturization and smart building integration are converging to redefine pocket door specification criteria. Suppliers now compete on concealed technology rather than purely mechanical performance.
Soft-close damping systems with hydraulic piston mechanisms are expanding into mid-market residential specifications. Production homebuilders in the southwestern United States are adopting these as standard features to differentiate entry-level product lines. The technology is expanding into price tiers previously served by basic roller hardware, compressing the addressable market for entry-level track suppliers.
EPA Lead-Safe Renovation, Repair and Painting Rule compliance is adding documentation burden to pre-1978 housing retrofits. Contractors must certify containment protocols when disturbing wall cavities, extending project timelines and steering some owners toward surface-mounted sliding barn doors as substitutes. The regulation most affects independent remodeling contractors in older urban housing stock across the northeastern and midwestern United States.
Builder procurement teams are consolidating hardware specifications across multi-project portfolios. National production homebuilders are negotiating master service agreements with single-source suppliers, displacing fragmented local distributor relationships. This concentration is most visible in the United States, where top-ten builders command substantial specification influence through direct vendor programs.
Pocket Door Market Segmentation
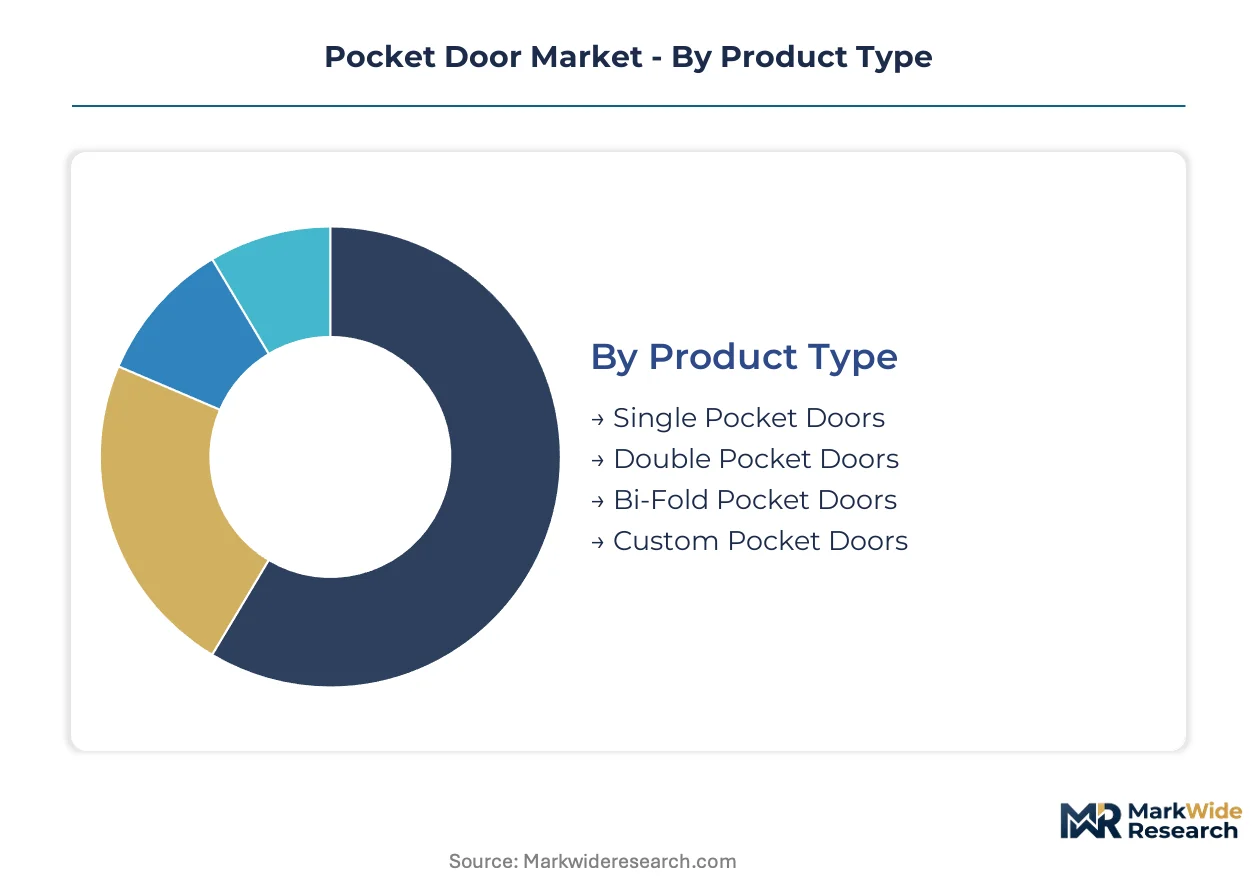
Pocket door procurement decisions cascade through multiple technical dimensions simultaneously. Builders weigh spatial constraints against acoustic performance, while material selection determines regulatory compliance pathways and lifecycle maintenance burdens.
Product Type:
Supply concentration favors single-panel systems where standardized framing kits achieve manufacturing scale.
- Single Pocket Doors:These units employ one sliding panel that recesses into a single wall cavity, typically accommodating panels up to 42 inches wide. Residential new construction in the United States absorbs the majority of volume, driven by bedroom and bathroom applications where space economy outweighs acoustic concerns. Single-panel configurations dominate because their hardware requires less precise alignment tolerance.
- Double Pocket Doors:Two panels meet at center and recess into opposite wall cavities, enabling openings up to 8 feet wide without swing clearance. Hospitality fit-outs in Germany specify these for conference room flexibility, though installation complexity limits residential penetration. Double systems demand perfectly plumb wall framing that concentrates skilled labor costs.
- Bi-Fold Pocket Doors:Hinged panel pairs fold before sliding, accommodating wider openings in constrained wall depths. Commercial retrofits in Japan utilize these where existing masonry walls prevent deep cavity modifications.
- Custom Pocket Doors:Bespoke dimensions and integrated millwork serve luxury residential and boutique hotel projects. Acoustic-rated assemblies with STC 50+ performance command substantial price premiums over standard units.
Today's leader: Single Pocket Doors. Tomorrow's challenger: Custom Pocket Doors.
Material:
Cost tier stratification separates commodity substrates from performance-engineered alternatives.
- Wood:Solid-core hardwood and engineered composite panels provide traditional aesthetic compatibility with residential millwork. North American production homebuilders specify paint-grade MDF cores for cost control, while stain-grade hardwood concentrates in custom residential.
- Metal:Aluminum and steel framing systems deliver fire-rated performance for commercial egress requirements. Industrial applications in the United States specify hollow metal pocket doors where durability trumps aesthetic refinement.
- Glass:Tempered low-iron panels with integrated track channels enable frameless installations. Hospitality and high-end commercial fit-outs in California specify these for daylighting compliance, representing the steepest expansion trajectory among material categories.
- PVC:Cellular polymer cores resist moisture degradation in coastal and humid climates. Budget residential renovations in Florida utilize these where maintenance simplicity outweighs premium appearance.
Volume concentrates in wood. Margin concentrates in glass.
Application:
Customer type divergence separates specification-driven commercial procurement from price-sensitive residential purchasing.
- Residential:Single-family and multi-family housing drives baseline demand through space-efficient floor plans. Open-concept renovations in the United States specify pocket doors to reclaim circulation area for usable living space.
- Commercial:Office fit-outs and retail environments prioritize flexibility and visual connectivity. Tenant improvement projects in New York City utilize glass pocket doors to subdivide open floor plates without permanent construction.
- Industrial:Warehouse offices and cleanroom applications demand durability over refinement. Food processing facilities specify stainless steel hardware for washdown compliance.
- Hospitality:Hotels and conference centers require acoustic isolation combined with spatial adaptability. Boutique properties in Germany integrate custom millwork pocket doors as brand differentiation elements.
Residential commands unit volume. Hospitality commands unit value.
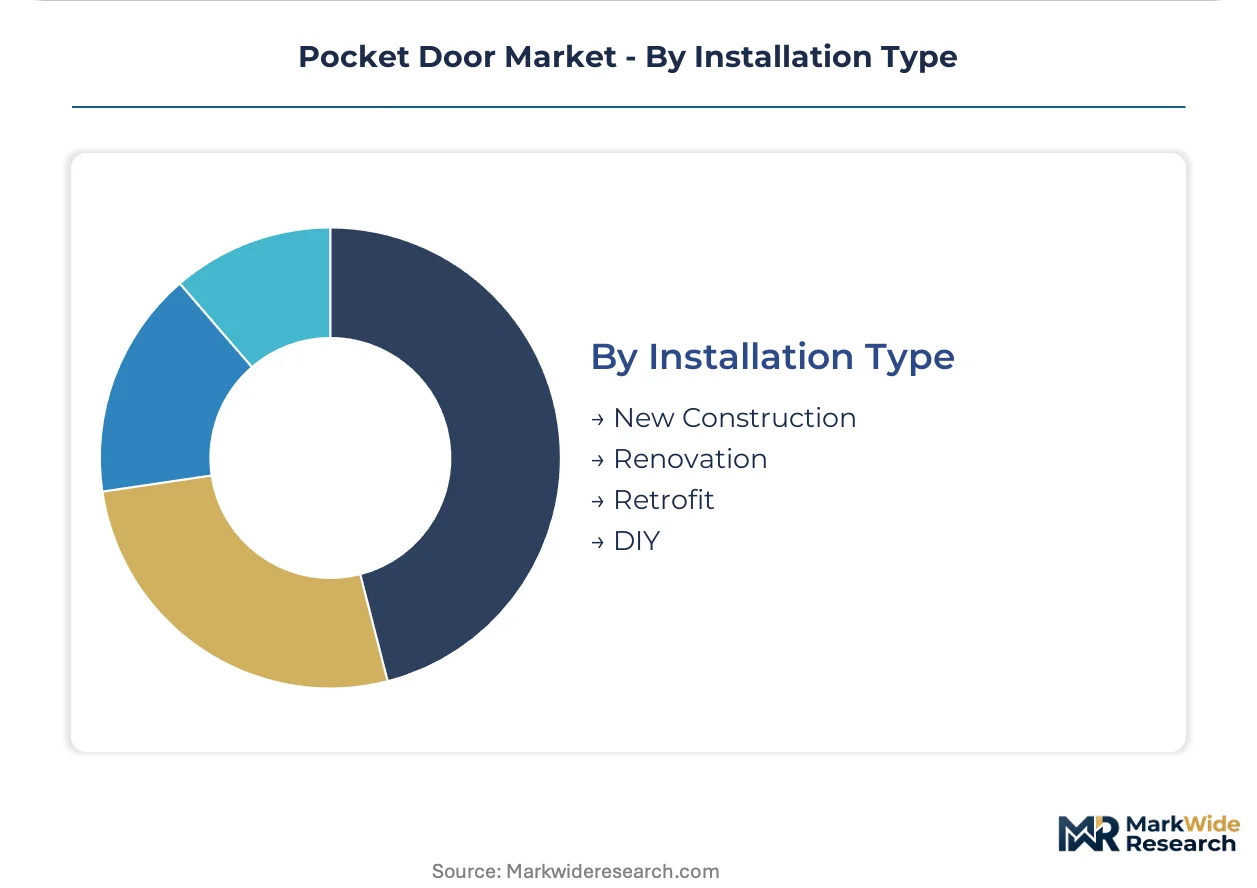
Installation Type:
Maturity gradients separate established new construction practices from emerging retrofit methodologies.
- New Construction:Rough framing accommodates pocket door cassettes during wall erection, minimizing installation precision requirements. Production homebuilders in the southwestern United States specify these as standard features in entry-level product lines.
- Renovation:Existing wall demolition and reconstruction demands specialized millwork contractors. EPA Lead-Safe Renovation, Repair and Painting Rule compliance adds documentation burden to pre-1978 housing stock modifications.
- Retrofit:Surface-mounted track systems bypass cavity requirements, though these sacrifice the space-reclaiming benefit that defines true pocket doors. Older urban housing in the northeastern United States sees substitution toward barn-door alternatives.
- DIY:Pre-assembled framing kits with installation templates target homeowner renovators. Johnson Hardware anchors this segment through accessible retail distribution.
New construction absorbs manufacturing scale. Renovation captures margin through service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled millwork contractors cluster in Germany's Black Forest region, Japan's Kanto industrial corridor, and the northeastern United States where historic housing stock demands specialized retrofit expertise.
United States
Production homebuilders in the southwestern states specify pocket doors as standard features in entry-level product lines to maximize usable floor area. EPA Lead-Safe Renovation, Repair and Painting Rule compliance adds documentation burden to pre-1978 housing retrofits in older urban centers. Specialized millwork contractors in Boston and Philadelphia concentrate installation expertise for historic brownstone renovations.
Germany
Hospitality developers specify double-panel systems for conference room flexibility in boutique hotel fit-outs across Berlin and Munich. REACH chemical compliance frameworks govern hardware finishing processes for European market access. Prefabricated wall panel manufacturers in Baden-Württemberg integrate factory-installed pocket door cassettes for modular construction partnerships.
Japan
Micro-unit residential towers in Tokyo deploy pocket doors to reclaim circulation space for rentable floor area in high-density developments. METI building energy efficiency guidelines credit space-efficient layouts toward compliance benchmarks. Osaka-based fabricators supply bi-fold configurations for commercial retrofits where existing masonry walls prevent deep cavity modifications.
United Kingdom
Tenant improvement projects in London utilize glass pocket doors to subdivide open floor plates without permanent construction in flexible office environments. CE marking requirements for sliding door hardware shape procurement specifications across commercial fit-outs. Manchester millwork specialists serve northern England's conversion market for industrial-to-residential adaptive reuse projects.
Canada
Multi-family housing developers in Toronto and Vancouver specify acoustic-rated assemblies to meet stringent STC requirements in urban mid-rise construction. Health Canada building code harmonization with US standards facilitates cross-border hardware sourcing. Calgary-based contractors concentrate expertise in energy-efficient envelope integration for cold-climate performance targets.
Pocket Door Market Vendor Landscape
Top-tier vendors anchor premium commercial-grade track systems, while mid-market fabricators compete on accessible DIY-ready framing kits. The vendor base stratifies across three functional tiers: heavy-duty commercial specialists, broad-coverage architectural hardware distributors, and residential renovation-focused suppliers. Two dominant competitive moves define current positioning: strategic partnerships with modular construction firms and portfolio diversification into smart home-integrated motorized systems.
Within the premium commercial-grade tier, Crown Industrial and Hafele occupy positions that exemplify hardware specialization and geographic coverage archetypes respectively. Crown Industrial represents the heavy-duty track system specialist concentrated in commercial hospitality and healthcare applications. Hafele anchors the broad architectural hardware distributor model with European and North American market presence. Johnson Hardware sits within the accessible residential renovation segment, targeting DIY-ready specification through retail distribution channels.
| Leading Market Players |
|---|
| Crown Industrial |
| Hafele |
| Amba Products |
| Raydoor |
| Johnson Hardware |
| Andersen Windows & Doors |
| Eclisse |
| Cavity Sliders USA Inc. |
| Colonial Elegance Inc. |
| Others |
Supply Flow & Price Mechanics
Cold-rolled steel price volatility cascades through pocket door hardware manufacturing, compressing margins for track system suppliers unable to pass input cost swings downstream while stratifying end-market pricing across installation-bundled and component-only procurement channels.
Pricing Analysis
Installation-bundled versus component-only procurement splits the market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under ANSI/BHMA A156.14 cycle-life testing tiers and acoustic performance ratings. Cost compression in economy track systems is intensifying because production homebuilders negotiate master service agreements that consolidate volume through single-source suppliers. DIY-ready framing kits face the highest price sensitivity among residential renovators, while hospitality developers specifying STC 50+ custom assemblies demonstrate minimal price elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Chinese cold-rolled steel mills supplying high-tensile alloys for commercial-grade track systems. Manufacturing concentration clusters in China, Germany, and the United States for precision-extruded aluminum channels and hardened steel roller hardware. Raw material dependencies encompass cold-rolled steel, tempered low-iron glass, and engineered composite cores for fire-rated assemblies. Tariff exposure on Chinese steel inputs threatens margin stability for North American hardware fabricators. Distribution runs through architectural hardware distributors serving commercial contractors and big-box retail channels targeting residential renovators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pocket door hardware functions as a stable compounder anchored by irreversible urban densification trends that permanently elevate space-efficiency specifications in residential and commercial construction.
For Market Incumbents: Acquire specialized millwork installation contractors to capture renovation-margin pools currently leaking to fragmented regional carpentry firms. Consolidate distribution control through exclusive partnerships with prefabricated wall panel manufacturers in Germany and Scandinavia. Defensive positioning requires certification investment to meet tightening ANSI/BHMA A156.14 cycle-life mandates before smaller competitors face retooling cost barriers. For New Entrants and Emerging Players: California Title 24 energy code opens a window for specification entry through floor-area-ratio bonus engineering that rewards space-efficient layouts. Target acoustic-rated retrofit assemblies for multi-family housing in Toronto and Vancouver where stringent STC requirements outpace incumbent capacity. Go-to-market leverage rests on direct contractor education programs that demystify pocket door framing for general carpentry crews outside specialized millwork networks. For Investors and Strategic Acquirers: Asymmetric upside sits with motorized smart-home-integrated system developers serving assisted living and luxury residential segments. Long-term viability frames around hardware-software convergence rather than pure mechanical component manufacturing. Acquisition focus should center on firms with captive soft-close damping technology and voice-control integration capabilities. The signal to watch is modular construction partnership announcements from offsite builders in Germany and Japan that validate factory-installed cassette demand.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Construction Partnership | Factory-installed pocket door cassettes in Baden-Württemberg prefabricated panels validate offsite integration demand. |
| Smart Home Convergence Investment | Motorized systems with occupancy sensors penetrate luxury residential and assisted living specification criteria. |
| Acoustic Performance Certification | STC 50+ rating achievement unlocks multi-family housing procurement in Toronto and Vancouver mid-rise construction. |
| Distribution Channel Consolidation | Master service agreements with top-ten US production homebuilders displace fragmented local distributor relationships. |
| Shallow-Depth Hardware Development | Slim track systems fitting standard 2x4 cavities address open-concept renovation constraints without load rating compromise. |
Methodological Framework
Direct dialogue with hardware manufacturing executives, millwork installation contractors, production homebuilder procurement directors, and architectural specification writers grounded qualitative insights that secondary sources subsequently validated against customs records, SEC 10-K filings, and building permit databases. Bottom-up and top-down triangulation cross-checked shipment volumes against construction spending patterns across residential, commercial, and hospitality verticals.
Segment-level value outputs across product type, material, application, and installation methodology dimensions were derived through econometric modeling over the projection horizon. CAGRs emerged from regression analysis against housing starts, renovation spending indices, and regulatory adoption curves. Industry-specific forecast inputs incorporated ANSI/BHMA certification penetration rates and modular construction partnership announcement flows.
Revisions become necessary when steel input cost volatility exceeds historical bands, when building code amendments alter floor-area-ratio bonus structures, or when smart home integration standards fragment across voice-control platforms. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
North America Concrete Superplasticizer Market
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Global Concrete Repair Mortars Market
Building & Construction Materials
Hollow Concrete Block Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Architectural Membrane Market
Building & Construction Materials
Global Concrete Block and Brick Manufacturing Market