
 Mexico Oriented Strand Board Market | 2026-2036
Mexico Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Oriented Strand Board Market Insights
Mexico's northern industrial corridor is reshaping regional OSB supply dynamics as cross-border lumber flows adapt to evolving trade frameworks. Arauco leverages its integrated forestry-to-panel operations across Latin America to sustain cost advantages in Mexican distribution channels. West Fraser Timber Co. Ltd. anchors North American supply relationships that position it strategically for northern Mexico construction demand. Louisiana-Pacific Corporation competes through specialized structural panel grades tailored to seismic-zone building requirements in central Mexican markets.
Oriented strand board consists of compressed wood strands arranged in cross-oriented layers bonded with waterproof resin adhesives, typically manufactured in continuous press systems at densities between 600-680 kg/m³ for structural load-bearing applications. Structural OSB dominates commercial construction specifications due to superior span ratings and code acceptance, while moisture resistant OSB captures expanding share in Mexico's humid coastal zones where conventional panels degrade prematurely. Flooring and wall sheathing applications generate the highest volume throughput, though furniture components represent a margin-accretive niche for precision-cut specialty grades.
CONUEE establishes Mexican energy efficiency standards that increasingly reference certified wood products, while NOM construction standards under Secretaría de Desarrollo Agrario, Territorial y Urbano dictate structural panel performance criteria for residential builds. BIS-equivalent conformity assessment procedures for imported OSB create compliance checkpoints that filter non-certified suppliers from formal procurement channels. Stakeholders must monitor evolving NOM amendments and cross-border certification reciprocity agreements to secure uninterrupted market access as Mexican building code harmonization with international standards advances.
Market Dynamics
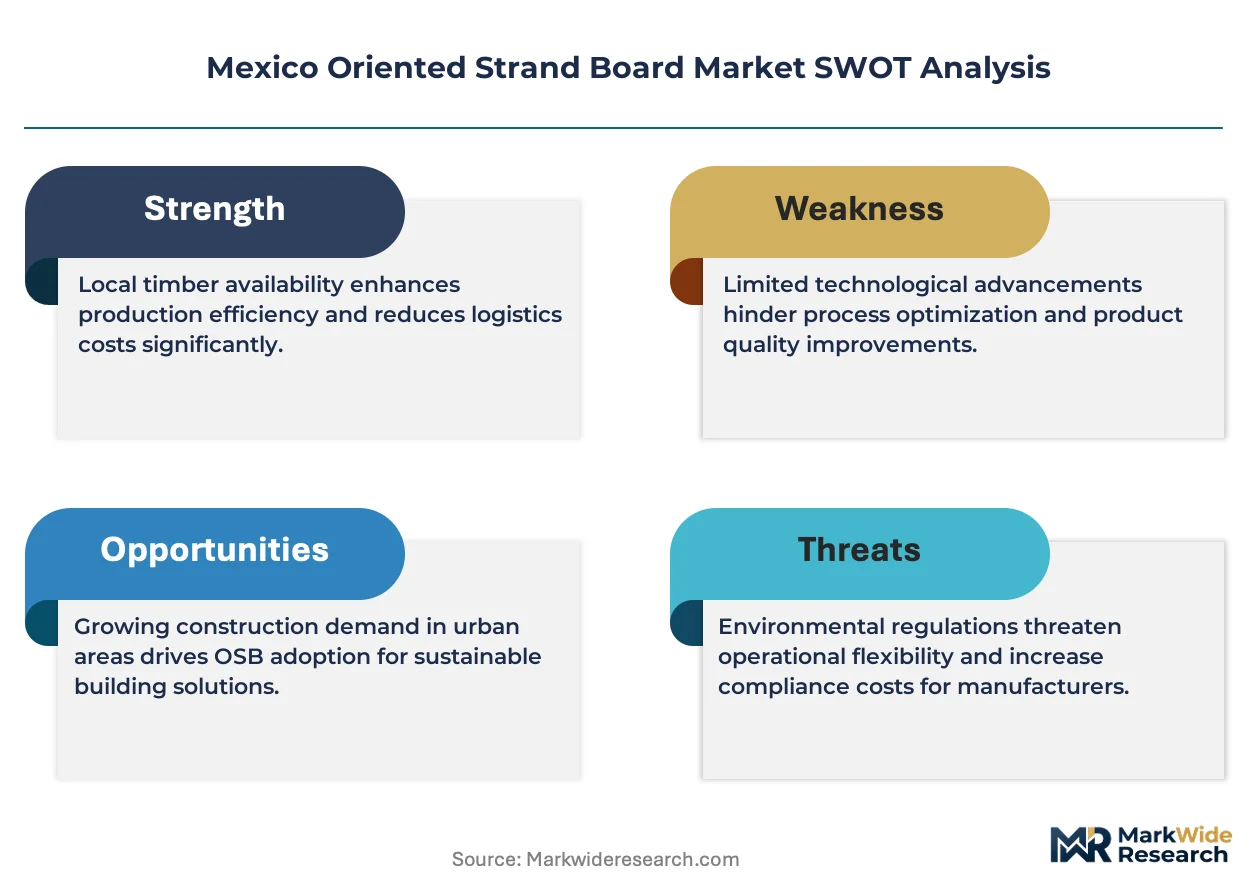
CONUEE's energy efficiency standards are compressing substitution timelines for traditional plywood across Mexican residential construction, forcing procurement officers to recertify supplier bases around structural panel performance criteria.
Growth Catalysts
- CONUEE Building Code Alignment:Updated NOM standards under Secretaría de Desarrollo Agrario, Territorial y Urbano mandate certified structural panels for affordable housing developments, accelerating formal procurement channel migration.
- Seismic-Zone Engineering:Central Mexico's highland construction firms specify engineered wood panels for shear-wall applications in multi-story residential builds, displacing conventional framing systems.
- Northern Industrial Corridor Expansion:Manufacturing facility construction across Chihuahua and Nuevo León generates sustained demand for structural sheathing in large-format commercial envelopes.
Market Restraints
- Resin Input Volatility:Methanol and formaldehyde price swings compress panel manufacturing margins, particularly for mid-scale producers lacking captive chemical supply.
- Import Certification Friction:BIS-equivalent conformity assessment procedures for cross-border OSB shipments create compliance bottlenecks at Mexican port-of-entry inspection points.
- Coastal Degradation Risk:Conventional OSB formulations face premature failure in Veracruz and Yucatán humidity zones, limiting addressable market for non-specialized grades.
Strategic Opportunities
- Moisture-Resistant Grade Penetration:Uncertified coastal construction markets in Campeche and Tabasco present white-space expansion potential for phenolic-resin panel variants.
- Furniture Component Specialization:Precision-cut specialty grades for cabinetry and fixture manufacturing command margin premiums in Guadalajara's woodworking cluster.
- Direct-to-Developer Distribution:Bypassing traditional lumber yard intermediaries through volume contracting with INFONAVIT-subsidized housing developers reduces channel cost structure.
Industry Challenges
- Continuous Press Operator Scarcity:Specialized technician training lags behind capacity expansion timelines for new continuous press installations.
- NOM Amendment Tracking Burden:Compliance teams must monitor evolving construction standard revisions without centralized regulatory notification systems.
- Strand Quality Consistency:Variable pine and eucalyptus fiber supply from fragmented Mexican timber holdings disrupts panel density uniformity targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Oriented Strand Board Market |
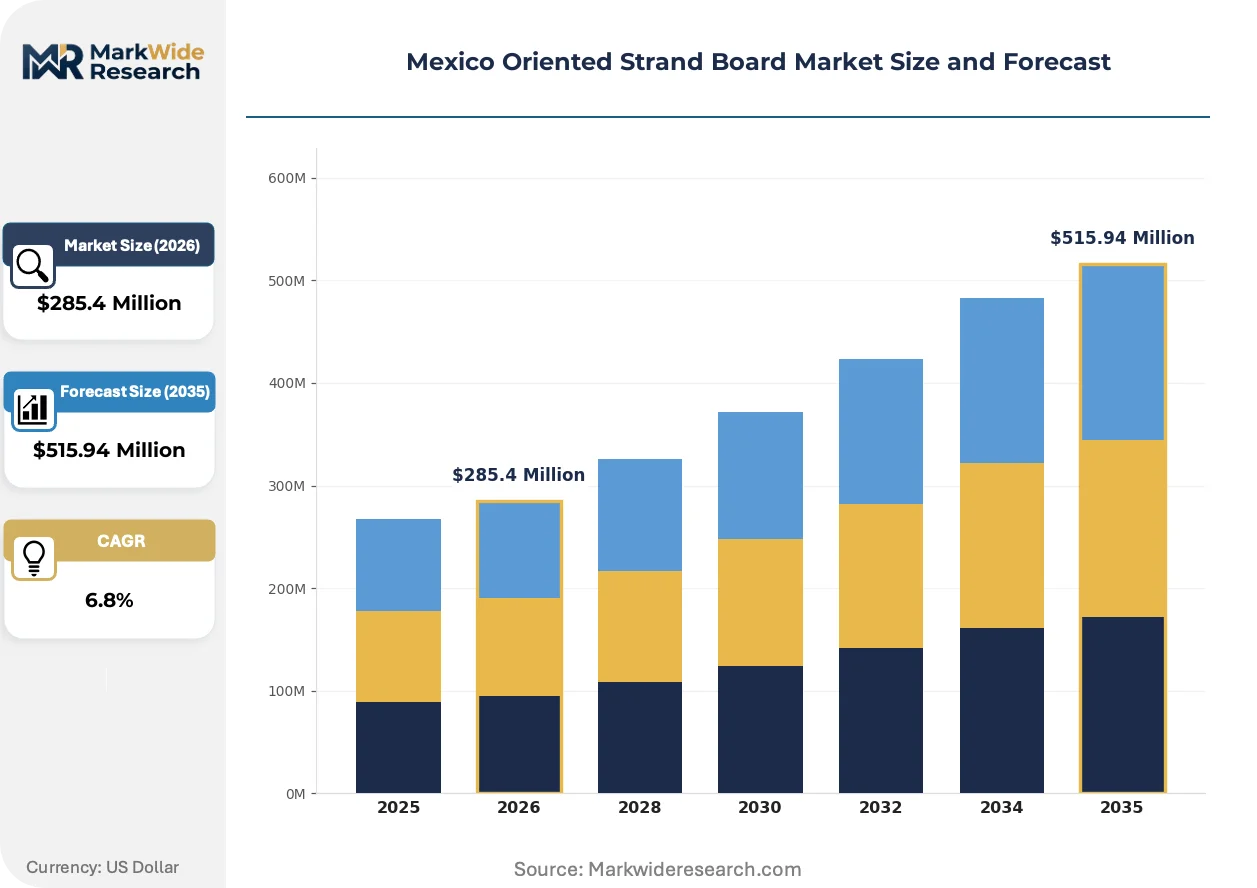
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard OSB, Structural OSB, Moisture Resistant OSB, Fire Retardant OSB Application: Flooring, Roofing, Wall Sheathing, Furniture Components End User: Construction Companies, Furniture Manufacturers, DIY Enthusiasts, Distributors Thickness: 7/16 inch, 1/2 inch, 5/8 inch, 3/4 inch |
| Companies Covered | Arauco, Kronospan, West Fraser Timber Co. Ltd., Louisiana-Pacific Corporation, Georgia-Pacific, Weyerhaeuser Company, Egger Group, Swiss Krono Group, Sonae Arauco, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Oriented Strand Board Market Trends and Innovations
Digital process control systems are compressing quality variance in Mexican OSB manufacturing while regulatory harmonization pressures reshape certification requirements across the construction value chain.
Continuous press automation is digitizing strand alignment precision and resin distribution monitoring. Large-scale producers in Estado de México deploy real-time density scanning to reduce grade rejection rates. This capability is digitizing quality assurance workflows that previously required manual batch testing.
CONUEE's alignment with ISO 14001 environmental management standards is mandating lifecycle documentation for structural wood products. Panel manufacturers must now submit embodied carbon calculations for federal housing project eligibility. Central region suppliers have reorganized procurement teams to manage chain-of-custody certification requirements.
Volume contracting is consolidating buyer power among INFONAVIT-affiliated developers in the Mexico City metropolitan corridor. Traditional spot purchasing through regional distributors is yielding to multi-year supply agreements with fixed-grade specifications. This concentration is most visible in Tlalnepantla and Ecatepec construction clusters where developer consortia negotiate directly with panel producers.
Mexico Oriented Strand Board Market Segmentation
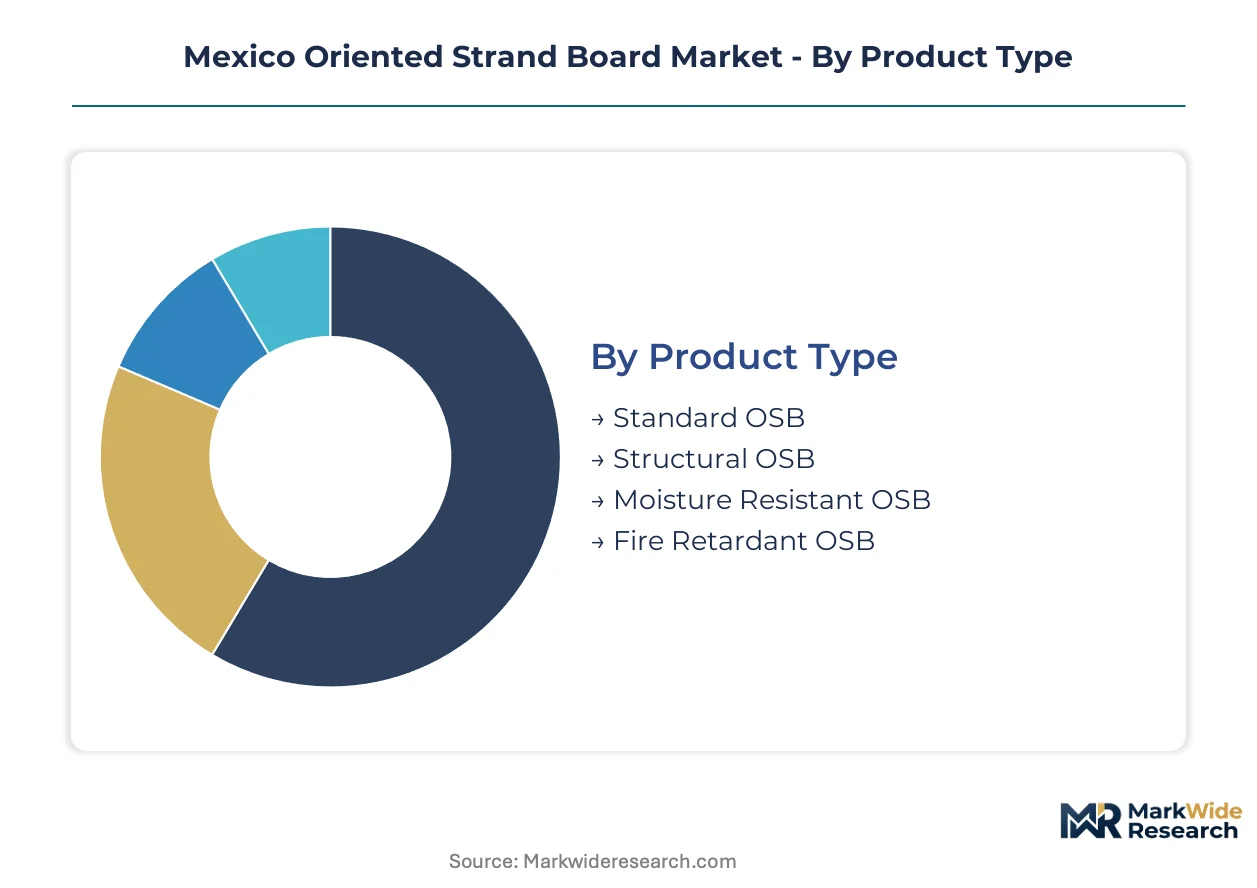
Segmentation in Mexico's OSB market reveals how procurement specifications diverge between seismic-zone structural requirements and coastal humidity challenges. Product-grade differentiation directly determines distribution channel access and federal housing project eligibility under CONUEE standards.
Product Type:
Cycle times vary dramatically across panel grades, with commodity-standard formulations turning inventory fastest while specialty-certified products require longer specification approval windows.
- Standard OSB:Manufactured with conventional phenol-formaldehyde resin systems at densities between 600-640 kg/m³ for general-purpose sheathing. Demand concentrates in Mexico City's peripheral housing developments where INFONAVIT-subsidized projects prioritize cost efficiency over performance certification.
- Structural OSB:Cross-oriented strand layering achieves superior span ratings and shear-wall performance for multi-story residential builds. Central Mexico highland construction firms specify this grade for seismic-zone applications, displacing conventional plywood in formal procurement channels.
- Moisture Resistant OSB:Phenolic-resin formulations withstand Veracruz and Yucatán humidity exposure without edge swelling or delamination.
- Fire Retardant OSB:Borate-treated variants meet commercial envelope specifications in Nuevo León industrial facilities.
Structural OSB anchors the volume base while moisture-resistant grades gain share at the steepest rate.
Application:
Cost tiers separate high-volume structural sheathing from precision-cut specialty components serving margin-accretive niches.
- Flooring:Tongue-and-groove edge profiling supports residential subfloor systems with superior load distribution across joist spans. Tlalnepantla and Ecatepec construction clusters specify this application for INFONAVIT-affiliated multi-unit housing.
- Roofing:Panel grades with enhanced nail-hold resistance secure thermal insulation layers in commercial envelope systems. Northern Chihuahua manufacturing facilities drive specification volume for large-format industrial roofs.
- Wall Sheathing:Continuous sheathing applications dominate Mexico City metropolitan corridor residential construction.
- Furniture Components:Precision-cut specialty grades command premium pricing in Guadalajara's woodworking cluster.
Flooring and wall sheathing anchor the volume base while furniture components climb the fastest in margin contribution.
End User:
Customer type determines procurement scale, with formal developers leveraging volume contracting against fragmented spot purchasing through traditional lumber yards.
- Construction Companies:Large-scale residential developers in Estado de México negotiate multi-year supply agreements with fixed-grade specifications, bypassing regional distributor markups.
- Furniture Manufacturers:Guadalajara's cabinetry and fixture producers source precision-cut specialty grades through direct mill relationships.
- DIY Enthusiasts:Small-lot purchasers access OSB through home improvement retail channels in urban centers.
- Distributors:Traditional lumber yards serve fragmented regional construction markets outside metropolitan corridors.
Construction companies anchor the volume base while furniture manufacturers expand most quickly in value terms.
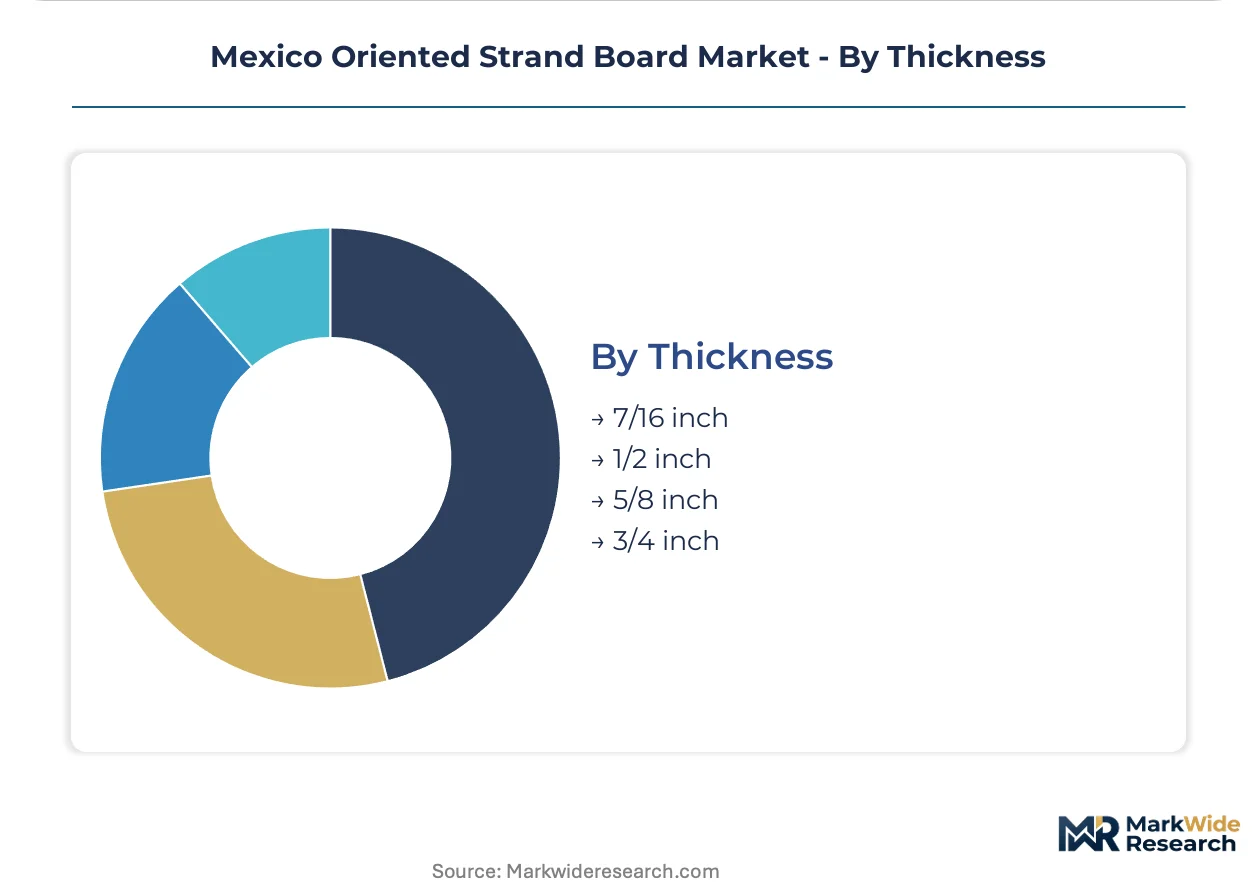
Thickness:
Supply concentration favors standard thicknesses, with non-standard dimensions requiring extended lead times and premium pricing.
- 7/16 inch:Minimum thickness for roof sheathing applications in single-family residential construction across Mexico's central highlands.
- 1/2 inch:Standard wall sheathing specification for light-frame residential builds in Tlalnepantla construction clusters.
- 5/8 inch:Enhanced span ratings support floor joist spacing in multi-story affordable housing developments.
- 3/4 inch:Heavy-duty flooring and commercial subfloor applications in Nuevo León industrial facilities.
7/16 inch and 1/2 inch thicknesses anchor the volume base while 5/8 inch specifications expand most quickly in multi-story residential applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CONUEE's building code harmonization anchors demand concentration across Mexico's central highlands, where federal housing programs and seismic engineering requirements intersect. Metropolitan construction corridors generate disproportionate procurement volume as developer consortia consolidate supply relationships.
Mexico City Metropolitan Corridor
INFONAVIT-subsidized affordable housing developments in Tlalnepantla and Ecatepec drive structural panel procurement at scale. NOM construction standards under SEDATU mandate certified OSB for multi-story residential shear-wall applications. Developer consortia in Estado de México negotiate multi-year supply agreements directly with producers, bypassing traditional lumber yard intermediaries.
Nuevo León
Industrial facility construction across Monterrey and Apodaca generates sustained demand for fire-retardant and heavy-duty flooring grades. State-level environmental permits align with CONUEE efficiency benchmarks for commercial envelope systems. Chihuahua manufacturing spillover extends specification influence into northern Nuevo León border zones.
Jalisco
Guadalajara's woodworking cluster sources precision-cut specialty grades for cabinetry and fixture manufacturing at margin premiums. Furniture component applications climb fastest in value terms as regional producers develop direct mill relationships. State industrial promotion programs support downstream wood processing capacity expansion.
Veracruz and Yucatán Peninsula
Humidity exposure in Campeche and Tabasco construction markets creates white-space expansion potential for phenolic-resin moisture-resistant variants. Conventional OSB formulations face premature edge swelling and delamination failure in coastal zones. Uncertified local builders present conversion opportunity as CONUEE standards extend enforcement reach.
Chihuahua and Northern Border States
Cross-border lumber flows adapt to evolving trade frameworks as manufacturing facility construction sustains structural sheathing demand. BIS-equivalent conformity assessment procedures create compliance bottlenecks at port-of-entry inspection points. Ciudad Juárez and Chihuahua City industrial zones anchor regional distribution infrastructure.
Mexico Oriented Strand Board Market Competitive Landscape
Capability concentration sits with integrated forestry-to-panel operators; scale advantage sits with North American supply network anchors. The vendor base stratifies across three tiers: Latin American integrated producers with captive timber supply, Canadian and US majors leveraging cross-border logistics infrastructure, and European specialists targeting premium-grade niches. Dominant competitive moves include backward integration into resin chemistry and continuous press capacity expansion.
Within the integrated Latin American tier, Arauco exemplifies forestry-to-panel vertical control, while Sonae Arauco occupies a parallel position with Iberian-African supply chain linkages. At the North American scale-driven end, West Fraser Timber Co. Ltd. and Louisiana-Pacific Corporation anchor cross-border distribution networks serving northern Mexico construction demand. These three represent distinct archetypes: hemispheric resource integration, transatlantic specialty positioning, and continental logistics dominance.
| Leading Market Players |
|---|
| Arauco |
| Kronospan |
| West Fraser Timber Co. Ltd. |
| Louisiana-Pacific Corporation |
| Georgia-Pacific |
| Weyerhaeuser Company |
| Egger Group |
| Swiss Krono Group |
| Sonae Arauco |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals from Estado de México press installations compress supplier pricing power while simultaneously accelerating procurement consolidation among INFONAVIT-affiliated developers. Continuous press utilization rates below optimal thresholds force mid-scale producers to absorb resin input volatility rather than pass through cost increases.
Pricing Analysis
Geographic price spreads between Mexico City metropolitan corridor and Veracruz coastal zones reflect moisture-resistant grade premiums and logistics cost differentials. Three-tier pricing structure across structural-certified, standard sheathing, and economy grades separates formal procurement channels from spot-market transactions. Pricing pressure stems from methanol and formaldehyde cost compression in resin chemistry inputs. INFONAVIT-subsidized developers exhibit highest price sensitivity, while Guadalajara furniture manufacturers accept premiums for precision-cut specialty grades.
Supply Chain Analysis
Tariff exposure between United States and Mexico dominates cross-border OSB shipment economics at Ciudad Juárez and Laredo port-of-entry inspection points. Supply concentration rests on Chilean integrated forestry operations, Canadian cross-border logistics networks, and domestic Estado de México manufacturing clusters. Raw material dependencies include pine and eucalyptus fiber from fragmented Mexican timber holdings, phenol-formaldehyde resin systems, and waterproof adhesive chemistry. Single-source vulnerability concentrates in continuous press equipment supply from European specialized manufacturers. Distribution runs through direct-to-developer volume contracting, bypassing traditional lumber yard intermediaries in Tlalnepantla and Ecatepec construction clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortages of trained continuous press operators and certified quality technicians constrain capacity expansion timelines across Mexican OSB manufacturing, creating asymmetric returns for stakeholders who secure technical talent pipelines.
For Market Incumbents: Pre-empt resin input volatility by securing captive chemical supply agreements or backward integration into adhesive manufacturing. Expand continuous press capacity in Estado de México before competitor installations saturate local fiber supply. CONUEE certification reciprocity negotiations threaten to filter non-compliant suppliers from federal housing procurement channels. For New Entrants and Emerging Players: Campeche and Tabasco coastal construction markets present white-space expansion potential for phenolic-resin moisture-resistant panel variants. Uncertified local builders in Yucatán Peninsula humidity zones lack access to compliant structural grades. Direct mill relationships with Guadalajara woodworking clusters bypass established distribution markups. For Investors and Strategic Acquirers: Capital is best deployed toward integrated forestry-to-panel operators with captive timber supply across Latin America. Long-term viability hinges on CONUEE alignment and NOM construction standard compliance capabilities. Watch for INFONAVIT procurement volume inflections as affordable housing program acceleration signals demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Press Capacity Expansion | Real-time density scanning capabilities reduce grade rejection rates in Estado de México manufacturing clusters. |
| Backward Integration into Resin Chemistry | Captive phenol-formaldehyde supply shields margins from methanol price volatility affecting mid-scale competitors. |
| CONUEE Certification Investment | NOM construction standard compliance secures eligibility for INFONAVIT-subsidized federal housing project procurement. |
| Direct-to-Developer Distribution | Volume contracting with Tlalnepantla and Ecatepec consortia eliminates traditional lumber yard intermediary markups. |
| Moisture-Resistant Grade Development | Phenolic-resin formulations capture Veracruz and Yucatán coastal construction markets prone to conventional panel degradation. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with OSB manufacturing executives, procurement officers at INFONAVIT-affiliated developers, SEDATU regulatory compliance leads, and Guadalajara furniture cluster production managers; alongside secondary validation through CONUEE standard documentation, NOM construction code amendments, Mexican customs trade records, and SEC filings of North American panel producers. Bottom-up volume estimates from continuous press capacity installations triangulated against top-down construction sector demand projections.
Forecast inputs span product-grade segmentation across structural, moisture-resistant, and fire-retardant formulations; application dimensions including flooring, wall sheathing, roofing, and furniture components; and end-user categories from construction companies to DIY retail channels. CAGRs were derived from elasticity-adjusted demand modeling across the projection horizon, incorporating resin input cost trajectories and CONUEE enforcement timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chilean integrated producers or sudden NOM standard acceleration would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Rubber Expansion Joints Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
United States I-Joist Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Concrete Conditioner Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Decks Market
Building & Construction Materials
Urethane Concrete Sealer Market