
 Outside Door Handle Market | 2026-2036
Outside Door Handle Market Size, Share, and Industry Trends Forecast 2026-2036
Outside Door Handle Market Analytics
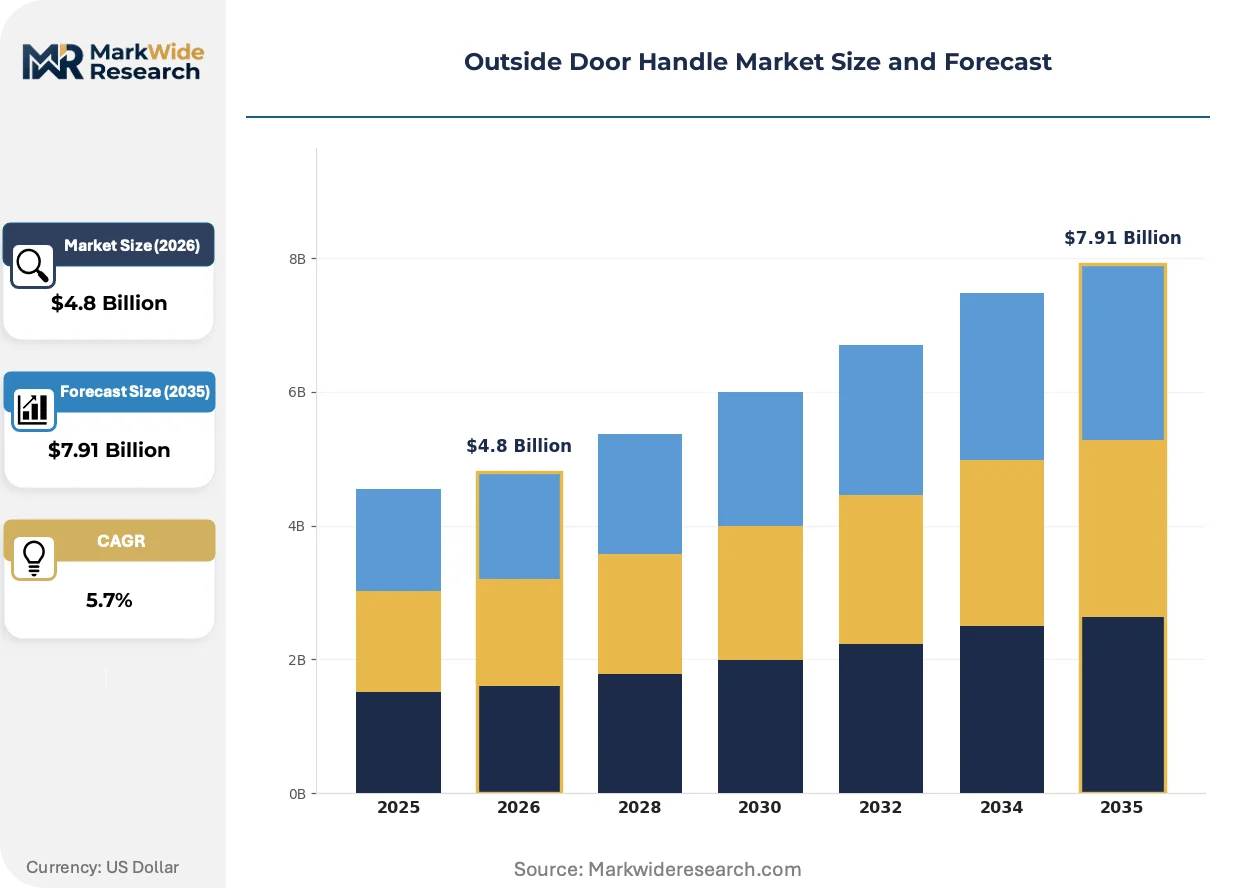
Luxury automotive OEMs are gaining procurement share as mainstream fleet operators retrench, and the outside door handle market is bifurcating into premium experience-driven and cost-optimized supply tiers. Assa Abloy AB leverages its electronic access expertise to dominate smart handle architectures for high-end vehicles. dormakaba Holding AG sustains R&D intensity in power-assisted mechanisms for European automotive platforms. Hoppe Holding AG anchors its position through manufacturing scale in precision metal forming for OEM supply chains.
An outside door handle is a mechanical or electromechanical interface component, typically fabricated from die-cast aluminum or injection-molded reinforced polymers, that enables manual or automated actuation of a vehicle or building entry latch mechanism. The component must withstand cyclic fatigue loads exceeding thousands of operations while maintaining corrosion resistance and tactile feedback standards. Smart and keyless product types command the strongest margin pools as semiconductor integration and capacitive sensing replace mechanical tumblers. Stainless steel material grades retain volume leadership in OEM channels where durability specifications override lightweighting targets, though aluminum is displacing legacy steel in electrified vehicle architectures seeking mass reduction.
NHTSA in the United States enforces occupant safety and exterior protrusion standards that dictate handle geometry and breakaway force thresholds for automotive applications. ECE R21 regulations across European type-approval frameworks govern interior and exterior projections, directly influencing handle design minimums and maximums for vehicles sold in EU member states. REACH compliance in Europe further constrains coating chemistries and surface treatments available to manufacturers. Stakeholders must monitor evolving cybersecurity mandates for keyless entry systems as connected vehicle architectures expand attack surfaces beyond mechanical theft vectors.
Market Dynamics
Electrification architectures are compressing mechanical component counts while expanding semiconductor integration, forcing handle suppliers to requalify die-cast aluminum and capacitive sensor modules under stricter electromagnetic compatibility standards.
Growth Catalysts
- EU F-Gas Regulation:Phasedown of hydrofluorocarbon propellants is accelerating solvent-free coating adoption for European automotive supply chains, opening qualification windows for compliant surface treatment vendors.
- Luxury automotive OEMs:Premium cabin differentiation strategies are expanding procurement of smart handles with integrated puddle lamps and biometric sensing across German and Japanese flagship platforms.
- Die-cast aluminum forming:Mass reduction imperatives in battery-electric vehicles are displacing stainless steel in closure hardware, with Stuttgart and Munich component clusters scaling precision casting capacity.
Market Restraints
- Zinc alloy price volatility:Die-cast substrate costs fluctuate with LME zinc pricing, squeezing margin predictability for mid-volume handle manufacturers serving mainstream OEM tiers.
- Semiconductor supply concentration:Capacitive sensing ICs and NFC controllers face fabrication bottlenecks concentrated in Taiwan and South Korea, constraining smart handle output scaling.
- ECE R21 protrusion limits:Exterior projection maximums restrict handle housing depth and breakaway geometry, limiting design freedom for integrated electronic modules.
Strategic Opportunities
- India PLI scheme:Automotive component production-linked incentives are attracting handle tooling investments to Pune and Chennai manufacturing corridors for export-oriented supply.
- Keyless-to-phone convergence:Ultra-wideband and Bluetooth Low Energy integration with smartphone digital keys is creating white space for software-defined access platforms.
- REACH coating exemptions:Regulatory review timelines for hexavalent chromium alternatives are shortening, rewarding early movers in trivalent passivation and thin-film ceramic technologies.
Industry Challenges
- EMC validation cycles:Electromagnetic compatibility testing for capacitive handles requires extended chamber time, compressing program launch windows for new vehicle platforms.
- Cross-functional talent scarcity:Mechatronics engineers with both precision metal forming and embedded firmware expertise command premium compensation, constraining R&D team scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outside Door Handle Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Power, Smart, Keyless Material: Plastic, Metal, Aluminum, Stainless Steel End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Dealerships Installation Type: Integrated, Retrofit, Replacement, Custom |
| Companies Covered | Hoppe Holding AG, dormakaba Holding AG, Assa Abloy AB, Kuriki Manufacture Co., Aarkay Vox, Allegion Plc, Emtek Products Inc., West INX Ltd., The Häfele Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outside Door Handle Market Evolving Landscape
Capacitive sensing and connected vehicle architectures are collapsing the boundary between mechanical hardware and software-defined access, redistributing value capture toward semiconductor and systems integration competencies.
Flush-mounted capacitive handles with integrated pressure and proximity sensing are displacing conventional pull-type mechanisms in premium electric vehicle architectures. German luxury OEMs are qualifying these modules for 2026 platform launches, requiring suppliers to master thin-film deposition and conformal coating processes previously foreign to metal forming operations. This displacement is compressing the supplier base toward tier-one electronics integrators with captive mechatronics capabilities.
REACH authorization processes for chromium trioxide in decorative finishes are tightening compliance timelines across European supply chains. ECHA sunset date extensions for aerospace and automotive applications are narrowing, forcing coating houses to accelerate trivalent chromium and PVD alternative qualification. Decorative stainless steel handle suppliers serving Stuttgart OEMs are most exposed, with some advancing ceramic composite topcoats to bypass metal finishing constraints entirely.
Fleet operators and leasing companies are consolidating specification authority previously dispersed across individual OEM purchasing departments. Large European rental and corporate fleet managers are issuing unified technical requirements for handle durability and repair cost predictability, bypassing traditional OEM tiering structures. This concentration is most visible in Germany's commercial vehicle segment, where procurement teams now specify standardized handle architectures across multi-brand fleets.
Outside Door Handle Market Segmentation
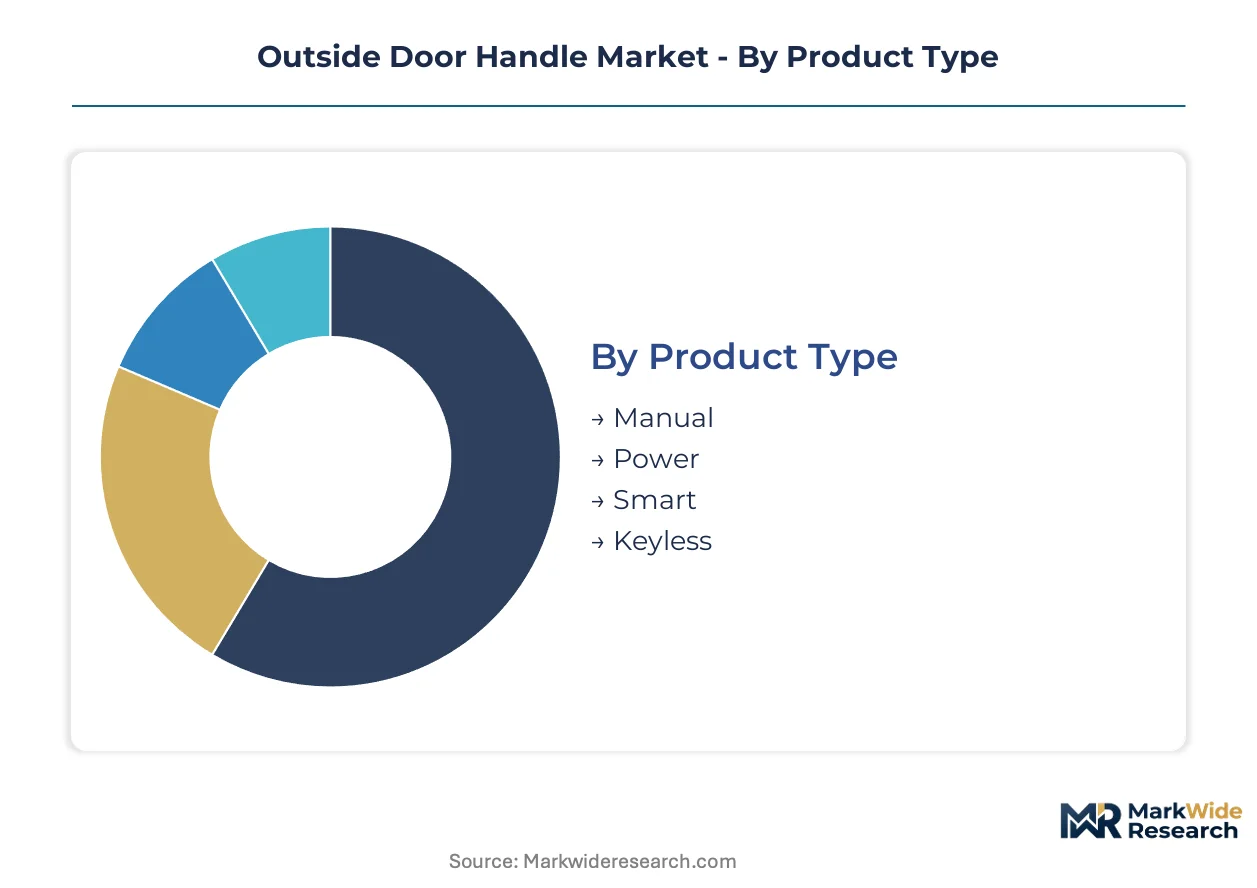
Outside door handle procurement splits sharply across electronic complexity tiers and material specifications, with regulatory compliance costs and electrification roadmaps dictating supplier qualification pathways. Segmentation reveals where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
REACH and ECE R21 compliance requirements diverge most sharply between mechanical and electronic actuation systems, forcing separate validation tracks for European automotive supply chains.
- Manual:Purely mechanical pull-lever designs fabricated from stamped steel or zinc die-cast substrates. Stuttgart-based OEM procurement for entry-level fleet vehicles sustains volume, though specifications tighten on breakaway force tolerances under NHTSA exterior protrusion standards.
- Power:Motor-assisted mechanisms with electromechanical latch release for accessibility compliance. German luxury platforms in Munich and Stuttgart clusters specify these for premium sedan architectures, with KBA type-approval cycles extending lead times.
- Smart:Capacitive sensing modules with proximity detection and puddle lamp integration. Demand concentrates in Japanese flagship EV platforms seeking cabin differentiation through gesture-based entry.
- Keyless:Passive entry systems with UWB and BLE smartphone pairing capability. Cybersecurity mandates from UNECE WP.29 regulations constrain firmware architecture choices for European deployment.
Manual handles still process the highest unit throughput across mainstream OEM tiers; keyless systems are expanding most quickly on revenue share as digital key adoption accelerates.
Material:
Mass reduction targets in battery-electric architectures are compressing traditional material hierarchies, with aluminum displacing legacy steel in closure hardware faster than polymer substitution.
- Plastic:Glass-reinforced polyamide and PBT compounds for cost-optimized aftermarket replacement channels. Injection molding scale in China's Yangtze River Delta serves global export demand, though surface finish durability limits OEM adoption.
- Metal:Zinc-aluminum die-cast alloys (Zamak) dominating mid-volume OEM supply with established plating infrastructure. LME zinc price volatility squeezes margin predictability for Stuttgart component suppliers.
- Aluminum:High-pressure die-cast and extruded grades achieving 40% mass reduction versus steel equivalents. Stuttgart and Munich clusters are scaling precision casting capacity for European BEV platform launches.
- Stainless Steel:Austenitic grades (304, 316) retaining specification in commercial vehicle and marine applications where corrosion resistance overrides lightweighting. Decorative finish houses in Germany's North Rhine-Westphalia region face REACH chromium trioxide sunset pressures.
Aluminum commands the steepest expansion trajectory as electrification penetrates premium passenger segments; stainless steel retains defensive positions in durability-critical niches.
End User:
Procurement authority consolidation among fleet operators is collapsing traditional OEM tiering structures, with specification power shifting from brand purchasing departments to multi-brand fleet technical offices.
- OEMs:Original equipment manufacturers with captive handle specifications tied to platform engineering cycles. German luxury OEMs in Stuttgart and Munich are consolidating smart handle suppliers to reduce electromagnetic compatibility validation redundancy.
- Aftermarket Providers:Independent distributors and e-commerce channels serving collision repair and restoration demand. India's Pune manufacturing corridor is attracting tooling investments under PLI scheme incentives for export-oriented aftermarket supply.
- Vehicle Manufacturers:Commercial vehicle and specialty equipment builders with durability-focused specifications. Fleet procurement concentration in Germany's corporate leasing segment is standardizing handle architectures across multi-brand truck deployments.
- Dealerships:Authorized service networks handling warranty replacements and accessory upgrades. Margin compression in retail channels favors standardized SKUs over custom configurations.
OEMs retain the dominant share of specification authority; fleet operators are gaining share fastest as procurement centralization accelerates.
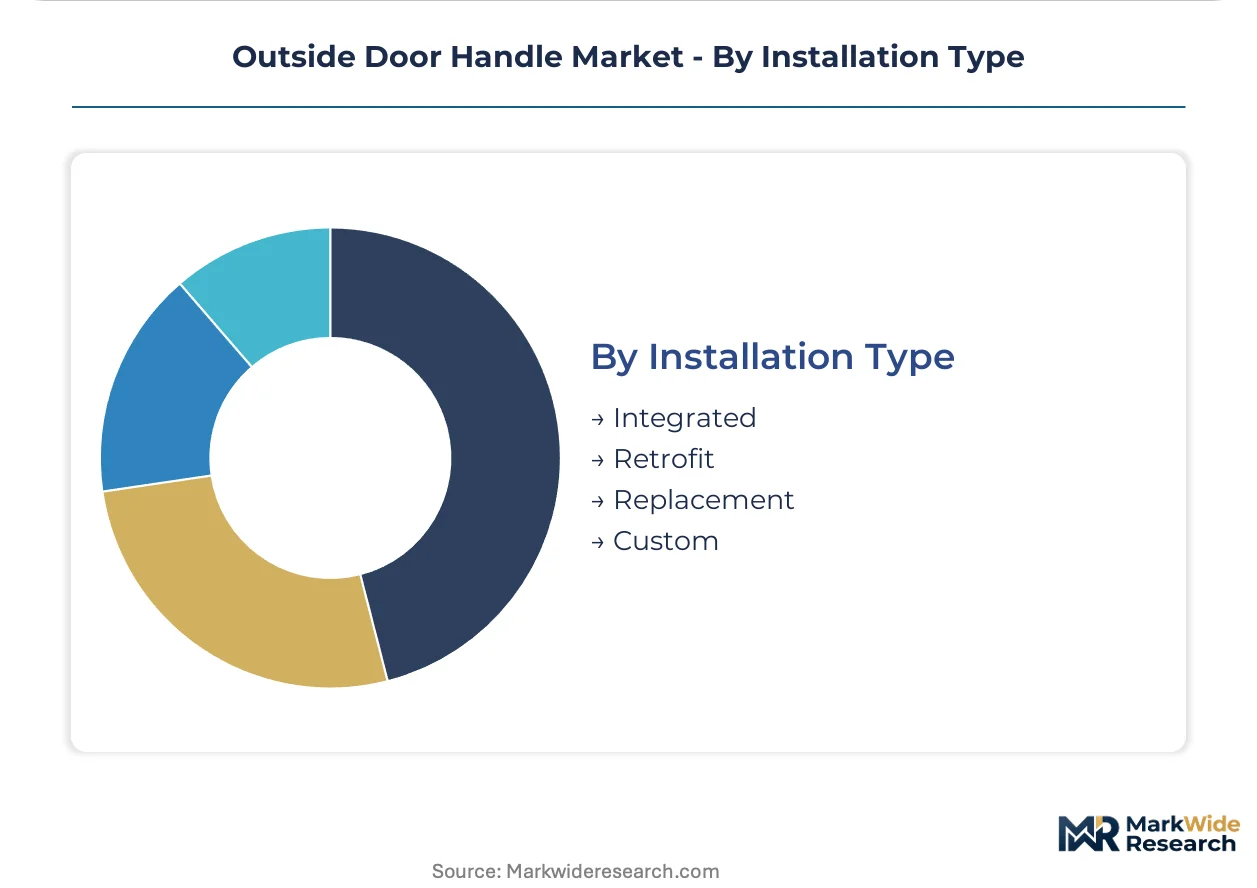
Installation Type:
Service channel economics and vehicle lifecycle positioning determine installation architecture choices, with integrated designs capturing platform engineering value and replacement channels optimizing for technician efficiency.
- Integrated:Factory-installed modules with embedded electronics and sealed sensor assemblies. Stuttgart OEMs specify these for premium EV architectures requiring flush-mounted capacitive interfaces.
- Retrofit:Aftermarket conversion kits upgrading manual to power-assisted mechanisms. Aging fleet segments in North American commercial vehicle markets sustain demand despite warranty complexity.
- Replacement:Direct-fit components matching original specifications for collision repair. Insurance cost pressures favor certified aftermarket alternatives over OEM captive parts in Germany's repair network.
- Custom:Bespoke fabrication for restoration, motorsport, and luxury coachbuilding applications. Low-volume specialty houses in Italy's Emilia-Romagna cluster command premium pricing for hand-finished metalwork.
Integrated installations dominate new vehicle value capture; replacement channels show the fastest volume growth as parc age extends across European and North American markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German component clusters export precision die-cast aluminum handle assemblies to Japanese luxury OEMs and North American EV platforms, establishing Stuttgart-Munich as the dominant supply corridor for smart access modules.
Germany
Luxury OEM procurement for capacitive flush-mount handles and KBA type-approval requirements for power-assisted mechanisms concentrate specification authority in Stuttgart and Munich component clusters, where suppliers scale precision casting capacity for 2026 BEV platform launches.
United States
Fleet operator consolidation in commercial vehicle segments and NHTSA exterior protrusion standards for breakaway force tolerances reshape procurement patterns, with Midwest manufacturing corridors serving domestic OEMs and Tier 1 integrators.
China
Yangtze River Delta injection molding scale for glass-reinforced polymer aftermarket replacements and MIIT electromagnetic compatibility mandates for connected vehicle architectures position the region as cost-optimized export supply.
Japan
Flagship EV platforms seeking cabin differentiation through gesture-based entry drive smart handle demand, with METI cybersecurity guidelines for keyless systems constraining firmware architecture choices for domestic deployment.
India
PLI scheme incentives attract handle tooling investments to Pune and Chennai manufacturing corridors, where export-oriented aftermarket supply targets European and North American collision repair channels.
Outside Door Handle Market Competitive Landscape
Player mix skews toward European precision metal formers with captive mechatronics capabilities and Asian scale manufacturers serving cost-optimized tiers. Market structure concentrates around three strategic archetypes: electronics-integrated system integrators, die-cast aluminum specialists, and polymer-focused aftermarket suppliers. Dominant competitive moves include backward integration into sensor module production and strategic partnerships for UWB digital key certification.
Within the electronics-integrated tier, Assa Abloy AB and dormakaba Holding AG exemplify the convergence of access control expertise with automotive qualification requirements, while Hoppe Holding AG anchors the precision metal forming archetype through established OEM supply relationships. These three entities represent distinct capability configurations: semiconductor integration, power-assisted mechanism R&D, and manufacturing scale respectively.
| Leading Market Players |
|---|
| Hoppe Holding AG |
| dormakaba Holding AG |
| Assa Abloy AB |
| Kuriki Manufacture Co. |
| Aarkay Vox |
| Allegion Plc |
| Emtek Products Inc. |
| West INX Ltd. |
| The Häfele Group |
| Others |
Value Network & Pricing Analysis
Fourteen-week die-cast aluminum lead times from Stuttgart suppliers concentrate pricing power among precision metal formers with captive foundry capacity, while downstream OEMs absorb cost pass-throughs through long-term offtake agreements. This inventory-to-pricing dynamic tightens most acutely for smart handle modules where semiconductor content locks in component-level pricing floors.
Pricing Analysis
Smart-to-mechanical pricing gaps span three technology generations, with capacitive modules commanding premium positioning over power-assisted mechanisms and legacy pull-lever designs. Three-tier pricing structure across premium, standard, and economy levels stratifies by semiconductor integration depth and KBA type-approval status. Cost compression in mid-volume Zamak die-cast tiers intensifies because LME zinc volatility squeezes margin predictability for Stuttgart component houses. Fleet procurement teams exhibit highest price sensitivity through standardized multi-brand specifications, while German luxury OEMs prioritize electromagnetic compatibility certification over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate semiconductor-intensive smart handle production, with Taiwan and South Korea fabrication bottlenecks forcing six-month die-bank commitments for capacitive sensing ICs. Geographic supply concentration centers on Germany, China, and Mexico for die-cast forming, with Yangtze River Delta injection molding serving cost-optimized aftermarket channels. Raw material dependencies rest on LME zinc pricing, high-purity aluminum ingot, and glass-reinforced polyamide compounds. Single-source vulnerability concentrates in NFC controller supply from Taiwanese foundries. Distribution runs through Tier 1 electronics integrators with captive mechatronics capabilities, bypassing traditional metal forming distributors for smart handle architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical-to-electronic substitution threatens legacy pull-lever suppliers as capacitive sensing displaces conventional actuation across premium platforms. Incumbents must defend hardware value capture against software-defined access platforms that redistribute margins toward semiconductor integrators.
For Market Incumbents: Fortify captive sensor module production through backward integration into thin-film deposition processes, eliminating dependency on external electronics houses for conformal coating. Secure KBA type-approval cycles early for power-assisted mechanisms ahead of 2026 BEV platform launches. Electromagnetic compatibility validation redundancy poses the critical threat, compressing program windows for suppliers without in-house chamber capacity.
For New Entrants and Emerging Players: Aftermarket firmware upgrade services represent the most penetrable white-space where incumbents under-serve aging fleet segments with legacy mechanical architectures. Target India's Pune manufacturing corridor for export-oriented replacement supply under PLI scheme incentives. Pursue direct-to-fleet technical sales bypassing traditional OEM tiering structures, leveraging standardized durability specifications from consolidated German leasing procurement offices.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mechatronics engineering talent scarcity constrains R&D team scaling across mid-cap metal formers. Acquisition targets center on precision die-cast specialists with nascent capacitive sensing capabilities and established Stuttgart OEM relationships. Monitor UWB digital key certification timelines as the inflection signal—early movers in smartphone pairing firmware capture disproportionate smart handle specification share.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Module Backward Integration | Captive thin-film deposition eliminates external electronics dependency for conformal coating compliance. |
| EMC Chamber Capacity Expansion | In-house electromagnetic compatibility validation compresses launch windows for 2026 BEV platforms. |
| UWB Firmware Certification Investment | Early smartphone digital key qualification secures specification share from METI cybersecurity mandates. |
| India PLI Corridor Manufacturing Footprint | Pune tooling investments target export-oriented aftermarket supply for North American collision repair. |
| Trivalent Chromium Coating Qualification | REACH sunset acceleration rewards early movers in hexavalent chromium alternatives for decorative finishes. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributors, and KBA type-approval officers, then refined through secondary validation. Primary fieldwork drew from vehicle production databases, IHS Markit registration data, SEC filings from listed component suppliers, and ECHA REACH authorization timelines. Bottom-up triangulation across die-cast aluminum capacity announcements and top-down reconciliation with vehicle parc age projections anchored volume estimates.
Variance decomposition across product type, material grade, end-user procurement authority, and installation channel shaped the analytical framework over the projection horizon. Segmentation modeling captured electronic complexity tiers from mechanical pull-lever through UWB-enabled keyless systems, with CAGRs derived from platform launch cadence and electrification penetration curves. Forecast inputs incorporated LME zinc price volatility bands and semiconductor fab capacity utilization from Taiwan and South Korea.
Underlying assumptions cover sustained BEV platform electrification roadmaps and REACH coating exemption timelines, with deviation risk concentrated in Taiwan semiconductor supply disruptions and German luxury OEM consolidation of smart handle suppliers. Revision becomes warranted when UWB digital key adoption crosses mass-market penetration thresholds or ECE R21 protrusion limits tighten beyond current breakaway geometry tolerances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Thailand Construction Chemicals Market
Building & Construction Materials
Plastic Roofing Tiles Market
Building & Construction Materials
Marble Market
Building & Construction Materials
Fire Rated Duct Market
Building & Construction Materials
Mosaic Tiles Market
Building & Construction Materials
Canada Facade Market
Building & Construction Materials
Israel Ceramic Tiles Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Masonry Sealers Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Pervious Concrete Market