
 North America Decks Market | 2026-2036
North America Decks Market Size, Share, and Industry Trends Forecast 2026-2036
North America Decks Market Insights
Composite decking formulation is narrowing the performance gap between synthetic boards and traditional lumber across North American job sites. Trex Company, Inc. leverages its proprietary shell technology to command premium positioning in the residential replacement cycle. AZEK Company, Inc. anchors its growth in the commercial and hospitality channels through capped polymer boards. Fiberon competes aggressively on price while sustaining quality certifications that appeal to contractor-specified projects.
Decks are load-bearing outdoor platforms, typically constructed from wood fibers, thermoplastic resins, or extruded aluminum, designed to extend usable living space and support furniture, foot traffic, and environmental loads. Composite materials now lead value creation in the material segment, as homeowners prioritize moisture resistance and reduced maintenance cycles over first-cost savings. The residential end-user category dominates volume, though the hospitality segment generates superior margins through custom design specifications and accelerated replacement schedules.
The EPA regulates preservative-treated wood under pesticide registration requirements, while the IRC and IBC establish structural load standards that govern deck engineering across U.S. jurisdictions. Canada’s CSA O86 and NBC provisions enforce parallel compliance burdens for cross-border suppliers. Stakeholders must monitor evolving state-level building code adoptions and material-specific carbon accounting rules that could reorder competitive positioning between wood, composite, and aluminum alternatives.
Market Dynamics
Residential renovation spending across the United States and Canada is compressing replacement cycles for outdoor living infrastructure, while EPA-treated wood regulations and state-level composite incentives actively restructure material procurement patterns among contractors and homeowners.
Growth Catalysts
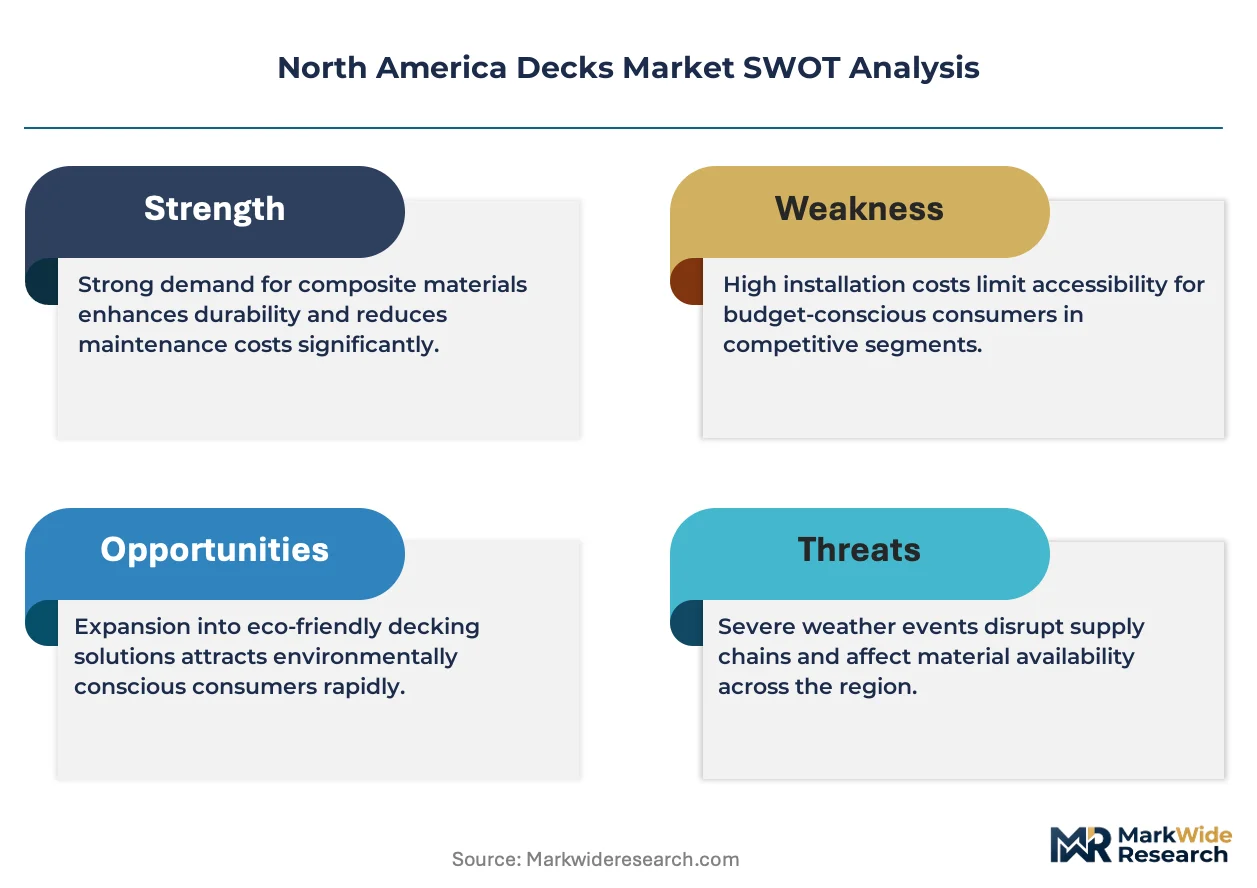
- State-level composite incentives:California and Florida tax credits for low-maintenance decking materials accelerate homeowner adoption of capped polymer boards over traditional lumber in renovation projects.
- Warm-climate suburban sprawl:Year-round construction feasibility in the southeastern United States sustains contractor backlog visibility and material demand continuity across seasonal cycles.
- IRC structural load standards:Updated International Residential Code provisions for deck engineering drive professional-grade material specification in permit-dependent jurisdictions.
Market Restraints
- Petrochemical input volatility:Thermoplastic resin prices tied to crude oil fluctuations compress margin stability for composite board manufacturers operating at fixed contract pricing.
- Western Canadian lumber concentration:SPF lumber supply bottlenecks from British Columbia mill curtailments create price pressure on treated wood alternatives competing for budget-conscious segments.
- Moisture barrier technical limitations:Uncapped composite boards in freeze-thaw climates exhibit surface degradation that constrains warranty coverage expansion in northern tier states.
Strategic Opportunities
- Underpenetrated Canadian prairie provinces:Saskatchewan and Manitoba deck penetration rates trail Ontario and British Columbia, presenting whitespace for contractor network expansion.
- Hospitality rooftop applications:Urban hotel and restaurant outdoor dining investments favor aluminum framing systems with composite surfacing for load-bearing elevated installations.
- Carbon accounting rule convergence:Emerging state-level embodied carbon disclosure requirements for construction materials favor recycled-content composite producers over virgin lumber suppliers.
Industry Challenges
- Certified installer skill gaps:Shortage of contractors trained in thermal expansion management for composite boards delays project completion in high-growth metropolitan markets.
- Multi-material integration complexity:Specifying compatible fastening systems across wood, composite, and aluminum substructures increases design liability exposure for residential architects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Decks Market |
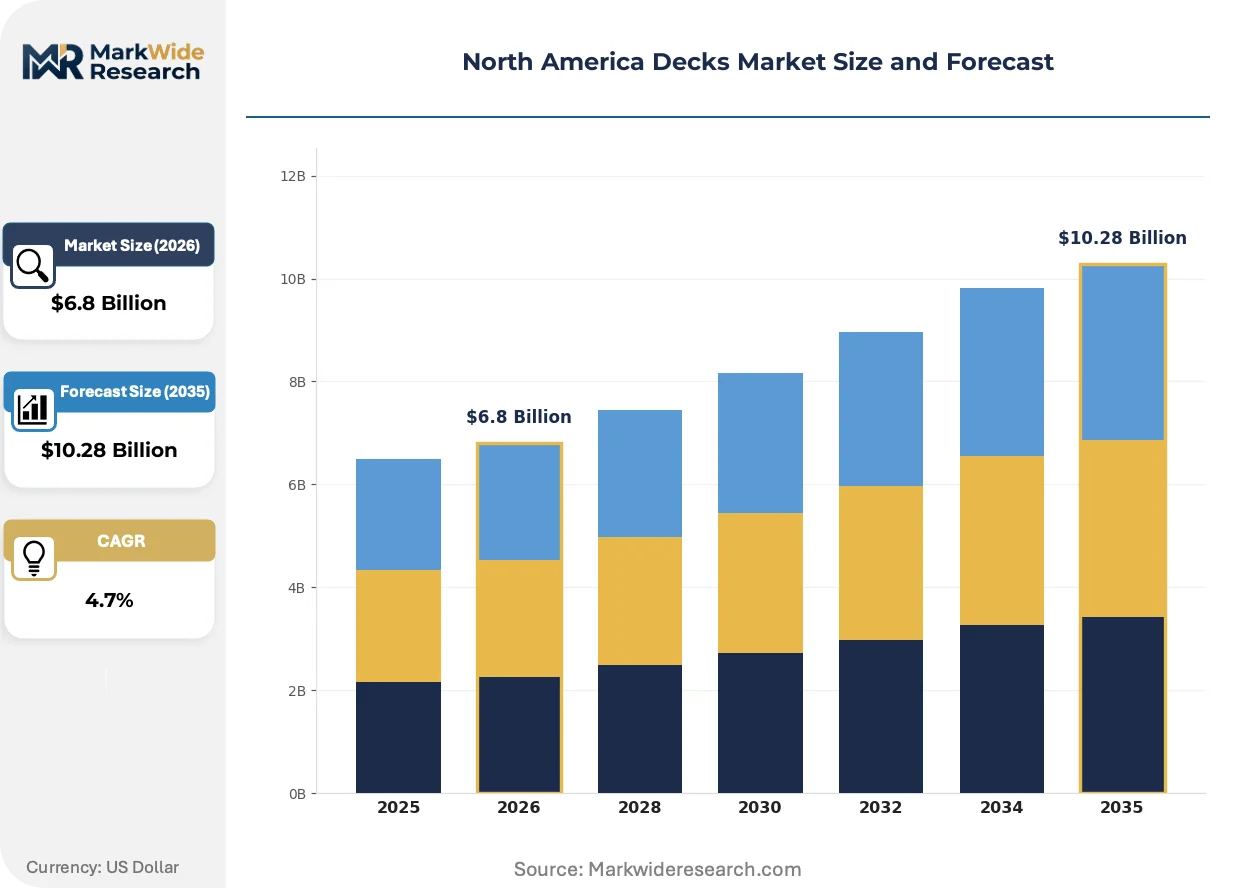
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Wood, Composite, PVC, Aluminum Design Type: Platform, Tiered, Raised, Freestanding End User: Residential, Commercial, Hospitality, Recreational Installation Type: Custom, Kit, Pre-Built, DIY |
| Companies Covered | Trex Company, Inc., AZEK Company, Inc., Fiberon, Cali Bamboo, LLC, Lumberock, Deckorators, Inc., Wahoo Building Products, MoistureShield, Louisiana Pacific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Decks Market Trends and Innovations
Material science advances and procurement digitization are restructuring how decking products reach end-users, with formulation improvements narrowing performance gaps while channel consolidation compresses distribution margins.
Co-extruded capped composite technology is collapsing the maintenance-cost differential that previously justified premium pricing for tropical hardwoods. Homeowners in Texas and Arizona markets are specifying these boards for second-home installations where service access is limited. The technology is collapsing replacement-cycle timelines from fifteen years toward twenty-five, compressing total-cost-of-ownership calculations in contractor sales presentations.
EPA pesticide registration requirements for copper-based wood preservatives are tightening disposal documentation for treated lumber removal. Contractors in coastal California counties now face extended permit timelines for demolition projects involving legacy arsenic-treated posts. The regulation is redirecting commercial specification toward polymer alternatives in marina and boardwalk applications subject to marine environment scrutiny.
Direct-to-builder digital procurement platforms are fragmenting traditional lumberyard channel control over contractor relationships. Large multi-location deck builders in Florida and Georgia are consolidating material purchasing through integrated vendor portals that bypass distributor markup layers. This channel shift concentrates volume with national composite brands offering consolidated logistics and project financing tools.
North America Decks Market Segmentation
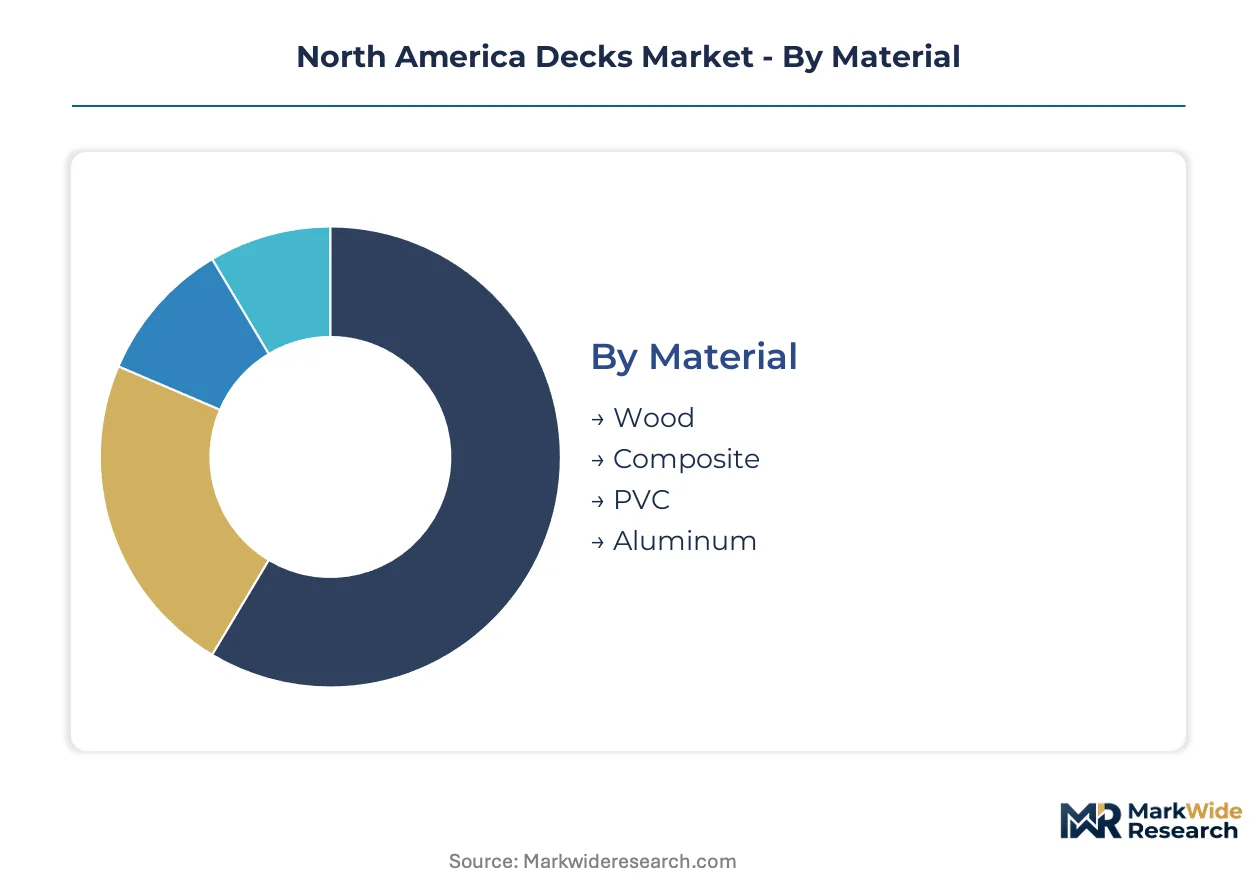
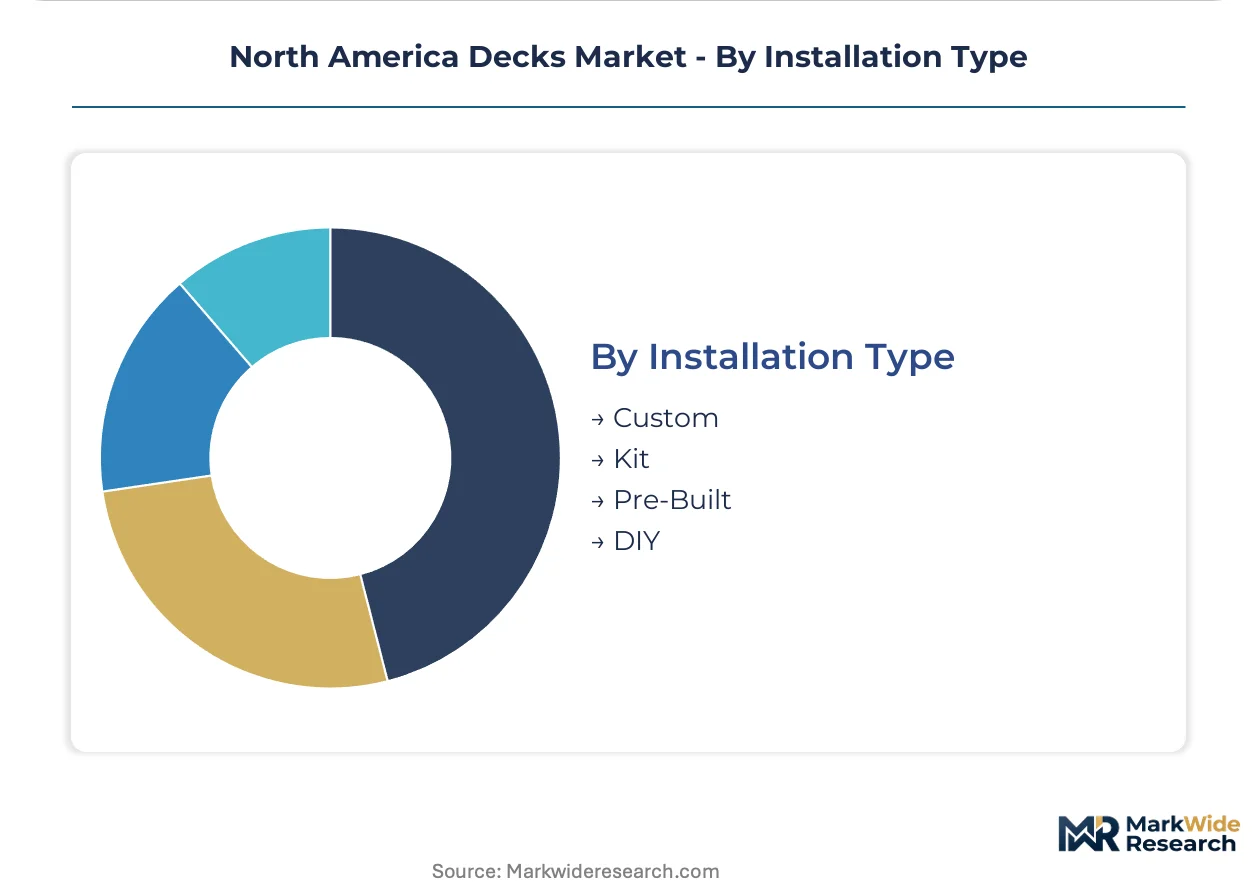
Material selection and installation method determine replacement frequency and margin structure across North American deck construction. Contractors segment procurement by lifecycle cost rather than first-cost alone, reshaping how suppliers position wood against synthetic alternatives.
Material:
Replacement cycles vary dramatically by material chemistry, with thermoplastic composites extending service intervals beyond traditional lumber by a decade or more.
- Wood:Pressure-treated southern yellow pine and western red cedar dominate existing stock. SPF lumber from British Columbia faces supply volatility that compresses contractor margins on budget residential projects.
- Composite:Wood-plastic formulations with co-extruded caps now command specification in high-moisture southeastern markets. Trex and Fiberon shell technologies reduce maintenance callbacks that plague natural lumber installations.
- PVC:Cellular vinyl boards deliver superior stain resistance for hospitality pool decks. Florida and Arizona resort properties specify these for chlorine and UV exposure environments.
- Aluminum:Extruded plank systems support elevated rooftop applications where structural load limits constrain traditional framing. Urban hotel developments in Toronto and Chicago favor these for fire-code compliance.
Wood anchors the volume base while composite gains share at the steepest rate.
Design Type:
Structural complexity drives engineering cost and permit timeline variation across metropolitan building departments.
- Platform:Single-level construction on grade represents the standard specification for suburban tract housing. Texas and Georgia builders complete these within standard residential permit windows.
- Tiered:Multi-level designs with integrated staircases require structural engineering sign-off in seismic zones. California jurisdictions extend review timelines for these configurations.
- Raised:Elevated structures on posts or piers dominate sloped lot developments in Appalachian and Pacific Northwest terrain. IRC lateral load provisions govern connection hardware specification.
- Freestanding:Detached platforms for pool houses and gazebos bypass dwelling attachment requirements. These accelerate permitting in municipalities with backlog congestion.
Platform designs generate the highest permit volume while raised configurations command premium structural engineering fees.
End User:
Customer type determines specification authority and payment security, with commercial channels demanding extended warranty terms.
- Residential:Single-family homeowners drive seasonal demand concentration in second-quarter construction windows. Replacement cycles compress when property turnover accelerates in Sun Belt markets.
- Commercial:Multi-family developers specify standardized materials across portfolio builds. National apartment operators in Dallas and Atlanta consolidate procurement through master service agreements.
- Hospitality:Hotel and restaurant outdoor dining investments favor rapid-install aluminum systems. Miami and Scottsdale properties prioritize accelerated project completion for seasonal revenue capture.
- Recreational:Marina and campground operators face EPA disposal constraints on legacy treated lumber. Boardwalk specifications increasingly default to composite for marine environment durability.
Residential channels absorb the greatest material volume while hospitality specifications expand most quickly.
Installation Type:
Delivery method shapes labor allocation and contractor risk exposure across project scales.
- Custom:Site-built framing with specified materials dominates high-value residential renovations. California and Florida coastal properties demand hurricane and seismic engineering customization.
- Kit:Pre-engineered component packages reduce field labor for regional production builders. National homebuilders in Phoenix and Charlotte standardize these for cycle-time compression.
- Pre-Built:Factory-assembled modules arrive crane-set for urban rooftop installations. Chicago and Vancouver high-rise developments specify these for logistics-constrained sites.
- DIY:Big-box retail channel serves homeowner self-installation in rural and exurban markets. These purchases concentrate in spring seasonal surges at Home Depot and Lowe's locations.
Custom installation retains the largest contractor labor allocation while kit solutions are climbing the fastest among production builders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian treated lumber shipments supply the United States renovation market through cross-border trade corridors concentrated in British Columbia and Quebec. Mexico's emerging deck construction sector absorbs composite materials from Texas and California distributors.
United States
Suburban sprawl across Texas and Florida sustains year-round deck construction demand unmatched by northern climates. EPA pesticide registration requirements for copper-based wood preservatives tighten disposal documentation for treated lumber removal projects. Atlanta and Dallas contractors consolidate procurement through direct-to-builder digital platforms that bypass traditional lumberyard channels.
Canada
Homeowners in Ontario and British Columbia prioritize moisture-resistant composite boards for extended service intervals in freeze-thaw cycles. CSA O86 and National Building Code provisions enforce structural load compliance burdens for cross-border suppliers accessing Canadian markets. Toronto high-rise developments specify aluminum plank systems for rooftop applications where fire codes constrain traditional framing materials.
Mexico
Rising residential construction in Nuevo León and Jalisco creates incremental demand for low-maintenance outdoor living infrastructure. The country's national building code regulator enforces seismic design standards that elevate engineered material specifications in permit-dependent jurisdictions. Mexico City metropolitan area hospitality investments favor rapid-install systems for accelerated project completion timelines.
North America Decks Market Competitive Landscape
On the supply side, the industry is consolidating around national composite brands with integrated logistics networks that compress distributor margins. Three strategic archetypes dominate: proprietary shell-technology specialists, price-competitive quality-certified producers, and commercial-hospitality channel anchors. Capacity expansion in southeastern manufacturing corridors and strategic partnerships with direct-to-builder procurement platforms represent the dominant competitive moves reshaping channel access.
Among publicly traded building materials companies, Trex Company, Inc. and AZEK Company, Inc. exemplify the technology-differentiated tier, while Fiberon occupies a position within the quality-certified value segment. These entities represent how formulation patents and shell-technology investments create defensive positioning against commodity lumber alternatives in residential replacement cycles.
| Leading Market Players |
|---|
| Trex Company, Inc. |
| AZEK Company, Inc. |
| Fiberon |
| Cali Bamboo, LLC |
| Lumberock |
| Deckorators, Inc. |
| Wahoo Building Products |
| MoistureShield |
| Louisiana Pacific Corporation |
| Others |
Pricing and Supply Chain Analysis
Petrochemical input volatility determines both the widening spreads between capped composite premium tiers and pressure-treated economy options and the southeastern manufacturing corridor concentration that dominates North American supply. This dual dependency creates margin compression for composite producers locked into fixed contractor pricing while lumber alternatives face British Columbia mill curtailment bottlenecks.
Pricing Analysis
Third-generation co-extruded capped composite technology commands 40-60% premiums over first-generation uncapped boards, while next-generation bio-polymer formulations are beginning to test price ceilings in coastal California markets. Three-tier pricing structure across premium shell-technology, standard capped composite, and economy pressure-treated lumber segments reflects after-sales service bundling and warranty length differentiation. Pricing pressure stems from SPF lumber supply volatility that forces composite producers to absorb resin cost spikes rather than pass through to renovation-contractor customers. Production homebuilders in Phoenix and Charlotte exhibit highest price sensitivity, while hospitality specifiers in Miami and Scottsdale prioritize lifecycle cost over first-cost.
Supply Chain Analysis
Upstream thermoplastic resin production concentrates in Texas and Louisiana petrochemical corridors, while wood fiber feedstock draws from southeastern pine plantations and British Columbia SPF forests. Raw material dependencies span polyethylene and polypropylene resins, wood flour from paper mill residuals, and copper-based preservative chemicals for treated lumber alternatives. Tariff exposure on Canadian lumber shipments creates single-source vulnerability for cross-border suppliers accessing U.S. renovation markets. Distribution runs through direct-to-builder digital platforms that are fragmenting traditional lumberyard channel control over contractor relationships in Florida and Georgia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against aluminum plank systems that are capturing elevated rooftop and fire-code-constrained applications in urban cores. Incumbents must navigate material science convergence that threatens to collapse the maintenance-cost justification for premium composite positioning.
For Market Incumbents: Pre-empt aluminum encroachment by accelerating co-extruded cap technology licensing to contractor networks, locking in specification authority before fire-code jurisdictions expand. Backward integration into southeastern wood fiber processing secures feedstock against British Columbia supply volatility. Certification investment in CSA O86 compliance opens Canadian prairie province expansion corridors.
For New Entrants and Emerging Players: Build out contractor training infrastructure in Saskatchewan and Manitoba where deck penetration trails Ontario by substantial margins. Hospitality rooftop applications in Toronto and Chicago present the most penetrable segment given aluminum's current supply constraints. Direct-to-builder procurement platform partnerships offer the cleanest go-to-market angle for bypassing established lumberyard relationships.
For Investors and Strategic Acquirers: Regional composite formulators with captive southeastern manufacturing and established contractor networks represent the most compelling acquisition target archetype for portfolio exposure to renovation cycle durability. Long-term viability hinges on carbon accounting rule convergence that favors recycled-content producers over virgin lumber suppliers. Watch for state-level embodied carbon disclosure mandates as the inflection indicator that reorders competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-Extruded Cap Technology Licensing | Extends specification control into fire-code jurisdictions where aluminum currently dominates. |
| Southeastern Wood Fiber Integration | Captive supply of pine residuals insulates margin from British Columbia SPF volatility. |
| CSA O86 Certification Investment | Unlocks contractor network expansion in underpenetrated Canadian prairie provinces. |
| Direct-to-Builder Platform Partnership | Bypasses lumberyard markup layers that compress composite producer margins. |
| Hospitality Rooftop Specification Capture | Accelerated installation timelines in Miami and Scottsdale properties drive premium pricing. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with deck contractor owners, lumberyard procurement managers, composite manufacturer sales directors, and hospitality development project managers. Secondary validation drew from EPA pesticide registration filings, CSA O86 technical standards, International Residential Code adoption tracking, and U.S. Census Bureau residential construction permit databases. Bottom-up project pipeline analysis triangulated against top-down material shipment estimates from cross-border trade corridors.
Calibration against historical replacement cycle data and permit issuance patterns anchored volume projections across the analysis window. Segmentation modeling incorporated material chemistry tiers, design type complexity, end-user category, and installation method dimensions. CAGRs derived from regression analysis of renovation spending correlation with housing turnover velocity and seasonal construction windows. Forecast inputs included state-level composite incentive program adoption curves and EPA-treated wood disposal regulation enforcement intensity.
Practitioners should monitor resin price volatility, British Columbia mill operating rates, and state carbon accounting rule proposals for early signals of forecast revision. Cross-checking against U.S. Census Bureau residential improvement spending surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Residential Elevator Market
Building & Construction Materials
North America Industrial Flooring Market
Building & Construction Materials
Fiberboard Ceiling Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Facade Anchor Systems Market
Building & Construction Materials
Europe AAC Blocks and Panels Market
Building & Construction Materials
Glue-Laminated Timber Market
Building & Construction Materials
North America Residential Water Heater Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Gutter and Downspout Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Europe Timber Construction Connectors Market
Building & Construction Materials
Modular Commercial Building System Market