
 Saudi Arabia Manufactured Homes Market | 2026-2036
Saudi Arabia Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Manufactured Homes Market Analytics
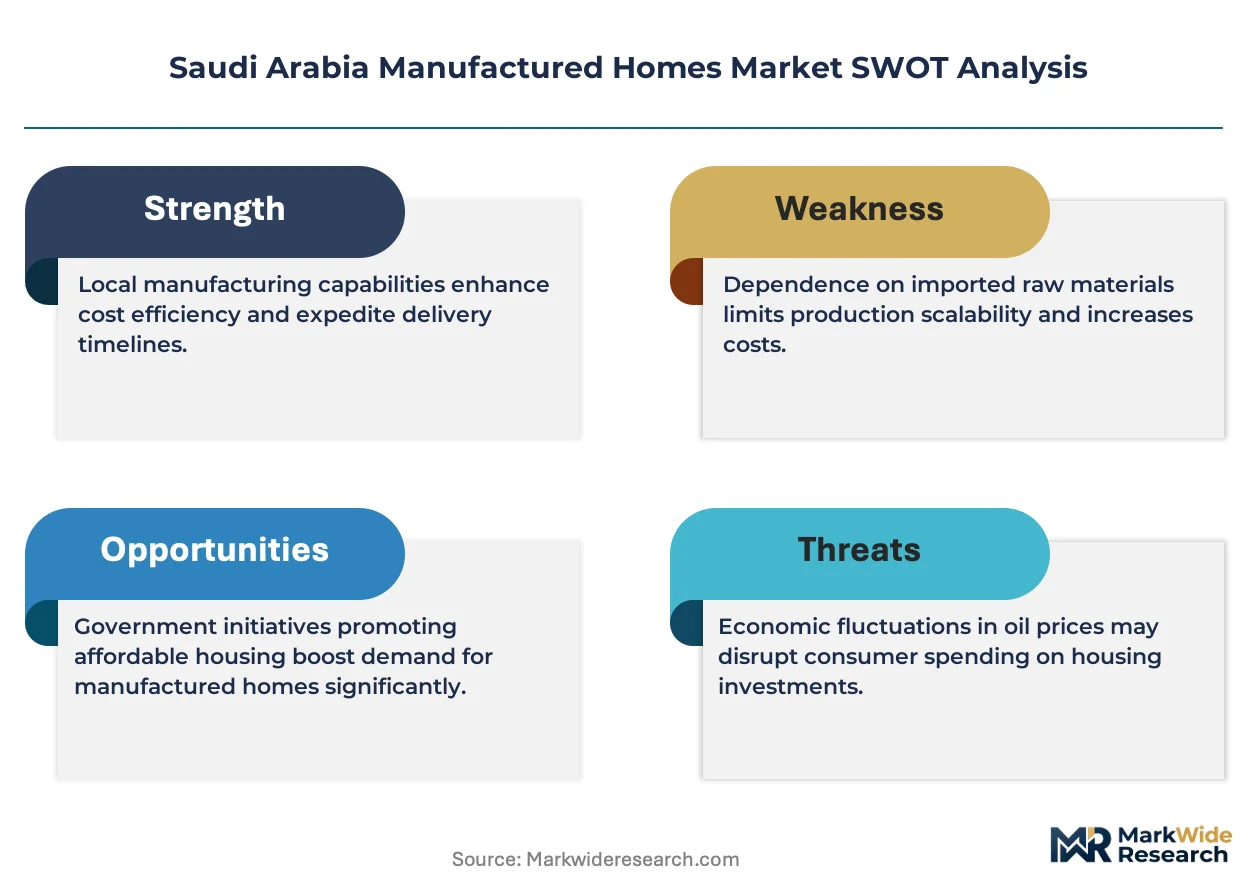
Aftermarket service revenue is rewriting value capture across the Saudi Arabia manufactured homes sector. Red Sea International leverages its installation and maintenance network to sustain recurring income beyond unit sales. Maani Ventures anchors its position through captive fabrication facilities in the Eastern Province. Spacemaker KSA differentiates via rapid-deployment project management for government contracts.
Manufactured homes are factory-built residential structures engineered to national building codes and transported to sites for final assembly, typically using steel framing or precast concrete panels to withstand Gulf climate conditions. Their primary purpose is delivering standardized housing units faster than conventional construction for workforce accommodation and mass residential programs. Multi-section homes and modular units command the deepest margin pools as developers prioritize scalable configurations over single-section models. Steel and composite materials are gaining share against traditional wood framing as thermal performance standards tighten across Saudi building codes.
Saudi Building Code requirements and SFDA material certification protocols shape product specifications and market access for domestic and imported manufacturers. Municipal zoning boards in Riyadh, Jeddah, and Dammam increasingly integrate modular construction into master-planned development approvals. Stakeholders must monitor how evolving energy-efficiency mandates and local-content regulations reshape supplier qualification criteria and procurement priorities.
Market Dynamics
Saudi Arabia's manufactured homes sector is restructuring around municipal code liberalization that now permits modular construction for public housing, creating a demand pull from government procurement channels previously closed to prefabricated units.
Growth Catalysts
- SFDA Material Certification Alignment:Streamlined protocols for steel and composite panel approvals are compressing product qualification timelines for domestic fabricators seeking public contracts.
- Riyadh-Dammam Corridor Clustering:Developer-led residential communities along this corridor are absorbing prefabricated units at volume, creating economies of scale for multi-section home production.
- Saudi Building Code Modular Integration:Municipal zoning boards in Riyadh, Jeddah, and Dammam are embedding modular construction into master-planned development approvals, normalizing factory-built units in urban housing stock.
Market Restraints
- Steel Input Cost Volatility:Thermal performance mandates are driving specification upgrades to higher-grade steel framing, exposing fabricators to commodity price swings in Gulf steel markets.
- Fabrication Capacity Concentration:Eastern Province captive facilities dominate domestic supply, creating geographic single-point risk for projects outside the Dammam industrial zone.
- Wood Framing Technical Limitations:Traditional wood construction faces tightening humidity and fire-resistance standards under Saudi Building Code Chapter 23, restricting its deployment in coastal and high-occupancy applications.
Strategic Opportunities
- Tabuk and Northern Borders Underpenetration:Neom-adjacent development zones lack established modular supply chains, creating first-mover positioning for rapid-deployment fabricators with government contracting experience.
- Energy-Efficiency Mandate Tailwinds:Evolving Saudi Energy Efficiency Center standards for building envelopes are favoring composite-panel manufacturers with pre-certified thermal performance ratings.
- Installation-Maintenance Service Unbundling:Aftermarket revenue streams from unit commissioning and lifecycle maintenance are opening margin pools beyond one-time sales for network-capable operators.
Industry Challenges
- Modular-Site Integration Skill Gaps:Shortages of certified technicians for final assembly and utility hookup are extending project timelines and inflating warranty exposure for developers.
- SFDA Certification Timeline Compression:Material approval backlogs for novel composite formulations are delaying product launches and freezing R&D pipelines for innovative suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Manufactured Homes Market |
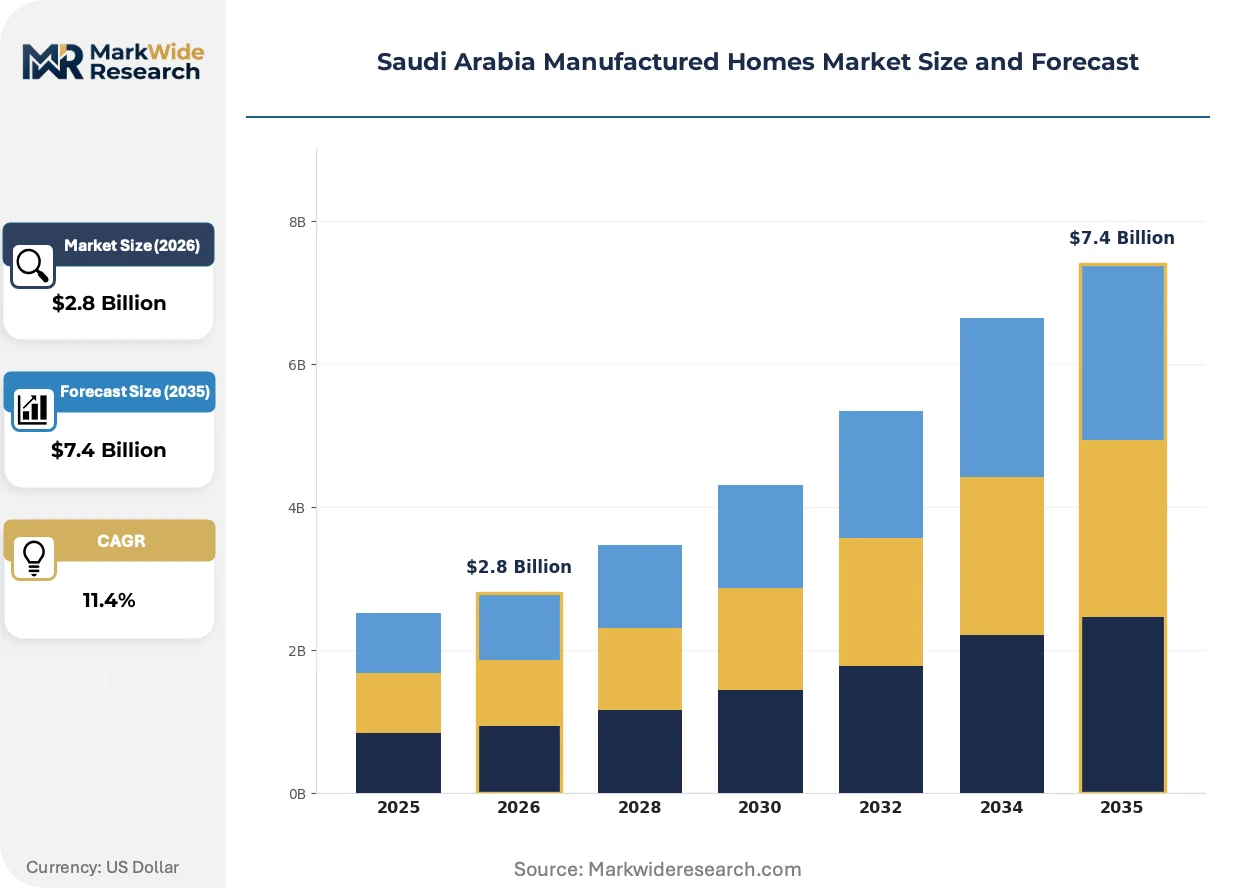
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Section Homes, Multi-Section Homes, Modular Homes, Park Model Homes Application: Residential, Commercial, Recreational, Emergency Housing Material: Wood, Steel, Concrete, Composite End User: Individuals, Developers, Government Agencies, Corporations |
| Companies Covered | Red Sea International, Maani Ventures, Spacemaker KSA, Aldamegh Portable House Factory, Speed House Group of Companies, TSSC Group, ISG Prefab, Karmod Prefabricated Technologies, BK Gulf, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Manufactured Homes Market Evolving Landscape
Factory-built housing in Saudi Arabia is pivoting from standardized workforce accommodation toward customizable residential configurations, driven by municipal code evolution and thermal performance mandates that favor advanced material systems.
Steel framing systems with integrated thermal breaks are migrating from industrial workforce camps to master-planned residential communities. Government housing agencies are specifying these systems for public projects under Riyadh's revised municipal codes. The shift is compressing demand for conventional wood-framed units in urban corridors where fire resistance and humidity tolerance carry premium weighting.
Saudi Building Code amendments governing modular construction are tightening energy-efficiency thresholds for factory-built envelope assemblies. Fabricators must now demonstrate compliance with Saudi Energy Efficiency Center thermal performance benchmarks to qualify for municipal permits. Multi-section residential developers in Jeddah and Dammam are responding by pre-certifying entire wall systems rather than component-by-component approval.
Developer procurement patterns are consolidating around turnkey installation contracts that bundle fabrication, transport, and site assembly. Single-source accountability is displacing fragmented subcontractor networks in Riyadh's public housing tenders. Government agencies now represent the fastest-growing buyer segment as procurement officers prioritize schedule certainty over lowest-unit-cost bidding.
Saudi Arabia Manufactured Homes Market Segmentation
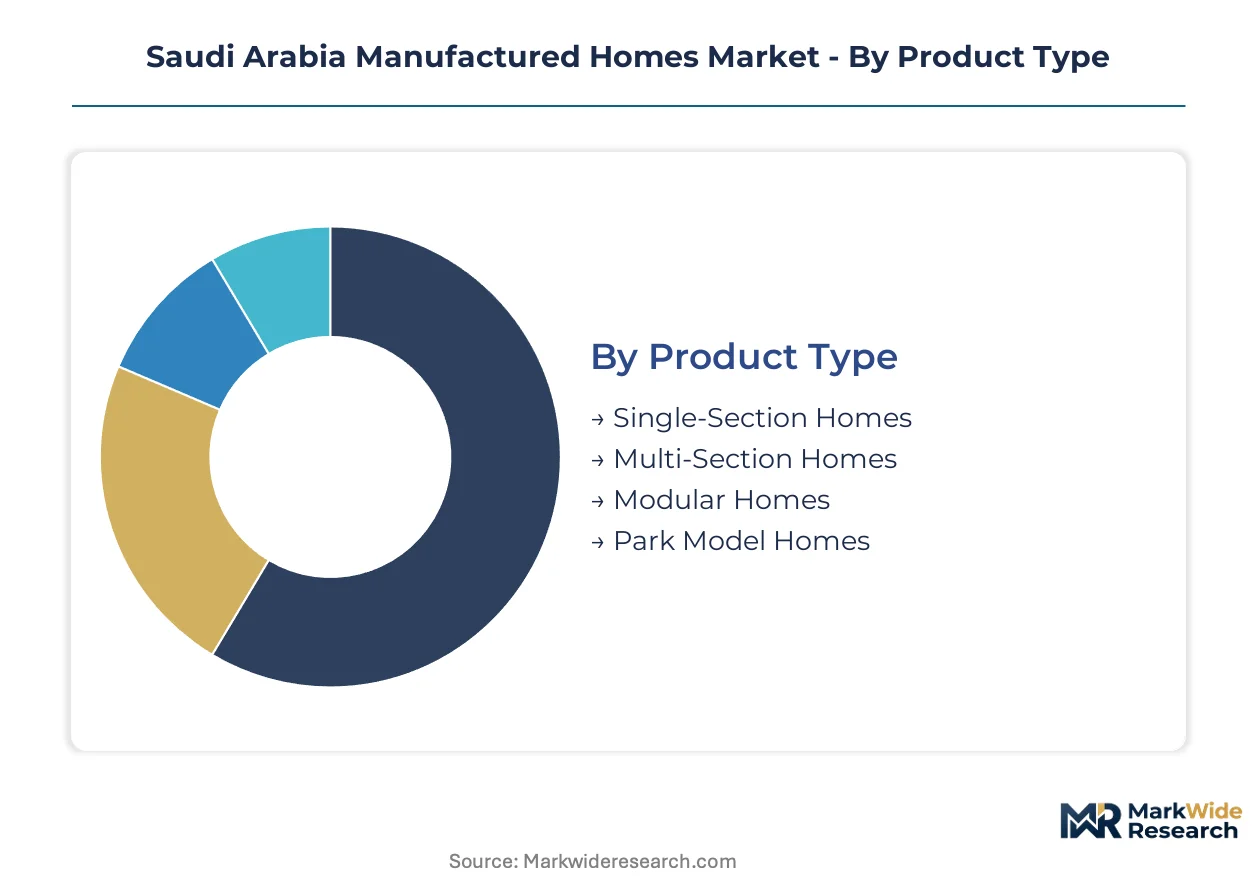
Saudi Arabia's manufactured homes market fragments across four distinct dimensions that shape procurement patterns and margin structures. Product type and material specifications dominate technical qualification for SFDA certification, while end-user identity determines contract scale and payment security.
Product Type:
Factory-built configurations span a use-case spectrum from compact workforce units to expandable family residences, with each format carrying distinct transportation logistics and site-assembly requirements.
- Multi-Section Homes:These units ship in two or more modules for on-site joining, enabling larger floor plans with complex room configurations. Developers across Riyadh-Dammam corridor residential communities specify these for middle-income housing projects where scale and customization intersect. Saudi Building Code Chapter 23 compliance for multi-module structural connections creates qualification barriers that favor established fabricators with certified assembly protocols.
- Modular Homes:Engineered to national building codes as permanent structures rather than transportable dwellings, these units integrate steel framing or precast concrete panels for Gulf climate durability. Government agencies in Riyadh's public housing procurement now specify modular construction under revised municipal codes that permit factory-built methods for permanent residential stock.
- Single-Section Homes:Compact factory-built units transported as complete structures, serving workforce accommodation camps in remote industrial zones.
- Park Model Homes:Smaller recreational units designed for seasonal occupancy, finding limited application in Saudi Arabia's permanent-housing dominant market.
Established volume favors multi-section configurations; emerging adoption favors modular homes as municipal codes normalize permanent factory-built housing.
Application:
Demand concentrates in deployment scenarios where speed of delivery outweighs architectural customization, with each application carrying distinct regulatory oversight and financing structures.
- Residential:Permanent housing for families and individuals, spanning master-planned communities and standalone units. Jeddah and Dammam municipal zoning boards embed modular residential construction into development approvals, with thermal performance mandates under Saudi Energy Efficiency Center standards shaping envelope specifications.
- Emergency Housing:Rapid-deployment units for displacement response and disaster relief, requiring minimal site preparation and utility infrastructure. Northern Borders and Tabuk regions adjacent to Neom development zones present first-mover opportunities for fabricators with government contracting experience and rapid-deployment logistics.
- Commercial:Factory-built structures for retail, office, and service applications, subject to commercial building code chapters.
- Recreational:Seasonal and leisure-oriented units for coastal and desert tourism developments, constrained by occupancy duration regulations.
Residential commands current procurement volume; emergency housing climbs the fastest as civil defense and humanitarian agencies build rapid-response inventories.
Material:
Specification choices pivot on thermal performance mandates and fire-resistance requirements that have tightened across Saudi Building Code amendments, displacing legacy material systems.
- Steel:Galvanized and cold-formed steel framing systems with integrated thermal breaks are migrating from industrial camps to master-planned residential communities. Higher-grade steel specifications for thermal performance expose fabricators to Gulf steel market commodity volatility.
- Composite:Engineered panel systems combining insulation cores with weather-resistant facings, gaining share as Saudi Energy Efficiency Center envelope standards tighten. Pre-certified composite wall systems accelerate municipal permitting versus component-by-component approval pathways.
- Concrete:Precast concrete panels for permanent modular structures, specified where acoustic separation and thermal mass carry premium weighting.
- Wood:Traditional framing faces tightening humidity and fire-resistance standards under Saudi Building Code Chapter 23, restricting deployment in coastal and high-occupancy applications.
Steel retains dominant share; composite materials gain fastest as energy-efficiency mandates reshape envelope specifications.
End User:
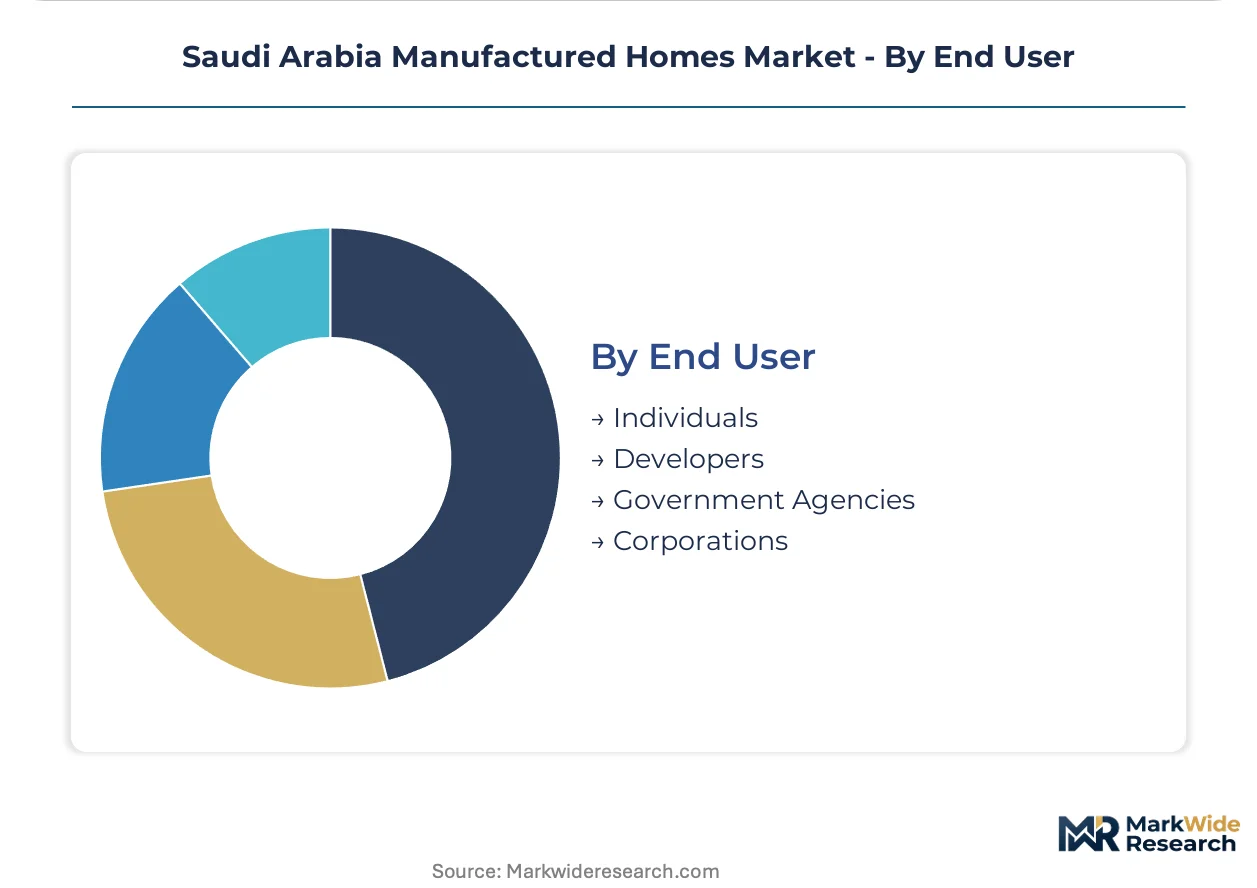
Buyer identity determines contract structure, with government procurement channels offering scale and payment security distinct from private-market transactions.
- Government Agencies:Municipal housing authorities and public project developers, now the expanding buyer segment as Riyadh's building codes permit modular construction for public housing. Procurement officers prioritize schedule certainty and single-source accountability over lowest-unit-cost bidding, consolidating tenders around turnkey installation contracts.
- Developers:Private residential and mixed-use project sponsors along Riyadh-Dammam corridor, absorbing prefabricated units at volume for master-planned communities. Developer procurement patterns favor bundled fabrication-transport-assembly contracts that displace fragmented subcontractor networks.
- Corporations:Industrial and resource sector employers sourcing workforce accommodation for remote operations.
- Individuals:Direct purchasers for private residential use, representing a thin market segment given Saudi Arabia's developer-dominated housing supply.
Developer volume anchors current production; government agencies expand most quickly as procurement channels open to factory-built methods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Saudi Arabia diverge sharply between the industrialized east and the emerging northwest corridor. Eastern Province demand centers on permanent modular housing for workforce communities, while Riyadh and Neom-adjacent zones prioritize rapid-deployment configurations for government housing programs.
Eastern Province
Dammam industrial zones anchor domestic fabrication capacity with captive steel-framing facilities serving Aramco-adjacent workforce camps. SFDA material certification protocols for higher-grade steel specifications are compressing qualification timelines for fabricators seeking municipal public housing tenders. The Dammam-Ras Tanura corridor concentrates multi-section home production for developer-led residential communities.
Riyadh
Municipal building code liberalization now permits modular construction for permanent public housing stock, redirecting government procurement toward factory-built methods. Revised zoning board approvals embed prefabricated units into master-planned developments across the metropolitan area. Northern Riyadh submarkets absorb turnkey installation contracts bundling fabrication, transport, and site assembly.
Western Region
Jeddah municipal zoning integrates modular residential construction into Red Sea coastal development approvals, with thermal performance mandates under Saudi Energy Efficiency Center standards shaping envelope specifications. Humidity-resistant composite panel systems are displacing wood-framed alternatives under Saudi Building Code Chapter 23 fire-resistance requirements. The King Abdullah Economic City corridor attracts pre-certified wall system fabricators.
NEOM Northwest
Tabuk and Northern Borders regions adjacent to Neom development zones lack established modular supply chains, creating positioning opportunities for rapid-deployment operators with government contracting experience. Civil defense and humanitarian agencies are building rapid-response inventories for emergency housing deployment. The coastal plain between Amlaj and Sharma presents first-mover terrain for network-capable fabricators.
Saudi Arabia Manufactured Homes Market Competitive Landscape
Capability concentration sits with established fabricators possessing certified assembly protocols and SFDA-aligned material approvals; scale advantage sits with developer-integrated operators controlling captive Eastern Province production capacity. The vendor base stratifies across three tiers: turnkey installation specialists, captive fabrication-integrated developers, and rapid-deployment government contractors. Consolidation pressure is intensifying as municipal tenders favor single-source accountability over fragmented subcontractor networks. Dominant competitive moves include backward integration into steel supply chains and geographic expansion toward underpenetrated northern corridors.
Within the turnkey installation tier, Red Sea International and Maani Ventures exemplify contrasting scale-coverage strategies. Red Sea International occupies a position emphasizing aftermarket service revenue through installation and maintenance network coverage. Maani Ventures anchors the captive fabrication archetype with in-house Eastern Province production capacity. Spacemaker KSA sits within the rapid-deployment specialist tier, representing government-contracting positioning for schedule-critical public projects.
| Leading Market Players |
|---|
| Red Sea International |
| Maani Ventures |
| Spacemaker KSA |
| Aldamegh Portable House Factory |
| Speed House Group of Companies |
| TSSC Group |
| ISG Prefab |
| Karmod Prefabricated Technologies |
| BK Gulf |
| Others |
Value Network & Pricing Analysis
The Dammam-Ras Tanura freight corridor carries steel framing and composite panels from Eastern Province fabrication zones to Riyadh-Dammam corridor developers, with transport cost dynamics amplifying pricing power for captive producers while compressing margins for non-integrated distributors serving remote northern deployments.
Pricing Analysis
Long-term offtake contracts dominate government procurement as Riyadh municipal housing authorities prioritize schedule certainty over spot-market flexibility. Pricing stratifies across premium, standard, and economy tiers based on SFDA certification tier and bundled installation-maintenance coverage. Cost compression in economy-tier single-section units is intensifying because Gulf steel market volatility feeds directly into framing material costs. Developer buyers along the Riyadh-Dammam corridor show lowest price sensitivity due to turnkey accountability requirements, while individual purchasers face acute budget constraints.
Supply Chain Analysis
Export-control regimes on advanced composite panel manufacturing equipment limit technology transfer from Germany and South Korea to Saudi fabricators, constraining domestic capacity expansion for energy-efficient envelope systems. Supply concentration rests on China for insulation core materials, the UAE for aluminum facing substrates, and domestic Eastern Province mills for galvanized steel framing. Single-source vulnerability runs through the Dammam industrial zone where captive fabrication facilities cluster. Distribution runs through developer-integrated logistics networks rather than independent wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's manufactured homes sector sits in early-cycle expansion as municipal code liberalization opens government procurement channels previously restricted to conventional construction methods.
For Market Incumbents: Pre-empt emerging rapid-deployment specialists by securing SFDA pre-certification for composite wall systems ahead of Saudi Energy Efficiency Center mandate tightening. Backward integration into steel supply chains defends margin position against Gulf commodity volatility. Eastern Province capacity holders should lock long-term offtake with Riyadh municipal authorities before northern corridor entrants establish positioning.
For New Entrants and Emerging Players: Pursue Tabuk and Northern Borders emergency housing contracts where established supply chains remain absent and civil defense agencies are building rapid-response inventories. Government contracting experience represents the most penetrable entry credential. Lead with rapid-deployment project management capabilities rather than fabrication scale.
For Investors and Strategic Acquirers: Saudi Building Code Chapter 23 amendments reshaping envelope material standards reshape the acquisition landscape toward composite-panel fabricators with pre-certified thermal performance ratings. Five-to-ten year viability favors operators with installation-maintenance service networks generating recurring revenue beyond unit sales. Watch for SFDA timeline compression on novel material approvals as the inflection signal for R&D pipeline viability.
| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Certification Pre-Investment | Accelerates municipal permitting timelines for composite envelope systems under Saudi Energy Efficiency Center standards. |
| Turnkey Installation Contracting | Consolidates single-source accountability that Riyadh government procurement officers now prioritize over fragmented subcontractor networks. |
| Backward Steel Supply Integration | Insulates margin structures from Gulf steel market commodity swings affecting higher-grade thermal break framing specifications. |
| Rapid-Deployment Capability Buildout | Positions operators for Neom-adjacent emergency housing tenders in Tabuk where supply chain infrastructure remains underdeveloped. |
| Aftermarket Service Network Expansion | Captures recurring revenue streams from unit commissioning and lifecycle maintenance beyond one-time manufactured home sales. |
Research Methodology
Initial hypotheses were tested against primary input from fabricated housing procurement officers at municipal housing authorities, project directors at developer-led residential communities, SFDA certification specialists, and Eastern Province plant operations managers, then refined through secondary validation against Saudi Building Code amendment records, Saudi Energy Efficiency Center thermal performance benchmarks, customs data on steel and composite material imports, and municipal zoning board approval databases. Bottom-up unit deployment estimates and top-down construction spending allocations were triangulated for convergence.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material specification, end-user category, and regional corridor. CAGRs were derived from installed base growth trajectories and replacement cycle analysis. Industry-specific forecast inputs included SFDA certification pipeline backlogs and Saudi Building Code enforcement timelines across Riyadh, Jeddah, and Dammam municipal jurisdictions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese composite panel exporters or accelerated Saudi Energy Efficiency Center mandate implementation would shift outcomes. Material shifts in SFDA material approval protocols or Gulf steel market structural pricing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Construction
Italy Manufactured Homes Market
Residential Construction
Prefabricated Homes Market
Residential Construction
Canada Residential Construction Market
Residential Construction
Qatar Residential Construction Market
Residential Construction
Japan Residential Construction Market
Residential Construction
US Residential Construction Market
Residential Construction
Europe Prefabricated Housing Market
Residential Construction
Austria Prefabricated Housing Market
Residential Construction
North America Residential Construction Market
Residential Construction
North America Prefabricated Housing Market
Residential Construction
Bathroom Remodeling Market
Residential Construction
UAE Manufactured Homes Market
Residential Construction
Residential Roofing Market
Residential Construction
UK Residential Construction Market
Residential Construction
Latin America Manufactured Homes Market
Residential Construction
Saudi Arabia Residential Construction Market