
 Precast Concrete Pile Market | 2026-2036
Precast Concrete Pile Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Concrete Pile Market Insights
Private developers is collapsing as public works authorities expand procurement for resilient transportation and energy infrastructure across North America and Europe. CEMEX leverages its vertically integrated cement-to-pile production network across Mexico and the southern United States. HeidelbergCement anchors European supply through specialized marine-grade pile formulations for North Sea installations. Tindall Corporation differentiates via custom-engineered precast systems for heavy industrial foundations in the US Midwest.
Precast concrete piles are reinforced or prestressed concrete structural elements manufactured in controlled factory conditions, typically cured to achieve compressive strengths exceeding 50 MPa before transportation and installation. These elements transfer structural loads through weak surface soils to deeper, competent bearing strata in bridge abutments, offshore platforms, and heavy industrial facilities. Circular piles dominate marine and waterfront applications where uniform bending resistance against multidirectional wave forces proves critical. Driven installation methods sustain the largest equipment and contractor base, though vibro and pressed techniques are gaining share in urban settings where noise and vibration restrictions constrain traditional impact hammers. Jacked piles command premium positioning for retrofit foundation strengthening beneath existing structures where settlement tolerance is minimal.
US infrastructure projects face Federal Highway Administration load-rating requirements and state-level DOT seismic design criteria that dictate pile reinforcement ratios and connection detailing. The European Construction Products Regulation mandates CE marking and EN 12737 conformity for precast concrete piles, with ECHA REACH compliance governing admixture chemistry in coastal exposure zones. China's NMPA-aligned construction material standards and MEE environmental discharge rules for precast manufacturing facilities shape domestic production economics. Stakeholders must monitor evolving carbon-border adjustment mechanisms and embodied-carbon disclosure rules that will restructure competitive positioning between regional and imported pile suppliers.
Market Dynamics
Carbon-border adjustment mechanisms and embodied-carbon disclosure mandates are restructuring competitive positioning between regional and imported pile suppliers, forcing manufacturers to reconfigure supply chains and certification portfolios.
Growth Catalysts
- Federal infrastructure spending:US DOT resilience grants and IIJA bridge replacement programs are accelerating pile procurement for transportation corridors across the Gulf Coast and Midwest.
- Marine-grade formulation advances:Specialized concrete mixes with corrosion-resistant admixtures are extending service life for North Sea and Yangtze River Delta installations exposed to chloride attack.
- GB 50007 foundation code revisions:China's tightened bearing capacity requirements are phasing out cast-in-situ alternatives in favor of factory-controlled precast systems.
Market Restraints
- Portland cement price volatility:Energy-intensive clinker production faces input cost pressure from natural gas and electricity tariffs, compressing margins for standardized pile grades.
- Heavy-lift equipment scarcity:Crane and pile driver availability concentrates with specialized contractors in Hamburg, Rotterdam, and Singapore, creating bottleneck risk for project timelines.
- Steel fiber substitution:High-strength driven steel piles retain share in seismic zones where ductility requirements exceed prestressed concrete performance envelopes.
Strategic Opportunities
- Carbon-capture concrete integration:Mineralized CO2 curing processes are creating premium product differentiation for suppliers serving EU Green Deal procurement criteria.
- Urban pressed-pile techniques:Vibration-free installation methods are opening retrofit foundation markets beneath existing industrial facilities in Germany's Rhine-Ruhr corridor.
- Offshore wind transition:Jacket foundation and monopile transition piece applications are absorbing precast pile expertise from declining oil platform markets.
Industry Challenges
- Prestressing tendon certification:EN 12737 and ACI 318 compliance timelines for post-tensioning systems extend qualification cycles for new product variants.
- Geotechnical modeling integration:Finite-element soil-structure interaction capabilities remain scarce among mid-tier foundation designers, constraining value-engineering penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Concrete Pile Market |
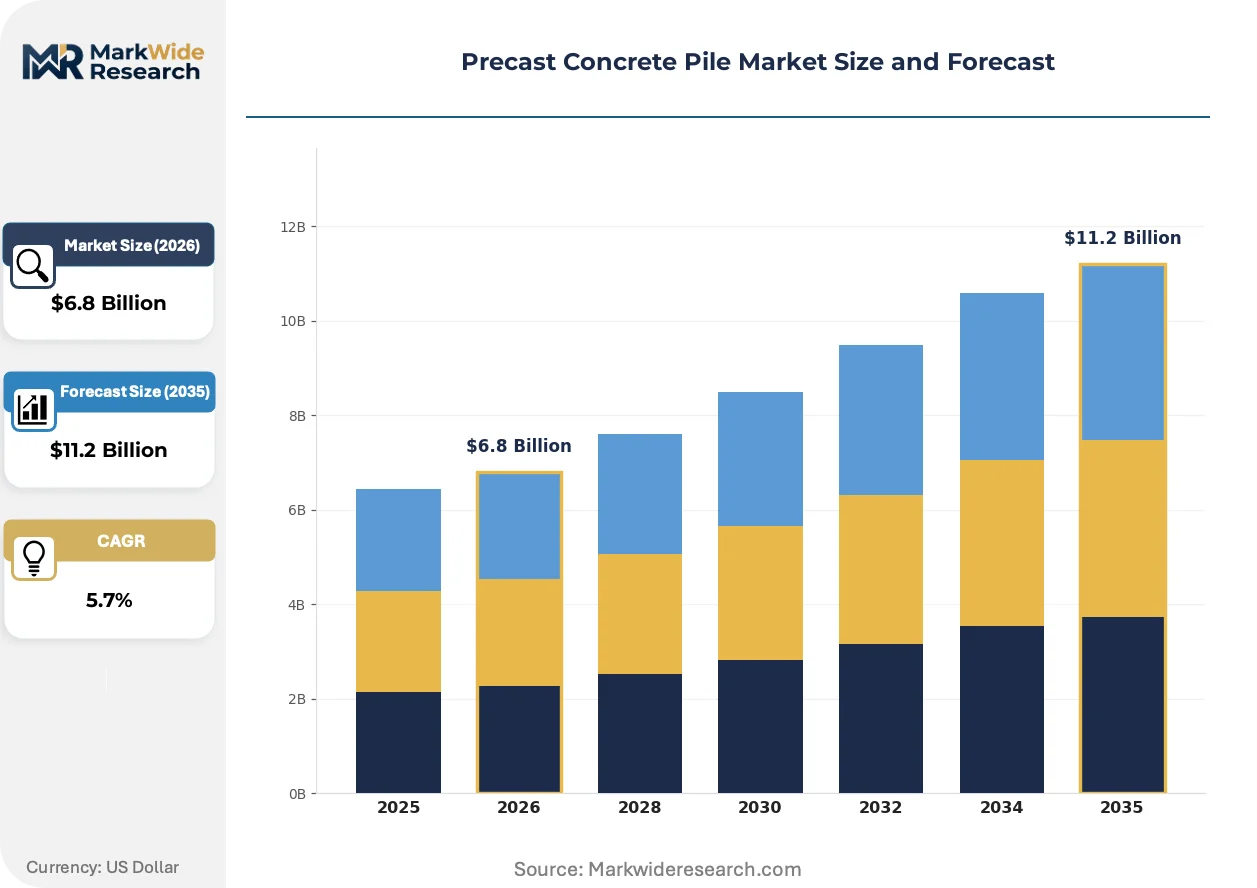
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square Piles, Circular Piles, H-Piles, Pipe Piles, U-Piles Installation Method: Driven, Bored, Jacked, Vibro, Pressed Application: Bridge Construction, Marine Structures, Industrial Foundations, Power Plants, Commercial Complexes End User: Construction Contractors, Infrastructure Developers, Engineering Firms, Public Works Authorities, Private Developers |
| Companies Covered | Forterra, Holcim, Oldcastle Infrastructure, HeidelbergCement, CRH, Spancrete, CEMEX, Gulf Precast, Tindall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Concrete Pile Market Trends and Innovations
Digital fabrication and low-carbon material science are converging to transform how precast piles are engineered, certified, and procured across heavy infrastructure value chains.
Self-compacting concrete with optimized rheology is fragmenting traditional vibration-casting workflows in controlled factory environments. Marine contractors in the Netherlands and Denmark are adopting these mixes for complex reinforcement cages where manual consolidation proves unreliable. The technology is fragmenting equipment investment patterns, as producers redirect capital from external vibrators toward precision pumping and formwork automation systems.
REACH-compliant admixture disclosure requirements are tightening formulation transparency for coastal exposure applications. ECHA enforcement of substance-of-very-high-concern screening is forcing reformulation of traditional corrosion inhibitors and air-entraining agents. German and Belgian manufacturers are responding fastest, leveraging in-house chemistry capabilities to secure CE marking ahead of competitors dependent on third-party blenders.
Performance-based foundation design contracts are displacing prescriptive specification procurement in public-private partnership structures. Dutch port authorities and Danish energy developers now transfer subsurface risk to contractors through lump-sum geotechnical packages. This shift concentrates most visibly in North Sea offshore wind and Hamburg port modernization programs, where design-build entities absorb pile quantity and installation method risk.
Precast Concrete Pile Market Segmentation
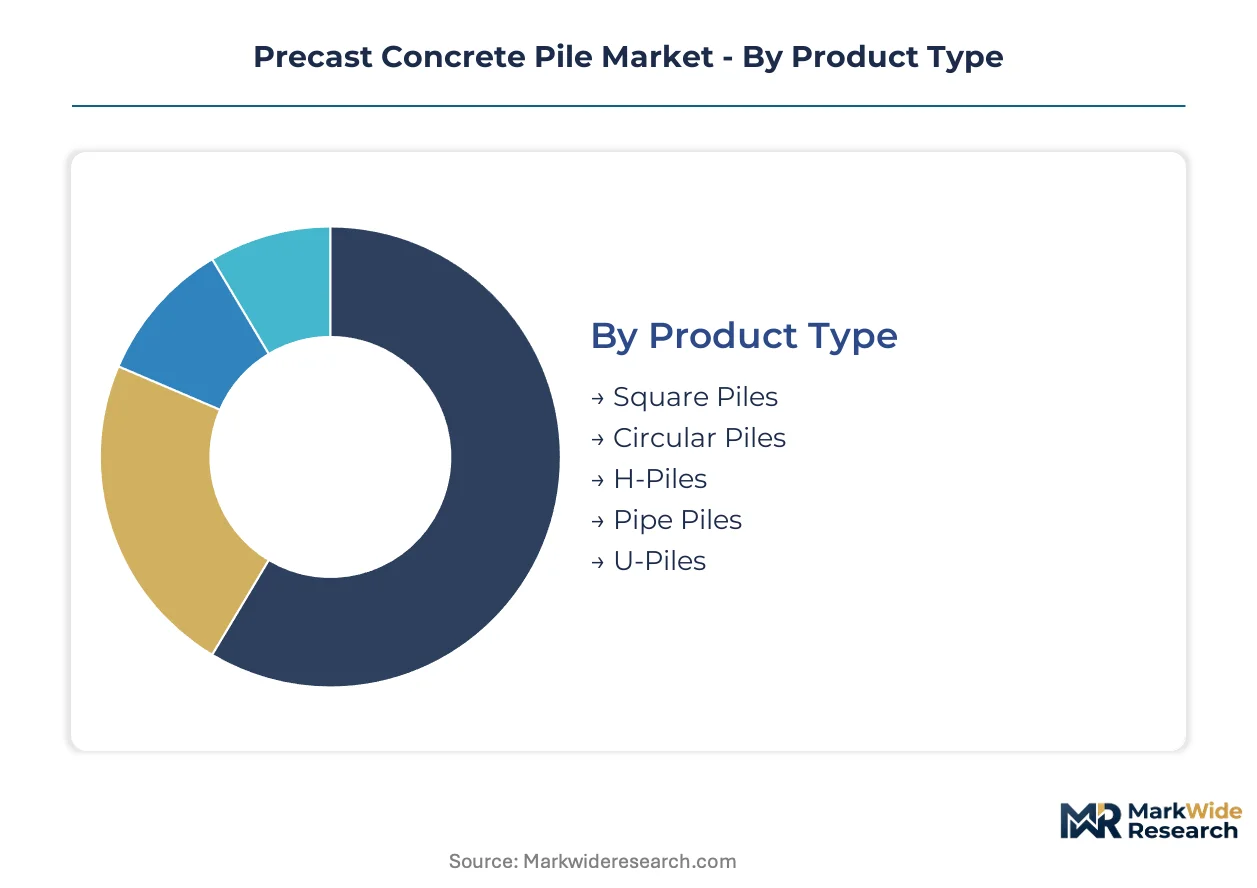
Precast concrete pile manufacturers configure production lines around dimensional standards and installation physics that dictate formwork investment, curing cycles, and transportation logistics. Segment-level margin capture depends on matching product geometry to soil conditions and regulatory load requirements across specific infrastructure verticals.
Product Type:
Margins concentrate in specialized geometries requiring custom formwork and prestressing bed configurations that limit competitor replication.
- Circular Piles:Uniform cross-sections deliver consistent bending resistance against multidirectional wave forces in marine environments. Hamburg port modernization and Yangtze River Delta bridge piers specify these sections for chloride-exposure durability under Eurocode 7 and GB 50007 bearing capacity benchmarks.
- Square Piles:Flat faces simplify connection detailing with cap beams and pile caps in building foundations. German industrial facilities in the Rhine-Ruhr corridor favor these for pressed-pile retrofit installations where vibration restrictions apply.
- H-Piles:Composite steel-concrete sections suit heavy vertical loads with minimal lateral constraints. These configurations appear in US Gulf Coast petrochemical foundations.
- Pipe Piles:Hollow cores reduce mass for long-distance marine transport and offshore platform jacket legs. North Sea wind transition pieces utilize these specifications.
- U-Piles:Channel profiles enable sheet-pile wall configurations for waterfront retention. Dutch and Belgian coastal defense projects specify these for interlocking barrier systems.
Circular piles hold installed capacity. Square piles are rotating up the share rankings.
Installation Method:
Equipment specialization and contractor certification requirements create tiered pricing power across techniques.
- Driven:Impact hammers deliver rapid penetration through dense strata with established contractor networks. US Federal Highway Administration load-rating protocols and state DOT seismic criteria sustain demand for this method across Midwest bridge replacement corridors.
- Pressed:Hydraulic jacking eliminates vibration for urban retrofit foundations beneath operational industrial facilities. Germany's pressed-pile specialists command premium positioning in Rhine-Ruhr corridor foundation strengthening where settlement tolerance approaches zero.
- Bored:Rotary drilling accommodates variable depths with minimal ground disturbance. These techniques suit mixed soil profiles in Chinese Yangtze River Delta infrastructure.
- Jacked:Precise load control enables underpinning of existing structures. These methods absorb precast pile expertise for commercial complex expansions.
- Vibro:High-frequency oscillation reduces soil resistance during penetration. Urban restrictions in Hamburg and Rotterdam constrain deployment despite faster cycle times.
Driven installation holds installed capacity. Pressed techniques are rotating up the share rankings.
Application:
Project scale and design-build risk transfer patterns determine procurement concentration across end-use verticals.
- Marine Structures:Chloride exposure demands specialized admixture formulations and dense concrete cover. North Sea offshore wind jacket foundations and Hamburg port modernization programs absorb premium marine-grade pile production from REACH-compliant manufacturers.
- Bridge Construction:Seismic design criteria and scour protection requirements dictate reinforcement ratios and connection detailing. US DOT resilience grants and IIJA programs accelerate pile procurement for Gulf Coast and Midwest transportation corridors.
- Industrial Foundations:Heavy equipment loads and vibration isolation specifications favor prestressed systems. German chemical processing facilities specify these for dynamic load distribution.
- Power Plants:Turbine and transformer foundations require precise settlement control. These applications concentrate in coastal zones with cooling water access.
- Commercial Complexes:High-rise building cores and podium structures utilize precast piles where bearing strata sit at depth. China's GB 50007 revisions phase out cast-in-situ alternatives in urban centers.
Marine structures hold installed capacity. Bridge construction is rotating up the share rankings.
End User:
Procurement authority and risk appetite separate price-takers from specification-setters in contract structures.
- Public Works Authorities:Federal and state agencies mandate prescriptive standards with extended qualification timelines. US DOT and German federal transport authorities dominate transportation corridor procurement with resilience-focused technical specifications.
- Infrastructure Developers:Design-build entities absorb geotechnical risk through lump-sum foundation packages. Dutch port authorities and Danish offshore wind developers concentrate demand in performance-based contracting structures.
- Construction Contractors:Equipment ownership and installation expertise create vertical integration incentives. Specialized pile driving contractors in Rotterdam and Singapore control crane and hammer availability.
- Engineering Firms:Geotechnical design capabilities influence pile quantity and specification optimization. Finite-element soil-structure integration remains scarce among mid-tier designers.
- Private Developers:Commercial real estate sponsors prioritize schedule certainty over lowest unit cost. These actors retreat as public infrastructure expands.
Public works authorities hold installed capacity. Infrastructure developers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta bridge corridor, Hamburg's deep-water port modernization, and US Gulf Coast energy infrastructure anchor precast concrete pile demand across three continents. Federal resilience grants and tightening foundation codes in each jurisdiction are accelerating specification upgrades for factory-cured pile systems.
United States
Bridge replacement corridors across the Gulf Coast and Midwest absorb driven pile volumes under Federal Highway Administration load-rating protocols. The Infrastructure Investment and Jobs Act channels DOT resilience grants toward transportation foundations in seismic zones. Houston petrochemical complexes and Louisiana LNG export terminals specify marine-grade precast systems for cooling water intake structures.
Germany
Rhine-Ruhr industrial retrofit projects favor pressed-pile techniques beneath operational chemical processing facilities where vibration tolerance is minimal. Eurocode 7 geotechnical standards and ECHA REACH compliance for coastal admixtures shape procurement specifications. Hamburg's port modernization program concentrates demand for corrosion-resistant circular piles in North Sea exposure conditions.
China
Yangtze River Delta infrastructure corridors phase out cast-in-situ alternatives under revised GB 50007 foundation code bearing capacity requirements. Shanghai-Ningbo bridge piers and Nantong port expansions specify factory-controlled precast systems. MEE environmental discharge rules for manufacturing facilities constrain domestic production economics in coastal provinces.
Netherlands
Rotterdam port expansion and Maasvlakte offshore wind staging areas drive marine-grade pile procurement under performance-based design-build contracts. Dutch coastal defense projects specify U-pile sheet wall configurations for interlocking barrier systems. REACH-compliant admixture disclosure requirements favor domestic manufacturers with in-house chemistry capabilities.
United Arab Emirates
NEOM linear city foundations and Red Sea coastal tourism infrastructure specify high-capacity precast piles for marine exposure conditions. Dubai's port modernization and Abu Dhabi industrial zones absorb Gulf Precast production from regional fabrication hubs. The country's national construction material standards emphasize durability certification for chloride-exposure applications.
Precast Concrete Pile Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base concentrates around vertically integrated cement producers and regional precast fabricators with specialized formwork capabilities. Three archetypes dominate: multinational building materials conglomerates with captive pile production, mid-sized precast specialists with custom engineering services, and port-proximate marine contractors with heavy-lift equipment ownership. Capacity expansion and carbon-curing technology licensing represent the dominant competitive moves.
Among multinational building materials conglomerates, CEMEX and HeidelbergCement exemplify scale-driven archetypes with integrated cement-to-pile production networks spanning multiple continents. Tindall Corporation occupies a position within the custom-engineered precast specialist tier, representing private fabricators that differentiate through project-specific foundation design capabilities rather than commodity volume.
| Leading Market Players |
|---|
| Forterra |
| Holcim |
| Oldcastle Infrastructure |
| HeidelbergCement |
| CRH |
| Spancrete |
| CEMEX |
| Gulf Precast |
| Tindall Corporation |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day curing cycles for high-strength precast concrete piles concentrate inventory carrying costs with vertically integrated cement producers, amplifying pricing power for CEMEX and HeidelbergCement against regional fabricators dependent on spot-market clinker purchases. This lead-time rigidity reinforces volume-tiered contracting structures where public works authorities lock in multi-year offtake agreements at cost-plus benchmarks, while private developers absorb spot-price volatility for project-specific deliveries.
Pricing Analysis
Volume-discount tiering structures separate marine-grade certified piles from standard highway foundation grades and economy-tier building applications. Price differentiation hinges on corrosion-resistant admixture certification under ECHA REACH compliance and prestressing tendon qualification timelines under EN 12737. Cost compression in economy-tier square piles is intensifying because Portland cement input costs track natural gas and electricity tariff volatility. Public works authorities with federal resilience grant backing exhibit lowest price sensitivity, while private commercial developers facing construction loan carry costs prioritize schedule certainty over unit-cost optimization.
Supply Chain Analysis
Just-in-time curing-bed scheduling dominates among European and Chinese producers with captive cement kilns, while North American specialists maintain strategic stockpiles of prestressing strand and corrosion inhibitors to hedge against supply interruptions. Geographic supply concentration centers on Mexico and the southern United States for CEMEX, Germany and the North Sea corridor for HeidelbergCement, and coastal Chinese provinces for domestic producers serving Yangtze River Delta infrastructure. Raw material dependencies draw from clinker production, high-tensile steel strand for post-tensioning systems, and REACH-compliant chemical admixtures. Single-source vulnerability concentrates in specialized marine-grade admixture formulation capabilities held by German and Belgian manufacturers. Distribution runs through project-specific direct delivery from fabrication yards to construction sites, with heavy-lift crane availability constraining last-mile logistics in Rotterdam, Hamburg, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Performance-based foundation design contracts are transforming precast concrete pile procurement into a platform ecosystem where geotechnical risk transfer and carbon-credential interoperability determine vendor selection, mirroring shifts already visible in Dutch port authority and Danish offshore wind lump-sum contracting structures.
For Market Incumbents: Fortify backward integration into clinker production and captive admixture chemistry capabilities to defend margin position against carbon-border adjustment mechanisms that disadvantage importers lacking embodied-carbon disclosure infrastructure. Prioritize CE marking and EN 12737 certification bed expansion in Hamburg and Rotterdam corridors where marine-grade specification premiums concentrate. Carbon-capture concrete curing licensing represents the critical R&D lever for EU Green Deal procurement compliance. For New Entrants and Emerging Players: Urban pressed-pile retrofit services beneath operational industrial facilities in Germany's Rhine-Ruhr corridor expose a service-layer gap where incumbents under-serve vibration-sensitive foundation strengthening demand. Target this segment through equipment-light hydraulic jacking partnerships with specialized contractors rather than capital-intensive greenfield fabrication. Carbon-credential verification and embodied-carbon audit services offer the most penetrable go-to-market angle for design-build entities facing disclosure mandates. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across carbon-capture curing technology and automated self-compacting concrete pumping systems, favoring acquisition targets with existing formwork automation and in-house chemistry capabilities over commodity volume players. Five-to-ten-year viability hinges on positioning for EU Green Deal and Infrastructure Investment and Jobs Act procurement criteria that privilege low-carbon verified supply chains. The signal to watch is carbon-border adjustment mechanism implementation timelines that restructure import competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Capture Curing Licensing | Mineralized CO2 processes unlock EU Green Deal procurement preference in Hamburg port modernization. |
| Backward Integration into Clinker | Captive cement production insulates HeidelbergCement and CEMEX from energy tariff volatility compressing margins. |
| Pressed-Pile Equipment Partnerships | Vibration-free installation capabilities open Rhine-Ruhr retrofit markets beneath operational chemical facilities. |
| REACH-Compliant Admixture Expansion | In-house chemistry capabilities secure CE marking ahead of competitors dependent on third-party blenders. |
| Performance-Based Design-Build Contracting | Lump-sum geotechnical risk transfer concentrates demand with contractors absorbing pile quantity and installation method risk. |
Research Methodology
Desk research of Eurocode 7 technical committees, ECHA REACH substance databases, and GB 50007 foundation code revision documentation preceded structured interviews with geotechnical engineering directors, port authority procurement officers, precast fabrication plant managers, and heavy-lift marine contractors. Primary fieldwork with foundation designers in Rotterdam, Hamburg, and Shanghai validated secondary trade data on prestressing tendon supply and admixture formulation capabilities. Bottom-up project pipeline analysis across US DOT resilience grants, Dutch port expansion programs, and Yangtze River Delta bridge corridors triangulated against top-down cement consumption and precast capacity estimates.
Variance decomposition across installation method, product geometry, and end-use verticals shaped the analytical framework for volume and value outputs across the projection horizon. Segmentation dimensions modeled encompass driven versus pressed versus bored installation physics, circular versus square versus pipe pile configurations, and marine structure versus bridge construction versus industrial foundation applications. CAGRs derived from project-level procurement timelines and foundation code implementation schedules, with Federal Highway Administration load-rating protocol adoption curves and China's GB 50007 bearing capacity phase-out timelines serving as industry-specific demand inflection inputs.
Underlying assumptions cover continued federal infrastructure spending authorization, ECHA enforcement trajectory for substance-of-very-high-concern screening, and MEE environmental discharge compliance costs for Chinese coastal producers, with deviation risk concentrated in carbon-border adjustment mechanism implementation timing and heavy-lift equipment availability bottlenecks in specialized contractor markets. Revision becomes warranted when EU Green Deal procurement criteria penetration or US IIJA program reauthorization crosses thresholds that restructure competitive positioning between regional and imported pile suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Angular Rubber Expansion Joints Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Precast Concrete Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Europe I-Joist Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Dimension Stone Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Global Cool Roofs Market