
 Concrete Reinforcing Fiber Market | 2026-2036
Concrete Reinforcing Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Reinforcing Fiber Market Intelligence
The shift toward direct sales channels to major construction and precast concrete producers is reconfiguring the traditional distributor-led model. This dynamic favors suppliers with extensive technical support and logistical capabilities. Bekaert leverages its deep expertise in steel fibers to dominate high-specification infrastructure projects. Sika AG differentiates through its broad portfolio of chemical admixtures, while BASF SE competes on material science innovation in synthetic fibers.
Concrete reinforcing fibers are short, discrete filaments mixed into concrete to provide three-dimensional reinforcement. These fibers, typically made of steel, glass, or synthetic polymers, improve toughness and control plastic shrinkage cracking. Synthetic fibers, particularly polypropylene and macro-synthetic types, represent the fastest-growing fiber type segment due to their corrosion resistance and ease of handling. In terms of application, demand for fibers in shotcrete and precast elements is expanding faster than in traditional flooring applications.
Product performance and market access are governed by standards like ASTM International C1116 in the United States and the CE marking framework under EN 14889 in Europe. These regulations establish minimum performance criteria for fibers used in structural and non-structural applications. The key decision for specifiers and engineers is now balancing initial material cost against long-term durability and life-cycle performance benefits.
Market Dynamics
The imperative to build more resilient and sustainable infrastructure is the central force shaping the concrete reinforcing fiber market. Performance-based building codes and national decarbonization targets are compelling a shift away from traditional reinforcement methods toward advanced material solutions.
Growth Catalysts
- Sustainability Mandates:The EU Green Deal and similar global initiatives promote materials that extend infrastructure service life and reduce the carbon footprint of concrete, creating a direct pull for reinforcing fibers.
- Infrastructure Expansion:Large-scale transportation and utility projects in India and Southeast Asian nations require advanced concrete solutions to meet aggressive construction timelines and durability specifications.
- Material Advancement:The development of high-performance macro-synthetic fibers provides a corrosion-resistant alternative to steel, particularly for slabs-on-ground, precast elements, and marine structures.
Market Restraints
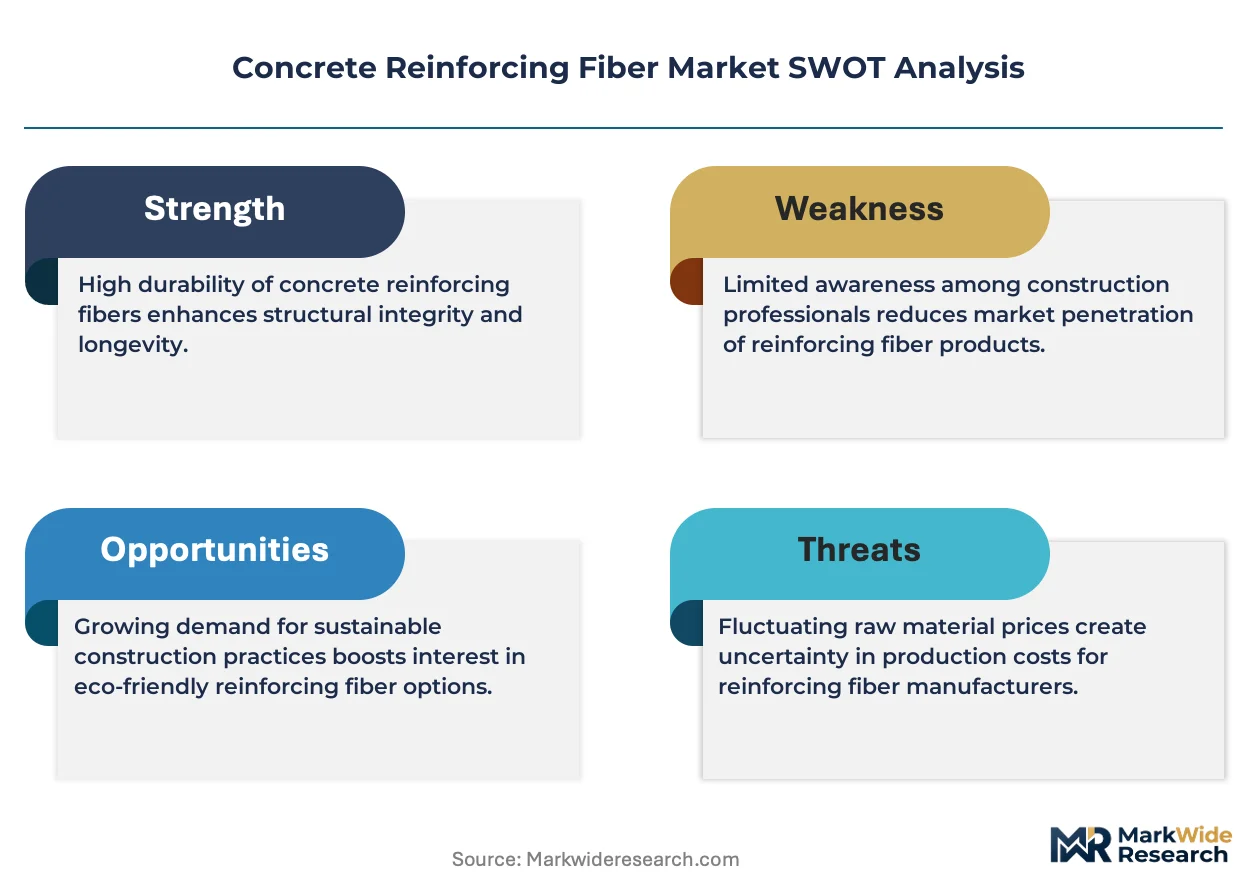
- Initial Cost Premium:The upfront material cost for synthetic and steel fibers often exceeds that of traditional welded wire mesh, presenting a barrier for cost-sensitive projects without a life-cycle cost analysis.
- Conservative Design Practices:A persistent lack of familiarity and training among some structural engineers regarding fiber-reinforced concrete design principles slows adoption in favor of established rebar-based methods.
- Substitution Threat:In certain non-structural applications, alternative crack control methods, such as improved curing compounds or concrete mix designs with shrinkage-reducing admixtures, compete directly with microfibers.
Strategic Opportunities
- Emerging Applications:The growth of 3D concrete printing presents a significant opportunity, as discrete fibers are integral to providing inter-layer strength and dimensional stability in printed structures.
- New Material Development:Basalt fibers, derived from volcanic rock, offer a combination of high tensile strength, chemical inertness, and temperature resistance, opening possibilities in specialized and harsh-environment applications.
- Geographic Penetration:Underdeveloped residential markets in North America and Europe for fiber-reinforced slabs-on-grade and foundations represent a substantial volume opportunity.
Industry Challenges
- Standardization Gaps:Discrepancies between key international standards, such as ASTM C1116 in the U.S. and EN 14889 in Europe, create compliance and testing hurdles for manufacturers operating globally.
- Specifier Education:Overcoming decades of reliance on traditional reinforcement requires significant investment in educating architects, engineers, and contractors on the proper specification and application of fiber technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Reinforcing Fiber Market |
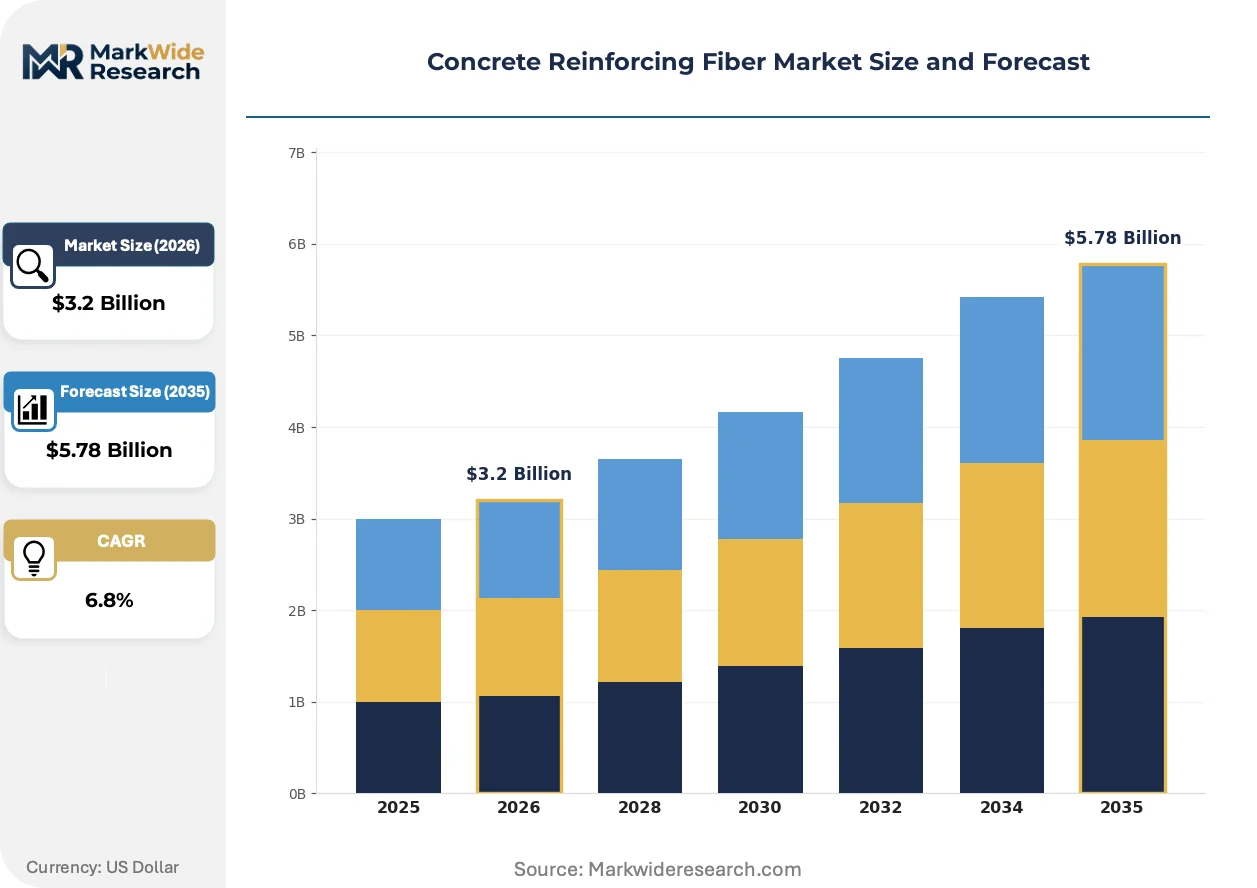
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fiber Type: Steel Fiber, Glass Fiber, Synthetic Fiber, Natural Fiber Manufacturing Process: Cutting, Extrusion, Chemical Treatment, Mixing End User: Construction, Infrastructure, Mining, Industrial Application: Flooring, Pavements, Shotcrete, Precast |
| Companies Covered | BASF SE, Bekaert, Sika AG, FORTA Corporation, The Euclid Chemical Company, Nycon Corporation, Owens Corning, Cemex S.A.B. de C.V., ABC Polymer Industries, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Reinforcing Fiber Market Strategic Shifts & Innovations
The convergence of material science and digital construction tools is redefining performance benchmarks for concrete reinforcement. This evolution prioritizes verifiable, long-term durability and construction efficiency over simple material substitution, altering specification and procurement patterns.
Hybrid fiber systems that combine different materials, such as steel and polypropylene fibers, are engineered to deliver tailored performance. Precast concrete producers are adopting this approach to simultaneously manage plastic shrinkage cracking with microfibers and enhance toughness with macrofibers. The ability to customize reinforcement for specific elements **is rendering obsolete** the traditional one-size-fits-all approach of using a single fiber type or rebar mesh.
Performance-based building codes are increasingly supplanting older, prescriptive material standards. This regulatory shift, aligned with objectives like those in the EU Green Deal, permits engineers to use innovative materials like macro-synthetic fibers if they can prove equivalent or superior long-term performance through testing. The shotcrete and tunneling segments are most affected, as project owners seek to accelerate construction and improve safety by using fiber-reinforced mixes.
Direct specification by large engineering and construction firms is altering the established sales model. This pattern disintermediates traditional building material distributors on major infrastructure projects, creating a preference for fiber suppliers who offer integrated technical, design, and logistical support. This demand-side shift is most prominent in large-scale transportation and renewable energy projects across the Middle East and Australia.
Concrete Reinforcing Fiber Market Segmentation
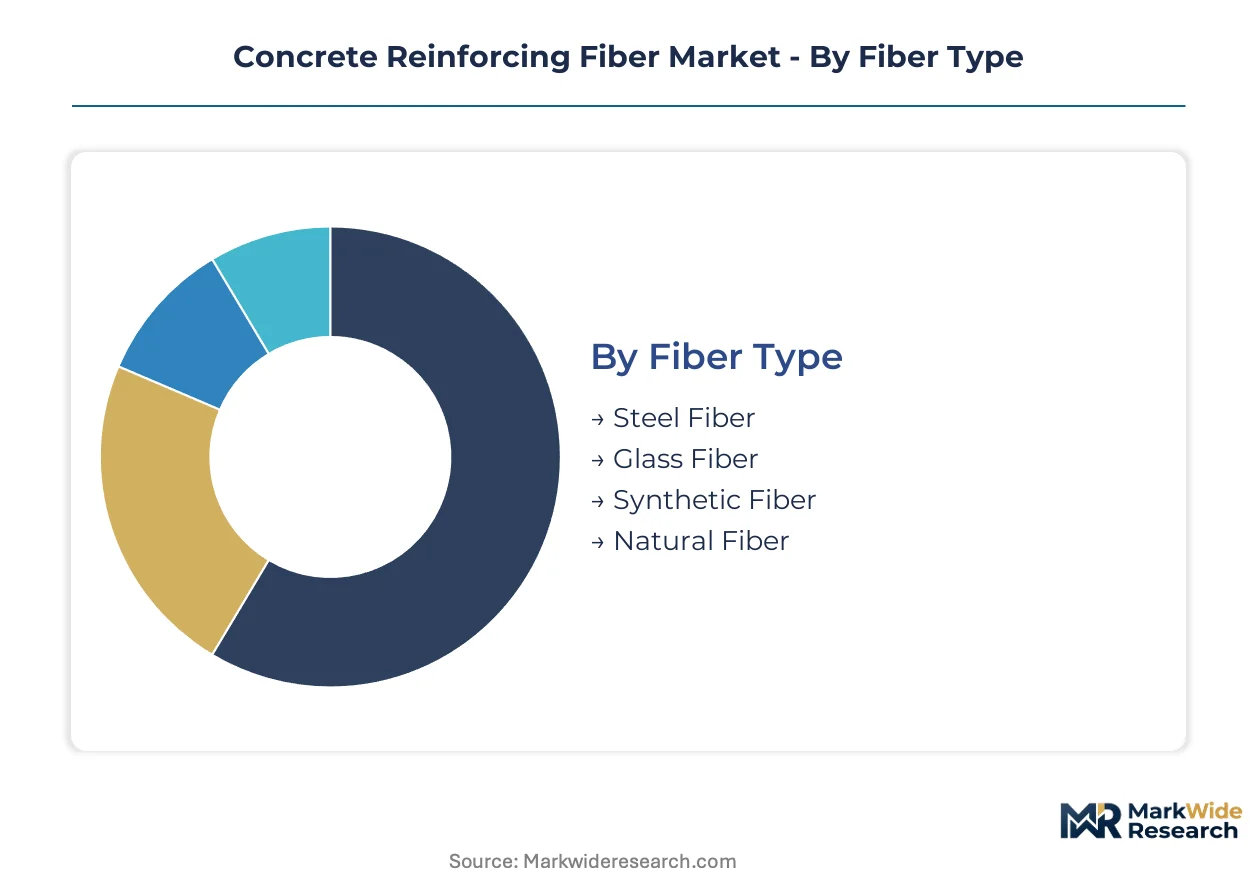
The concrete reinforcing fiber market divides into distinct segments based on material composition, production methods, and end-use applications. Understanding these classifications reveals specific demand patterns and technological preferences across diverse construction projects. This granular view assists stakeholders in identifying high-growth niches and optimizing product development strategies.
Fiber Type:
The market's fiber type segmentation highlights the performance characteristics and cost profiles associated with different reinforcing materials.
- Synthetic Fiber:These fibers, often polypropylene or macro-synthetic, offer corrosion resistance and ease of handling in concrete mixes. Demand is focusing in slabs-on-ground and precast elements due to their chemical inertness and improved ductility.
- Steel Fiber:Steel fibers provide high tensile strength and impact resistance, crucial for heavy-duty industrial floors and infrastructure. Specification for these fibers is driven by structural requirements in high-stress applications, particularly in North America and Europe.
- Glass Fiber:Glass fibers enhance ductility and crack control, finding application in architectural panels and specialized concrete products.
- Natural Fiber:Natural fibers, such as basalt, are gaining traction for their sustainable profile and high temperature resistance in niche applications.
Steel Fiber commands the established base. The steepest expansion runs through Synthetic Fiber.
Manufacturing Process:
Manufacturing process segmentation reflects the techniques employed to produce reinforcing fibers, influencing their form, cost, and suitability for various concrete applications.
- Extrusion:This process forms continuous filaments, primarily for synthetic fibers, offering precise control over fiber geometry and length. Demand for extruded macro-synthetic fibers is accelerating in tunneling and shotcrete applications where uniform dispersion is critical.
- Cutting:Cutting involves processing steel wires or synthetic sheets into discrete lengths, yielding fibers suitable for bulk concrete mixing. This method supports the high-volume production of steel fibers for industrial flooring and large-scale infrastructure projects.
- Mixing:Mixing refers to the incorporation of fibers into the concrete matrix, often occurring at the batch plant or on-site.
- Chemical Treatment:Chemical treatment enhances fiber-matrix bonding and durability, particularly for glass and natural fibers, improving overall composite performance.
Cutting methods produce a significant volume of traditional fibers. Extrusion techniques are gaining share fastest due to advanced synthetic fiber development.
End User:
The end-user segmentation categorizes demand based on the primary industry sector utilizing concrete reinforcing fibers, indicating project scale and performance requirements.
- Infrastructure:This segment includes transportation networks, bridges, and utility projects, demanding high-durability and long-life concrete solutions. Large-scale infrastructure projects in India and Southeast Asian nations are driving significant fiber consumption.
- Construction:The construction sector encompasses residential, commercial, and institutional buildings, where fibers improve crack control and reduce rebar usage. Residential markets in North America and Europe show substantial underpenetrated volume opportunity for fiber-reinforced slabs.
- Mining:Mining operations use fiber-reinforced shotcrete for ground support and tunnel stabilization, enhancing safety and operational efficiency.
- Industrial:Industrial facilities, including warehouses and manufacturing plants, specify fibers for durable, abrasion-resistant concrete floors subject to heavy loads.
Construction represents a broad and established end-user base. Infrastructure projects are exhibiting the steepest expansion trajectory for fiber adoption.
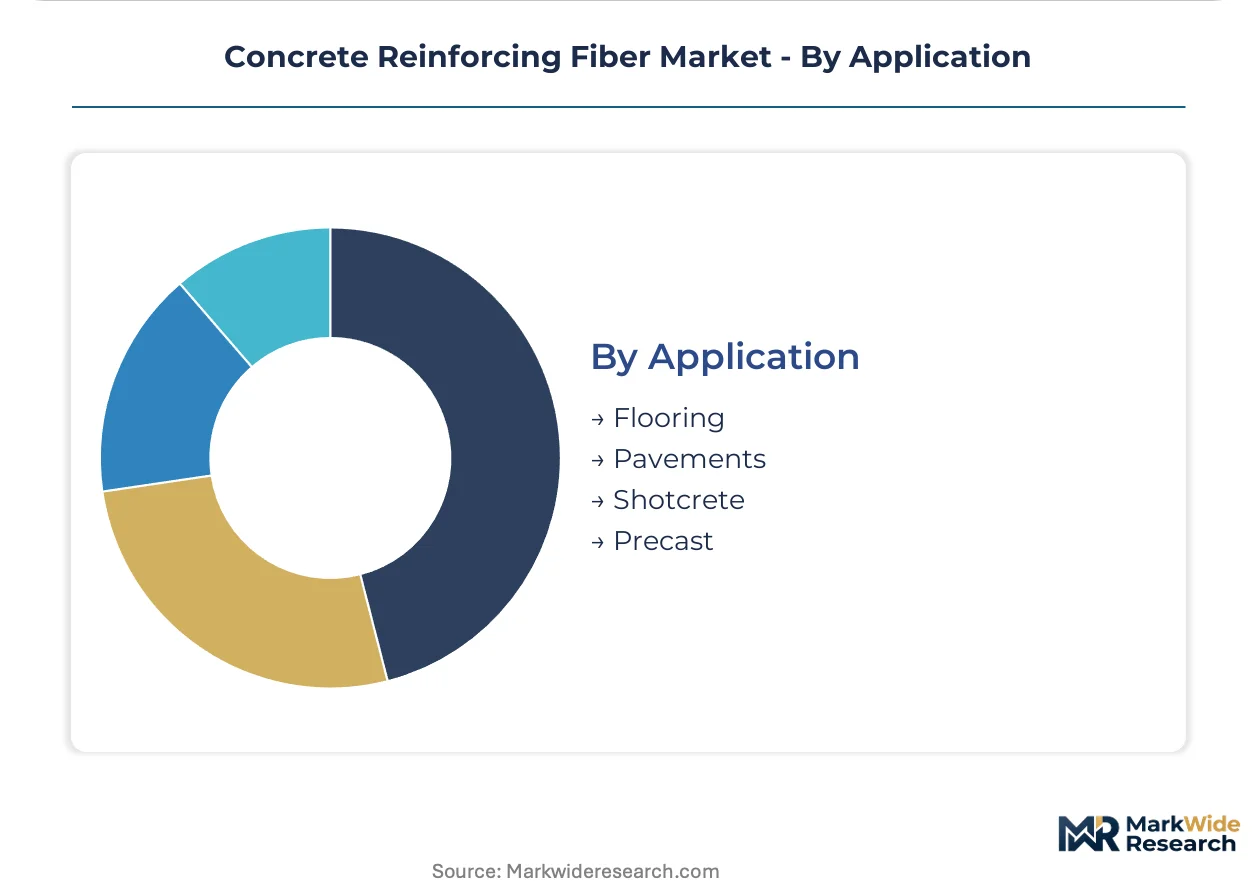
Application:
Application segmentation details the specific uses for fiber-reinforced concrete, highlighting distinct performance requirements and design considerations for each scenario.
- Shotcrete:Shotcrete applications, particularly in tunnels and slope stabilization, benefit from fibers that enhance ductility and reduce rebound. This segment is experiencing rapid growth as project owners seek to accelerate construction timelines and improve worker safety.
- Precast:Precast concrete elements, such as pipes, panels, and façade components, utilize fibers for improved strength, crack resistance, and reduced weight. Demand is concentrating in this segment due to the controlled manufacturing environment allowing for precise fiber integration and quality.
- Flooring:Flooring applications, including industrial slabs and commercial floors, use fibers for crack control, impact resistance, and surface durability.
- Pavements:Pavements, including roads and airport runways, incorporate fibers to improve fatigue resistance and extend service life under heavy traffic loads.
Flooring applications form a foundational demand segment. Shotcrete and Precast applications are climbing the fastest in terms of fiber adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and similar national decarbonization targets globally are compelling a shift towards advanced material solutions in construction. This policy-driven demand for sustainable and resilient infrastructure directly influences regional adoption of concrete reinforcing fibers. Infrastructure expansion projects in developing economies also contribute significantly to regional market dynamics.
India
Large-scale transportation and utility projects in India require advanced concrete solutions to meet aggressive construction timelines. The country's national infrastructure plan, including the Gati Shakti initiative, prioritizes high-durability materials. Major urban centers like Mumbai and Delhi are experiencing significant fiber consumption in metro rail and highway construction.
United States
Performance-based building codes in the United States encourage the use of innovative materials like fiber-reinforced concrete for long-term durability. The Infrastructure Investment and Jobs Act provides substantial funding for projects that can integrate advanced construction techniques. Underpenetrated residential markets in states like Texas and Florida offer substantial volume opportunities for fiber-reinforced slabs-on-grade.
Germany
Germany's commitment to the EU Green Deal mandates materials that reduce the carbon footprint of concrete and extend infrastructure service life. Stringent German building standards, such as those from DIN, promote the specification of certified reinforcing fibers. Industrial and automotive clusters in Bavaria and North Rhine-Westphalia are adopting fiber-reinforced floors for enhanced performance.
United Arab Emirates
The United Arab Emirates is undertaking ambitious infrastructure development and urban expansion projects, demanding high-performance concrete solutions. Government initiatives like Vision 2040 in Dubai emphasize sustainable construction practices and material innovation. Major construction hubs in Dubai and Abu Dhabi are seeing increased direct specification of fibers for large-scale projects.
Australia
Australia's focus on resilient infrastructure and mining operations drives the demand for durable concrete reinforcing fibers. Australian standards for concrete structures emphasize long-term performance and crack control. Mining regions in Western Australia and Queensland utilize fiber-reinforced shotcrete for ground support and tunnel stabilization.
Concrete Reinforcing Fiber Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, with established material science companies alongside specialized fiber producers. This configuration supports both high-volume standardized products and niche, high-performance solutions. Key strategic archetypes include diversified chemical giants and focused fiber specialists. Dominant competitive moves center on portfolio diversification and geographic expansion.
Diversified chemical companies, such as BASF SE, exemplify material science innovation, particularly in synthetic fibers for concrete applications. Specialists like Bekaert anchor the high-specification steel fiber segment, leveraging deep expertise for infrastructure projects. Sika AG occupies a position as a broad portfolio provider, integrating chemical admixtures with fiber solutions for comprehensive offerings.
| Leading Market Players |
|---|
| BASF SE |
| Bekaert |
| Sika AG |
| FORTA Corporation |
| The Euclid Chemical Company |
| Nycon Corporation |
| Owens Corning |
| Cemex S.A.B. de C.V. |
| ABC Polymer Industries, LLC |
| Others |
Cost & Logistics Intelligence
Shanghai's concentration of synthetic fiber production capacity directly influences global pricing power for these materials within the concrete reinforcing fiber market. This dynamic also extends to raw material availability, impacting downstream manufacturing costs for fiber producers. Procurement patterns increasingly favor direct supplier relationships for large-scale projects.
Pricing Analysis
Certification level, such as ASTM C1116 in the United States and EN 14889 in Europe, creates the primary spread in fiber pricing. Pricing often follows a contract-based, project-specific model for large infrastructure. Technical support and logistical capabilities also differentiate suppliers. Pricing pressure stems from the initial cost premium of fibers compared to traditional reinforcement, making cost-sensitive projects exhibit higher price sensitivity.
Supply Chain Analysis
Commodity price volatility for steel wire rod and polymer resins dominates the concrete reinforcing fiber supply chain. Fiber production concentrates in industrial hubs across China and Europe. The industry relies on consistent access to specialized steel wire and polypropylene granules. Downstream distribution increasingly runs through direct sales channels to large engineering firms and precast manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete reinforcing fiber market presents a fragmentation opportunity as performance-based building codes create specialized demand for tailored solutions. This shift allows for the emergence of niche players focusing on specific applications or material types.
For Market Incumbents: Build a technical expertise moat by expanding integrated design and logistical support services. This mitigates the threat from conservative design practices and alternative crack control methods. Incumbents should invest in R&D for advanced materials like basalt fibers, and diversify into hybrid fiber systems to secure project specifications.
For New Entrants and Emerging Players: Build out specialized offerings for underpenetrated residential markets in North America and Europe. Focus on fiber-reinforced slabs-on-grade, emphasizing long-term durability and crack control. A go-to-market angle highlighting life-cycle cost savings over initial material premium resonates with developers, and targeting emerging 3D concrete printing applications provides a high-growth niche.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fiber specialists with strong R&D in advanced synthetics and basalt. The long-term viability stems from the global shift towards resilient and sustainable infrastructure. Acquisition targets should include companies excelling in macro-synthetic fiber development or niche applications like 3D printing. The signal to watch is the accelerated adoption of performance-based building codes in new geographies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Supports growing demand for synthetic fibers in infrastructure projects. |
| Green Manufacturing Transition | Aligns with EU Green Deal mandates for reduced concrete carbon footprint. |
| Long-term Supply Agreement | Mitigates raw material price volatility for polypropylene and steel. |
| Joint Venture | Integrates fiber solutions directly into precast element manufacturing processes. |
| Product Launch | Addresses specialized application needs for high-temperature and chemical resistance. |
Research Approach
Operator-level perspectives from structural engineers, precast manufacturers, and infrastructure project managers anchored the qualitative base. This primary research was validated against secondary sources including ASTM International standards, EN 14889 framework, and national infrastructure plans. A bottom-up and top-down triangulation approach ensured data consistency across all segments.
Scenario-bracketing across conservative, base, and aggressive growth trajectories defined the quantitative analytical framework over the projection horizon. This framework modeled dimensions including fiber type, manufacturing process, end user, and application. Compound annual growth rates were derived from historical data and projected shifts in infrastructure spending and building code evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by material science innovators or new entrants would shift outcomes. Forecasts reflect underlying assumptions regarding market dynamics and technological adoption. Disruptive material science breakthroughs or rapid regulatory changes represent key risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Global Facade Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Aluminum Door and Window Market
Building Materials
Global Building Panels Market
Building Materials
Sanded Grout Market
Building Materials
North America Engineered Stone Market
Building Materials
Foam Concrete Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Gravity Retaining Wall Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Fiber Cement Market
Building Materials
Global FRP Rebar Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
Cement Tiles Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Southeast Asia Concrete Admixtures Market