
 Precision Engineering Machines Market | 2026-2036
Precision Engineering Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Engineering Machines Market Intelligence
The capability gap between asset-light digital manufacturing platforms and capital-intensive traditional machine shops is collapsing due to software and automation. Xometry leverages its AI-driven marketplace to connect buyers with a distributed network of suppliers. In contrast, Proto Labs operates with a significant in-house production infrastructure for rapid prototyping. Specialists like JTR Precision differentiate through deep expertise in complex, high-tolerance components for specific end-markets.
Precision engineering machines are automated systems designed to fabricate components with exceptionally tight tolerances, often achieving sub-micron levels of accuracy. Their primary industrial purpose is to produce high-fidelity parts for sectors where performance and reliability are paramount. Subtractive manufacturing via CNC machines continues to dominate production volume, but additive manufacturing technologies are experiencing rapid adoption for prototype development. The aerospace and medical devices end-user segments command the highest value, requiring complex custom parts manufacturing processes.
Quality and safety are governed by a matrix of standards, including the globally recognized ISO 9001 for quality management systems. Specific sectors impose stricter requirements, such as AS9100 for aerospace supply chains and the European Union's Medical Device Regulation (MDR) for component traceability. Future competitive advantage will be determined by a firm's ability to navigate complex material qualification pathways and integrate digital thread continuity from design to final inspection.
Market Dynamics
The central tension in the precision engineering machines market is the software-driven convergence of subtractive and additive manufacturing processes. This integration forces a re-evaluation of production workflows, from design validation to final part qualification, demanding greater digital continuity across the value chain.
Growth Catalysts
- Medical Device Sector Demand:Growth in medical devices, under regulations like the EU's MDR, necessitates machines for complex, biocompatible parts with full traceability.
- Additive Manufacturing Proliferation:Guided by standards like ISO/ASTM 52900, the adoption of additive technologies for prototyping and custom parts creates new machine demand.
- German Industrial Clusters:Demand from Germany's advanced automotive and aerospace manufacturing hubs drives investment in high-precision machining centers.
Market Restraints
- High Capital Outlay:The substantial upfront investment for multi-axis CNC and additive manufacturing systems presents a significant barrier to entry for smaller firms.
- Component Supply Concentration:Reliance on a few suppliers in Germany and Japan for critical components like high-precision spindles creates supply chain vulnerability.
- Complex Material Qualification:The costly process of qualifying new materials for regulated sectors like aerospace under AS9100 slows the adoption of new processes.
Strategic Opportunities
- Indian Manufacturing Incentives:India's PLI scheme for electronics and medical devices creates a significant opportunity for machine suppliers to equip new domestic factories.
- Small Satellite Components:The commercial space sector's demand for small satellite constellations opens a new market for machines producing lightweight, high-strength parts.
- AI-Driven Quality Assurance:Integrating in-situ metrology with machine learning offers a path to develop self-correcting machining systems, reducing waste and inspection time.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and engineers with expertise in operating and programming advanced 5-axis CNC machines and metal 3D printers limits production capacity.
- Digital Thread Integration:Achieving seamless data continuity from CAD/CAM software through to production and final inspection systems remains a significant technical and organizational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Engineering Machines Market |
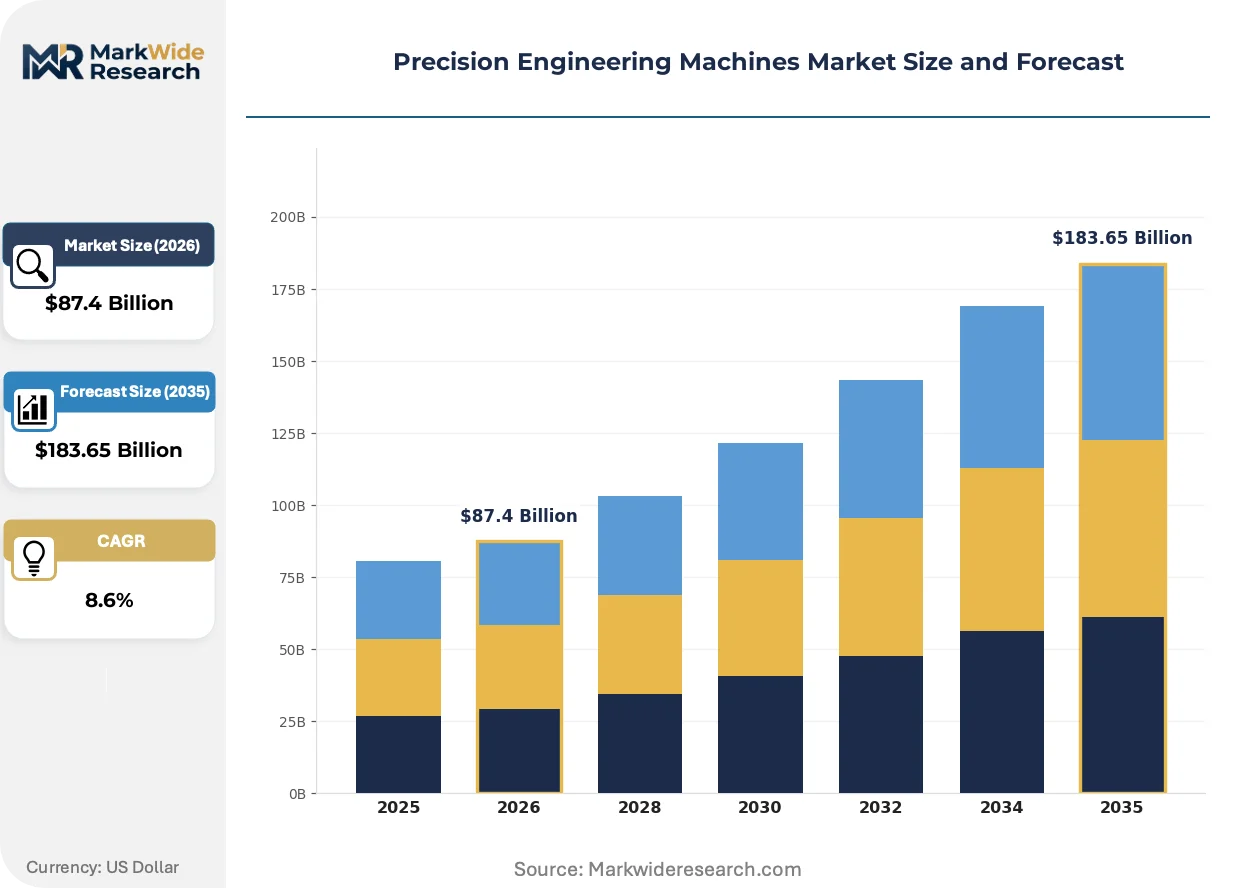
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $183.65 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Machines, Laser Cutting Machines, 3D Printers, Tool Grinders Technology: Hybrid Technology, Additive Manufacturing, Subtractive Manufacturing, Automation Technologies End User: Aerospace, Automotive OEMs, Medical Devices, Electronics Application: Prototype Development, Mass Production, Custom Parts Manufacturing, Maintenance Services |
| Companies Covered | Fictiv, eMachineShop, Proto Labs, JTR Precision, WayKen, Xometry, RapidDirect, Dongguan Kachi Precision Manufacturing, Renjie Precision, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Engineering Machines Market Strategic Shifts & Innovations
Software is becoming the central nervous system of precision engineering, enabling a shift from discrete machining operations to integrated, data-driven production ecosystems. This evolution prioritizes digital continuity and process automation over standalone machine performance.
Hybrid manufacturing systems integrate additive processes, such as directed energy deposition, with subtractive CNC milling within a single machine. Aerospace and defense firms are adopting this technology to repair high-value components and create complex geometries. This convergence is decomposing the traditionally separate and linear workflow of fabrication and finishing into a single, consolidated operation.
The European Union's Medical Device Regulation (MDR) mandates stringent traceability and quality verification for all components. This forces medical device manufacturers to adopt production systems that can generate and maintain a complete digital record for each part. Suppliers of orthopedic implants and surgical instruments are particularly impacted, investing in machines with integrated inspection and data logging.
Buyer behavior is shifting from outright capital equipment acquisition towards procuring capacity through on-demand digital manufacturing marketplaces. This model allows engineering teams to bypass traditional sales channels and directly source custom parts from a distributed supplier network. The trend is most visible among hardware startups and corporate R&D labs in the United States that prioritize speed and agility.
Precision Engineering Machines Market Segmentation
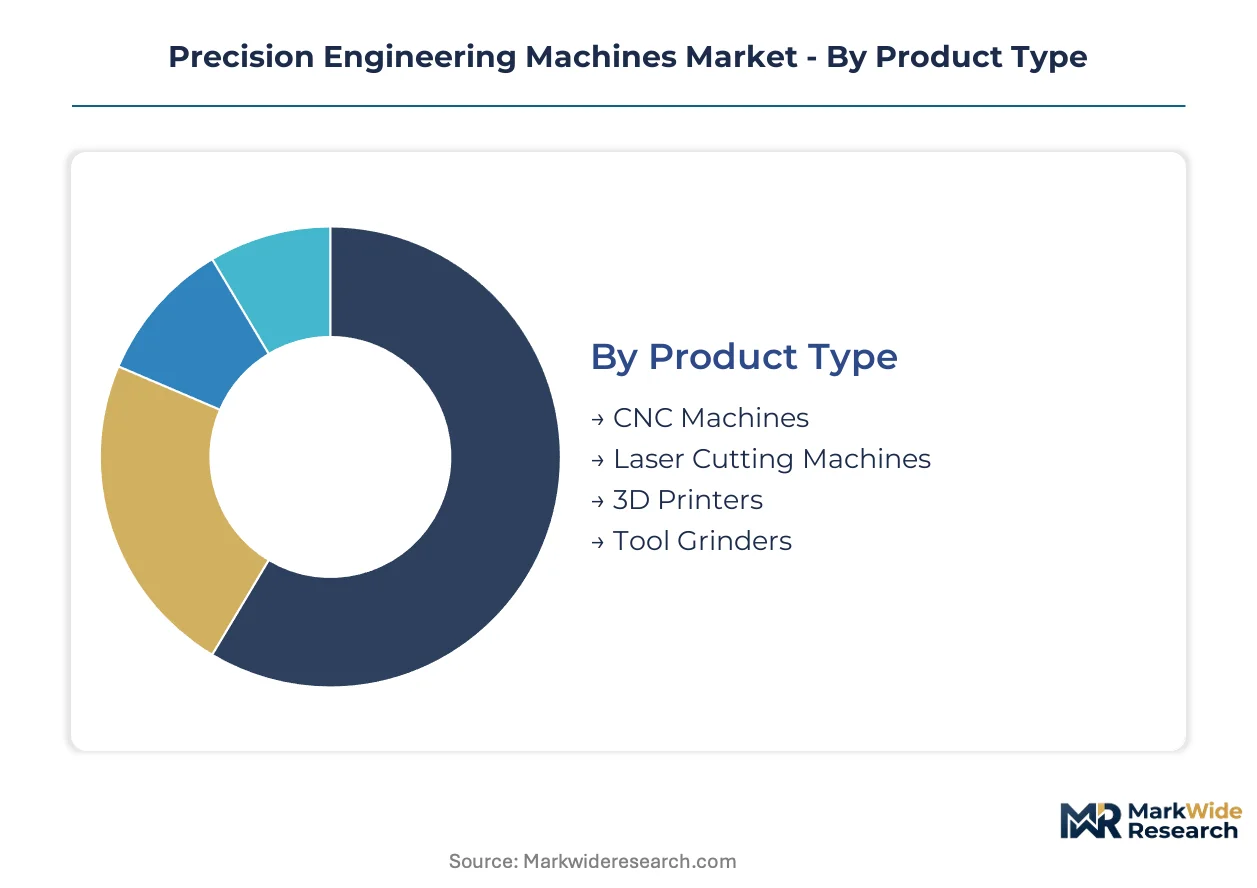
The precision engineering machines market serves diverse industrial requirements, necessitating a detailed segmentation to understand demand patterns and technological adoption. Analyzing these distinct segments reveals how various machine types, technologies, end-user sectors, and applications contribute to the market's overall expansion. This segmentation highlights the specific drivers influencing procurement decisions across the value chain.
Product Type:
The distribution channels for precision engineering machines vary significantly by product type, with established equipment often requiring direct sales while newer technologies leverage specialized integrators.
- CNC Machines:These computer numerically controlled systems perform subtractive manufacturing operations like milling, turning, and grinding with high accuracy. Demand for CNC machines concentrates in Germany's advanced manufacturing clusters for automotive and aerospace components.
- 3D Printers:These additive manufacturing systems build parts layer by layer from digital designs, utilizing various materials such as metals and polymers. The proliferation of 3D printers is driven by rapid prototyping and custom part manufacturing in the medical devices sector.
- Laser Cutting Machines:These machines use a focused laser beam to cut materials with high precision, widely used in electronics and sheet metal fabrication.
- Tool Grinders:Tool grinders sharpen and recondition cutting tools, essential for maintaining efficiency in traditional machine shops.
CNC Machines dominate the installed base of precision engineering equipment. 3D Printers are where expansion concentrates.
Technology:
Production volume significantly differentiates precision engineering technologies, with established methods handling large runs and newer approaches focusing on specialized, lower-volume applications.
- Subtractive Manufacturing:This technology removes material from a solid workpiece to create a desired shape, primarily using CNC machines. It continues to dominate production volume for high-fidelity parts across the automotive and industrial sectors.
- Additive Manufacturing:This technology builds three-dimensional objects by adding material layer by layer, encompassing processes like powder bed fusion and directed energy deposition. Its adoption is accelerating for prototype development and complex custom parts in aerospace.
- Hybrid Technology:Hybrid systems integrate both additive and subtractive processes within a single machine, optimizing for repair and complex geometry creation.
- Automation Technologies:These encompass robotics and integrated software for machine tending, quality control, and data-driven workflow optimization in manufacturing.
The market for subtractive manufacturing technologies maintains a substantial share. Additive manufacturing technologies are expanding most quickly in adoption for specialized applications.
End User:
The margin profiles for precision engineering services vary considerably across end-user segments, reflecting differing regulatory burdens and component complexity.
- Medical Devices:This segment requires machines for producing biocompatible implants, surgical instruments, and diagnostic components with stringent traceability. Growth in medical devices, driven by EU's MDR, necessitates high-precision machines for complex custom parts.
- Aerospace:The aerospace sector demands machines capable of fabricating lightweight, high-strength parts for aircraft and satellites, often with AS9100 compliance. Complex custom parts manufacturing processes command high value within this segment.
- Automotive OEMs:Automotive original equipment manufacturers utilize precision machines for engine components, transmission parts, and specialized tooling.
- Electronics:The electronics industry relies on precision engineering for micro-components, semiconductor manufacturing equipment, and intricate housings.
Medical devices and aerospace end-users command the highest value for precision engineering machines. Electronics manufacturing represents a segment with consistent, high-volume requirements.
Application:
Different customer types prioritize distinct applications, with startups often focusing on rapid development and established firms emphasizing large-scale production efficiency.
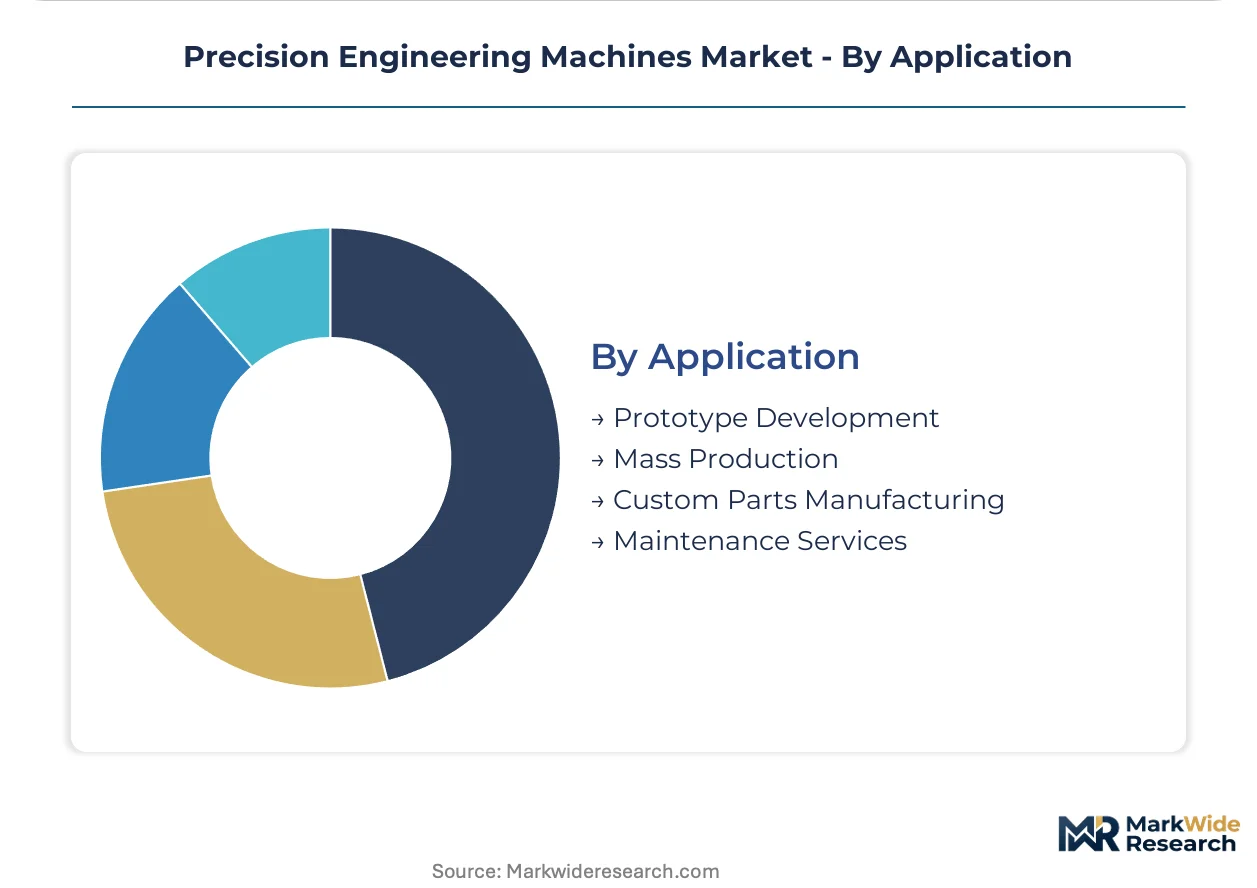
- Mass Production:This application involves manufacturing large quantities of identical parts efficiently and cost-effectively, primarily utilizing subtractive CNC technologies. Demand from Germany's automotive and industrial sectors drives investment in mass production capabilities.
- Prototype Development:This application focuses on creating initial versions of parts for testing and validation, with additive manufacturing technologies increasingly preferred for speed and design flexibility. Hardware startups and corporate R&D labs in the United States prioritize this application.
- Custom Parts Manufacturing:This involves producing unique, specialized components tailored to specific requirements, common in aerospace and medical sectors.
- Maintenance Services:This application includes repair, refurbishment, and servicing of existing machinery and components, ensuring operational longevity.
Mass production applications represent a foundational demand for precision engineering machines. Prototype development applications are experiencing the steepest expansion trajectory due to technological advancements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for precision engineering machines varies significantly by end-user, with highly regulated sectors demonstrating lower price sensitivity compared to those prioritizing rapid prototype development. This divergence shapes regional investment patterns and technological adoption across global manufacturing hubs. Government incentives further influence procurement decisions in specific geographies.
Germany
German industrial clusters, particularly in automotive and aerospace, drive substantial demand for high-precision CNC machines. The country's strict quality standards, including adherence to ISO 9001 and AS9100, mandate advanced manufacturing capabilities. Bavaria and Baden-Württemberg remain key centers for specialized machine tool production and application.
United States
Hardware startups and corporate R&D labs in the United States prioritize rapid prototype development, fostering demand for agile additive manufacturing solutions. The Food and Drug Administration (FDA) regulations for medical devices also necessitate highly accurate and traceable production systems. Silicon Valley and the Boston corridor lead in adopting these innovative manufacturing approaches.
India
India's Production Linked Incentive (PLI) scheme for electronics and medical devices stimulates domestic manufacturing, creating new demand for precision engineering machines. This policy encourages local production capabilities for high-value components. Manufacturing hubs like Maharashtra and Karnataka are expanding their capacity with new equipment.
Japan
Japanese manufacturers maintain a strong global position in producing critical high-precision components, such as advanced spindles, for the machine tool industry. Adherence to strict JIS standards ensures the reliability and performance of these essential parts. Industrial regions like Aichi Prefecture concentrate expertise in precision machinery development.
China
China's vast electronics manufacturing sector and industrial base generate consistent, high-volume demand for precision engineering machines. National policies, including "Made in China 2025," support upgrading manufacturing capabilities. The Yangtze River Delta region remains a primary hub for both production and consumption of these machines.
Precision Engineering Machines Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the precision engineering machines market, reflecting a tiered competitive structure. The market exhibits fragmentation among specialized service providers and consolidation among established machine tool manufacturers. Strategic archetypes include asset-light digital manufacturing platforms, vertically integrated rapid prototyping specialists, and niche experts in complex components. Dominant competitive moves involve strategic partnerships to integrate digital threads and targeted capacity expansion in high-growth segments.
Digital manufacturing marketplaces like Xometry exemplify the asset-light approach, efficiently connecting buyers with distributed supplier networks for custom parts across various industries. In contrast, Proto Labs represents a hybrid model, combining significant in-house production infrastructure with rapid prototyping services to ensure speed and quality. Furthermore, specialists such as JTR Precision occupy a distinct position through deep expertise in complex, high-tolerance components tailored for specific end-markets, often requiring specialized material qualification.
| Leading Market Players |
|---|
| Fictiv |
| eMachineShop |
| Proto Labs |
| JTR Precision |
| WayKen |
| Xometry |
| RapidDirect |
| Dongguan Kachi Precision Manufacturing |
| Renjie Precision |
| Others |
Cost & Logistics Intelligence
Additive manufacturing technologies, displacing traditional subtractive processes for prototyping, simultaneously reshape material input dependencies and introduce new pricing models driven by design complexity rather than solely volume. This shift influences where specialized components are sourced globally.
Pricing Analysis
After-sales service contracts and specialized consumables drive significant lifetime value for precision engineering machines. Pricing stratifies across premium, standard, and economy tiers, often based on machine accuracy, certification level like AS9100, and customization capabilities. Pricing pressure stems from the high initial capital outlay and competition for standard CNC machines. However, demand from highly regulated sectors like medical devices exhibits lower price sensitivity for compliant, high-performance systems.
Supply Chain Analysis
Long lead times for critical components, particularly high-precision spindles and advanced control systems, characterize the precision engineering machine supply chain. Supply concentrates heavily in Germany and Japan for these essential parts. Reliance on a few specialized suppliers creates single-source vulnerability, especially for complex multi-axis CNC and hybrid systems. Distribution runs through direct sales channels for major equipment manufacturers and specialized integrators for additive manufacturing solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers a significant service-attach opportunity, as software and digital thread integration services are expanding faster than core machine hardware sales. Firms can leverage recurring revenue streams from data management and process optimization solutions.
For Market Incumbents: Secure digital thread continuity from CAD/CAM to final inspection to counter the rise of asset-light digital manufacturing platforms. Invest in hybrid manufacturing capabilities that integrate additive and subtractive processes to defend against technological displacement. Prioritize R&D in AI-driven quality assurance to reduce waste and improve system autonomy. Ensure compliance with stringent standards like AS9100 and EU MDR to maintain market access in high-value segments.
For New Entrants and Emerging Players: Digital thread integration services, especially for small to medium-sized enterprises lacking in-house expertise, represent a significant service-layer gap. Target hardware startups and corporate R&D labs in the United States with agile, on-demand additive manufacturing solutions. Develop AI-driven metrology software that integrates seamlessly with diverse machine types, offering a clear path to market entry. Focus on niche applications requiring rapid prototyping and complex custom parts to gain traction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital manufacturing marketplaces and rapid prototyping specialists, offering consolidation opportunities. Long-term viability hinges on firms capable of integrating advanced software with physical production capabilities for regulated sectors. Target acquisition archetypes include niche experts in complex, high-tolerance components or specialized material qualification. The signal to watch is the successful integration of in-situ metrology with machine learning for self-correcting systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-driven Metrology | Enhances quality assurance and reduces inspection time for complex parts. |
| Develop Hybrid Manufacturing Systems | Optimizes repair and complex geometry creation for high-value components. |
| Expand Capacity in India | Leverages PLI scheme incentives to equip new domestic factories. |
| Certify for Aerospace/Medical Standards | Unlocks access to high-value, regulated end-user segments. |
| Form Digital Marketplace Partnerships | Connects with distributed supplier networks for custom part sourcing. |
Research Approach
Cross-validation between primary interviews and extensive secondary validation anchors the qualitative findings of this study. Interviews included plant managers, R&D engineers, procurement leads, and regulatory affairs specialists. Secondary data comprised ISO/ASTM standards, EU MDR guidelines, AS9100 documentation, and specialized manufacturing reports. Bottom-up and top-down triangulation methods ensured data accuracy.
Sensitivity analysis was applied to key market drivers to model various growth scenarios across the analysis window. The analytical framework segmented the market by product type, technology, end-user, application, and geographic manufacturing cluster. Compound annual growth rates were derived from historical data and projected technology adoption rates. Capital expenditure trends and material qualification pathways served as critical forecast inputs.
Forecasts assume regulatory continuity in EU, US, and global ISO regimes; material policy shifts would require re-modeling. Projections reflect current trends, but skilled labor availability and global supply chain disruptions pose potential risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Precision Mechanics and Electrics
Industrial Spindles Market
Precision Mechanics and Electrics
Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Precision Adjustment Screw Market
Precision Mechanics and Electrics
Precision Strain Wave Reducer Gearboxes Market
Precision Mechanics and Electrics
Right Angle Fastener Market
Precision Mechanics and Electrics
Asia-Pacific Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
Turning Machining Product Market
Precision Mechanics and Electrics
Impression Die Forging Market
Precision Mechanics and Electrics
Global Ball Screw Market
Precision Mechanics and Electrics
Precision Roller Levelers Market
Precision Mechanics and Electrics
Laser Surface Texturing Market
Precision Mechanics and Electrics
Laser Cladding Market
Precision Mechanics and Electrics
North America Precision Turned Product Manufacturing Market
Precision Mechanics and Electrics
High Precision Worm Shaft Market