
 Aluminum Door and Window Market | 2026-2036
Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Door and Window Market Analysis
Thermal break specification upgrades is redrawing competitive boundaries across the aluminum door and window industry. Schüco leverages its European engineering heritage to dominate high-performance facade systems. YKK AP anchors its position through integrated manufacturing from extrusion to hardware. Kawneer competes on large-scale commercial project expertise across North American metropolitan corridors.
Aluminum doors and windows are fabricated from extruded aluminum alloy profiles, typically 6063-T5 or 6061-T6 grade, assembled with polyamide thermal breaks and EPDM gaskets to achieve U-values below 1.4 W/m²K for energy-compliant building envelopes. Their primary purpose is to provide structurally stable, corrosion-resistant openings that balance daylight transmission with thermal and acoustic insulation in commercial and residential structures. Sliding doors and bi-fold doors command premium positioning in luxury residential and hospitality applications where expansive glass walls drive aesthetic value. Thermal break material grade segments are capturing margin pools as building codes tighten energy performance mandates across developed economies. Fixed windows retain volume leadership in high-rise commercial towers where operability requirements diminish and cost efficiency dominates specification decisions.
The EPA Energy Star certification program and the European Union's F-Gas Regulation are elevating thermal performance thresholds for fenestration products entering their respective markets. China's GB standards and India's BIS certification requirements are similarly tightening aluminum profile energy efficiency criteria for new construction permits. Stakeholders must monitor evolving code harmonization between national energy rating systems and material sourcing transparency mandates to preserve market access across jurisdictions.
Market Dynamics
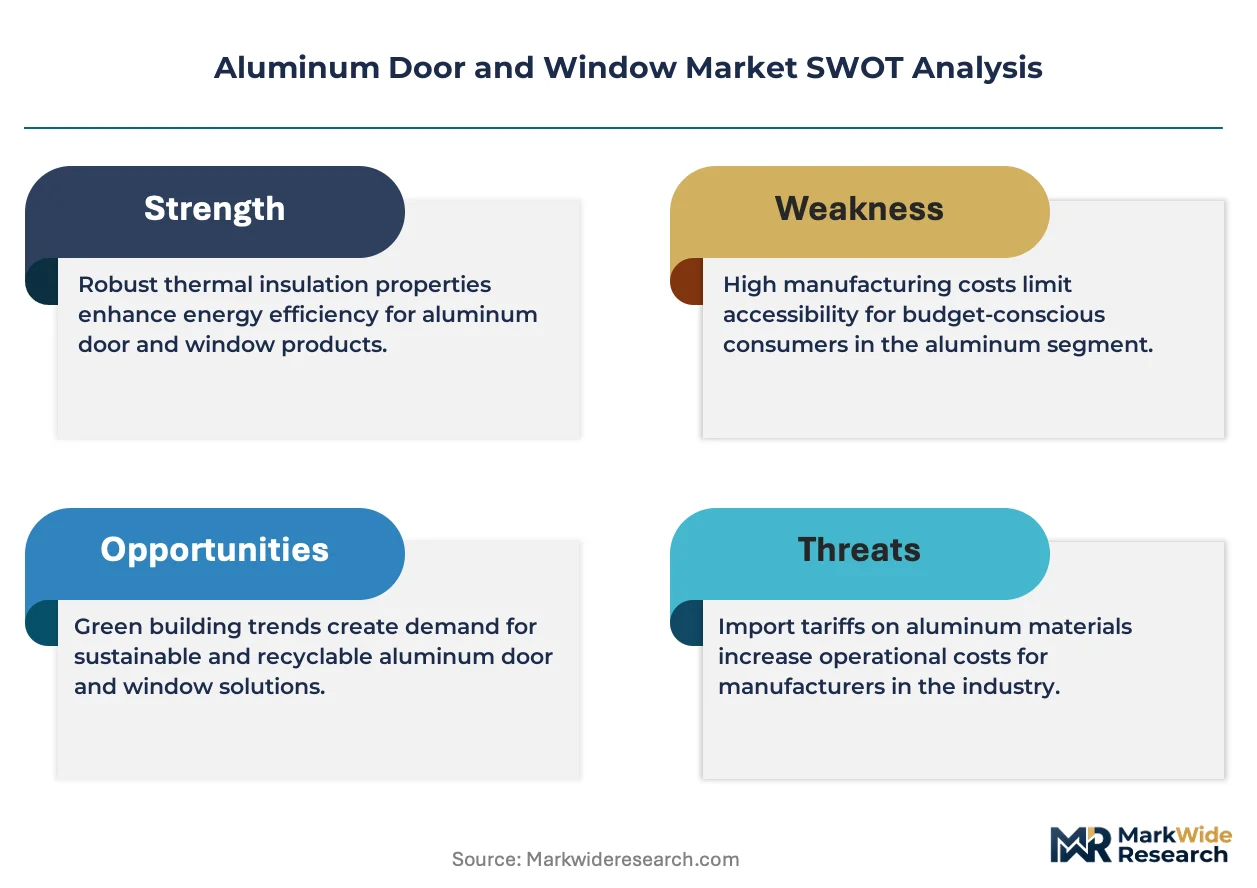
Thermal break specification upgrades are compressing margins for non-compliant fabricators while rewarding systems engineers with certified testing infrastructure. The shift from basic extrusion supply to performance-guaranteed envelope solutions is restructuring procurement relationships across commercial construction.
Growth Catalysts
- EPA Energy Star Certification:US commercial developers now require third-party verified U-values below 1.4 W/m²K for federal tax incentives, pulling specification-grade thermal break systems into mid-rise office construction.
- India's BIS Certification Mandate:New construction permits in Mumbai, Delhi, and Bangalore now require Bureau of Indian Standards compliance for aluminum profile energy efficiency, forcing import substitution toward domestic certified fabricators.
- Curtain Wall Retrofit Cycles:Aging 1990s commercial towers in Chicago, Frankfurt, and Shanghai are triggering replacement demand for high-performance aluminum glazing systems with improved acoustic and thermal performance.
Market Restraints
- Primary Aluminum Price Volatility:LME aluminum price swings above fifteen percent annually compress fabricator margins and destabilize fixed-price commercial contracts.
- Polyamide Thermal Break Supply Concentration:European and Chinese specialty polymer producers control eighty percent of certified thermal break strip supply, creating single-source vulnerability for North American window manufacturers.
- Steel Window Resurgence in Heritage Restoration:Historic preservation codes in Boston, London, and Melbourne mandate steel fenestration for designated buildings, blocking aluminum specification in premium restoration segments.
Strategic Opportunities
- Saudi Giga-Project Pipeline:NEOM, Red Sea Project, and Qiddiya developments specify European-grade aluminum facades with accelerated delivery timelines, rewarding fabricators with regional pre-positioning.
- Smart Glass Integration:Electrochromic glazing convergence with aluminum framing systems creates premium positioning for building envelope contractors with electrical integration capabilities.
- EU F-Gas Regulation Phase-Down:Refrigerant restrictions are elevating passive thermal management through high-performance fenestration, redirecting HVAC specification budgets toward advanced aluminum window systems.
Industry Challenges
- Thermal Modeling Skill Scarcity:Computational fluid dynamics expertise for facade performance simulation remains concentrated among European engineering consultancies, limiting in-house capability development for Asian fabricators.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of NFRC, PHI, and local fire-safety ratings for a single product family extends time-to-market by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Door and Window Market |
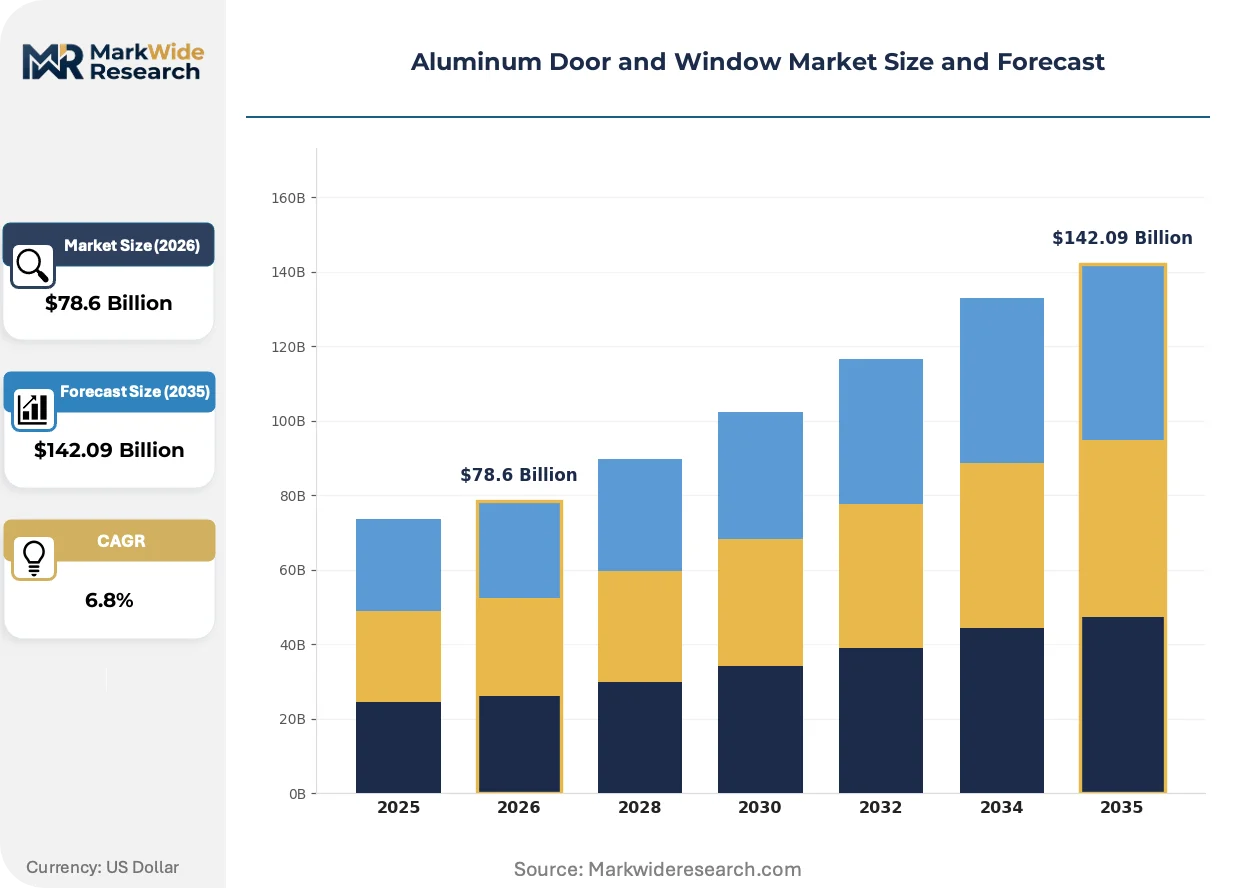
| Market Size in 2026 | $78.6 Billion |
| Market Size in 2035 | $142.09 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sliding Doors, Casement Windows, Bi-fold Doors, Fixed Windows Application: Residential, Commercial, Industrial, Hospitality End User: Builders, Contractors, Homeowners, Architects Material Grade: Powder Coated, Anodized, Mill Finish, Thermal Break |
| Companies Covered | Kawneer, AluK, Schüco, Technal, Alumil, Reynaers Aluminium, Andersen Windows & Doors, Fenesta, YKK AP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Door and Window Market Emerging Trajectories
Aluminum fenestration is transitioning from commodity extrusion supply to integrated building envelope solutions. Three parallel developments are compressing traditional fabrication models while opening premium service tiers.
Polyamide thermal break technology with multi-chamber geometry is supplanting basic two-chamber strips in specification-grade commercial projects. High-rise developers in Toronto, Singapore, and Dubai now mandate third-party tested thermal performance guarantees, compressing specification authority toward systems houses with captive testing laboratories and certified installation networks.
REACH substance restrictions and the EU F-Gas Regulation are eliminating chromate conversion coatings and certain sealant chemistries from supply chains. Fabricators with pre-qualified alternative surface treatments and fluoropolymer-free gasket compounds are securing preferential access to German and Nordic public procurement frameworks, while laggards face contract disqualification.
Design-assist contracting is replacing traditional bid-specify-install sequences for complex facade packages. Developers in Manhattan, London, and Sydney now retain envelope specialists during schematic design, unbundling architectural specification from general contractor procurement. This compresses competitive bidding windows while elevating early-engagement fabricators with BIM-capable engineering teams.
Aluminum Door and Window Market Segmentation
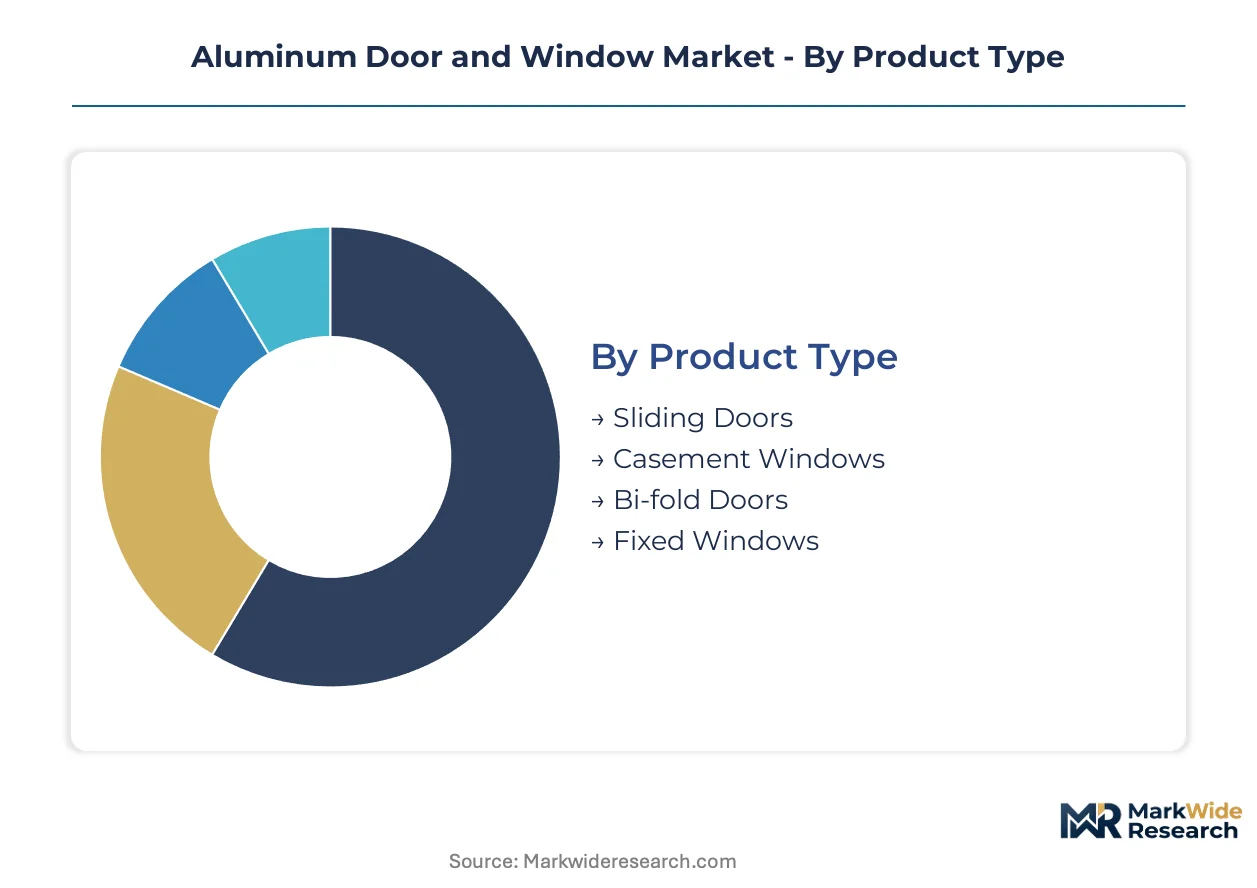
Aluminum fenestration procurement channels diverge sharply by project scale and specification complexity. Residential homeowners favor retail and dealer networks for replacement windows, while commercial developers engage systems houses directly for performance-guaranteed facade packages. Understanding these channel dynamics illuminates where margin pools concentrate and which segments reward early-engagement sales models.
Product Type:
Channel concentration varies dramatically across door and window formats, with project-scale fabricators dominating commercial specifications and retail distributors capturing residential replacement demand.
- Sliding Doors:Multi-track aluminum systems with heavy-duty rollers and low-threshold drainage accommodate expansive glass panels up to 400 kg per sash. Hospitality developments in Dubai, Miami, and Bali specify premium lift-slide configurations for ocean-view suites, with procurement flowing through design-assist contracts rather than competitive bidding.
- Casement Windows:Side-hinged aluminum frames with multi-point locking hardware achieve superior air infiltration ratings against sliding alternatives. German and Austrian window manufacturers dominate this segment through specialized hardware integration and established PHI certification pathways for passive house construction.
- Bi-fold Doors:Folding panel systems with concealed hinges and bottom-hung or top-hung hardware enable full wall openings. Residential demand concentrates in California, Queensland, and the UK home counties where indoor-outdoor living drives premium positioning.
- Fixed Windows:Non-operable aluminum frames with minimal sightlines maximize daylight transmission and thermal performance. High-rise towers in Toronto, Singapore, and Frankfurt specify these for curtain wall applications where operability is sacrificed for cost efficiency and structural simplicity.
By volume, Fixed Windows leads. By growth pace, Bi-fold Doors is climbing the fastest as luxury residential and hospitality segments expand outdoor connectivity specifications.
Application:
Cost tier stratification separates specification-grade commercial facades from commodity residential products, with margin structures inverting between new construction and replacement cycles.
- Commercial:Office towers, retail centers, and institutional buildings demand thermally broken aluminum systems with third-party certified U-values and acoustic ratings. Chicago, London, and Mumbai developers now require design-assist contracting for complex envelope packages, compressing traditional bidding windows.
- Residential:Single-family and multi-family housing drives volume through replacement cycles and new construction, with procurement split between big-box retail for standard sizes and specialized dealers for custom openings. Energy retrofit subsidies in Germany, France, and Italy are accelerating thermal break upgrades in existing housing stock.
- Industrial:Warehouses, manufacturing facilities, and logistics centers prioritize durability and low maintenance over thermal performance, accepting mill-finish or basic powder-coated aluminum without thermal breaks. Rapid deployment timelines favor local fabricators with standardized product lines.
- Hospitality:Hotels, resorts, and serviced apartments command premium aesthetic and acoustic specifications, with sliding and bi-fold door systems dominating poolside and rooftop applications. Procurement flows through international procurement consultants for branded property developments.
Commercial applications command the highest per-unit margins. Residential replacement cycles deliver the steadiest volume base across economic cycles.
End User:
Customer type determines specification authority and procurement complexity, with architects and developers wielding disproportionate influence over product selection.
- Builders:Production homebuilders and regional construction firms prioritize cost certainty and delivery reliability, favoring established fabricators with regional distribution networks. Volume commitments enable preferential pricing on standard thermal break configurations.
- Contractors:General contractors and specialized envelope installers balance first-cost pressures with installation efficiency, rewarding systems with pre-glazed options and simplified anchoring details. Design-build procurement is elevating early contractor involvement in product selection.
- Homeowners:Individual property owners in replacement markets research energy ratings and aesthetic options through online configurators, with final purchase decisions influenced by contractor recommendations and financing availability.
- Architects:Design professionals specify performance criteria and aesthetic requirements, increasingly mandating BIM-compatible product data and embodied carbon documentation for public and corporate clients.
Builders and contractors control procurement volume. Architects are gaining specification authority fastest as performance mandates tighten.
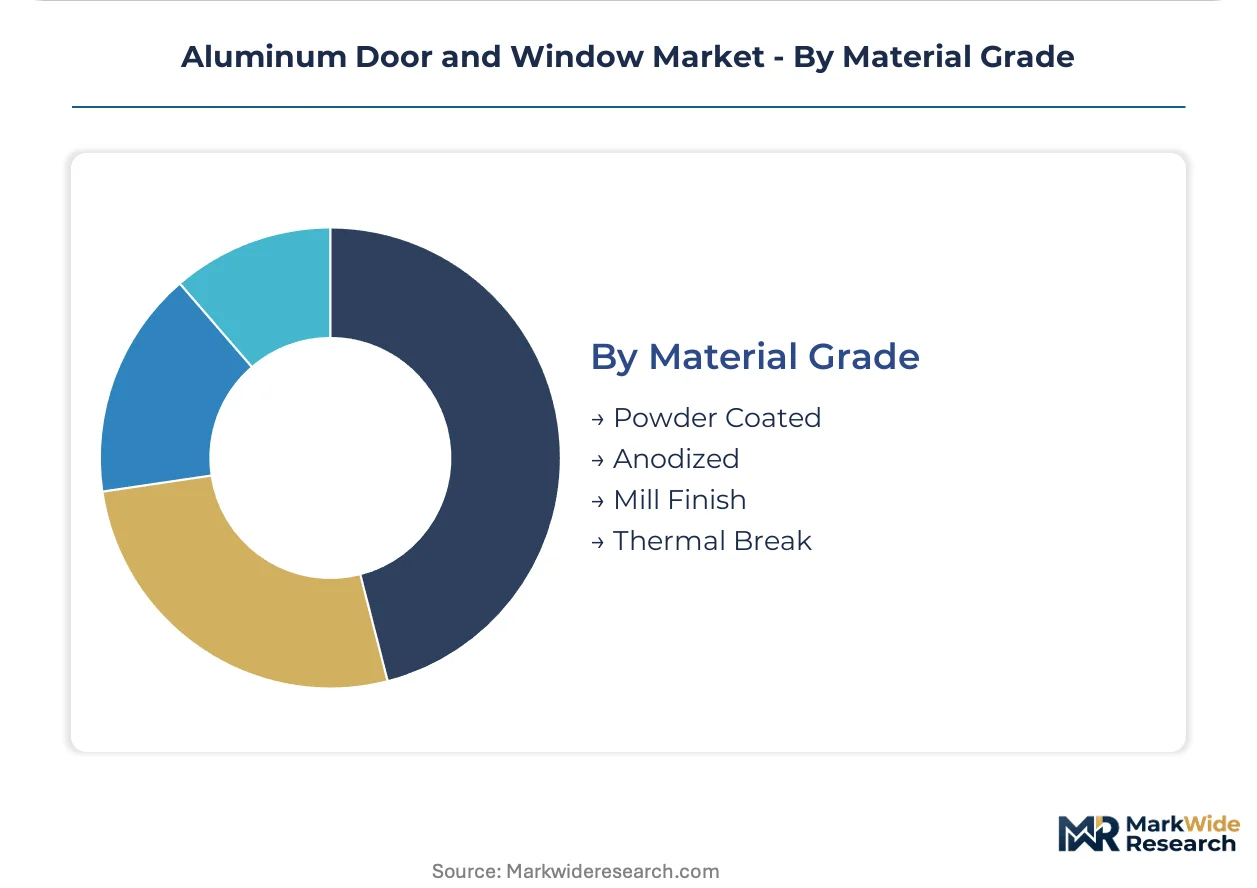
Material Grade:
Supply concentration for certified thermal break materials and REACH-compliant surface treatments is reshaping competitive access to premium segments.
- Thermal Break:Polyamide strips with glass fiber reinforcement create thermal separation between aluminum profiles, enabling U-values below 1.4 W/m²K for energy code compliance. European and Chinese specialty polymer producers control certified supply, creating qualification barriers for North American fabricators.
- Powder Coated:Electrostatically applied polyester or fluoropolymer finishes provide color consistency and durability at moderate cost, dominating commercial and residential specification where custom colors support branding requirements.
- Anodized:Electrochemical surface conversion creates a hard, corrosion-resistant oxide layer with metallic appearance, preferred for heritage-sensitive and high-traffic applications in transit stations and public buildings.
- Mill Finish:Unfinished extruded aluminum with natural oxide protection offers lowest first cost for industrial and utilitarian applications where appearance is secondary to function and rapid procurement.
Powder Coated leads by volume across all applications. Thermal Break is expanding most quickly as energy codes tighten in developed economies and certification mandates spread to emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics vary sharply across major aluminum fenestration markets. China and Germany maintain substantial trade surpluses in extruded profiles and finished systems, while the United States and India remain net importers of high-performance thermal break technologies.
United States
Commercial high-rise construction in Chicago, New York, and Miami drives specification-grade thermal break demand. EPA Energy Star certification mandates for federal tax incentives compress procurement toward NFRC-verified fabricators. The Southeast corridor from Atlanta to Tampa anchors domestic production capacity expansion for mid-rise office envelopes.
Germany
Passive house construction standards in Bavaria and Baden-Württemberg sustain premium thermal performance requirements. ECHA REACH substance restrictions eliminate chromate conversion coatings from supply chains, forcing surface treatment upgrades. The Rhine-Ruhr industrial cluster concentrates systems engineering expertise and captive thermal break testing laboratories.
China
Urbanization in the Yangtze River Delta and Pearl River Delta sustains volume demand for both commercial facades and residential replacement. GB standards for aluminum profile energy efficiency tighten compliance thresholds for new construction permits. Shenzhen and Shanghai developers now mandate third-party thermal performance guarantees for curtain wall specifications.
India
Bureau of Indian Standards certification requirements for Mumbai, Delhi, and Bangalore construction permits force import substitution toward domestic fabricators. PLI scheme incentives for building materials attract extrusion capacity investment. The Gujarat industrial corridor emerges as a thermal break assembly hub for western Indian commercial projects.
Saudi Arabia
NEOM, Red Sea Project, and Qiddiya giga-developments specify European-grade aluminum facades with accelerated delivery timelines. SFDA-equivalent building product registration streamlines import clearance for certified systems. The Eastern Province industrial zone positions fabrication capacity to serve Gulf Cooperation Council high-rise construction.
Aluminum Door and Window Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure and regional installation networks. The vendor base concentrates around systems houses with captive thermal testing laboratories and certified installer networks, while commodity extruders face margin compression from energy code upgrades. Three archetypes dominate: European heritage systems engineers, integrated Asian manufacturers, and North American project specialists. Competitive moves center on design-assist contracting capabilities and regional pre-positioning for giga-project pipelines.
Among European heritage systems engineers, Schüco and Reynaers Aluminium exemplify the performance-guaranteed facade archetype with established PHI certification pathways. YKK AP represents integrated manufacturing from extrusion through hardware integration. Kawneer occupies a position within the North American commercial project specialist tier, with concentration on large-scale metropolitan corridor developments. These three anchors illustrate how certification depth and regional installation density separate premium positioning from commodity supply.
| Leading Market Players |
|---|
| Kawneer |
| AluK |
| Schüco |
| Technal |
| Alumil |
| Reynaers Aluminium |
| Andersen Windows & Doors |
| Fenesta |
| YKK AP |
| Others |
Supply Flow & Price Mechanics
Extrusion capacity utilization above eighty percent in Chinese and German manufacturing clusters compresses margin flexibility for smaller fabricators while anchoring price floors for specification-grade thermal break systems. Scale economies in captive polyamide thermal break production reward integrated systems houses with cost advantages that commodity extruders cannot replicate, concentrating pricing power among European and Asian engineering specialists.
Pricing Analysis
Industrial OEM buyers anchor transactional pricing for mill-finish and basic powder-coated profiles, while commercial developers negotiate project-based contracts for performance-guaranteed facade systems. Three-tier pricing structure across premium, standard, and economy levels separates PHI-certified passive house configurations from code-minimum thermal break products and non-compliant commodity extrusions. Price differentiation centers on certification depth and installation network density, with NFRC-verified fabricators commanding fifteen to twenty percent premiums over uncertified competitors. Pricing pressure stems from LME aluminum volatility and polyamide supply concentration, squeezing mid-tier fabricators without backward integration into raw material supply. Residential replacement buyers exhibit highest price sensitivity, while hospitality developers prioritize performance guarantees over first-cost optimization.
Supply Chain Analysis
Polyamide thermal break strip production concentrates in Germany, China, and Austria, creating single-source vulnerability for North American window manufacturers seeking certified supply. Raw material dependencies span primary aluminum ingot from Gulf smelters, glass-fiber reinforced polyamide from European polymer specialists, and fluoropolymer coatings from Japanese chemical producers. Supply chain risk centers on REACH substance restrictions eliminating chromate conversion coatings, forcing qualification timelines for alternative surface treatments. Distribution runs through systems houses with certified installer networks for commercial projects, while residential replacement flows through regional fabricators and big-box retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal break specification upgrades are disrupting traditional fabrication models, with EPA Energy Star certification and EU F-Gas Regulation phase-downs compressing competitive windows for non-compliant suppliers. Incumbents and entrants must reposition around performance-guaranteed envelope solutions rather than commodity extrusion supply.
For Market Incumbents: Shield margin pools by deepening captive supply of certified thermal break materials and expanding NFRC-verified testing infrastructure. Acquire regional installation networks in high-growth corridors to defend against design-assist contracting specialists. Prioritize backward integration into polyamide strip production to reduce single-source exposure from European and Chinese polymer suppliers. For New Entrants and Emerging Players: Lead with smart glass integration capabilities and electrochromic glazing convergence to capture premium positioning in hospitality and commercial retrofit segments. Target Saudi giga-project pipelines and Indian BIS certification mandates as white-space opportunities where established European systems houses lack regional pre-positioning. Deploy BIM-capable engineering teams for early design-assist engagement rather than competing on bid-specify-install procurement cycles. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors systems houses with captive thermal testing laboratories and certified installer network density over commodity extruders facing margin compression. Long-term viability hinges on regulatory compliance infrastructure rather than scale alone. Acquisition target archetype: regional fabricators with established PHI or NFRC certification pathways and underutilized extrusion capacity. Watch for harmonization between national energy rating systems as the inflection signal for cross-border consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Break Production | Captive polyamide supply reduces European and Chinese import dependency for North American fabricators. |
| NFRC Certification Investment | Third-party verified U-values unlock federal tax incentive procurement for commercial developers. |
| Design-Assist Contracting Capability | BIM-compatible engineering teams capture early specification authority from Manhattan and London developers. |
| Saudi Giga-Project Pre-Positioning | Eastern Province fabrication capacity serves NEOM and Red Sea Project accelerated delivery timelines. |
| Smart Glass Integration Partnership | Electrical system capabilities differentiate aluminum framing for electrochromic glazing convergence. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented compliance trajectories. Conversations with facade engineering directors, thermal testing laboratory managers, commercial developer procurement leads, and certified installation contractors informed competitive positioning assessments. Secondary sources include EPA Energy Star certification databases, ECHA REACH substance restriction updates, BIS construction permit filings, and customs trade data for extruded aluminum profiles. Bottom-up demand modeling from project pipelines in Chicago, Mumbai, and Dubai triangulates against top-down market sizing from systems house revenue disclosures.
Sensitivity analysis across primary aluminum price scenarios and thermal break supply disruption events stress-tests volume and value projections over the analysis window. Segmentation dimensions span product type, application, material grade, and regional regulatory cluster, with CAGRs derived from installed base replacement cycles and new construction permit trajectories. Forecast inputs incorporate curtain wall retrofit demand from 1990s commercial towers and BIS mandate enforcement timelines in Indian metropolitan construction markets.
The analysis sits within stated boundaries; outcomes outside sustained LME price stability and REACH compliance pathway continuity would require recalibration. Forecasts reflect assumptions regarding certification harmonization between NFRC, PHI, and local fire-safety rating systems. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and GB standards enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Poland Architectural Coatings Market
Building Materials
India Concealed Cistern Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Pozzolana Cement Market
Building Materials
United Kingdom Architectural Coatings Market
Building Materials
Thin Brick Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Europe Dry-Mix Mortar Market
Building Materials
Shotcrete Market
Building Materials
Europe Fiber Cement Market
Building Materials
Drywall Joint Tape Market
Building Materials
US Cement Tiles Market
Building Materials
Radiant Barriers and Reflective Insulation Market