
 Global Building Panels Market | 2026-2036
Global Building Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Building Panels Market Analysis
Cross-laminated timber is consolidating share in mid-rise structural applications as engineered wood products displace conventional concrete and steel on cost-per-square-foot and carbon-intensity metrics. Owens Corning leverages vertical integration from glass fiber through insulation-facing to sustain margin capture across the thermal envelope stack. Saint-Gobain anchors European specification through gypsum and glass wool combinations that dominate multi-family retrofit programs. Kingspan Group plc differentiates via controlled-environment panel systems that occupy leadership in cold-chain and cleanroom construction segments.
Building panels are factory-manufactured planar assemblies—typically spanning 600 mm to 1,200 mm in module width, with R-values ranging from R-11 to R-60 depending on core material and thickness—engineered for structural, insulating, or finishing functions in vertical and horizontal building envelopes. Their primary purpose is to accelerate on-site assembly, reduce thermal bridging, and enable performance predictability in both new construction and deep-energy retrofit contexts. Composite panels lead product type value contribution due to multi-attribute performance integration, while metal panels compete aggressively on speed-of-erection in commercial and industrial end uses. Modular construction and panelized systems represent the fastest-growing installation method category as labor scarcity and schedule compression reshape procurement patterns across residential and commercial verticals.
The EU Green Deal and F-Gas Regulation shape product chemistry and thermal performance thresholds for panels sold across Europe, while China's GB standards and dual carbon goals enforce energy-efficiency minimums that redirect domestic manufacturing toward higher-insulation core configurations. The EPA and OSHA in the United States govern formaldehyde emissions and workplace fabrication exposures, respectively, adding compliance layers that favor scaled producers with certified quality systems. Stakeholders must monitor regulatory divergence between jurisdictions, as divergent carbon-accounting rules and embodied-carbon disclosure requirements will increasingly determine which panel technologies qualify for public procurement and green-financing channels.
Market Dynamics
Urban densification across Asia-Pacific is compressing construction timelines and redirecting specification toward factory-manufactured envelope assemblies that eliminate on-site thermal bridging.
Growth Catalysts
- EU Green Deal thermal codes:Stringent energy-efficiency mandates under the F-Gas Regulation and Building Renovation Passport framework are redirecting commercial specification toward high-performance insulated metal composite systems across Germany, France, and the Netherlands.
- Cross-laminated timber engineering:Engineered wood products are capturing mid-rise structural applications as carbon-accounting rules in public procurement favor lower-embodied-carbon alternatives to conventional concrete and steel framing.
- China's dual carbon goals:GB standards enforcement is accelerating domestic manufacturing reconfiguration toward higher-R-value core configurations in insulated panel production for cold-chain logistics facilities.
Market Restraints
- Polyisocyanurate feedstock volatility:Fluctuating MDI and polyol pricing compresses margin predictability for insulated metal panel producers dependent on petrochemical-derived core materials.
- Glass fiber supply concentration:Owens Corning and a limited set of European suppliers control high-performance glass wool facing supply, creating bottleneck risk for second-tier panel assemblers.
- Formaldehyde emission compliance:EPA TSCA Title VI and CARB ATCM Phase 2 create cross-border certification friction for wood-based panel imports into the United States.
Strategic Opportunities
- India's affordable housing shortfall:The Pradhan Mantri Awas Yojana and PMAY-Urban 2.0 create volume demand for prefabricated concrete sandwich panels in 100+ smart city developments.
- Cleanroom and cold-chain convergence:Controlled-environment panel systems are penetrating pharmaceutical manufacturing and biologics storage as GMP compliance tightens across FDA and EMA jurisdictions.
- Direct-to-developer digital platforms:B2B procurement marketplaces are disintermediating traditional distributor networks for standardized metal panel specifications in industrial warehouse construction.
Industry Challenges
- Building envelope commissioning expertise:Shortage of certified thermographers and blower-door technicians delays performance verification for high-R-value assemblies in deep-energy retrofits.
- Multi-material integration complexity:Coordinating structural, fire-resistance, and thermal performance certifications across gypsum, mineral wool, and metal composite layers extends product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Building Panels Market |
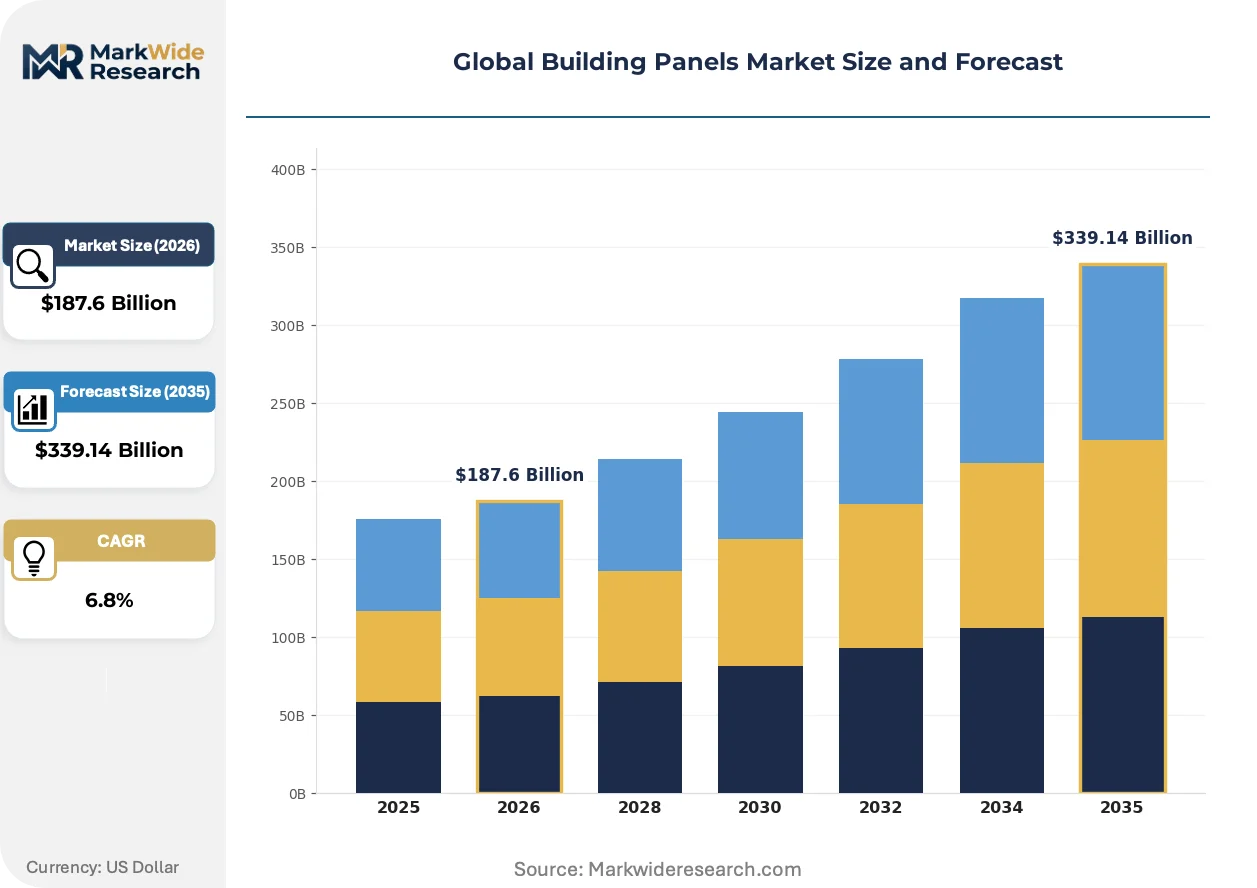
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $339.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Panels, Plastic Panels, Wood Panels, Composite Panels End User: Residential, Commercial, Industrial, Agricultural Insulation Type: Thermal Insulation, Acoustic Insulation, Fireproofing, Vapor Barriers Installation Method: Panelized Systems, Prefabricated Units, Modular Construction, Traditional Installation |
| Companies Covered | Kingspan Group plc, Owens Corning, Saint-Gobain, BASF SE, Nucor Corporation, Rockwool International A/S, CRH plc, ArcelorMittal S.A., Fletcher Building Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Building Panels Market Emerging Trajectories
Material chemistry and fabrication automation are converging to compress panel-to-panel variation and enable mass-customization of envelope assemblies without sacrificing thermal predictability.
Vacuum-insulated panels are absorbing market attention in ultra-high-performance applications where space constraints override cost sensitivity. Healthcare and laboratory end-users in Switzerland and Japan are specifying VIP cores for R-60 equivalent performance in sub-100mm thickness. This technology is absorbing specification share from conventional polyurethane cores in premium segments where envelope depth is physically constrained.
REACH Annex XVII restrictions on flame retardants are forcing reformulation of polystyrene and polyurethane core chemistries across European manufacturing. Producers are migrating to halogen-free intumescent systems and mineral wool hybrid configurations to maintain CE marking compliance. The multi-family retrofit segment in Germany and Austria is experiencing the most acute specification disruption as existing inventory faces re-certification.
Design-build firms are consolidating supplier relationships around single-source envelope responsibility to compress warranty fragmentation. Industrial warehouse developers in the United States are shifting from component procurement to performance-contracting with panel system integrators who assume thermal bridging liability. This behavioral pivot is most visible in Texas and Arizona markets where speed-to-occupancy drives developer economics.
Global Building Panels Market Segmentation
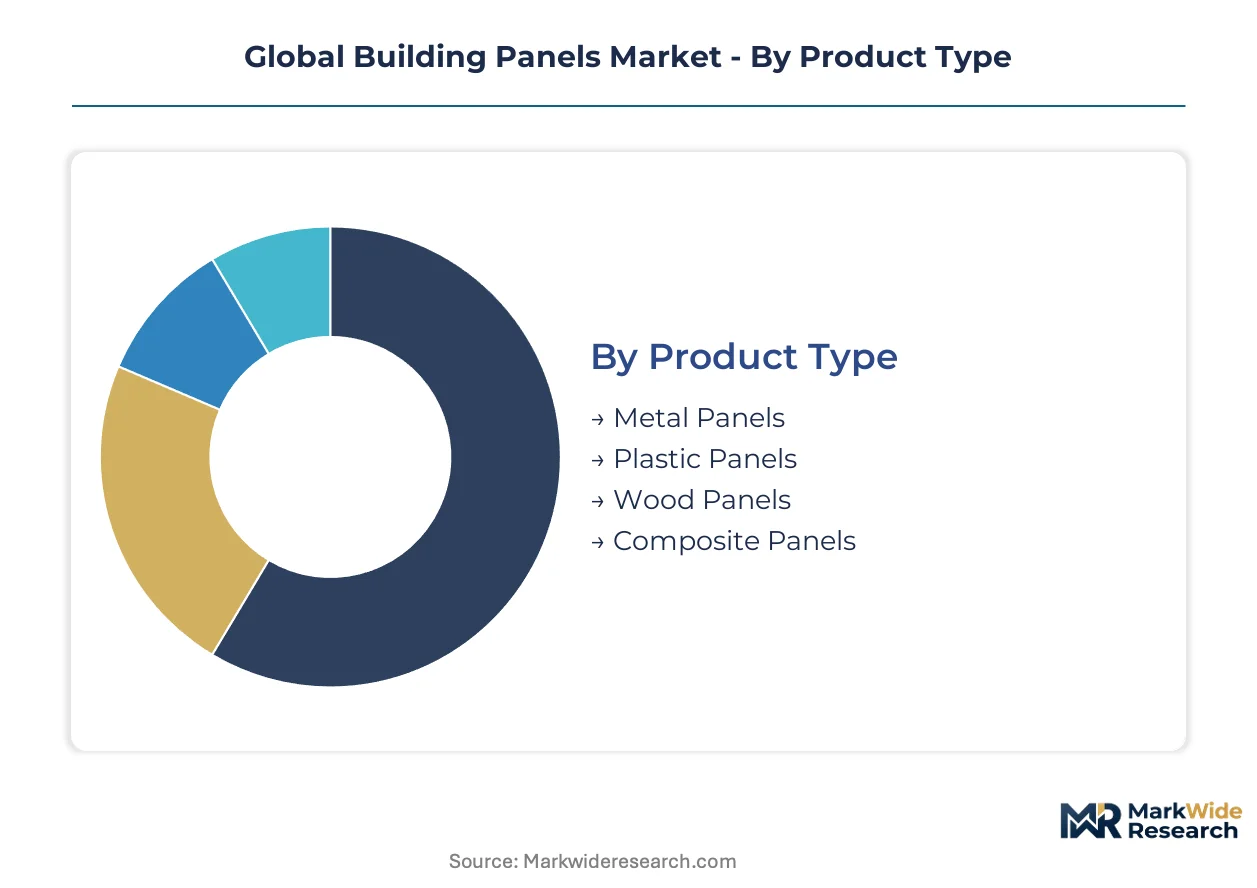
Segmentation in building panels reveals how capital deployment, regulatory exposure, and labor economics fragment procurement patterns across envelope technologies. Manufacturers align production assets against specific performance tiers rather than pursuing horizontal coverage.
Product Type:
Capital intensity varies sharply across material platforms, with continuous metal coil processing and composite lamination lines demanding the heaviest upfront investment.
- Composite Panels:Multi-layer assemblies bonding metal skins to insulating cores achieve R-values from R-30 to R-60 in thicknesses under 150mm. Cold-chain logistics facilities in Germany and the Netherlands specify these for thermal predictability under EMA temperature-compliance protocols.
- Metal Panels:Single-skin and insulated metal configurations dominate speed-critical commercial construction. Warehouse developers in Texas and Arizona procurement channels favor these for 30-day envelope closure timelines.
- Wood Panels:Cross-laminated timber and oriented strand board serve structural and finish functions with lower embodied carbon than mineral alternatives.
- Plastic Panels:Polycarbonate and PVC formulations occupy daylighting and hygienic interior applications where moisture resistance outweighs structural loading requirements.
Composite panels absorb the bulk of installed capacity; metal panels are expanding most quickly in industrial verticals.
End User:
Customer procurement sophistication determines specification depth, with commercial developers maintaining the most stringent performance-contracting relationships.
- Commercial:Office, retail, and hospitality envelopes demand integrated fire-resistance, thermal, and acoustic certifications. Design-build firms in the United States consolidate single-source envelope responsibility to compress warranty fragmentation across these multi-attribute assemblies.
- Residential:Single-family and multi-family construction segments prioritize cost-per-square-foot and schedule compression. India's Pradhan Mantri Awas Yojana channels volume demand toward prefabricated concrete sandwich panels in smart city developments.
- Industrial:Manufacturing and warehouse facilities specify metal panel systems for column-free spans and rapid erection.
- Agricultural:Controlled-environment structures for livestock and crop production utilize lower-specification insulated panels with emphasis on corrosion resistance.
Commercial end-use commands specification authority; residential applications are climbing the fastest as urban densification accelerates across Asia-Pacific markets.
Insulation Type:
Regulatory chemistry restrictions are forcing core material reconfiguration, with thermal performance mandates and flame-retardant bans reshaping manufacturing investment.
- Thermal Insulation:Polyurethane, polyisocyanurate, and mineral wool cores deliver R-value density for energy-code compliance. China's GB standards enforcement redirects domestic production toward higher-R-value configurations for cold-chain logistics.
- Fireproofing:Mineral wool and intumescent systems satisfy fire-resistance ratings for high-occupancy structures. REACH Annex XVII restrictions on halogenated flame retardants drive reformulation costs across European manufacturing.
- Acoustic Insulation:Resilient channel and mass-loaded barrier systems address STC requirements in multi-family and healthcare construction.
- Vapor Barriers:Polyethylene and aluminum-faced membranes control moisture drive in high-humidity climate zones.
Thermal insulation holds the largest installed base; fireproofing cores are gaining share fastest as code enforcement tightens across EU and North American jurisdictions.
Installation Method:
Labor scarcity and schedule risk are redistributing value capture from field installation toward factory fabrication and system integration.
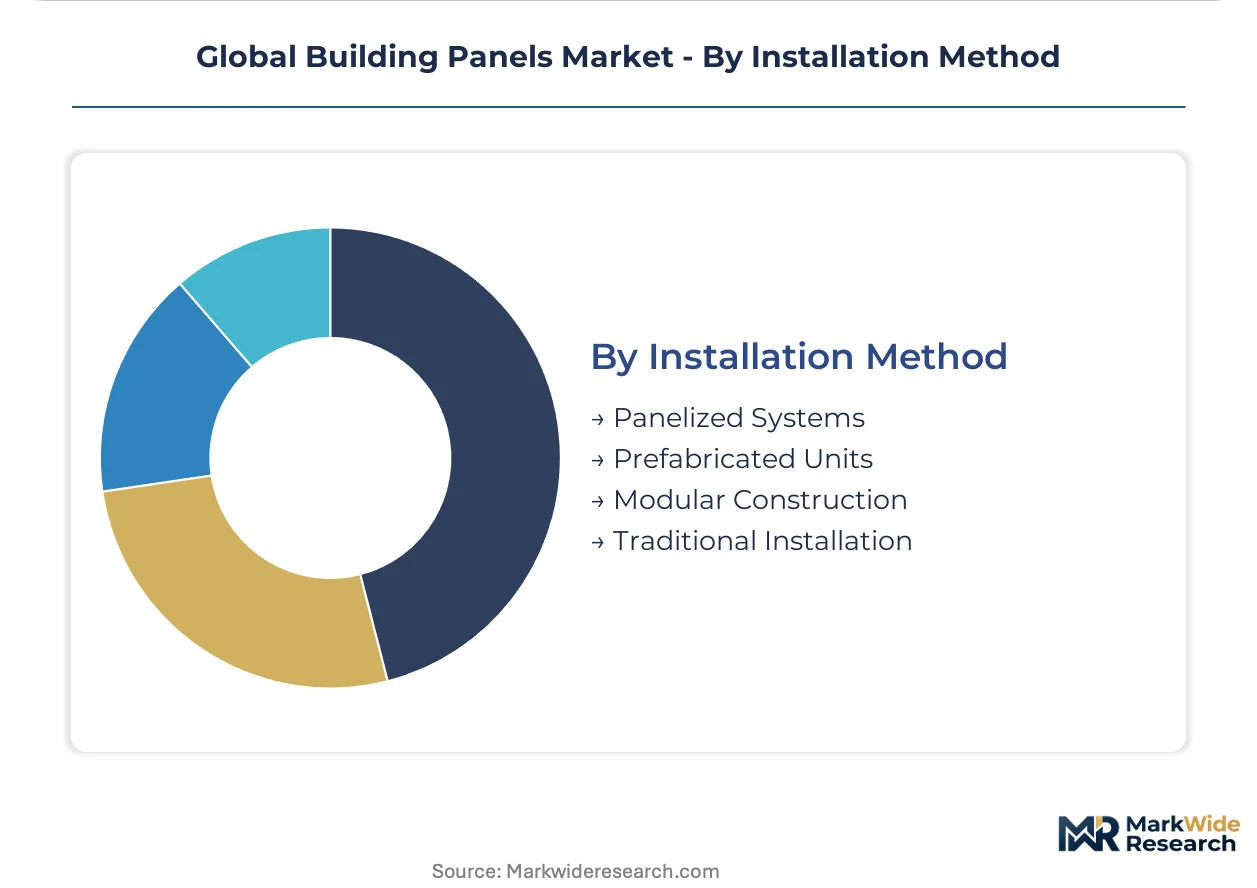
- Modular Construction:Volumetric units with pre-installed envelope panels compress site labor by 50-70% versus stick-built alternatives. Healthcare and hospitality developers in Japan and Switzerland specify these for GMP and seismic compliance.
- Panelized Systems:Flat-packed wall and roof assemblies ship to site for crane-assisted erection. B2B procurement marketplaces are disintermediating traditional distributor networks for standardized metal panel specifications in United States industrial warehouse construction.
- Prefabricated Units:Bathroom pods and plant rooms with integrated MEP reduce trade coordination complexity.
- Traditional Installation:Site-built framing with applied insulation and finish materials retains share in renovation and custom residential projects.
Panelized systems retain the largest deployment volume; modular construction is expanding most quickly as labor costs and schedule certainty reshape developer economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China, India, Germany, and the United States as urban densification and retrofit cycles intensify across these construction-intensive economies.
China
Cold-chain logistics facilities and smart city developments drive specification of insulated metal composite systems. GB standards enforcement under dual carbon goals redirects domestic manufacturing toward higher-R-value core configurations. Yangtze River Delta manufacturing clusters near Shanghai scale production of vacuum-insulated panels for premium envelope applications.
Germany
Multi-family retrofit programs and commercial new-build specifications absorb the bulk of European composite panel volume. EU Green Deal thermal codes and F-Gas Regulation mandate halogen-free core chemistries for CE marking compliance. Industrial clusters in Bavaria and North Rhine-Westphalia specialize in fire-resistant mineral wool hybrid configurations for high-occupancy structures.
United States
Industrial warehouse developers in Texas and Arizona prioritize speed-of-erection metal panel systems for 30-day envelope closure timelines. EPA TSCA Title VI and OSHA workplace exposure rules add compliance layers that favor scaled producers with certified quality systems. Southeast construction corridors from Florida to Georgia channel residential panelized system demand as labor scarcity reshapes procurement.
India
Pradhan Mantri Awas Yojana and PMAY-Urban 2.0 create volume demand for prefabricated concrete sandwich panels across 100-plus smart city developments. BIS certification requirements and state-level building codes enforce minimum thermal performance for affordable housing envelopes. Maharashtra and Gujarat industrial corridors scale domestic manufacturing capacity to reduce import dependency for core insulating materials.
Japan
Healthcare and hospitality developers specify modular volumetric units with pre-installed envelope panels for GMP and seismic compliance. METI energy-efficiency standards and JIS certification frameworks govern panel performance in high-density urban construction. Kanto region manufacturing clusters around Tokyo refine vacuum-insulated panel production for space-constrained premium applications.
Global Building Panels Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with vertically integrated material producers commanding premium specification in thermal envelope applications while regional fabricators compete on speed and customization. The vendor base organizes around three strategic archetypes: integrated chemical-to-panel producers controlling core material supply, specialized envelope system integrators assuming single-source warranty responsibility, and regional metal coil processors serving speed-critical industrial construction. Competitive moves concentrate on backward integration into glass fiber and mineral wool supply, and design-build partnership structures that transfer thermal bridging liability to panel system providers.
Among Europe-based material conglomerates, Saint-Gobain S.A. and BASF SE exemplify the integrated chemical-to-panel archetype through captive supply of gypsum, glass wool, and polyurethane core chemistries. Kingspan Group plc occupies a position within the specialized system integrator tier, with controlled-environment panel systems anchoring its presence in cold-chain and cleanroom construction segments. Owens Corning represents the upstream-controlled model, leveraging in-house production of glass fiber through insulation-facing to sustain margin capture across the thermal envelope stack.
| Leading Market Players |
|---|
| Kingspan Group plc |
| Owens Corning |
| Saint-Gobain |
| BASF SE |
| Nucor Corporation |
| Rockwool International A/S |
| CRH plc |
| ArcelorMittal S.A. |
| Fletcher Building Limited |
| Others |
Supply Flow & Price Mechanics
Factory automation in continuous metal coil processing is compressing unit economics while concentrating production capacity among capital-intensive producers who can amortize lamination line investments across multi-shift operations. This technological shift simultaneously reduces per-panel labor content and raises barriers to entry for regional fabricators lacking scale.
Pricing Analysis
Volume contracts in industrial warehouse construction command 15-25% discounts against spot procurement for comparable metal panel specifications. Price differentiation hinges on thermal performance certification tier and geographic delivery radius from manufacturing clusters. Cost compression in standard-grade polyurethane cores is intensifying because MDI feedstock volatility erodes margin predictability for second-tier assemblers. Residential developers in India exhibit the highest price sensitivity, while pharmaceutical cleanroom operators in Switzerland and Japan accept substantial premiums for vacuum-insulated panel performance guarantees.
Supply Chain Analysis
Reverse logistics for end-of-life panel recovery remains underdeveloped, with limited refurbishment infrastructure for metal skins and mineral wool core reclamation. Manufacturing draws from glass fiber supply concentrated in the United States and Germany, polyurethane chemical feedstocks anchored in China and the Netherlands, and steel coil production centered in India and Japan. Single-source vulnerability in high-performance glass wool facing creates bottleneck exposure for European panel assemblers dependent on Owens Corning and a limited supplier set. Distribution runs through design-build firms consolidating single-source envelope responsibility and B2B procurement platforms disintermediating traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in building panels is becoming a vertical-integration race, with producers capturing margin across glass fiber, core chemistry, and system integration layers to defend against feedstock volatility and specification commoditization.
For Market Incumbents: Anchor specification authority through captive supply of mineral wool and polyurethane core chemistries, mirroring Saint-Gobain's gypsum-to-insulation integration. Invest in certified quality systems to satisfy EPA TSCA Title VI and REACH Annex XVII compliance friction that disadvantages smaller importers. Defend against cross-laminated timber substitution by embedding carbon-accounting transparency into product documentation for public procurement channels. For New Entrants and Emerging Players: Launch via direct-to-developer digital platforms targeting standardized metal panel procurement in United States industrial warehouse construction, where speed-of-erection specifications favor new supply relationships. Exploit India's Pradhan Mantri Awas Yojana volume demand for prefabricated concrete sandwich panels in smart city developments, where domestic manufacturing capacity lags housing shortfall targets. Target cold-chain logistics facility developers in China seeking higher-R-value core configurations under GB standards enforcement. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated material conglomerates seeking thermal envelope stack coverage, with strategic value accruing to targets possessing certified European manufacturing and halogen-free core formulation capabilities. Five-to-ten year viability favors producers with backward integration into glass fiber or mineral wool supply, insulating margin capture from petrochemical feedstock cycles. Monitor REACH Annex XVII flame retardant restriction expansion and China's dual carbon goal enforcement intensity as inflection indicators for core chemistry reconfiguration investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glass Fiber Supply | Owens Corning's in-house fiber production sustains margin capture across thermal envelope applications. |
| Halogen-Free Core Chemistry Reformulation | REACH Annex XVII compliance investment separates CE-marked European producers from import-dependent competitors. |
| Design-Build Partnership Structures | Single-source envelope responsibility transfers thermal bridging liability to panel system integrators in Texas and Arizona markets. |
| Direct-to-Developer Digital Platform Launch | B2B procurement marketplaces disintermediate distributor networks for standardized industrial warehouse specifications. |
| Vacuum-Insulated Panel Production Scale-Up | R-60 equivalent performance in sub-100mm thickness commands premium specification in Swiss and Japanese healthcare construction. |
Methodological Framework
Document review covered regulatory filings with EPA, ECHA, and BIS, complemented by interviews with plant managers at composite panel manufacturers, procurement leads at cold-chain logistics developers, technical R&D directors at insulation material producers, and design-build firm envelope specification directors. Secondary validation drew from customs and trade data, EU Green Deal implementation reports, SEC 10-K disclosures from listed building material conglomerates, and GB standards enforcement documentation from China's Ministry of Ecology and Environment. Bottom-up demand modeling across end-use segments was triangulated against top-down macro construction expenditure projections.
The analytical framework produced volume and value estimates segmented by product type, insulation core chemistry, end-use vertical, installation method, and regional regulatory cluster across the projection horizon. CAGRs were derived from regression analysis of historical construction expenditure elasticities and policy-driven retrofit cycle timing. Industry-specific forecast inputs included thermal code stringency trajectories under EU Green Deal implementation and China's dual carbon goal enforcement intensity for cold-chain logistics facility construction.
The model assumes a particular technology adoption path for vacuum-insulated panel manufacturing scale-up; alternative pathways for mineral wool hybrid core development would alter the outlook for premium envelope segment capture. Forecasts reflect assumptions regarding REACH Annex XVII flame retardant restriction scope expansion and GB standards enforcement consistency. Practitioners should monitor MDI and polyol feedstock pricing volatility, cross-laminated timber engineering cost curves, and design-build firm procurement consolidation patterns for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Cross Laminated Timber (CLT) Market
Building Materials
India Aluminum Door and Window Market
Building Materials
Composite Rebar Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Sanded Grout Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Geocells Market
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Block Paving Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
Global FRP Rebar Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Asia-Pacific Cement Market
Building Materials
South Africa White Cement Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Global Lightweight Aggregate Concrete Market