
 Indonesia Concrete Admixtures Market | 2026-2036
Indonesia Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Concrete Admixtures Market Insights
Asset-light leasing models for batching plant equipment is narrowing the capital barrier for mid-tier contractors seeking specification-grade admixture supply contracts. PT Sika Indonesia leverages its Swiss parent company's R&D pipeline to sustain technology leadership in polycarboxylate superplasticizers. PT BASF Indonesia anchors its position through backward integration into local ethoxylate production, reducing import dependency for key raw materials. PT Master Builders Solutions Indonesia differentiates via dedicated technical service teams embedded at major infrastructure job sites.
Concrete admixtures are chemical formulations—typically lignosulfonates, naphthalene sulfonates, or polycarboxylate ethers—dosed at 0.5% to 3% by weight of cement to modify rheology, set time, or durability performance in fresh and hardened concrete. Their primary industrial purpose is enabling high-strength, low-permeability concrete placements under tropical conditions where ambient temperatures accelerate slump loss and hydration kinetics. Superplasticizers command the dominant share of product value due to their role in self-compacting and high-performance concrete specifications for Nusantara infrastructure. Infrastructure Projects represent the fastest-growing application channel as state-backed toll roads, ports, and the new capital city absorb premium admixture volumes. Residential Construction remains a mature, price-sensitive segment where commodity retarding and accelerating admixtures compete on distributor margins.
BIS-equivalent Indonesian National Standards (SNI) for construction chemicals, enforced by the Ministry of Public Works and Housing, mandate third-party certification for admixtures used in public infrastructure tenders. The Ministry of Industry's domestic content requirements (TKDN) shape procurement eligibility for state-funded projects, favoring local blending operations over direct imports. Stakeholders must monitor how TKDN threshold adjustments and SNI testing protocol updates will reshape supplier qualification requirements and raw material sourcing strategies.
Market Dynamics
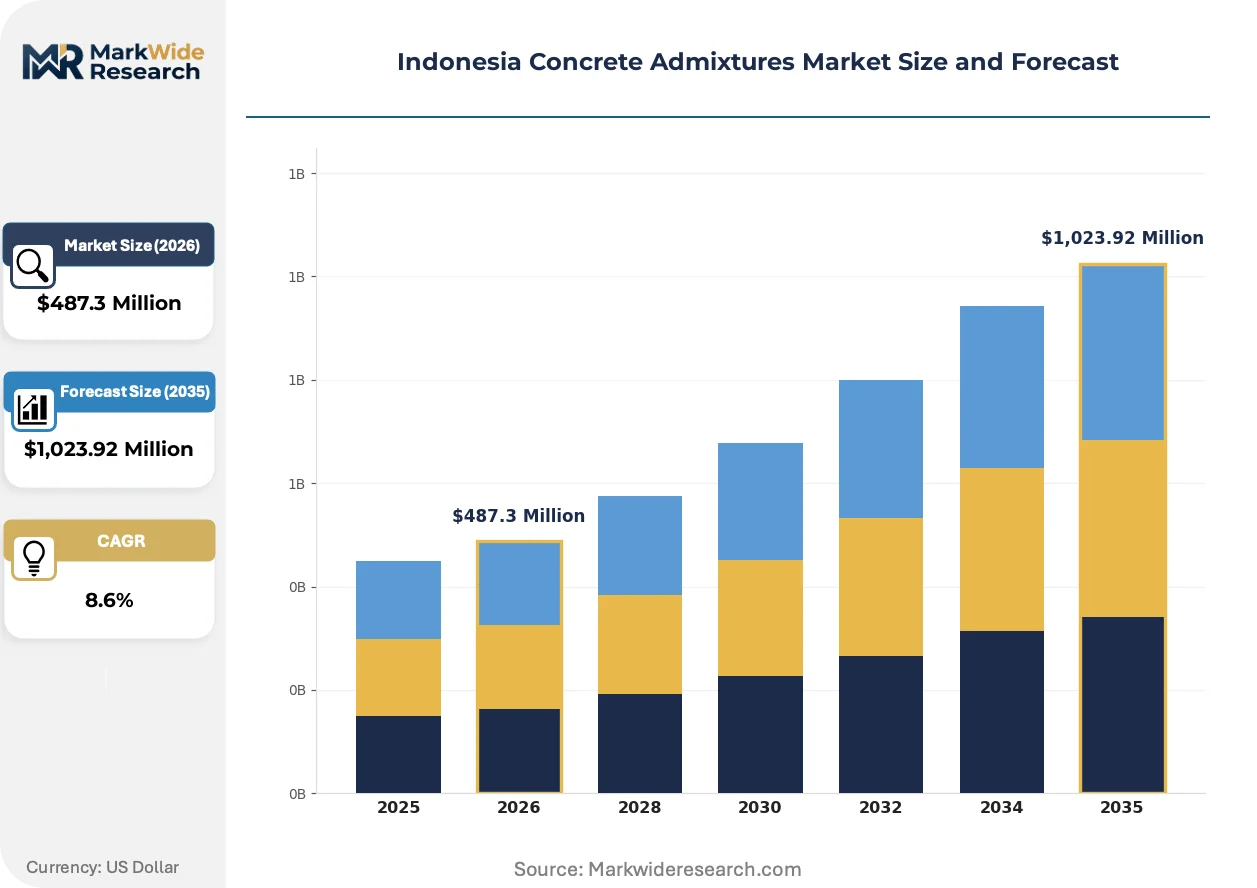
The Indonesia concrete admixtures market is being fundamentally restructured by the Ministry of Industry's tightening domestic content requirements (TKDN), which are forcing multinational suppliers to localize blending operations and raw material sourcing to maintain eligibility for state-funded infrastructure tenders.
Growth Catalysts
- Nusantara Capital Development:The government's new capital city megaproject mandates high-performance concrete specifications that require polycarboxylate superplasticizers, creating guaranteed demand volumes for qualified admixture suppliers.
- SNI Certification Mandates:The Ministry of Public Works and Housing now requires third-party certification for all construction chemicals used in public infrastructure, eliminating unqualified competitors and formalizing procurement channels.
- Tropical Climate Engineering:Ambient temperatures exceeding 30°C across Java's construction corridor accelerate slump loss in fresh concrete, making chemical admixtures indispensable for workable placements in high-rise and infrastructure applications.
Market Restraints
- Ethoxylate Import Dependency:Key raw materials for polycarboxylate ether production remain concentrated in Singapore and Thailand, exposing local blenders to freight cost volatility and currency fluctuation risks.
- TKDN Compliance Thresholds:The Ministry of Industry's domestic content calculations exclude imported active ingredients, creating a structural ceiling on product localization that caps margin expansion for multinational suppliers.
- Commodity Admixture Substitution:Price-sensitive residential contractors in peripheral Java markets continue substituting specification-grade superplasticizers with lignosulfonate-based alternatives, compressing addressable market value in the volume segment.
Strategic Opportunities
- Sulawesi and Kalimantan Infrastructure:Nickel processing facilities and smelter construction in Morowali and North Kalimantan are generating first-time demand for corrosion-inhibiting admixtures in industrial concrete specifications.
- Technical Service Embedding:Major contractors on Nusantara and Trans-Java toll road projects are accepting dedicated on-site admixture laboratories, shifting supplier relationships from transactional to partnership-based retainers.
- Biomass-Derived Raw Materials:Palm oil fatty acid methyl ester streams from Indonesia's oleochemical industry offer a pathway to locally sourced raw materials that would satisfy TKDN requirements for renewable content claims.
Industry Challenges
- Formulation Chemist Shortage:Local universities produce limited graduates with concrete rheology expertise, forcing suppliers to import technical talent or fund extended on-the-job training programs.
- SNI Testing Protocol Delays:The certification backlog at Ministry-authorized laboratories extends product qualification timelines by four to six months, delaying project-specific approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Concrete Admixtures Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,023.92 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superplasticizers, Retarding Admixtures, Accelerating Admixtures, Air-Entraining Agents Application: Residential Construction, Infrastructure Projects, Commercial Buildings, Industrial Applications End User: Contractors, Construction Companies, Engineers, Developers Distribution Channel: Online Sales, Direct Sales, Retail Distribution, Wholesale Distributors |
| Companies Covered | PT BASF Indonesia, PT Sika Indonesia, PT Chryso Indonesia, PT GCP Applied Technologies Indonesia, PT Master Builders Solutions Indonesia, Holcim Apasindo, PT Holcim Indonesia Tbk, PT Indocement Tunggal Prakarsa Tbk, PT Semen Indonesia (Persero) Tbk, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Concrete Admixtures Market Trends and Innovations
Technology migration and procurement restructuring are compressing traditional supply hierarchies in Indonesia's admixture sector. Three interconnected developments are redefining competitive positioning and customer relationships.
Polycarboxylate ether (PCE) superplasticizer technology is migrating from naphthalene sulfonate formulations in high-performance concrete applications. State-backed infrastructure contractors on Nusantara and Trans-Java projects now specify PCE-based self-compacting concrete for complex formwork geometries. This shift is compressing the viable product portfolio for suppliers unable to localize PCE synthesis or secure captive ethoxylate supply.
The Ministry of Public Works and Housing is incrementally harmonizing SNI admixture standards with ASEAN Mutual Recognition Arrangements, creating pressure for testing protocol alignment across Indonesia, Malaysia, and Thailand. Industrial consequence includes accelerated laboratory accreditation investments by multinational suppliers seeking cross-border certificate portability. Infrastructure segments with multi-national contractor consortia are responding fastest, demanding documentation packages that satisfy multiple national standard sets.
Asset-light batching plant leasing is fragmenting contractor capital deployment and altering admixture procurement accountability. Mid-tier construction firms now access specification-grade concrete production without owning fixed plant, shifting admixture specification authority from contractor technical staff to ready-mix supplier quality departments. This pattern concentrates most visibly in Greater Jakarta's peripheral development zones where project-scale volatility discourages capital commitment.
Indonesia Concrete Admixtures Market Segmentation
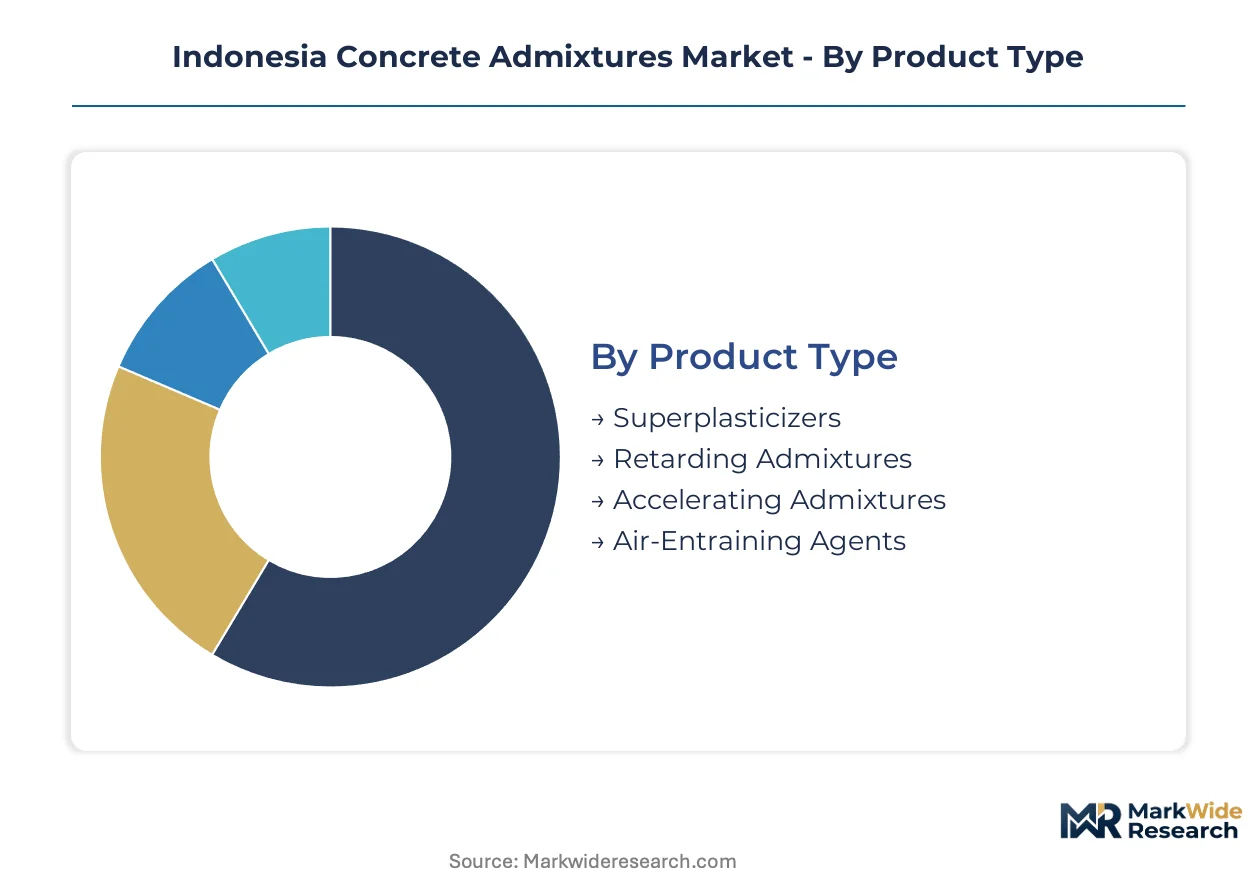
Segmentation in Indonesia's concrete admixtures market reveals how procurement authority, technical requirements, and project scale fragment demand across distinct commercial channels. Understanding these divisions exposes where specification-grade products command premium positioning versus commodity-grade competition.
Product Type:
Superplasticizers turn inventory fastest due to Nusantara infrastructure specifications, while air-entraining agents move slowest with seasonal demand tied to monsoon-exposed placements.
- Superplasticizers:Polycarboxylate ether and naphthalene sulfonate formulations enable high-slump concrete for complex formwork. Demand concentrates in Nusantara and Trans-Java toll road projects where self-compacting specifications are mandatory.
- Retarding Admixtures:Lignosulfonate and hydroxycarboxylic acid compounds delay hydration kinetics in tropical heat. Mass concrete placements for dam foundations and deep foundations in Greater Jakarta absorb the majority of volumes.
- Accelerating Admixtures:Calcium chloride and non-chloride formulations compress set times for cold-weather or fast-track schedules. Tunnelling contractors on Jakarta-Bandung high-speed rail extensions specify these for rapid formwork cycling.
- Air-Entraining Agents:Vinsol resin and synthetic surfactant formulations stabilize freeze-thaw durability in exposed concrete. Coastal infrastructure in Surabaya and Makassar generates intermittent procurement spikes during dry-season construction windows.
Superplasticizers anchor the volume base while accelerating admixtures gain share at the steepest rate.
Application:
Cost tiering separates specification-grade infrastructure demand from price-sensitive residential procurement, with commercial buildings occupying a contested middle band.
- Infrastructure Projects:State-backed toll roads, ports, and Nusantara capital works mandate certified admixtures with embedded technical service. Ministry of Public Works and Housing tenders enforce SNI compliance and TKDN thresholds.
- Residential Construction:Peripheral Java housing estates and mid-rise apartments prioritize cost minimization over performance optimization. Distributor margins compress as contractors substitute lignosulfonates for polycarboxylate formulations.
- Commercial Buildings:High-rise offices and retail complexes in Jakarta CBD and Surabaya's financial district balance aesthetic finish requirements with budget discipline. Ready-mix suppliers often dictate admixture selection through batching plant partnerships.
- Industrial Applications:Nickel smelters in Morowali and coal terminals in Kalimantan specify corrosion-inhibiting and sulfate-resistant formulations. First-time demand from Sulawesi mining infrastructure is expanding the addressable market beyond Java.
Infrastructure Projects absorb the highest value concentration while Industrial Applications expand most quickly.
End User:
Customer type determines whether procurement flows through technical specification or commercial negotiation, with engineers and contractors occupying opposing poles of influence.
- Contractors:Tier-1 infrastructure contractors on Nusantara and Trans-Java projects embed admixture laboratories on-site. Partnership-based retainers with technical service obligations replace transactional purchasing.
- Construction Companies:Mid-tier firms accessing leased batching plants delegate admixture selection to ready-mix suppliers. Quality department preferences override contractor technical staff in peripheral Jakarta development zones.
- Engineers:Consulting firms specifying concrete mix designs for public infrastructure enforce SNI certification requirements. Their technical approvals gate supplier eligibility before commercial terms are negotiated.
- Developers:Commercial and residential project sponsors prioritize total installed cost over per-unit admixture pricing. Volume commitments across multiple projects enable consolidated procurement leverage.
Contractors anchor the volume base while Engineers gain procurement influence at the steepest rate.
Distribution Channel:
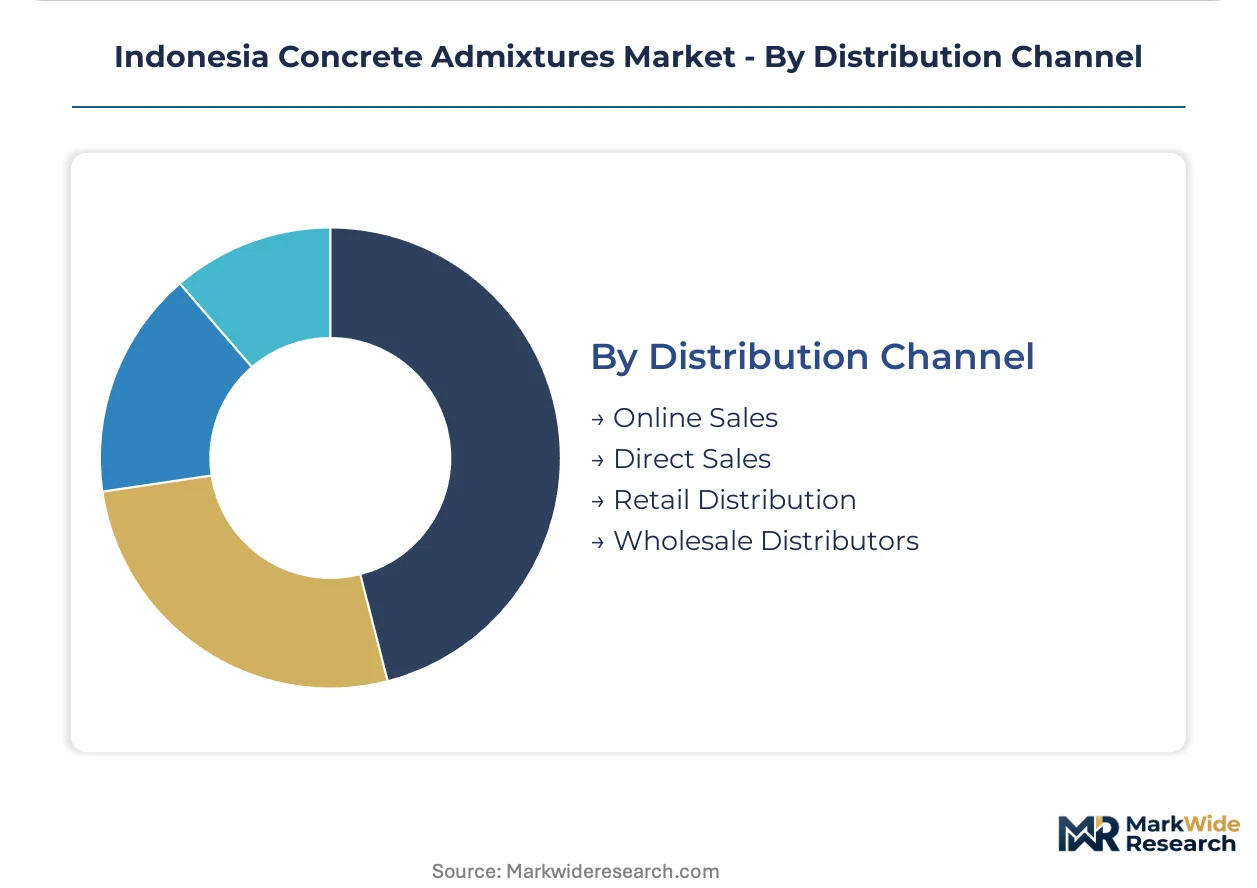
Supply concentration in Java's construction corridor shapes channel viability, with direct sales dominating specification-grade flows and wholesale handling commodity volumes.
- Direct Sales:Multinational suppliers maintain dedicated account teams for Nusantara and Trans-Java infrastructure contractors. Technical service embedding and on-site laboratory support justify relationship-based pricing.
- Wholesale Distributors:Regional distributors in Surabaya and Semarang aggregate demand from mid-tier contractors and smaller ready-mix operators. Inventory pooling reduces freight costs for peripheral Java projects.
- Retail Distribution:Construction chemical retailers in Greater Jakarta serve residential contractors and repair specialists. Shelf-stable retarding and accelerating admixtures dominate this channel's product mix.
- Online Sales:Digital procurement platforms are emerging for standardized commodity formulations in residential and light commercial segments. TKDN documentation and SNI certification verification remain friction points for specification-grade transactions.
Direct Sales anchors the value base while Wholesale Distributors expand geographical coverage at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's concrete admixtures trade remains import-dependent for specialty ethoxylates and active ingredients, while domestic blending capacity concentrates in Java's industrial corridor to serve Nusantara and Trans-Java infrastructure demand.
Java
Nusantara capital development and Trans-Java toll road extensions absorb specification-grade polycarboxylate superplasticizers at volumes unmatched elsewhere. The Ministry of Public Works and Housing enforces SNI certification for all public infrastructure admixtures, tightening supplier qualification. Greater Jakarta, Surabaya, and the emerging Nusantara zone form a continuous demand corridor where ready-mix suppliers and dedicated technical service teams co-locate.
Sumatra
Palm oil processing infrastructure and port expansion in Medan and Palembang generate steady demand for retarding and accelerating admixtures in mass concrete placements. The Ministry of Industry's TKDN domestic content requirements shape procurement eligibility for state-funded projects, favoring local blending over direct imports. Batam's industrial zone hosts multinational chemical operations that supply ethoxylate precursors to Java-based blenders.
Sulawesi
Nickel smelter construction in Morowali and Konawe is creating first-time demand for corrosion-inhibiting admixtures in industrial concrete specifications. Central Sulawesi's mining infrastructure boom operates under relaxed TKDN thresholds for strategic mineral projects, accelerating foreign supplier entry. The Morowali Industrial Park anchors this expansion with integrated logistics supporting bulk chemical imports.
Kalimantan
Coal terminal expansion and new capital city supply chain logistics in East Kalimantan are pulling admixture demand eastward from Java's manufacturing base. The Ministry of Public Works and Housing extends SNI certification requirements to Kalimantan infrastructure tenders, formalizing procurement channels. Balikpapan and Samarinda serve as distribution hubs for industrial applications in mining and energy infrastructure.
Bali and Eastern Indonesia
Tourism infrastructure recovery in Bali and geothermal power projects in Flores generate intermittent demand for specialty admixtures in aggressive environments. The national standards body extends SNI testing protocols to regional laboratories, reducing qualification delays for remote projects. Denpasar and Kupang function as procurement nodes where distributor networks aggregate fragmented construction activity.
Indonesia Concrete Admixtures Market Competitive Landscape
On the supply side, the industry is bifurcated between multinational chemical majors with captive R&D pipelines and domestic blenders competing on TKDN compliance and distributor reach. Three strategic archetypes dominate: technology leaders leveraging parent-company research, integrated producers controlling upstream ethoxylate supply, and service-oriented specialists embedding technical teams at major job sites. Capacity localization and SNI certification acceleration represent the dominant competitive moves, with second-tier players pursuing asset-light batching plant partnerships to bypass capital barriers.
Within the multinational tier, PT BASF Indonesia, PT Sika Indonesia, and PT Master Builders Solutions Indonesia occupy positions that exemplify divergent strategic orientations. BASF's German parentage suggests integrated production capabilities, Sika's Swiss origins align with specialty chemical positioning, and Master Builders Solutions represents the technical service-embedded model. These three anchors demonstrate how foreign-owned entities navigate TKDN compliance through varying degrees of local blending and raw material sourcing.
| Leading Market Players |
|---|
| PT BASF Indonesia |
| PT Sika Indonesia |
| PT Chryso Indonesia |
| PT GCP Applied Technologies Indonesia |
| PT Master Builders Solutions Indonesia |
| Holcim Apasindo |
| PT Holcim Indonesia Tbk |
| PT Indocement Tunggal Prakarsa Tbk |
| PT Semen Indonesia (Persero) Tbk |
| Others |
Pricing and Supply Chain Analysis
Singapore-Jakarta ethoxylate freight corridors transmit cost volatility directly into polycarboxylate superplasticizer pricing, concentrating margin pressure on blenders without captive raw material supply while enabling premium capture by integrated producers serving SNI-certified infrastructure tenders.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across Nusantara and Trans-Java megaprojects, with pricing stratifying across SNI-certified premium, TKDN-compliant standard, and commodity-grade economy tiers. Price differentiation rests on certification level and embedded technical service intensity, not formulation chemistry alone. Cost compression in the residential segment intensifies as lignosulfonate substitutes displace polycarboxylate volumes in peripheral Java housing estates. State-backed infrastructure contractors exhibit lowest price sensitivity due to performance guarantees and liquidated damages exposure, while mid-tier residential developers negotiate hardest on per-liter dosing costs.
Supply Chain Analysis
Tariff exposure between Singapore and Indonesia dominates supply chain risk calculations for specialty ethoxylate importers serving Java's blending corridor. Manufacturing concentration centers on Singapore, Thailand, and South Korea for polycarboxylate ether precursors, while local Indonesian operations handle final formulation and TKDN-compliant blending. Raw material dependency draws from imported ethoxylates, lignosulfonate byproducts from pulp processing, and palm oil-derived fatty acid methyl esters for renewable content claims. Single-source vulnerability persists for high-purity methoxy polyethylene glycol streams. Distribution runs through direct sales teams for specification-grade infrastructure accounts and wholesale distributors aggregating peripheral Java demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's concrete admixtures sector functions as a technical service-attach market where on-site laboratory retainers and embedded formulation support generate recurring revenue expanding faster than commodity admixture volumes.
For Market Incumbents: Pre-empt TKDN threshold escalations by accelerating backward integration into local ethoxylate production or palm oil-derived raw material streams before Ministry of Industry rule changes disqualify import-dependent formulations. Secure SNI certification pipeline capacity at Ministry-authorized laboratories to compress four-to-six-month qualification delays that threaten project-specific contract wins. Defensive consolidation through batching plant leasing partnerships protects channel access against asset-light entrants targeting mid-tier contractors. For New Entrants and Emerging Players: Sulawesi's Morowali nickel smelter corridor offers first-mover positioning in corrosion-inhibiting admixtures where incumbent technical service networks remain underdeveloped. Kalimantan's East Kalimantan coal terminal and Nusantara supply chain logistics pull demand eastward from Java's saturated blending base. Target industrial applications in mining infrastructure where TKDN thresholds relax for strategic mineral projects, enabling foreign supplier entry without full localization. Lead with distributor partnerships in Balikpapan and Samarinda rather than direct sales infrastructure. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors blenders with captive ethoxylate supply and SNI certification acceleration capabilities over pure formulation specialists. Long-term viability across the analysis window rests on TKDN compliance depth and technical service embedding density rather than R&D pipeline breadth. Acquisition target archetype: regional Indonesian blenders with established Ministry relationships and underutilized laboratory accreditation capacity. Signal to watch: Ministry of Industry announcements on TKDN calculation methodology changes for renewable content claims.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethoxylate Production | Captive supply from Singapore or Thai precursor operations insulates margin from freight volatility and currency fluctuation. |
| SNI Certification Pipeline Investment | Accelerated laboratory accreditation at Ministry-authorized facilities compresses product qualification timelines for infrastructure tenders. |
| Technical Service Team Embedding | On-site admixture laboratories at Nusantara and Trans-Java projects shift procurement from transactional to retainer-based relationships. |
| Palm Oil-Derived Raw Material Development | Fatty acid methyl ester streams from Indonesia's oleochemical industry satisfy TKDN renewable content thresholds. |
| Batching Plant Leasing Partnerships | Asset-light equipment models narrow capital barriers for mid-tier contractor channel access without fixed plant ownership. |
Research Methodology
The analysis maps superplasticizer, retarding, accelerating, and air-entraining admixture sub-sectors, each validated through procurement directors at ready-mix suppliers, technical service managers at multinational blenders, and Ministry of Public Works and Housing certification officers. Primary interviews with plant engineers at Nusantara infrastructure consortia, distribution channel partners in Surabaya and Semarang, and formulation chemists at domestic blending operations combined with secondary validation from Indonesian customs records, SNI testing protocol documentation, and Ministry of Industry TKDN circulars. Bottom-up volume triangulation across application segments and top-down value reconciliation against reported parent-company regional disclosures ensured cross-verification.
Assumptions held fixed include prevailing TKDN threshold calculations, SNI certification backlog durations, and Singapore-Jakarta freight rate volatility bands; varied assumptions encompass Nusantara construction phase pacing and Ministry of Industry rulemaking timelines. The projection framework modeled segmentation across product type, application channel, end-user procurement authority, and distribution structure, with CAGRs derived from trend extrapolation against infrastructure investment commitments. Industry-specific forecast inputs incorporated polycarboxylate ether migration rates from naphthalene sulfonate formulations and asset-light batching plant penetration curves in Greater Jakarta peripheral zones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed chemical exporters or accelerated TKDN threshold escalations would shift outcomes beyond modeled ranges. Specific risks include SNI testing protocol delays extending qualification timelines, ethoxylate supply disruptions from Singapore refinery maintenance, and Ministry of Industry domestic content recalculations excluding imported active ingredients. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Latin America Aluminum Door and Window Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Europe Dry-Mix Mortar Market
Building Materials
Qatar Cement Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Steel Slag Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Lightweight Cellular Concrete Market
Building Materials
Bolt (Fastener) Market
Building Materials
India Concrete Admixtures Market
Building Materials
Building and Construction Plastics Market
Building Materials
Europe Concealed Cistern Market
Building Materials
Global Building Panels Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market