
 Global Facade Market | 2026-2036
Global Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Global Facade Market Analysis
Skilled facade installer availability is collapsing across developed construction markets, forcing manufacturers to prefabricate more system components offsite. Saint-Gobain S.A. leverages its integrated glass and insulation portfolio to control specification pipelines from raw material to installed envelope. Kingspan Group anchors its position through insulated panel specialization and deep backward integration into core foam chemistry. YKK AP competes on precision-engineered operable systems that reduce field labor dependency in high-rise applications.
A facade constitutes the exterior envelope system of a building, integrating structural support, weather resistance, thermal insulation, and aesthetic functions through engineered assemblies of glass, metal, composite, or mineral-based materials. Curtain wall systems dominate commercial high-rise applications due to their non-load-bearing design and modular installation efficiency, while composite material facades represent the fastest-growing segment as architects pursue lighter weight-to-strength ratios for complex geometries. Panel systems retain mature margin pools in industrial and institutional projects where standardization outweighs customization premiums.
The EU Green Deal and REACH frameworks enforce embodied carbon disclosure and restricted substance compliance across facade material supply chains, directly shaping product development priorities for European projects. China's GB standards and dual carbon goals mandate progressive thermal performance ratings for new construction envelopes, accelerating substitution of conventional single-glazed systems. India's BIS certification and Energy Conservation Building Code establish baseline efficiency thresholds that filter market access for imported cladding systems. Stakeholders must monitor how divergent national compliance calendars reshape procurement timing and supplier qualification requirements across multi-jurisdiction project portfolios.
Market Dynamics
Prefabrication is compressing field installation timelines across high-rise construction, forcing envelope manufacturers to reconfigure production footprints and logistics networks around modular assembly capabilities rather than component supply.
Growth Catalysts
- EU Green Deal building performance standards:The EU Green Deal mandates progressive energy-efficiency thresholds for exterior cladding in commercial retrofits, accelerating specification of high-performance insulated systems across Germany, France, and the Netherlands.
- Composite material innovation:Fiber-reinforced polymer panels deliver superior weight-to-strength ratios that enable complex geometric facades previously unattainable with conventional aluminum or glass assemblies.
- Megacity urban renewal concentration:China's Yangtze River Delta and Pearl River Delta clusters are prioritizing sustainable envelope upgrades in existing commercial stock, creating sustained demand for retrofit-compatible curtain wall systems.
Market Restraints
- Aluminum and glass input cost volatility:Energy-intensive primary aluminum production faces electricity price swings that compress margin predictability for system fabricators.
- Specialized installer scarcity:Certified facade technicians are concentrating in Germany and Japan, leaving North American and Southeast Asian project pipelines exposed to labor bottleneck delays.
- REACH substance compliance friction:ECHA restrictions on specific flame retardants and coatings force reformulation cycles that extend product development timelines by 12-18 months.
Strategic Opportunities
- India's Energy Conservation Building Code expansion:BIS certification requirements for imported cladding systems create first-mover advantages for suppliers establishing local testing partnerships and technical documentation capabilities.
- Building-integrated photovoltaics convergence:Solar-active facade laminates merge envelope function with on-site generation, opening premium specification channels in net-zero commercial developments.
- Direct-to-contractor digital channels:Configurator platforms bypass traditional specification intermediaries, enabling manufacturers to capture margin previously allocated to architectural glazing consultants.
Industry Challenges
- Multi-jurisdiction certification complexity:Projects spanning EU member states, Switzerland, and the UK require parallel CE marking, Swissmedic building material approvals, and post-Brexit UKCA conformity assessments.
- Legacy building structural compatibility:Retrofit curtain wall installations on 1970s-1980s concrete frame structures demand bespoke anchoring engineering that fragments project economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Facade Market |
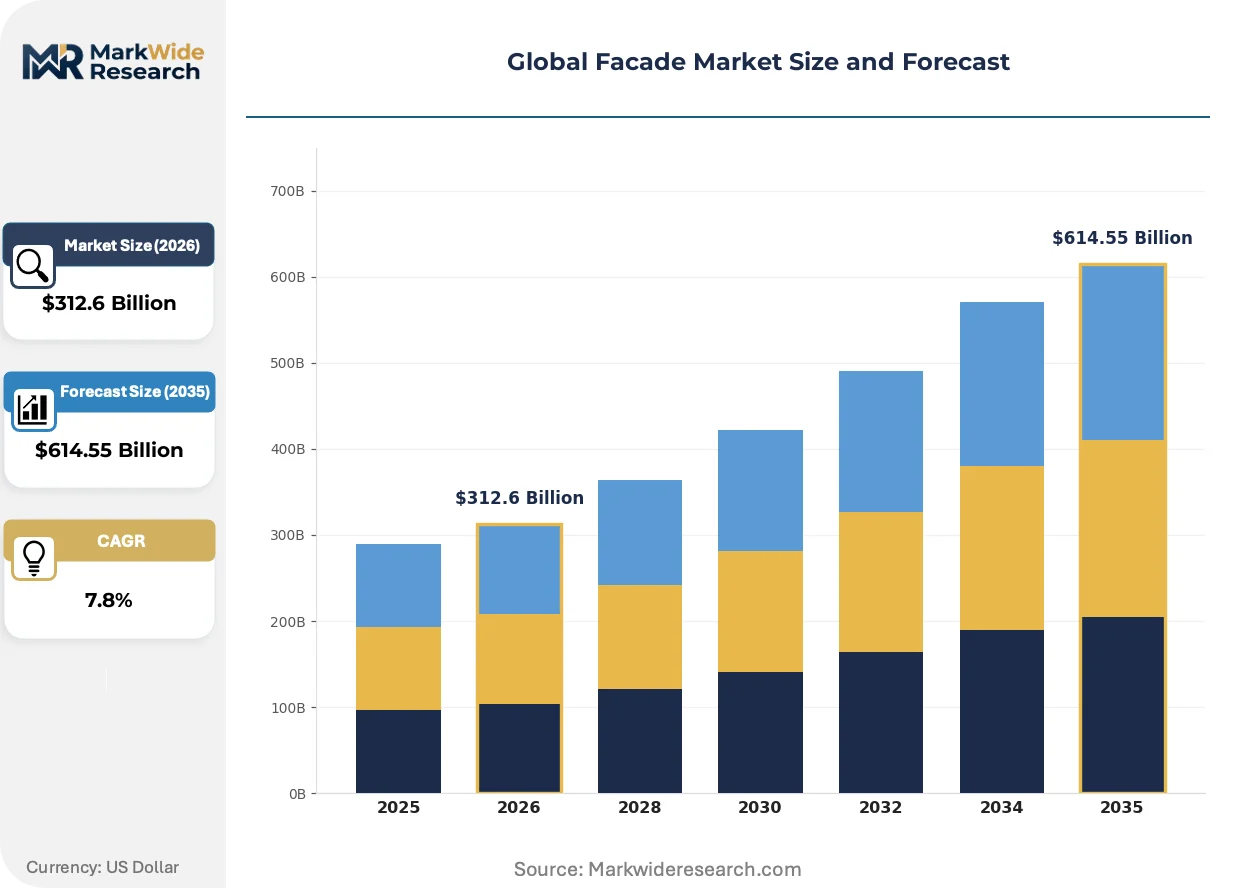
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $614.55 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Curtain Wall, Panel Systems, Windows, Doors Material: Glass, Aluminum, Steel, Composite Installation Type: New Construction, Renovation, Retrofitting, Modular End User: Residential Buildings, Commercial Buildings, Institutional Buildings, Industrial Facilities |
| Companies Covered | Enclos Corp., AGC Glass Europe, Saint-Gobain S.A., YKK AP, Schüco International, Kingspan Group, Permasteelisa S.p.A., Aluplex, Lindner Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Facade Market Emerging Trajectories
Digital fabrication and environmental compliance are converging to redefine how envelope systems are specified, manufactured, and installed across commercial construction value chains.
Automated robotic glazing is displacing manual unitized panel assembly in high-volume curtain wall production. European and North American fabricators are deploying vision-guided sealing robots to achieve consistent thermal break performance at throughput rates unmatchable by skilled technicians. This automation is compressing delivery lead times for standardized commercial tower projects while elevating quality thresholds that smaller competitors struggle to satisfy.
REACH framework amendments on per- and polyfluoroalkyl substances are forcing coating chemistry transitions across European supply chains. Manufacturers must reformulate hydrophobic surface treatments and anodized finishes to eliminate restricted fluorinated compounds without degrading weathering performance. German and Austrian system houses are responding fastest, leveraging in-house R&D to secure early ECHA pre-registration approvals that lock competitors out of public tender pipelines.
Design-assist procurement models are supplanting traditional bid-specify sequences in complex institutional projects. Owners in Singapore and the UAE are engaging envelope specialists during schematic design to co-develop performance-guaranteed solutions rather than delegating risk to lowest-bid subcontractors. This shift concentrates specification authority with technically capable manufacturers and marginalizes pure trading intermediaries lacking engineering depth.
Global Facade Market Segmentation
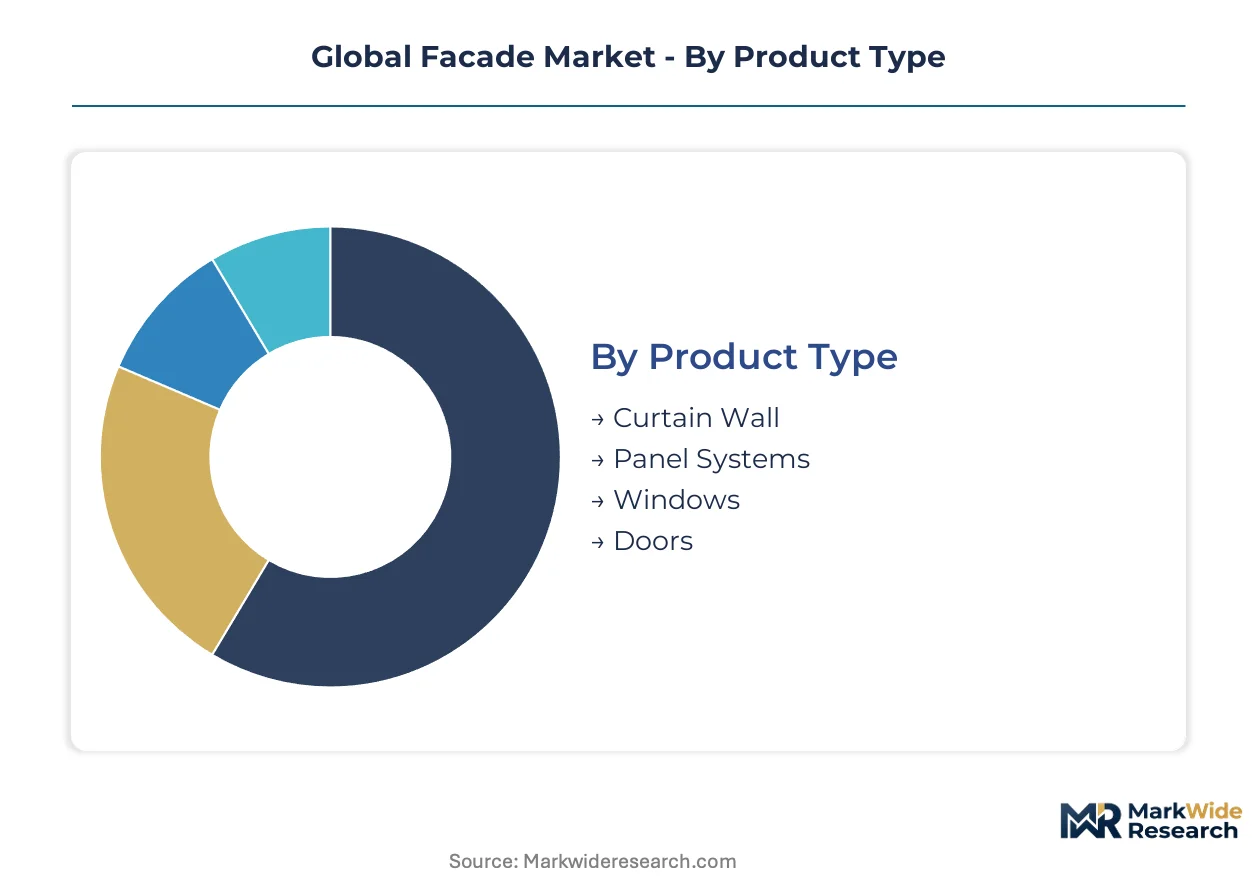
Facade procurement channels diverge sharply by product complexity and project scale. Specification authority concentrates with architectural consultants for high-rise curtain wall systems, while distributors and direct contractor relationships dominate standardized panel and window segments.
Product Type:
Curtain wall systems flow through design-assist partnerships with glazing contractors, whereas panel systems and fenestration products move through building material distributors and direct-to-contractor digital platforms.
- Curtain Wall:Non-load-bearing aluminum and glass assemblies engineered for high-rise commercial towers. Demand concentrates in China's Yangtze River Delta megacity cluster as urban renewal projects prioritize energy-efficient envelope upgrades in existing commercial stock.
- Panel Systems:Pre-fabricated insulated metal or composite panels installed on industrial and institutional buildings. Procurement runs through regional distributors serving warehouse and manufacturing facility developers in Germany and the US Midwest where standardization outweighs customization premiums.
- Windows:Operable and fixed glazing units for residential and light commercial applications. Sales channels fragment across big-box retailers, specialized fenestration dealers, and direct contractor programs.
- Doors:Entrance systems including automatic, manual, and security-rated assemblies. Specification authority splits between architect-driven commercial projects and contractor-driven residential replacement cycles.
By volume, Panel Systems leads. By growth pace, Curtain Wall is ahead.
Material:
Raw material selection drives fabrication footprint location and backward integration strategy across supplier tiers.
- Glass:Float and processed glass including laminated, tempered, and coated varieties. European fabricators leverage integrated float glass supply from Belgian and German production basins to control thermal performance specification pipelines.
- Aluminum:Extruded and unitized framing systems. Input cost volatility from energy-intensive primary smelting in Norway and Iceland compresses margin predictability for system fabricators.
- Steel:Structural framing and fire-rated assemblies. Demand clusters in institutional and industrial projects where blast resistance and span capability override weight considerations.
- Composite:Fiber-reinforced polymer and mineral composite panels. Architects in Singapore and the UAE specify these for complex geometric facades previously unattainable with conventional metal assemblies.
Glass commands the largest volume share. Composite materials are climbing the fastest.
Installation Type:
Project delivery method determines labor sourcing and manufacturer involvement depth.
- New Construction:Integrated design-build sequences where envelope specialists engage during schematic phases. Concentrated in India's expanding commercial corridors around Mumbai and Bangalore as BIS certification requirements filter supplier access.
- Renovation:Partial envelope replacement on occupied buildings. Labor bottlenecks in North American markets force manufacturers toward prefabricated solutions that reduce field technician dependency.
- Retrofitting:Full facade replacement on aging structures. EU Green Deal energy-efficiency mandates accelerate specification across Germany, France, and the Netherlands.
- Modular:Factory-assembled envelope units craned into position. Compression of high-rise construction timelines drives adoption in Japan and South Korea where skilled installer scarcity is most acute.
New Construction dominates volume. Modular installation is gaining share fastest.
End User:
Building typology shapes performance requirements, procurement authority, and margin structure.
- Residential Buildings:Single-family and multifamily housing envelope systems. Replacement cycles and new construction in US Sun Belt states drive fenestration demand through contractor and retail channels.
- Commercial Buildings:Office towers, retail centers, and hospitality structures. Net-zero development targets in the UK and California open premium channels for building-integrated photovoltaic facade laminates.
- Institutional Buildings:Healthcare, education, and government facilities. Design-assist procurement models in Singapore and the UAE concentrate specification authority with technically capable manufacturers.
- Industrial Facilities:Warehouses, manufacturing plants, and logistics centers. Standardized panel systems serve this segment through distributor networks with minimal engineering customization.
Commercial Buildings leads by value. Residential Buildings shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facade procurement patterns diverge sharply by geography. European project pipelines prioritize embodied carbon compliance, while Asian markets emphasize speed-to-install and retrofit compatibility on aging commercial stock.
China
Yangtze River Delta megacity clusters are driving demand for unitized curtain wall systems in urban renewal projects. GB standards and dual carbon goals mandate progressive thermal performance ratings that accelerate substitution of single-glazed envelopes. Shanghai and Suzhou commercial corridors concentrate specification activity for high-rise retrofit-compatible systems.
Germany
Commercial retrofit pipelines across Berlin and Munich prioritize high-performance insulated systems under EU Green Deal mandates. ECHA REACH restrictions on flame retardants and coatings force 12-18 month reformulation cycles that favor in-house R&D capabilities. Bavarian and North Rhine-Westphalian industrial basins anchor automated fabrication investments for vision-guided sealing robotics.
United States
Sun Belt commercial construction concentrates fenestration demand through contractor and distributor channels. Skilled installer scarcity across North American markets forces manufacturers toward prefabricated modular solutions that reduce field labor dependency. Texas and Florida project pipelines expose envelope schedules to technician bottleneck delays.
India
Mumbai and Bangalore commercial corridors are expanding as BIS certification requirements filter supplier access for imported cladding systems. Energy Conservation Building Code expansion creates first-mover advantages for suppliers establishing local testing partnerships. Maharashtra and Karnataka states concentrate new construction specification authority.
United Arab Emirates
Dubai and Abu Dhabi institutional projects are adopting design-assist procurement models that concentrate specification authority with technically capable manufacturers. Complex geometric facade specifications favor fiber-reinforced composite panels for weight-to-strength ratios unattainable with conventional metal assemblies. MOHAP building material approvals shape supplier qualification requirements.
Global Facade Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale fabricators occupying regional niches. The structure rewards backward integration into core material supply and captive control over thermal performance engineering. Three archetypes dominate: glass-and-insulation integrators, foam-chemistry specialists, and precision-operable system engineers. Competitive moves concentrate on modular assembly capacity expansion and design-assist partnership formations that bypass traditional specification intermediaries.
Within the integrated-materials tier, Saint-Gobain S.A. and Kingspan Group exemplify divergent paths to envelope control. Saint-Gobain leverages combined glass and insulation portfolios to anchor specification pipelines from raw material through installed performance. Kingspan occupies a position defined by insulated panel specialization and upstream integration into core foam chemistry. YKK AP sits within the precision-engineering archetype, representing manufacturers that reduce field labor dependency through operable system design. Schüco International and Lindner Group anchor European fabrication capabilities amid REACH-driven reformulation pressures.
| Leading Market Players |
|---|
| Enclos Corp. |
| AGC Glass Europe |
| Saint-Gobain S.A. |
| YKK AP |
| Schüco International |
| Kingspan Group |
| Permasteelisa S.p.A. |
| Aluplex |
| Lindner Group |
| Others |
Supply Flow & Price Mechanics
Automated fabrication scale in German and Austrian system houses compresses unit costs for standardized curtain wall assemblies, concentrating pricing power among capital-intensive producers while elevating entry thresholds for regional fabricators lacking vision-guided sealing robotics. This scale dynamic feeds backward into raw material procurement, where integrated glass-and-insulation portfolios command preferential float glass allocation from Belgian production basins.
Pricing Analysis
Long-term offtake contracts dominate high-rise commercial projects, locking aluminum and glass volumes ahead of energy-price volatility, while spot purchasing persists for renovation-grade panel systems. Price differentiation hinges on CE marking tier and thermal performance certification, with EU Green Deal-compliant systems commanding premiums over baseline imports. Cost compression in standard-grade segments intensifies as Chinese unitized producers expand direct contractor channels. Institutional buyers in Singapore and the UAE exhibit lowest price sensitivity due to design-assist procurement models, whereas US Sun Belt residential distributors face acute margin pressure from big-box retail competition.
Supply Chain Analysis
China and Germany anchor global curtain wall fabrication, with the Yangtze River Delta concentrating unitized assembly capacity and Bavaria hosting automated sealing robotics deployment. Primary aluminum smelting in Norway and Iceland feeds extrusion operations, while float glass supply draws from Belgian and German production basins. Single-source vulnerability concentrates in energy-intensive primary aluminum, where electricity price spikes transmit directly to framing system costs. Distribution runs through design-assist partnerships for high-rise specifications and regional distributors for standardized panel segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facade market sits at an inflection where EU Green Deal energy-efficiency mandates and REACH substance restrictions are accelerating substitution of conventional envelope systems, creating asymmetric growth windows for compliance-capable producers.
For Market Incumbents: Consolidate specification authority through captive thermal performance engineering and backward integration into core foam chemistry, insulating margin pools from commodity aluminum volatility. Expand automated fabrication footprints in Germany and Austria to exploit REACH-driven reformulation cycles that lock competitors out of public tender pipelines. Prioritize design-assist partnership formations in Singapore and the UAE where procurement models concentrate authority with technically capable manufacturers. For New Entrants and Emerging Players: BIS certification fast-tracks into India's Maharashtra and Karnataka commercial corridors offer first-mover positioning before Energy Conservation Building Code expansion hardens supplier qualification requirements. Target modular installation segments in Japan and South Korea where skilled installer scarcity forces procurement toward factory-assembled envelope units. Pursue direct-to-contractor digital channels to bypass architectural glazing consultant intermediaries and capture specification margin. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated-materials archetypes with captive glass supply and in-house coating chemistry R&D capabilities. Long-term viability over the next decade rests on automated fabrication scale and REACH pre-registration asset bases. Watch ECHA substance restriction calendars as inflection indicators for competitive lockout dynamics in European public procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fabrication Scale-Up | Vision-guided sealing robotics in German system houses compress delivery timelines below manual assembly thresholds. |
| Backward Integration into Foam Chemistry | Kingspan Group's upstream control over core insulation chemistry anchors thermal performance specification pipelines. |
| Design-Assist Partnership Formation | Singapore and UAE institutional projects concentrate authority with envelope specialists engaged during schematic phases. |
| REACH Pre-Registration Investment | German and Austrian manufacturers secure early ECHA approvals that exclude reformulation-lagged competitors from tenders. |
| Direct-to-Contractor Digital Channel | Configurator platforms bypass architectural glazing consultants and capture margin previously allocated to specification intermediaries. |
Methodological Framework
A spread of perspectives from facade system engineering directors, glazing contractor procurement leads, architectural specification consultants, and EHS compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against EU Green Deal implementation timelines, ECHA REACH substance restriction calendars, BIS certification requirement documents, and customs trade data for aluminum and glass imports. Bottom-up project pipeline assessments across China's Yangtze River Delta and India's Mumbai-Bangalore corridors were triangulated against top-down envelope spending forecasts from commercial construction databases.
Segmentation dimensions modeled span product type, material composition, installation method, and end-use building typology, with additional granularity on thermal performance certification tiers and regional regulatory compliance clusters. CAGRs were derived from fitted growth curves anchored to disclosed project backlogs and announced capacity expansions, cross-referenced against energy-efficiency mandate implementation calendars. Forecast inputs incorporated skilled installer scarcity indices, primary aluminum electricity cost differentials, and prefabrication adoption rates across high-rise construction markets.
Decision-makers should treat outputs as directional under base assumptions of progressive EU Green Deal enforcement and sustained Chinese urban renewal investment; material deviation in regulatory implementation velocity or construction credit availability would warrant model refresh. Recalibration cycles align with material shifts in ECHA substance restriction timelines and BIS certification expansion phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Ductile Iron Pipe Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
Block Paving Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
United States Architectural Coatings Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Recycled Concrete Aggregates Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Thermoplastic Composite Exterior Clips and Brackets Market
Building Materials
Radiant Barriers and Reflective Insulation Market
Building Materials
Europe Fireproof Cladding Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Europe Building and Construction Sheets Market
Building Materials
Aluminum Door and Window Market