
 North America Engineered Stone Market | 2026-2036
North America Engineered Stone Market Size, Share, and Industry Trends Forecast 2026-2036
North America Engineered Stone Market Insights
The EPA's crystalline silica rule is decoupling engineered stone demand from traditional fabrication networks. Cambria Company LLC leverages captive Minnesota production to sustain premium positioning across Midwest residential markets. Caesarstone US anchors its North American footprint through direct distribution control in major metropolitan corridors. MSI Surfaces competes on breadth, operating showrooms that span quartz, marble, and recycled material portfolios.
Engineered stone comprises quartz particles bound with polymer resins under vacuum vibration compression, yielding slabs with Mohs hardness near seven and porosity below 0.05 percent for stain-resistant surfaces. Quartz dominates product type volume due to color consistency and fabrication friendliness, while recycled materials represent the fastest-expanding category as LEED-driven commercial projects specify sustainable content. Countertops command the largest application share, though wall cladding in hospitality settings generates disproportionate margin capture through custom dimensioning and finish complexity.
OSHA enforces permissible exposure limits for respirable crystalline silica in fabrication facilities, while the EPA monitors resin binder emissions under Clean Air Act provisions. Health Canada and PMRA coordinate with provincial regulators to align product safety standards across the US-Canada trade corridor. Stakeholders must monitor evolving silica substitution technologies and state-level fabrication licensing requirements that could reshape regional supply economics.
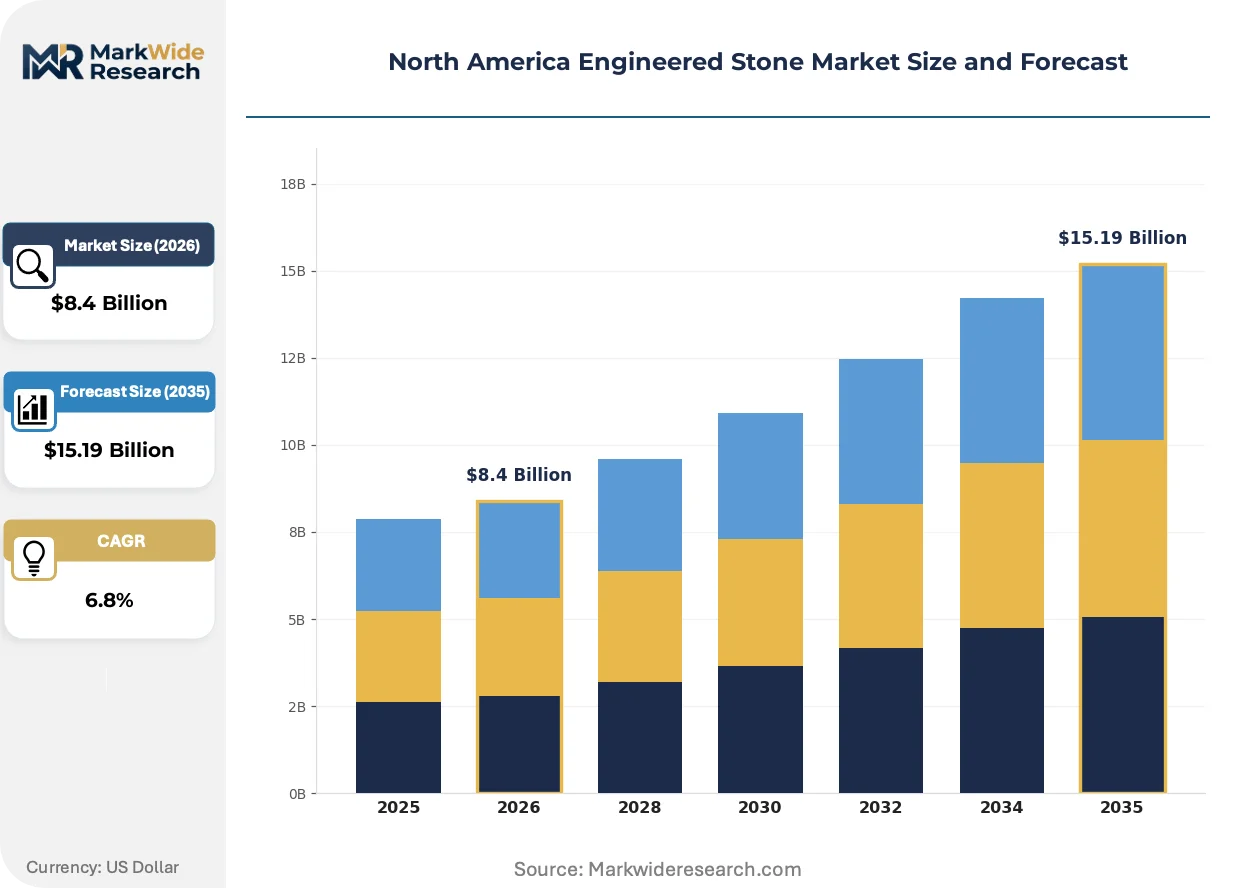
Market Dynamics
OSHA's respirable crystalline silica enforcement is fragmenting North American fabrication capacity, forcing demand toward captive production networks and certified installers. The regulatory pressure is compressing regional supply economics while accelerating consolidation among compliant operators.
Growth Catalysts
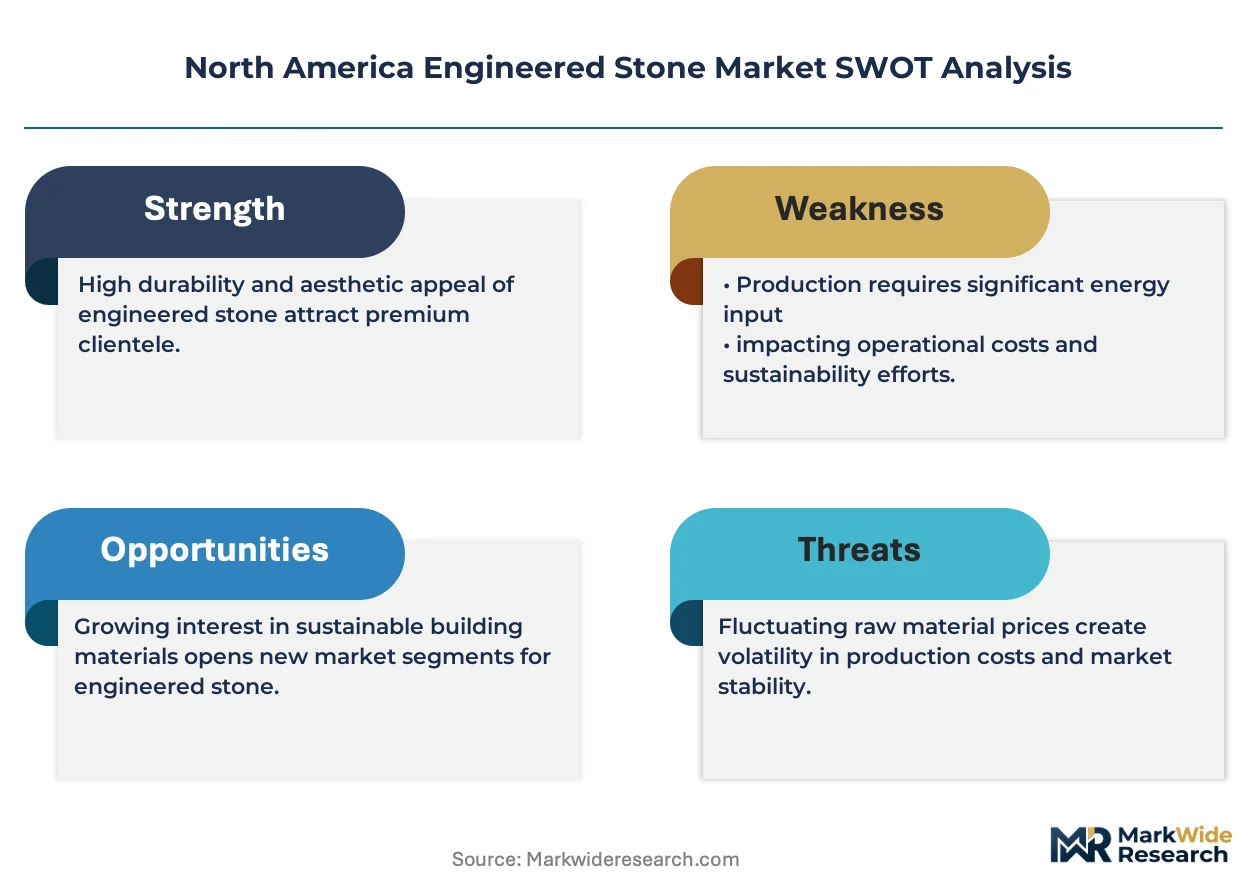
- Sun Belt residential construction:Phoenix, Dallas, and Atlanta metro areas generate concentrated countertop demand from new housing starts and kitchen renovations.
- LEED certification requirements:Commercial projects across the United States and Canada specify recycled content engineered stone to meet sustainability point thresholds.
- Polymer resin formulation advances:Improved UV stability and thermal shock resistance expand outdoor kitchen and hospitality applications previously served by natural stone.
Market Restraints
- Petrochemical resin price volatility:Polyester and epoxy binder costs fluctuate with crude oil derivatives, compressing fabrication margins during upstream spikes.
- Silica substitution R&D timelines:Alternative aggregate development remains capital-intensive with uncertain commercialization schedules.
- Regional fabrication concentration:Certified shop capacity clusters in specific metropolitan corridors, creating logistics bottlenecks for distributed residential projects.
Strategic Opportunities
- Canadian provincial expansion:Ontario and British Columbia present underpenetrated markets relative to US Sun Belt saturation.
- Healthcare facility surfaces:Antimicrobial resin formulations address infection control requirements in hospital and clinic renovations.
- Direct-to-installer digital platforms:B2B procurement channels bypass traditional distributor markups for midsize fabrication shops.
Industry Challenges
- Respirable silica remediation capex:Wet-cutting equipment and ventilation upgrades demand substantial capital outlays from independent fabricators.
- Cross-border certification reciprocity:US and Canadian provincial licensing standards create compliance complexity for multi-jurisdictional operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Engineered Stone Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz, Marble, Granite, Recycled Materials Application: Countertops, Flooring, Wall Cladding, Vanity Tops End User: Residential, Commercial, Hospitality, Retail Distribution Channel: Online Retail, Showrooms, Wholesalers, Direct Sales |
| Companies Covered | Cambria Company LLC, Caesarstone US, Daltile, MSI Surfaces, Silestone, Hanstone Quartz US, Meta Surfaces, Vadara Quartz, Stone Panels International LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Engineered Stone Market Trends and Innovations
Bio-based binder chemistry and digital templating workflows are compressing project timelines while opening specification pathways previously closed to engineered stone. These shifts are reshaping competitive differentiation beyond color and pattern libraries.
Hybrid inorganic-organic resin systems is unifying thermal performance and fabrication workability in a single slab formulation. Large-scale hospitality developers specify these materials for high-traffic surfaces requiring both heat resistance and field repairability. The technology is compressing the traditional tradeoff between natural stone aesthetics and polymer-bound durability.
EPA enforcement of Clean Air Act provisions on resin emissions is elevating low-VOC formulation premiums in fabrication-heavy corridors. Shops in Los Angeles and Houston face stricter monitoring than interior markets. California's South Coast Air Quality Management District rules are pushing manufacturers toward water-based binder alternatives.
Specification authority is migrating from general contractors to certified kitchen designers and direct homeowner research. Showroom visits now precede contractor engagement in renovation projects across suburban Texas and Florida markets. This channel compression rewards brands with searchable digital presence and localized inventory visibility.
North America Engineered Stone Market Segmentation
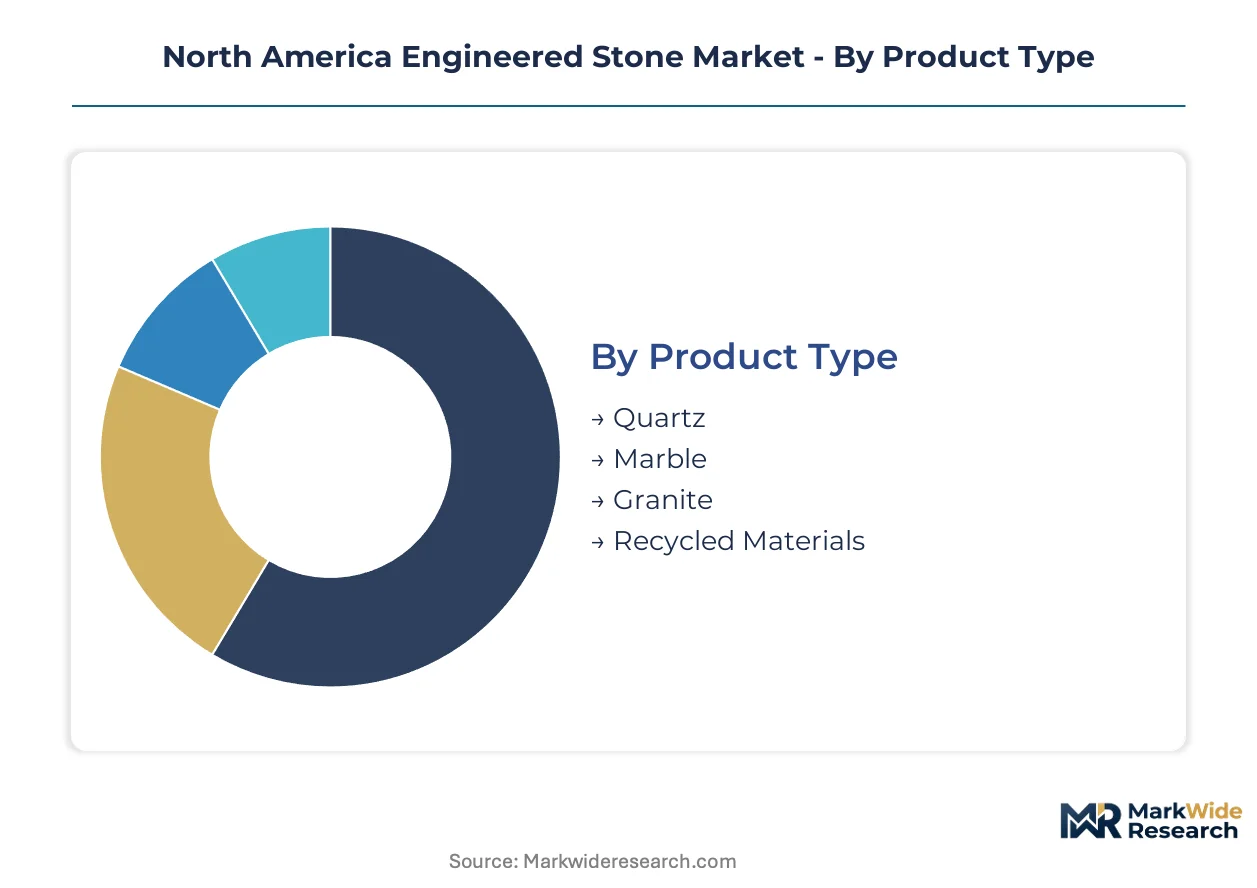
Engineered stone demand fragments across four distinct axes in North America. Product chemistry determines fabrication compliance costs, while application geometry drives margin structure. End-user procurement authority and channel control complete the segmentation map.
Product Type:
Material composition dictates silica exposure profiles and regulatory compliance intensity across fabrication networks.
- Quartz:Crushed quartz aggregate bound with polyester or epoxy resin yields slabs with consistent coloration and Mohs hardness near seven. Demand concentrates in Sun Belt residential kitchen renovations where thermal shock resistance and stain immunity command specification priority among certified installers in Phoenix, Dallas, and Atlanta corridors.
- Recycled Materials:Post-industrial glass, porcelain, and reclaimed stone fragments replace virgin quartz in polymer-bound matrices. LEED point thresholds in commercial projects across Toronto, Vancouver, and California metros are accelerating specification velocity for this category as sustainability documentation becomes mandatory in municipal procurement.
- Marble:Calcite-rich engineered variants mimic natural veining through controlled pigment dispersion. Hospitality developers in Miami and Las Vegas specify these surfaces for lobby and amenity spaces where aesthetic differentiation supports nightly rate positioning.
- Granite:Feldspar and mica inclusions create speckled patterns with higher compressive strength than quartz alternatives. Outdoor kitchen fabricators in Texas and Florida favor this material for UV stability in exposed installations.
Quartz leads on scale; recycled materials lead on momentum.
Application:
Surface geometry and traffic intensity determine fabrication complexity and installed margin capture.
- Countertops:Horizontal work surfaces in residential kitchens command the largest volume share, with standard slab dimensions of 120 by 56 inches dominating procurement. Sun Belt housing starts and renovation cycles in suburban Texas and Florida metros sustain fabrication shop capacity utilization.
- Wall Cladding:Vertical installations in hospitality lobbies and elevator cabs require custom dimensioning and finish complexity. Large-scale developers in Los Angeles and New York specify these applications for disproportionate margin capture through design-assist contracts.
- Flooring:High-traffic commercial surfaces demand enhanced abrasion resistance through denser resin formulations. Airport terminals and hospital corridors in Chicago and Denver represent concentrated specification nodes.
- Vanity Tops:Smaller-format bathroom surfaces integrate integrated sinks and backsplash profiles. Multi-family residential developers in Seattle and Boston standardize these configurations for procurement efficiency.
Countertops dominate volume contribution; wall cladding dominates margin contribution.
End User:
Procurement authority and specification timeline vary sharply across buyer categories.
- Residential:Homeowner-driven renovation projects with direct showroom engagement. Kitchen designers in suburban Dallas and Atlanta corridors now precede contractor selection in the specification sequence.
- Commercial:Corporate facility managers and general contractors with LEED compliance mandates. Office buildouts in Toronto and Vancouver specify recycled content for sustainability documentation.
- Hospitality:Brand-standard enforcement by hotel chains and casino operators. Large-scale developers in Las Vegas and Miami demand thermal shock resistance and field repairability for high-traffic surfaces.
- Retail:Fixture manufacturers and franchise operators with standardized rollout programs. Quick-service restaurant chains in Phoenix and Houston specify durable surfaces for counter and service areas.
Residential commands absolute volume; hospitality commands specification influence.
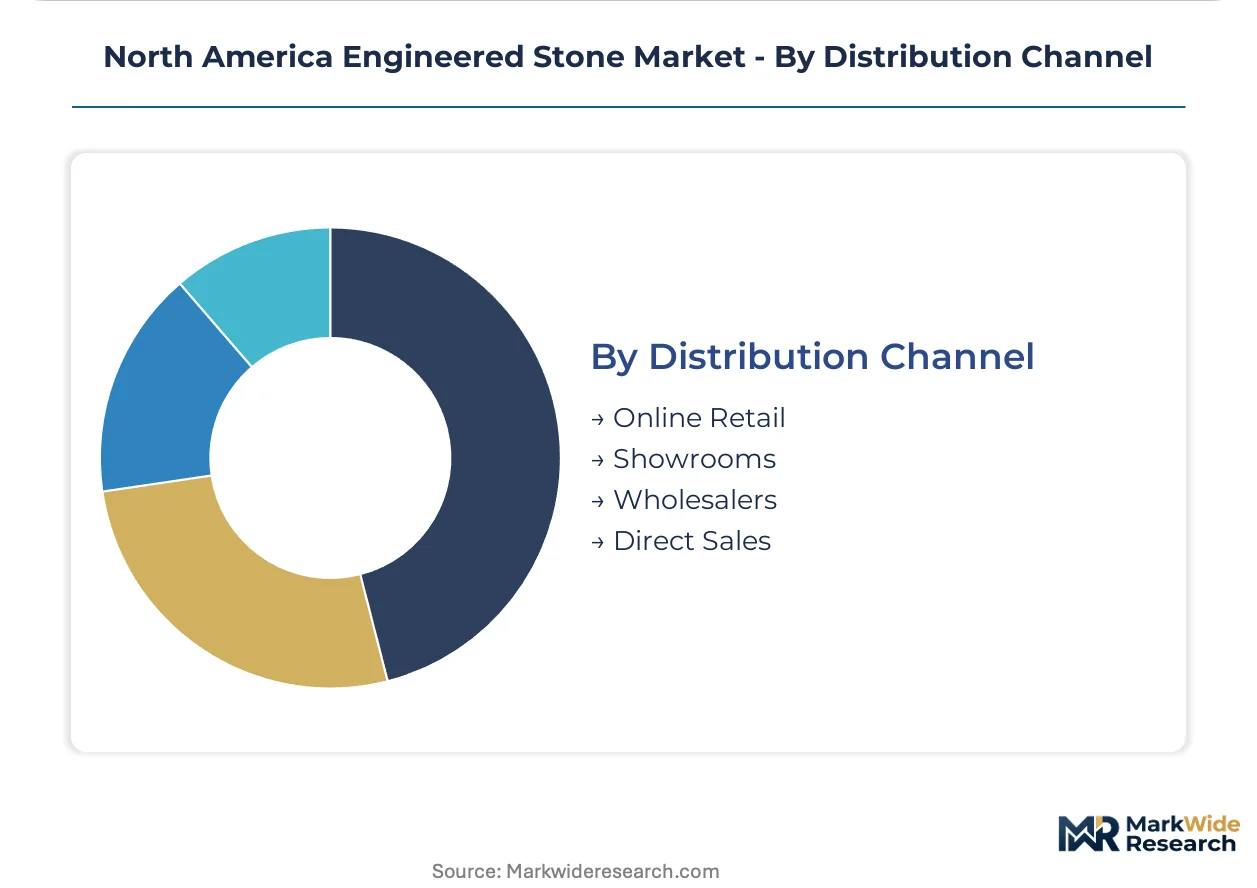
Distribution Channel:
Channel structure determines price realization and installer relationship depth.
- Showrooms:Physical display environments with templating services and certified installer referrals. Cambria and Caesarstone operate company-owned locations in major metropolitan corridors to control brand presentation.
- Direct Sales:Manufacturer-to-fabricator relationships bypassing distributor markups. MSI Surfaces leverages this channel for volume accounts in Texas and Florida.
- Wholesalers:Regional distributors serving independent fabrication shops with inventory financing. Concentrated capacity in Los Angeles and Houston faces EPA resin emission compliance pressure.
- Online Retail:Digital templating platforms and B2B procurement interfaces. Emerging presence among midsize fabrication shops seeking to bypass traditional distributor economics.
Showrooms lead on specification authority; direct sales lead on margin retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineered stone fabrication scaled first in Minnesota and Wisconsin during the 2000s, establishing captive production networks that now supply residential markets across the continent.
United States
Sun Belt metropolitan corridors generate concentrated countertop demand from housing starts and kitchen renovations. OSHA enforces respirable crystalline silica limits that fragment fabrication capacity toward certified operators. Phoenix, Dallas, and Atlanta sustain the highest shop utilization rates through suburban residential construction cycles.
Canada
Ontario and British Columbia present underpenetrated markets relative to US saturation, with LEED-driven commercial projects accelerating specification velocity. Health Canada and PMRA coordinate with provincial regulators to align product safety standards across the US-Canada trade corridor. Toronto and Vancouver fabrication clusters are expanding to capture cross-border supply chain efficiencies.
Mexico
Manufacturing cost advantages attract slab finishing operations serving US Southwest markets. The country's environmental regulator monitors resin emissions under federal clean air provisions. Monterrey and Guadalajara industrial zones host emerging fabrication capacity for hospitality export contracts.
North America Engineered Stone Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered positioning strategies. The vendor base clusters around three strategic archetypes: captive vertically integrated manufacturers, direct distribution controllers, and breadth-oriented portfolio operators. Consolidation pressure favors operators with certified fabrication networks and showroom-controlled specification channels. Dominant competitive moves include geographic expansion into underpenetrated provincial markets and portfolio diversification into recycled content categories.
Among North American-based fabricators, Cambria Company LLC exemplifies captive production architecture through Minnesota-based manufacturing control. Caesarstone US occupies a position as a direct distribution anchor across major metropolitan corridors. MSI Surfaces sits within the breadth-driven tier, spanning multiple material categories through showroom networks.
| Leading Market Players |
|---|
| Cambria Company LLC |
| Caesarstone US |
| Daltile |
| MSI Surfaces |
| Silestone |
| Hanstone Quartz US |
| Meta Surfaces |
| Vadara Quartz |
| Stone Panels International LLC |
| Others |
Pricing and Supply Chain Analysis
Captive vertical integration by Minnesota-based manufacturers anchors both supply security and premium pricing power across North American residential markets. This production architecture insulates against resin cost volatility while supporting three-tier positioning across certified installer networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Cambria's showroom-controlled positioning from distributor-dependent competitors. Price differentiation hinges on silica compliance certification grade and captive fabrication network density. Cost compression in economy tiers is intensifying because petrochemical resin feedstock volatility feeds through polyester and epoxy binder costs. Multi-family residential developers exhibit highest price sensitivity; hospitality specifiers demonstrate lowest sensitivity due to brand-standard enforcement.
Supply Chain Analysis
Buy-American procurement mandates in federal and municipal construction projects are reshaping sourcing toward domestic slab finishing capacity. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies spanning crushed quartz aggregate from Minnesota and Wisconsin deposits, polymer resins from Gulf Coast petrochemical corridors, and pigment dispersions from Ohio specialty chemical producers. Single-source vulnerability runs through certified fabrication shop networks clustered in Sun Belt metropolitan corridors. Distribution runs through manufacturer-operated showrooms, direct sales to volume fabricators, and regional wholesalers serving independent installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in engineered stone rests on silica substitution R&D maturation and premium-tier specification capture in hospitality and healthcare verticals.
For Market Incumbents: Extend certified fabrication network coverage into Ontario and British Columbia to preempt cross-border supply chain efficiencies. Deepen backward integration into bio-based binder chemistry before EPA Clean Air Act enforcement tightens resin emission standards. Prioritize showroom density in suburban Dallas and Atlanta corridors where specification authority migrates ahead of contractor engagement. For New Entrants and Emerging Players: Antimicrobial resin formulation technology offers a technology-first wedge into hospital and clinic renovation specifications where infection control documentation commands premium positioning. Target underpenetrated Canadian provincial markets with LEED-driven commercial project pipelines. Pursue direct-to-installer digital platforms bypassing traditional distributor markups for midsize fabrication shops in Texas and Florida. For Investors and Strategic Acquirers: Roll-up economics work for certified fabrication shop networks because OSHA silica enforcement fragments capacity toward compliant operators with captive customer relationships. Five-to-ten year viability favors operators with showroom-controlled specification channels and recycled content portfolio breadth. Monitor silica substitution technology commercialization timelines as inflection indicator for premium-tier displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Silica Substitution R&D Investment | Alternative aggregate development addresses OSHA compliance cost escalation while opening premium positioning pathways. |
| Canadian Provincial Expansion | Ontario and British Columbia fabrication clusters capture LEED-driven commercial specification velocity with cross-border supply chain efficiencies. |
| Healthcare Surface Certification | Antimicrobial resin formulations penetrate hospital renovation procurement where infection control documentation commands specification priority. |
| Direct-to-Installer Digital Platform | B2B procurement interfaces bypass distributor markups for midsize fabrication shops in high-volume Sun Belt corridors. |
| Recycled Content Portfolio Diversification | Post-industrial glass and porcelain matrices meet municipal procurement sustainability thresholds in Toronto and Vancouver metros. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each territory combined with secondary validation. Primary interviews engaged engineered stone plant managers, certified fabrication shop owners, commercial project specification consultants, and regional distribution channel partners. Secondary sources included OSHA enforcement records, EPA Clean Air Act filings, Health Canada product safety standards, provincial licensing databases, and trade flow data from US Census Bureau and Statistics Canada. Bottom-up fabrication shop capacity modeling triangulated against top-down residential construction permit analysis.
Rate-of-change decomposition across product type, application geometry, end-user procurement authority, and distribution channel structure anchored the analytical framework. Segmentation modeling captured quartz, recycled materials, marble, and granite chemistry variations alongside countertop, wall cladding, flooring, and vanity top application dimensions. CAGRs derived from housing start correlations, renovation cycle timing, and commercial construction pipeline tracking. Silica substitution technology readiness levels and EPA enforcement trajectory informed scenario-weighted outcomes.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical resin price volatility, silica alternative commercialization schedules, and state-level fabrication licensing reciprocity agreements. Forecasts reflect documented assumptions regarding Sun Belt housing construction cycles, LEED certification adoption curves, and cross-border regulatory alignment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
United States White Cement Market
Building Materials
Solar Control Window Film Market
Building Materials
Building and Construction Plastics Market
Building Materials
India Concealed Cistern Market
Building Materials
Global Metal Cladding Market
Building Materials
Sprayed Concrete Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Acoustic Damping Tiles Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Qatar Facade Market
Building Materials
US Contract Glazing Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Block Paving Market
Building Materials
Cement Board Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market