
 Construction Equipment Tire Market | 2026-2036
Construction Equipment Tire Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Equipment Tire Market Analytics
India is tilting toward expanded radial tire capacity as infrastructure outlays accelerate earthmoving demand. Bridgestone Corporation leverages its integrated rubber compound research to sustain premium positioning in high-load mining applications. Michelin anchors European supply through specialized foundry tire production for excavator and crane fleets. Continental AG competes on connected tire monitoring systems that extend service-interval predictability for rental company customers.
Construction equipment tires are engineered elastomer structures reinforced with steel or textile cords, designed to withstand extreme static loads, puncture hazards, and uneven terrain while maintaining traction on loose aggregates and finished surfaces. Radial tires dominate OEM fitment for large excavators and cranes due to cooler running temperatures and longer casing life, while solid tires capture maintenance-intensive segments like waste handling and demolition where puncture elimination outweighs ride comfort. Bias tires retain share in emerging-market backhoe loader fleets where first-cost sensitivity shapes procurement, and foam-filled variants occupy niche applications bridging pneumatic comfort with flat-proof reliability.
EPA emissions standards for off-road diesel equipment indirectly shape tire demand by accelerating fleet turnover to Tier 4 Final-compliant machines requiring matched tire specifications. OSHA worksite safety mandates on load stability and rollover protection influence tire selection criteria for construction firms operating in regulated environments. ISO 4250 dimensional standards govern interchangeability across global OEM platforms, constraining aftermarket product development. Stakeholders must monitor how EU REACH chemical restrictions and evolving EPA durability testing protocols reshape compound formulations and manufacturing cost structures.
Market Dynamics
The construction equipment tire market is being fundamentally restructured by EU REACH chemical restrictions on tire-derived substances, which are forcing compound reformulation across supply chains and compressing margins for manufacturers dependent on legacy carbon black and oil formulations.
Growth Catalysts
- Australian mining fleet renewal:Iron ore and copper operators are replacing aged haul truck fleets, creating synchronized demand for extra-large radial tires rated for 100-ton-plus payloads.
- PLI scheme incentives:India's production-linked incentive program for automotive components is attracting greenfield tire manufacturing investments to serve domestic earthmoving equipment demand.
- Connected tire monitoring:IoT-enabled pressure and temperature sensors embedded in tire casings are reducing unplanned downtime for rental fleet operators managing distributed equipment pools.
Market Restraints
- Natural rubber price volatility:Thai and Indonesian supply disruptions and currency fluctuations are destabilizing input cost planning for compounders.
- Steel cord supply concentration:Three East Asian metallurgical producers control the majority of ultra-high-tensile bead wire, creating single-source vulnerability for radial tire manufacturers.
- REACH compliance friction:ECHA's expanding restricted substance list is forcing reformulation of anti-degradant packages, extending R&D cycles by 18-24 months.
Strategic Opportunities
- Chilean copper expansion:State-owned Codelco and private operators are greenfielding pit mines in the Atacama, opening demand for severe-service tires in a market historically served by used equipment imports.
- Remanufactured casing programs:Premium retread operations using laser-guided buffing and monolithic tread extrusion are capturing fleet maintenance contracts from OEM new-tire sales.
- OSHA silica dust rules:Enhanced worksite safety enforcement is accelerating replacement of worn tires on concrete cutting and demolition equipment to prevent blowouts in enclosed spaces.
Industry Challenges
- Compound chemist scarcity:Formulation expertise for high-load mining applications is concentrated among retiring specialists, constraining new product development pipelines.
- ISO 4250 certification timelines:Dimensional standard testing for new size introductions requires 14-18 months of field validation, delaying market entry for specialized crane tire formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Equipment Tire Market |
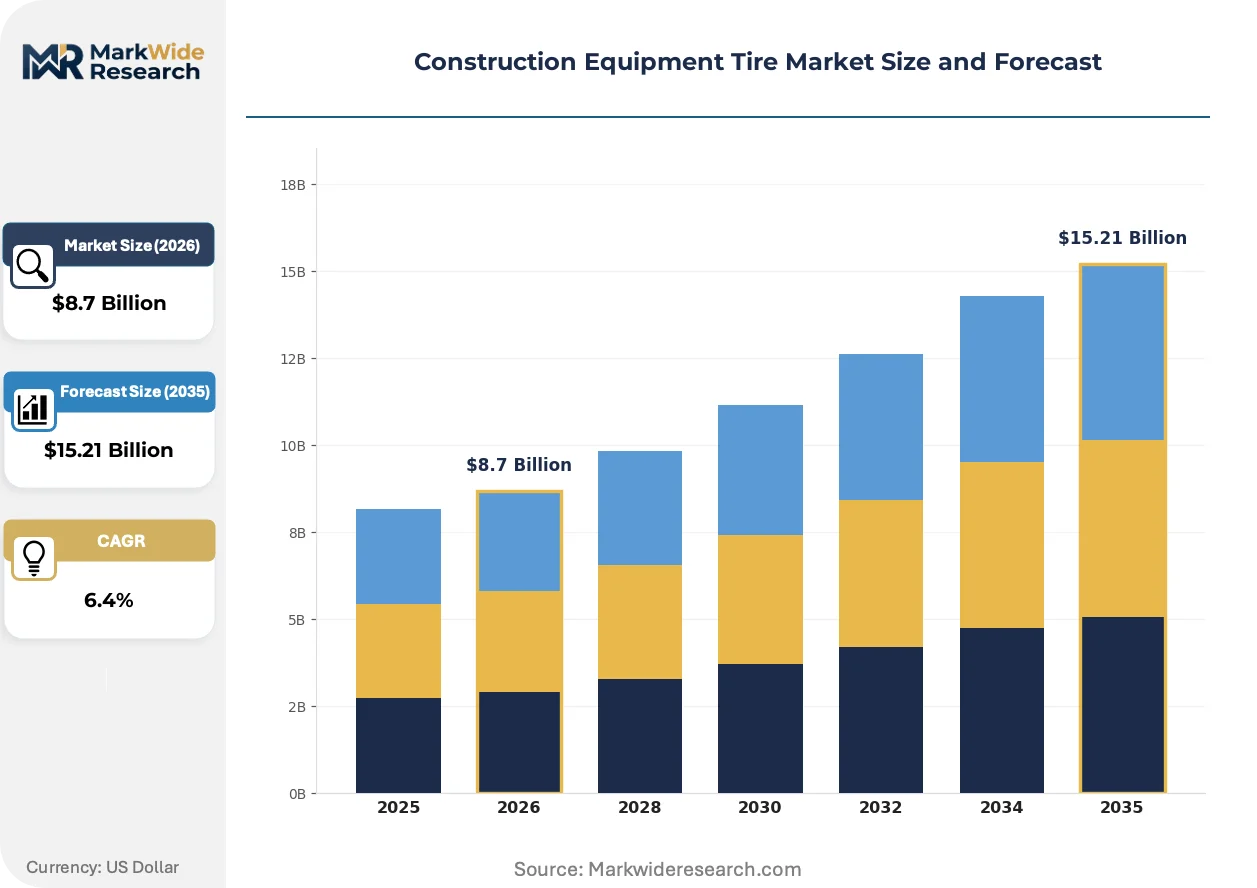
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Solid Tires, Foam-Filled Tires Application: Excavators, Bulldozers, Backhoe Loaders, Cranes End User: Construction Firms, Rental Companies, Agriculture Operators, Mining Companies Distribution Channel: Online Retail, Direct Sales, Distributor Networks, Service Centers |
| Companies Covered | Bridgestone Corporation, Michelin, Yokohama Rubber Company, Balkrishna Industries Limited, Continental AG, Goodyear Tire & Rubber Company, Trelleborg AB, Pirelli & C. S.p.A., Hankook Tire & Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Equipment Tire Market Evolving Landscape
Active innovation in construction equipment tires is concentrating on material science breakthroughs that reconcile durability demands with chemical compliance, while digital integration reshapes how fleet operators manage tire assets across distributed worksites.
Aramid fiber reinforcement is hybridizing with traditional steel belt packages in crane and large excavator radials, delivering equivalent load capacity at 15% reduced unsprung weight. European OEMs are specifying these hybrid constructions for boom trucks operating on finished concrete surfaces where casing deformation must be minimized. The technology is hybridizing procurement criteria, as fleet managers now specify fiber content percentages alongside traditional ply ratings.
EPA Tier 4 Final emissions enforcement is compressing equipment replacement cycles in regulated North American markets, indirectly accelerating tire demand as new machines require matched specifications. Off-road diesel compliance deadlines are forcing rental companies to retire pre-2014 backhoe and loader fleets. California's CARB waivers and Texas construction permit requirements are creating a two-speed replacement market with coastal states leading turnover.
Telematics-enabled tire tracking is supplanting manual inspection regimes for equipment rental chains managing cross-border fleets. Pressure and temperature data streams are triggering automated work-order generation before field failures occur. Australia and Chile are the most advanced adoption markets, where remote mine sites and port logistics operations cannot tolerate unplanned tire-related downtime.
Construction Equipment Tire Market Segmentation
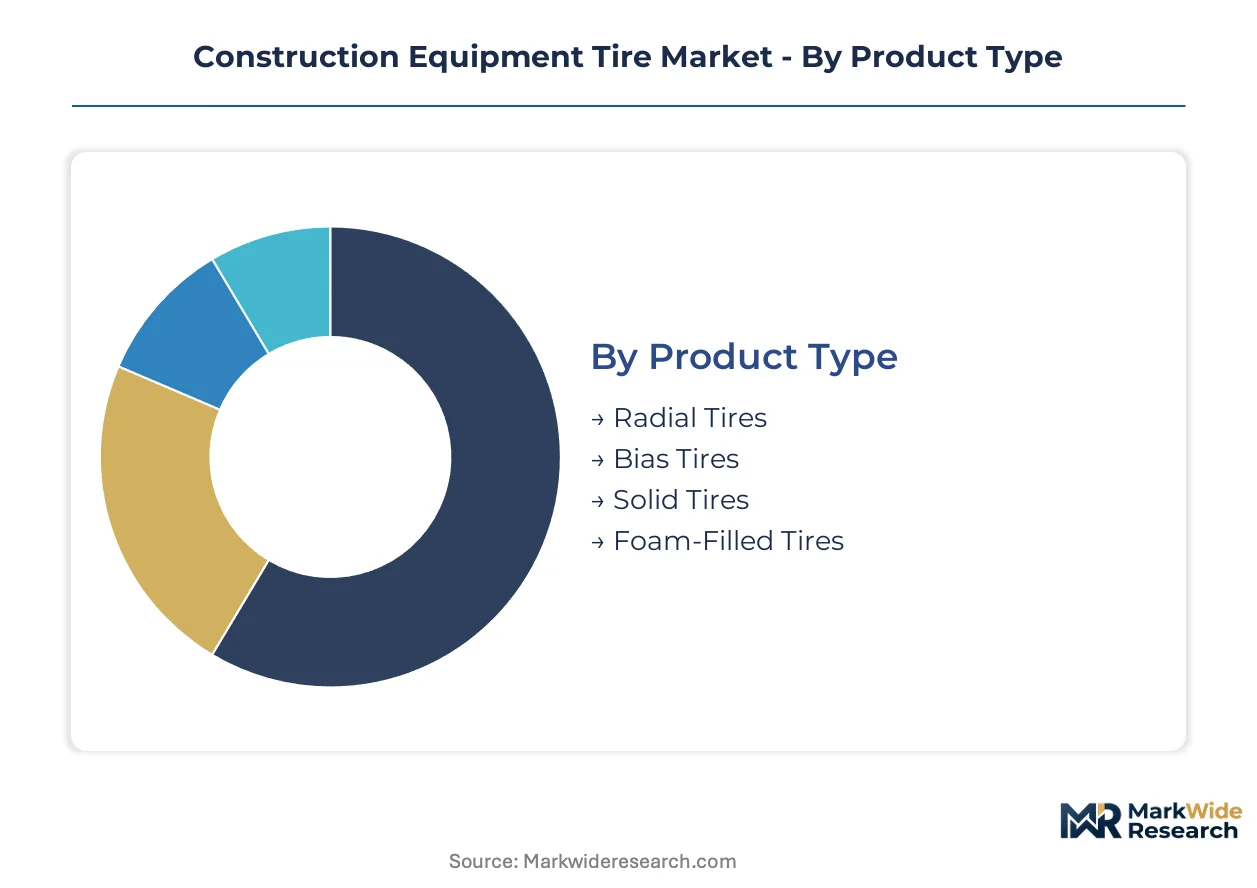
Construction equipment tire segmentation reveals divergent service intensity patterns across product architectures. Radial and solid tire categories demand fundamentally different aftermarket support models, while application-specific load profiles dictate casing durability specifications and replacement cadences.
Product Type:
After-sales service intensity varies dramatically across tire architectures, with radial constructions requiring precision retread management and solid tires demanding specialized mounting equipment and press-fit infrastructure.
- Radial Tires:Steel-belted constructions with textile or steel cord body plies arranged at 90-degree angles to the tread centerline, delivering cooler operating temperatures and extended casing life for high-speed earthmoving. Australian iron ore haulage fleets and Chilean copper operators are standardizing on extra-large radial formats rated for 100-ton-plus payloads, driven by synchronized fleet renewal programs and the total cost advantages of multiple retread cycles.
- Solid Tires:Monolithic elastomer structures eliminating pneumatic pressure entirely, engineered for puncture-proof reliability in demolition, waste handling, and scrap metal operations where debris penetration risks dominate operational economics. Demand concentrates in European recycling facilities and North American transfer stations where OSHA worksite safety mandates on load stability accelerate replacement of worn pneumatic alternatives in enclosed processing environments.
- Bias Tires:Cross-ply constructions with overlapping cord plies at 30-45 degree angles, offering lower first-cost procurement for price-sensitive fleet operators in emerging markets.
- Foam-Filled Tires:Pneumatic casings injected with polyurethane elastomer, bridging ride comfort with flat-proof reliability for niche applications in underground mining and urban demolition.
Radial tires hold the largest share; momentum sits with solid tires as safety regulations tighten across waste handling and demolition segments.
Application:
Equipment duty cycles segment tire demand by load severity, with crane and large excavator applications commanding premium specifications while backhoe loader fleets prioritize procurement flexibility.
- Excavators:High-displacement hydraulic machines operating in abrasive mining and quarry environments, requiring deep-tread patterns and reinforced sidewalls to resist rock cuts and sustained flex fatigue. Indian dam construction and highway earthmoving projects are accelerating demand for severe-service radial fitments, driven by infrastructure outlay expansion and contractor fleet scaling.
- Cranes:Boom-suspension equipment where casing stability directly influences load chart accuracy and outrigger stability calculations, necessitating minimal sidewall deflection and precise load distribution. European OEMs are specifying aramid-steel hybrid constructions for all-terrain mobile cranes, responding to finished-surface protection requirements and reduced unsprung weight targets in urban lifting operations.
- Bulldozers:Tracked and wheeled dozers in land clearing and grading applications, subject to high tractive loads and abrasive soil conditions.
- Backhoe Loaders:Versatile utility equipment dominating emerging-market construction, where first-cost sensitivity and multi-purpose deployment patterns favor bias-ply procurement.
Excavator applications command the highest unit values; crane specifications are climbing the fastest as hybrid reinforcement technologies penetrate European and Australian markets.
End User:
Procurement sophistication separates end-user segments, with mining companies and rental chains adopting telematics-enabled tire management while construction firms and agricultural operators rely on reactive replacement models.
- Mining Companies:Capital-intensive operators managing ultra-class haul truck fleets across remote sites, where unplanned tire failures incur production losses exceeding replacement costs by orders of magnitude. Australian and Chilean operators are deploying connected tire monitoring systems with automated work-order generation, driven by the impossibility of tolerating downtime at pit mines and port logistics facilities.
- Rental Companies:Equipment-as-a-service providers managing distributed cross-border fleets, where tire condition transparency determines utilization rates and contract renewal probabilities. North American rental chains are accelerating replacement of pre-2014 backhoe and loader fleets to match EPA Tier 4 Final-compliant machines with appropriate tire specifications, responding to emissions enforcement deadlines in California and Texas construction permit regimes.
- Construction Firms:Project-based contractors with variable fleet ownership, prioritizing first-cost procurement and local distributor relationships over lifecycle optimization.
- Agriculture Operators:Seasonal equipment users with intermittent earthmoving requirements, typically extending tire service intervals beyond manufacturer recommendations.
Mining companies dominate premium segment procurement; rental companies are expanding most quickly as telematics penetration reshapes fleet management economics.
Distribution Channel:
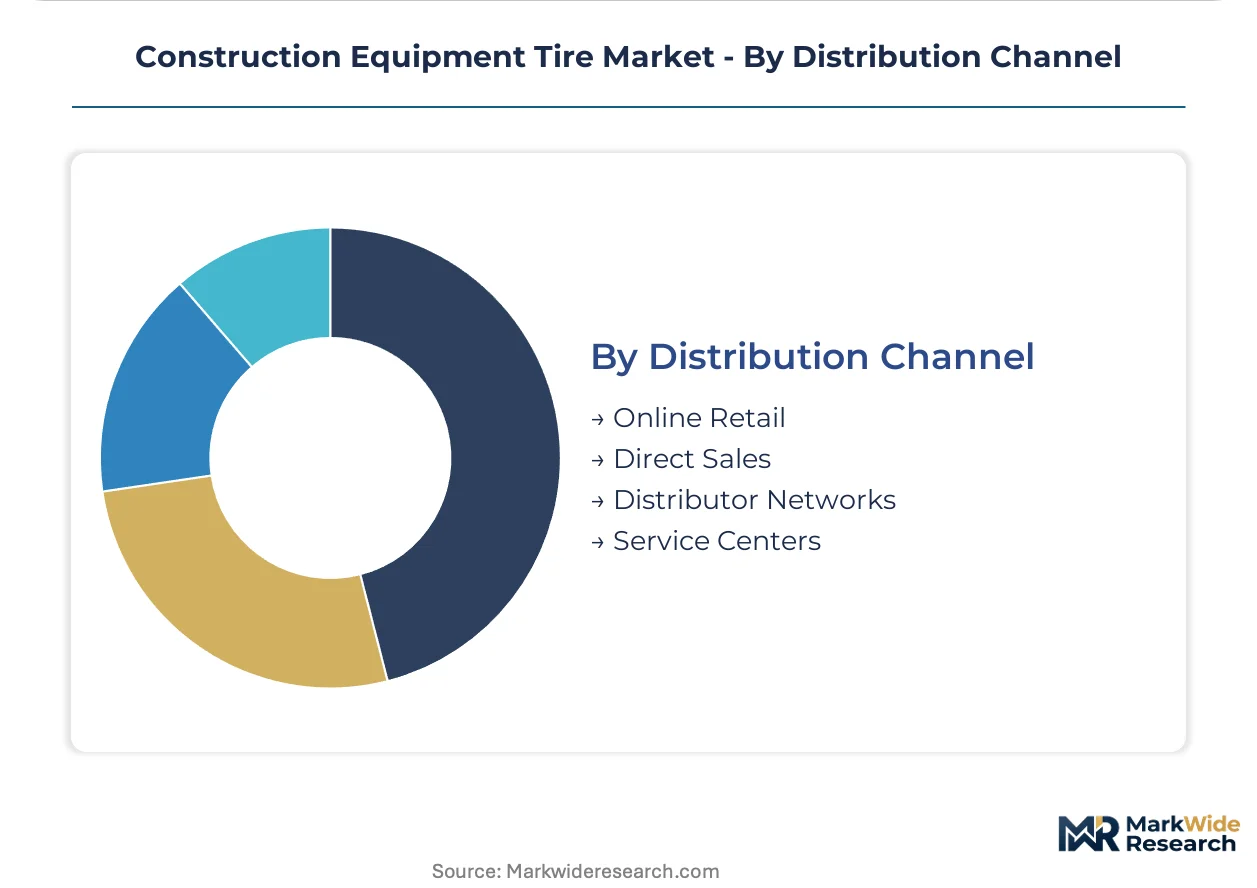
Channel selection reflects equipment criticality and technical support requirements, with direct sales and service centers capturing high-value mining contracts while distributor networks serve fragmented construction demand.
- Distributor Networks:Regional stocking dealers providing same-day availability and field mounting services for construction firms and agricultural operators with unpredictable failure patterns. India's production-linked incentive program for automotive components is attracting greenfield tire manufacturing investments, expanding domestic distributor capacity to serve accelerating earthmoving equipment demand from highway and dam projects.
- Service Centers:Integrated maintenance facilities offering tire supply alongside hydraulic, undercarriage, and engine services, capturing lifecycle contracts from fleet operators seeking single-source accountability. European service centers are retooling for REACH-compliant compound handling and laser-guided retread operations, responding to ECHA's expanding restricted substance list and the margin compression facing legacy carbon black formulations.
- Direct Sales:Manufacturer-direct relationships with mining and rental fleet operators, emphasizing volume commitments and technical collaboration.
- Online Retail:Digital procurement platforms serving small contractors and replacement part buyers with standardized sizes and documented specifications.
Distributor networks retain the broadest reach; service centers are gaining share fastest as integrated maintenance contracts displace transactional tire procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-tensile steel cord production clusters in East Asian metallurgical centers, creating single-source vulnerability for radial tire manufacturers serving mining and heavy construction segments. Three countries dominate demand generation through synchronized fleet renewal cycles and infrastructure investment waves.
Australia
Iron ore and copper operators in the Pilbara and Queensland are replacing aged haul truck fleets, creating synchronized demand for extra-large radial tires rated for 100-ton-plus payloads. The country's national mining safety regulator enforces strict load stability mandates that accelerate tire replacement cycles. Perth anchors aftermarket service networks serving remote pit mines where unplanned downtime incurs production losses exceeding replacement costs by orders of magnitude.
Chile
State-owned Codelco and private operators are greenfielding pit mines in the Atacama, opening demand for severe-service tires in a market historically served by used equipment imports. The national mining regulator applies stringent worksite safety standards that shape tire selection criteria for load stability and rollover protection. Antofagasta concentrates procurement decision-making for northern copper operations, with port logistics facilities demanding telematics-enabled tire monitoring to prevent unplanned failures.
India
Highway and dam projects are accelerating earthmoving activity, tilting demand toward expanded radial tire capacity as infrastructure outlays scale contractor fleets. The production-linked incentive scheme for automotive components is attracting greenfield tire manufacturing investments to serve domestic equipment demand. Mumbai and Delhi-NCR anchor distributor networks stocking same-day availability for construction firms with unpredictable failure patterns.
Germany
European OEMs are specifying aramid-steel hybrid constructions for all-terrain mobile cranes, responding to finished-surface protection requirements and reduced unsprung weight targets. ECHA's expanding restricted substance list under REACH compliance is forcing compound reformulation and extending R&D cycles for anti-degradant packages. The KBA enforces dimensional standard testing that constrains aftermarket product development for specialized crane tire formats.
United States
EPA Tier 4 Final emissions enforcement is compressing equipment replacement cycles, indirectly accelerating tire demand as new machines require matched specifications. OSHA worksite safety mandates on load stability and silica dust exposure are accelerating replacement of worn tires on concrete cutting and demolition equipment. California's CARB waivers and Texas construction permit requirements are creating a two-speed replacement market with coastal states leading turnover.
Construction Equipment Tire Market Competitive Landscape
Integrated rubber compound researchers and connected tire monitoring specialists split the market between premium positioning and service-interval predictability. The vendor base organizes around three strategic archetypes: vertically integrated material scientists controlling compound formulations, telematics-enabled fleet solution providers, and regional scale fabricators serving price-sensitive procurement. Dominant competitive moves include backward integration into captive rubber supply and technology licensing for IoT-enabled pressure monitoring systems.
Among Japanese material science conglomerates, Bridgestone Corporation and Yokohama Rubber Company exemplify the integrated research archetype, anchoring premium positioning through in-house compound development. Continental AG occupies a position within the connected systems tier, representing European engineering depth in sensor-embedded casing technology. These three entities sit within distinct competitive vectors—compound innovation, digital integration, and regional manufacturing scale—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin |
| Yokohama Rubber Company |
| Balkrishna Industries Limited |
| Continental AG |
| Goodyear Tire & Rubber Company |
| Trelleborg AB |
| Pirelli & C. S.p.A. |
| Hankook Tire & Technology |
| Others |
Value Network & Pricing Analysis
The Shanghai-Long Beach transpacific corridor anchors freight cost dynamics for steel cord and carbon black imports, compressing margins for compounders while amplifying price differentiation between REACH-compliant European formulations and legacy Asian supply. This logistics chokepoint concentrates pricing power among East Asian metallurgical producers and forces downstream tire manufacturers to absorb volatility or pass through costs to mining fleet operators.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across the construction equipment tire market, separating premium aramid-steel hybrid constructions from standard radial formulations and economy bias-ply alternatives. Price differentiation centers on certification grade for chemical compliance and volume scale for fleet procurement contracts. Cost compression in the standard tier is intensifying because ECHA's expanding restricted substance list extends R&D cycles for anti-degradant packages. Mining companies exhibit the least price sensitivity due to production loss economics, while emerging-market construction firms remain most reactive to first-cost procurement.
Supply Chain Analysis
Three East Asian metallurgical producers control the majority of ultra-high-tensile bead wire capacity, anchoring radial tire manufacturing in China, Japan, and South Korea. Raw material dependencies draw from Thai and Indonesian natural rubber harvests, Russian carbon black feedstocks, and Australian iron ore for steel cord production. Single-source vulnerability in bead wire supply creates systemic exposure to geopolitical disruption or trade restriction. Distribution runs through integrated service centers for mining contracts and regional distributor networks for fragmented construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The construction equipment tire market functions as a service-attach opportunity where telematics-enabled tire management and precision retread programs expand faster than hardware sales. Connected monitoring subscriptions and lifecycle maintenance contracts now generate recurring revenue streams that outpace unit shipment growth.
For Market Incumbents: Insulate premium positioning by deepening captive supply of REACH-compliant rubber compounds and securing ISO 4250 certification pipelines for specialized crane formats. Compound chemist scarcity threatens new product development timelines; anchor expertise through targeted retention and technical apprenticeship programs. Defensive consolidation of retread infrastructure in Australia and Chile captures fleet maintenance contracts before remanufactured casing programs displace new-tire sales.
For New Entrants and Emerging Players: Establish a beachhead in India's expanding radial capacity segment by leveraging PLI scheme incentives and domestic dam construction demand. The bias-ply backhoe loader market in Southeast Asia offers the most penetrable white-space target for price-disruptive procurement. A go-to-market angle anchored on same-day distributor availability and field mounting services bypasses incumbent service center dominance.
For Investors and Strategic Acquirers: Regional service center networks with integrated maintenance capabilities and laser-guided retread operations represent the priority acquisition archetype for this market. Long-term viability across the projection horizon depends on telematics penetration rates and chemical compliance adaptation speed. Watch adoption velocity of connected tire monitoring in Australian iron ore haulage as the inflection indicator for fleet management economics transformation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Rubber Supply | REACH-compliant compound control secures margin structure against ECHA regulatory expansion. |
| Telematics Platform Licensing Agreement | Sensor-embedded casing technology transfers to rental fleet operators managing distributed equipment pools. |
| Greenfield Manufacturing Scale-Up | PLI scheme incentives in India attract capacity expansion serving domestic earthmoving equipment demand. |
| Precision Retread Infrastructure Buildout | Laser-guided buffing operations capture lifecycle contracts from OEM new-tire sales in mining segments. |
| Long-Term Fleet Maintenance Contract | Integrated tire supply and monitoring services lock in utilization rates for cross-border rental chains. |
Research Methodology
Initial hypotheses were tested against primary input from mining fleet maintenance directors, tire compound R&D leads, rental company operations executives, and aftermarket service center managers, then refined through secondary validation against customs trade data, SEC filings from listed tire manufacturers, ECHA regulatory submissions, and ISO standard documentation. Bottom-up triangulation across equipment fleet counts and replacement cadences was cross-checked with top-down market sizing from raw material consumption patterns.
Demand-supply balance framing anchored the analytical approach across the analysis window, modeling volume trajectories through product type, application severity, end-user procurement sophistication, and regional infrastructure investment cycles. CAGRs were derived from segment-level replacement economics and fleet expansion rates rather than macroeconomic extrapolation. Industry-specific forecast inputs included mining production targets from Australian and Chilean operators and highway construction outlays from Indian infrastructure ministries.
Stress conditions across natural rubber price volatility, steel cord supply disruption, and REACH compliance timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet renewal synchronization and telematics adoption curves. Quarterly review of mining capital expenditure announcements and ECHA restricted substance list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Garage Equipment Market
Construction Equipment
Construction Wearable Technology Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
United States Crane Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Autonomous Cranes Market
Construction Equipment
Concrete Chain Saw Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Cement and Mortar Testing Equipment Market
Construction Equipment
GCC Crane Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Excavation Equipment Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Compact Power Equipment Rental Market