
 Global Metal Expansion Joints Market | 2026-2036
Global Metal Expansion Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Global Metal Expansion Joints Market Outlook
Stainless steel 316L is rebalancing procurement economics across the metal expansion joints supply base as nickel price volatility pushes engineers toward duplex alloy formulations. Witzenmann leverages its German manufacturing footprint to sustain long-term contracts with European chemical processors. EagleBurgmann anchors its position through backward integration into precision bellows forming. Senior Flexonics differentiates via specialized hydroforming capabilities for aerospace ducting applications.
Metal expansion joints are engineered flexible pressure-bearing elements constructed from single or multiple thin-walled metallic bellows convolutions, designed to absorb thermal expansion, mechanical vibration, and installation misalignment in piping systems while maintaining pressure boundary integrity. Multi bellows configurations dominate high-pressure steam circuits in power generation, where cumulative axial movement exceeds single-convolute capacity. Oil and gas applications represent the most mature demand pool, with margin concentration shifting toward subsea riser assemblies and cryogenic transfer lines. Water treatment infrastructure is generating incremental volume for non-metallic lined expansion joints handling aggressive effluent streams.
The American Society of Mechanical Engineers (ASME) Boiler and Pressure Vessel Code governs design qualification in North American process installations, while the European Pressure Equipment Directive (PED) mandates conformity assessment for CE-marked bellows assemblies sold across EU member states. China's GB/T 12777 standard shapes domestic procurement specifications for metallic expansion joints in thermal power stations. Stakeholders must monitor divergence between regional pressure equipment codes as project engineering increasingly sources components across multiple certification jurisdictions.
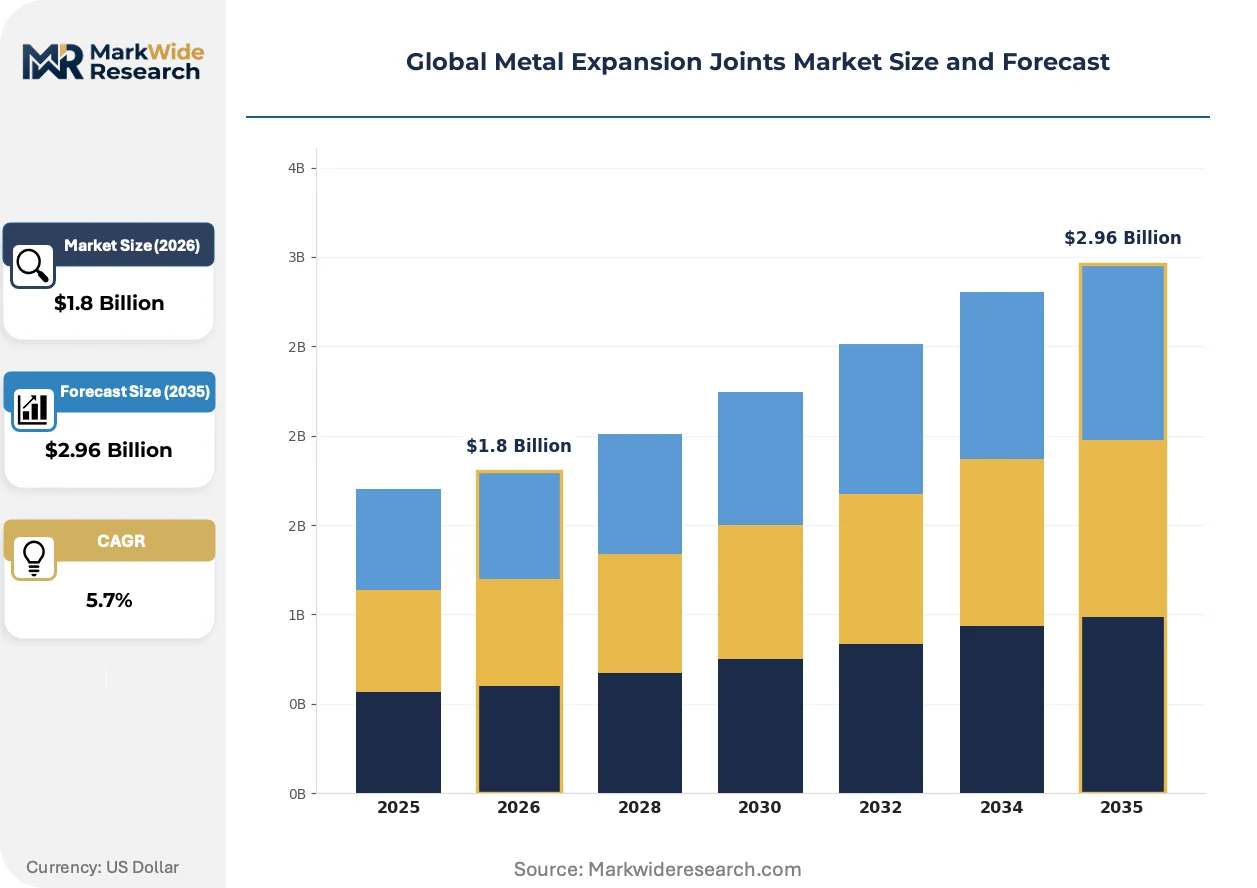
Market Dynamics
The metal expansion joints market is experiencing fundamental restructuring as nickel price volatility forces material substitution toward duplex stainless formulations, compressing traditional 316L procurement economics while opening premium alloy segments.
Growth Catalysts
- F-Gas Regulation:The European Union's F-Gas Regulation is redirecting capital toward metallic sealing solutions in process industries, displacing fluorinated polymer alternatives in high-temperature applications.
- Combined-cycle gas turbine expansion:Power generation utilities across Asia-Pacific are expanding procurement of high-cycle metal bellows for new turbine installations, driving demand for fatigue-resistant convolute designs.
- Gujarat petrochemical corridor:Refinery expansions along India's western coast require corrosion-resistant expansion joint assemblies, concentrating demand for super-austenitic and nickel-alloy bellows.
Market Restraints
- Nickel input volatility:London Metal Exchange nickel price swings above 40% annually destabilize cost structures for austenitic stainless steel bellows, forcing inventory risk onto fabricators.
- Supply concentration in precision forming:Hydroforming and roll-forming capacity clusters in Germany and Japan, creating single-source dependencies for aerospace-qualified convolutes.
- Technical limitation in ultra-high pressure:Single-ply bellows designs face pressure-temperature envelope constraints above 150 bar, restricting addressable share in subsea riser applications.
Strategic Opportunities
- Saudi downstream expansion:Neom and Jafurah gas development projects are generating demand for cryogenic transfer line expansion joints, a white space previously served by European imports.
- CE marking convergence:The European Pressure Equipment Directive is harmonizing conformity assessment across EU member states, enabling pan-European scale economies for certified bellows assemblies.
- Additive manufacturing convergence:Hybrid production combining laser powder bed fusion with conventional forming is enabling complex multi-ply geometries for nuclear primary loop applications.
Industry Challenges
- ASME Section VIII certification timelines:Design qualification cycles for Boiler and Pressure Vessel Code compliance extend 18-24 months, compressing project windows for North American power sector contracts.
- Skill scarcity in precision welding:Automated TIG welding of thin-walled bellows convolutions requires specialized operator certification, with training pipelines failing to match replacement demand in mature economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Metal Expansion Joints Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Bellows, Multi Bellows, Metallic, Non-Metallic Application: Oil & Gas, Power Generation, Chemical Processing, Water Treatment End User: Manufacturing, Construction, Marine, Aerospace Installation Type: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | Witzenmann, EagleBurgmann, Senior Flexonics, BOA Group, Kadant Unaflex, Metraflex, Belman A/S, Macoga, Flexicraft Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Metal Expansion Joints Market Strategic Shifts
Material science advances and regulatory harmonization are compressing traditional supply hierarchies while enabling new application domains for metallic flexible elements. Three developments warrant particular attention.
Duplex stainless steel 2205 and 2507 grades are consolidating position in offshore and chemical processing applications where chloride stress corrosion cracking resistance exceeds 316L capabilities. Norwegian subsea contractors are specifying these alloys for riser tensioner systems, displacing nickel-based alternatives at 60% lower material cost. The shift is consolidating procurement volumes around mills with duplex melting capacity, marginalizing single-grade stainless suppliers.
China's GB/T 12777 standard revision is tightening dimensional tolerance requirements for thermal power station bellows, forcing domestic fabricators toward CNC convolution forming. The regulatory tightening is accelerating technology transfer from European joint venture partners while creating compliance barriers for low-cost regional competitors. Domestic procurement specifications now reference the updated standard for all ultra-supercritical boiler feedwater applications.
Engineering-procurement-construction firms are unbundling expansion joint specification from general piping packages, creating direct manufacturer relationships for critical path items. This disintermediation is visible in Middle Eastern petrochemical projects where EPCs now retain separate bellows technical specialists. The model compresses margin capture by distribution intermediaries while extending manufacturer liability exposure.
Global Metal Expansion Joints Market Segmentation
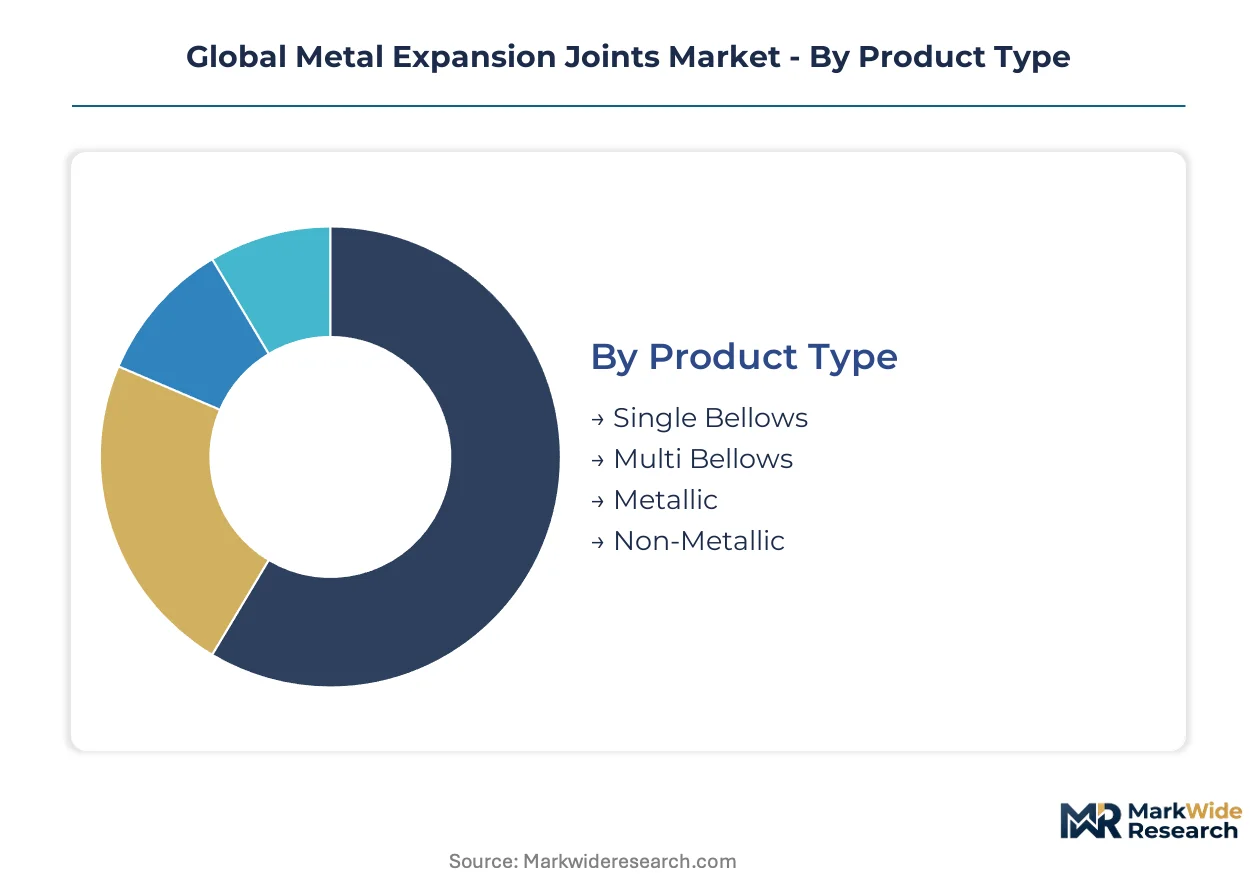
Metal expansion joints serve radically different duty cycles across pressure ratings, temperature envelopes, and corrosion environments. Segmentation reveals where material science investments concentrate versus where commoditized procurement dominates.
Product Type:
Volume concentrates in single-convolute designs for standard industrial piping, while premium economics accrue to engineered multi-ply configurations for critical service.
- Single Bellows:Thin-walled convolute designs handle axial thermal movement in low-to-moderate pressure steam and process lines. Demand clusters in India's thermal power refurbishment programs where legacy installations require direct replacement compatibility.
- Multi Bellows:Nested or stacked convolute assemblies accommodate cumulative movement exceeding single-ply capacity in high-pressure circuits. Combined-cycle gas turbine installations across Saudi Arabia and the UAE specify these for fatigue-resistant steam bypass lines.
- Metallic:Stainless steel, nickel alloy, and duplex formulations maintain pressure boundary integrity across cryogenic to elevated temperature service.
- Non-Metallic:PTFE-lined or elastomeric composite constructions handle aggressive chemical effluent where metallic corrosion rates prove uneconomical.
Today's leader: Multi Bellows. Tomorrow's challenger: Non-Metallic.
Application:
End-use maturity varies sharply, with established hydrocarbon processing funding incremental upgrades while water infrastructure creates new specification categories.
- Oil & Gas:Subsea riser tensioners and cryogenic LNG transfer lines command super-austenitic and Inconel specifications. Norwegian North Sea contractors are consolidating procurement around duplex 2507 for chloride-resistant riser assemblies at 40% below nickel alloy cost.
- Power Generation:Ultra-supercritical boiler feedwater circuits require ASME Section VIII-certified bellows with 200,000-cycle fatigue life. China's GB/T 12777 revision is tightening dimensional tolerances for domestic turbine OEM supply chains.
- Chemical Processing:Acid service and high-temperature catalyst regeneration units drive demand for Hastelloy and titanium convolutes.
- Water Treatment:Municipal desalination and industrial effluent handling generate volume for lined expansion joints in chloride-rich environments.
Power Generation retains the steepest expansion trajectory through Asia-Pacific capacity additions.
End User:
Customer technical sophistication determines whether procurement emphasizes catalog specifications or collaborative engineering development.
- Manufacturing:Process plant maintenance organizations favor standardized single-bellows designs with rapid delivery cycles.
- Construction:EPC contractors are unbundling expansion joint specification from general piping packages, creating direct manufacturer relationships for critical path items.
- Marine:Ship exhaust systems and cargo handling infrastructure require vibration-isolating flexible elements certified to Lloyd's Register or DNV rules.
- Aerospace:Engine ducting and fuel system applications demand hydroformed convolutes with micro-inch surface finish control.
Construction channels the largest absolute spend. Aerospace captures the highest engineering margin.
Installation Type:
Environmental exposure severity dictates alloy selection, protective coating requirements, and inspection protocol intensity.
- Onshore:Refinery and petrochemical plant installations access established maintenance infrastructure and standardized replacement inventories.
- Offshore:Platform and subsea applications impose salt spray, wave loading, and remote access constraints that favor corrosion-resistant duplex formulations.
- Indoor:Climate-controlled process buildings reduce thermal cycling severity and extend service intervals for standard 316L constructions.
- Outdoor:Exposed piping bridges and tank farm connections require weather-resistant external covers and accelerated inspection schedules.
Offshore commands specification premiums. Indoor offers volume scale.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat's petrochemical corridor along India's western coast commands concentrated procurement for corrosion-resistant expansion joint assemblies serving refinery expansions and chemical processing infrastructure.
United States
Combined-cycle gas turbine retrofits and ultra-supercritical coal plant upgrades drive demand for ASME Section VIII-certified multi-ply bellows with extended fatigue life cycles. The Federal Energy Regulatory Commission oversees interstate pipeline safety standards affecting expansion joint specification in transmission infrastructure. Houston's Energy Corridor hosts engineering-procurement-construction firms unbundling bellows procurement from general piping packages for Gulf Coast petrochemical projects.
Germany
European chemical processors are redirecting capital toward metallic sealing solutions as the EU F-Gas Regulation displaces fluorinated polymer alternatives in high-temperature process applications. The European Pressure Equipment Directive mandates conformity assessment for CE-marked bellows assemblies sold across member states. Witzenmann leverages its manufacturing footprint in Baden-Württemberg to sustain long-term supply contracts with Ludwigshafen and Leverkusen chemical complexes.
China
Thermal power station refurbishment programs and ultra-supercritical boiler installations generate procurement volume for GB/T 12777-compliant metallic expansion joints with tightened dimensional tolerances. The Ministry of Ecology and Environment enforces emissions standards that accelerate replacement cycles in legacy coal-fired generation. The Yangtze River Delta manufacturing belt concentrates domestic fabrication capacity serving both domestic turbine OEMs and export markets.
Saudi Arabia
Neom and Jafurah gas development projects are generating demand for cryogenic transfer line expansion joints in downstream processing and hydrogen export infrastructure. The Saudi Food and Drug Authority and national standardization bodies align pressure equipment regulations with international codes to facilitate technology transfer. The Eastern Province industrial zone around Jubail anchors fabrication demand for subsea riser assemblies and LNG handling systems.
Japan
Precision hydroforming capacity for aerospace ducting applications and nuclear primary loop bellows sustains premium-tier manufacturing specialization. The Ministry of Economy, Trade and Industry supports domestic capability retention for strategic energy infrastructure components. Nagoya's Chubu industrial region concentrates automated TIG welding expertise for thin-walled convolute production serving regional turbine manufacturers.
Global Metal Expansion Joints Market Competitive Environment
Global majors compete with regional champions across certification jurisdiction coverage and precision forming technology access. The vendor base clusters around German and Japanese hydroforming capacity for aerospace-qualified convolutes, while North American and Indian fabricators dominate standard industrial procurement. Three archetypes define competitive positioning: vertically integrated precision formers with captive bellows production, specialized aerospace ducting specialists with micro-inch surface finish capabilities, and regional maintenance suppliers with rapid replacement inventory models. Dominant competitive moves include backward integration into precision forming equipment and geographic expansion through CE marking convergence to capture pan-European scale economies.
Among European-based fabricators, Witzenmann GmbH and EagleBurgmann represent the vertically integrated tier with sustained long-term contract positions in chemical processing markets. Senior Flexonics occupies a specialization position in hydroformed aerospace applications. BOA Group exemplifies the regional champion archetype serving maintenance procurement with standardized industrial designs. These three anchors illustrate how competitive positioning stratifies across certification depth, forming technology, and end-use specialization rather than scale alone.
| Leading Market Players |
|---|
| Witzenmann |
| EagleBurgmann |
| Senior Flexonics |
| BOA Group |
| Kadant Unaflex |
| Metraflex |
| Belman A/S |
| Macoga |
| Flexicraft Industries |
| Others |
Value Chain & Pricing Dynamics
Combined-cycle gas turbine procurement specifications across Asia-Pacific are forcing fabricators toward fatigue-resistant multi-ply convolute designs, compressing margins on standard single-bellows production while opening premium pricing tiers for certified assemblies. This specification upgrade cascades through raw material procurement, with duplex alloy premiums reshaping supplier qualification economics.
Pricing Analysis
London Metal Exchange nickel volatility passes through to austenitic stainless steel bellows on 60-90 day lags, forcing fabricators to absorb inventory risk or demand price escalation clauses. Pricing stratifies across ASME Section VIII-certified premium tiers, CE-marked standard industrial grades, and uncertified economy replacements for maintenance procurement. Cost compression in standard 316L single-bellows segments is intensifying as Indian fabricators expand hydroforming capacity. Maintenance procurement teams at Gulf Coast refineries exhibit highest price sensitivity, while nuclear primary loop specifications show near-zero elasticity due to qualification barriers.
Supply Chain Analysis
Dual-sourcing mandates from European chemical processors and Saudi Aramco engineering standards require qualified suppliers in both Germany and Japan for critical path bellows. Raw material supply draws from Finnish duplex melting capacity, Japanese precision strip rolling, and Chinese seamless tubing mills. Commodity price volatility in nickel and molybdenum concentrates represents the dominant structural risk, with single-source dependencies in aerospace-qualified hydroforming creating secondary exposure. Distribution runs through EPC technical specialists unbundling specification from general piping packages, compressing traditional distributor margins.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between European F-Gas Regulation compliance costs and Asian manufacturing scale creates margin capture opportunities for suppliers with multi-jurisdiction certification coverage. The cost differential on CE-marked duplex assemblies versus uncertified alternatives exceeds material input spreads alone.
For Market Incumbents: Deploy backward integration into precision roll-forming equipment to defend against emerging Asian competitors with lower labor input costs. Secure long-term offtake agreements with Finnish and Swedish duplex alloy mills to lock in material cost advantages. Anchor position through captive supply of thin-walled strip stock for aerospace-qualified convolutes. For New Entrants and Emerging Players: Launch via direct EPC relationships in Saudi downstream expansion projects, bypassing established distributor channels serving European chemical processors. Target cryogenic transfer line specifications for Neom and Jafurah gas developments as the most penetrable white space, where European import dependence creates qualification windows for new entrants with ASME and PED dual certification. For Investors and Strategic Acquirers: Asymmetric upside sits with precision hydroforming specialists serving aerospace ducting applications, where micro-inch surface finish capabilities create defensible moats against commodity fabrication. Long-term viability hinges on additive manufacturing convergence for nuclear primary loop geometries. Watch for GB/T 12777 standard tightening in China as the inflection signal for technology transfer premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Forming | Captive hydroforming capacity insulates margin from nickel volatility and Asian labor arbitrage. |
| Dual ASME-PED Certification Investment | CE marking convergence enables pan-European scale economies for Middle East project exports. |
| Hybrid Additive Manufacturing Adoption | Laser powder bed fusion unlocks complex multi-ply geometries for nuclear primary loop applications. |
| Direct EPC Relationship Development | Unbundling from general piping packages captures margin previously captured by distribution intermediaries. |
| Duplex Alloy Supply Agreement | Long-term offtake with Finnish mills locks in 60% material cost advantage over nickel-based alternatives. |
Study Parameters
Multiple input streams — primary interviews with plant engineers and EPC procurement leads, trade data reconciliation, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Conversations with maintenance directors at Gulf Coast refineries, nuclear qualification specialists, and hydroforming equipment manufacturers informed capacity and technology assumptions. Secondary validation drew from ASME Boiler and Pressure Vessel Code interpretation bulletins, EU F-Gas Regulation implementation guidance, Chinese GB/T standard revision notices, and customs records for duplex alloy strip trade flows. Bottom-up project pipeline enumeration was cross-checked against top-down industrial capex forecasts.
Historical shipment patterns were cross-referenced against panel input from bellows fabricators and alloy mill sales teams to anchor growth trajectories across the projection horizon. The analytical framework modeled product type, application severity, end-user technical sophistication, and installation environment as core segmentation dimensions. CAGRs were derived from elasticity-adjusted demand curves reflecting nickel price substitution effects and regulatory-driven specification upgrades. Nuclear refurbishment cycles and combined-cycle gas turbine commissioning schedules provided industry-specific forecast anchors.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained nickel price volatility above historical bands or accelerated F-Gas Regulation enforcement timelines. Forecasts reflect documented assumptions regarding alloy substitution elasticities and certification timeline stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Hydraulic Hose and Fittings Market
Material Handling Equipment
Reach Trucks Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Global Linear Guide Market
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Pallet Truck Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Spring Shackles Market
Material Handling Equipment
Hoist Chains Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Rail Mounted Gantry Crane Market
Material Handling Equipment
Forklift Rental Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Global Warehouse Racking Market
Material Handling Equipment
Coal Handling Equipment Market