
 Southeast Asia Concrete Admixtures Market | 2026-2036
Southeast Asia Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Concrete Admixtures Market Analytics
Polycarboxylate ether (PCE) superplasticizer chemistry is tilting Southeast Asian formulation standards away from older naphthalene and melamine sulfonate bases. Sika AG leverages its Swiss R&D heritage to anchor premium PCE supply chains across Thailand and Malaysia. MBCC Group sustains competitive pressure through specialized alkali-free accelerators tailored for tropical humidity conditions. Fosroc Inc. differentiates via technical service teams embedded with infrastructure developers in the Philippines and Indonesia.
Concrete admixtures are chemical additives dosed at 0.5-5.0% by weight of cement to modify fresh or hardened concrete properties, including slump retention, set time control, and freeze-thaw resistance; their primary purpose is enabling specified performance in concrete mixes that would otherwise fail workability or durability requirements. Superplasticizers dominate value pools due to their critical role in high-performance concrete for megaproject foundations across the region. Ready-mix concrete applications expand fastest as batching plant networks proliferate in Vietnam and Indonesia, displacing site-mixed alternatives. Residential construction remains a mature volume channel with thinner margins, while civil engineering firms represent the most concentrated end-user segment for specialty admixture procurement.
Indonesia's BIS-aligned SNI concrete standards, Thailand's industrial product standards administered by the Thai Industrial Standards Institute, and Vietnam's Ministry of Construction technical regulations collectively mandate performance testing for imported admixture formulations. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established local laboratory certification. Stakeholders must monitor evolving green building codes across ASEAN member states that increasingly specify embodied carbon thresholds for concrete supply chains.
Market Dynamics
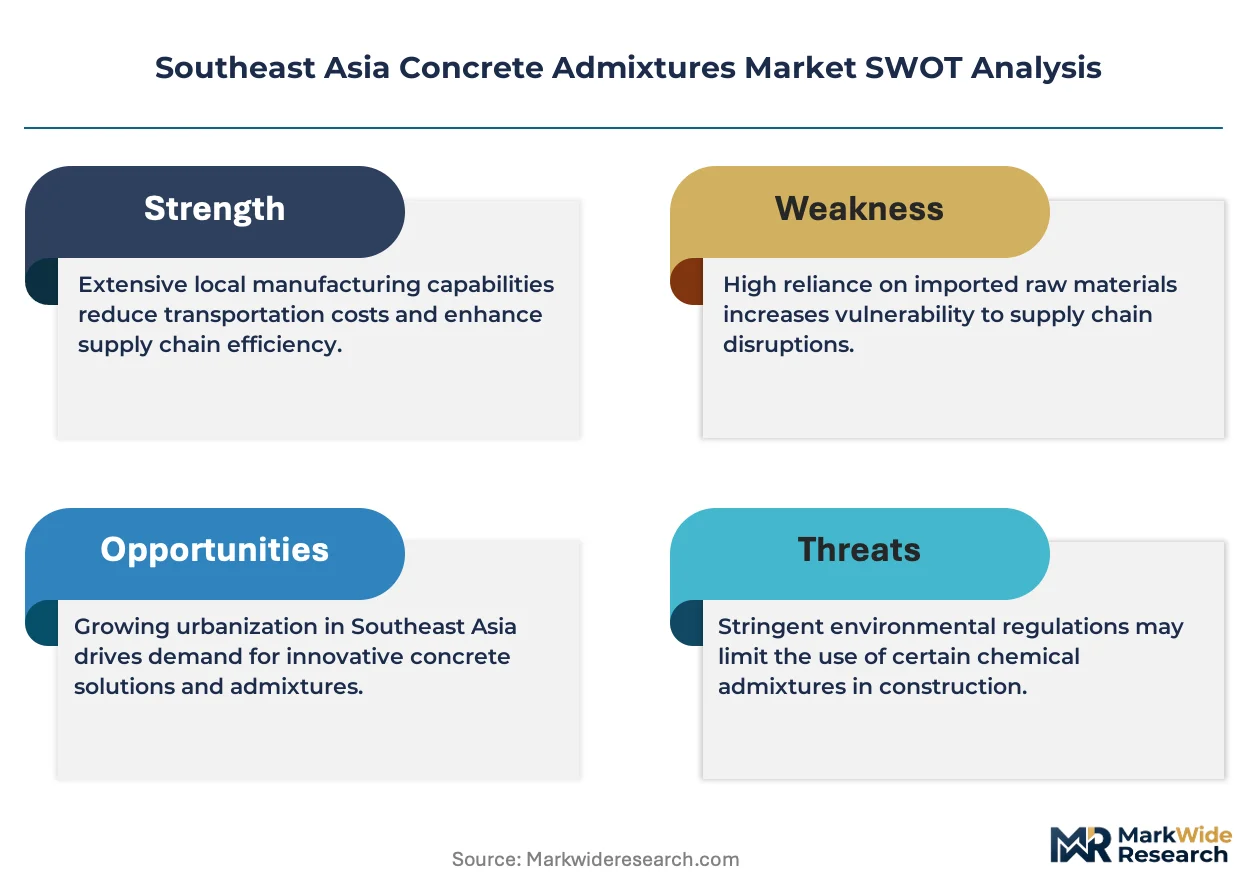
Polycarboxylate ether superplasticizers are compressing formulation margins across Southeast Asia as batching plants standardize on high-range water reducers and reject older chemistries. Indonesia's SNI concrete durability mandates accelerate this chemistry transition.
Growth Catalysts
- Indonesia's SNI 7656 Standard:Mandatory chloride permeability testing for infrastructure concrete drives specification of corrosion-inhibiting admixtures in Jakarta's elevated transit corridors.
- High-rise residential towers:Foundation designs exceeding 60 stories in Bangkok and Ho Chi Minh City require self-consolidating concrete enabled by viscosity-modifying admixtures.
- Alkali-silica reaction mitigation:Volcanic aggregate deposits across the Philippines necessitate lithium-based admixtures for dam and bridge longevity.
Market Restraints
- Naphthalene sulfonate oversupply:Legacy production capacity in China exports below-cost superplasticizers, eroding PCE price floors in Vietnam and Thailand.
- Ethylene oxide feedstock volatility:PCE polymer production depends on petrochemical derivatives subject to ASEAN refinery output fluctuations.
- Retarder incompatibility:Tropical heat formulations using sucrose-based set controllers degrade in extended storage, limiting distribution radius from production hubs.
Strategic Opportunities
- Myanmar infrastructure reconstruction:Post-conflict cement demand in Yangon-Mandalay corridor lacks local admixture blending capacity, creating import substitution potential.
- Carbon mineralization admixtures:CO2-cured concrete technologies align with Singapore's Building and Construction Authority green mark incentives for embodied carbon reduction.
- Ready-mix channel consolidation:Independent batching plants in Vietnam's Binh Duong province seek technical service partnerships absent from commodity chemical distributors.
Industry Challenges
- Formulation chemist scarcity:Southeast Asian universities produce civil engineers with limited polymer chemistry training, forcing suppliers to import technical staff from South Korea and Japan.
- SNI laboratory accreditation timelines:Indonesia's national standardization agency requires 14-18 months for foreign admixture certification, delaying market entry against domestic incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Concrete Admixtures Market |
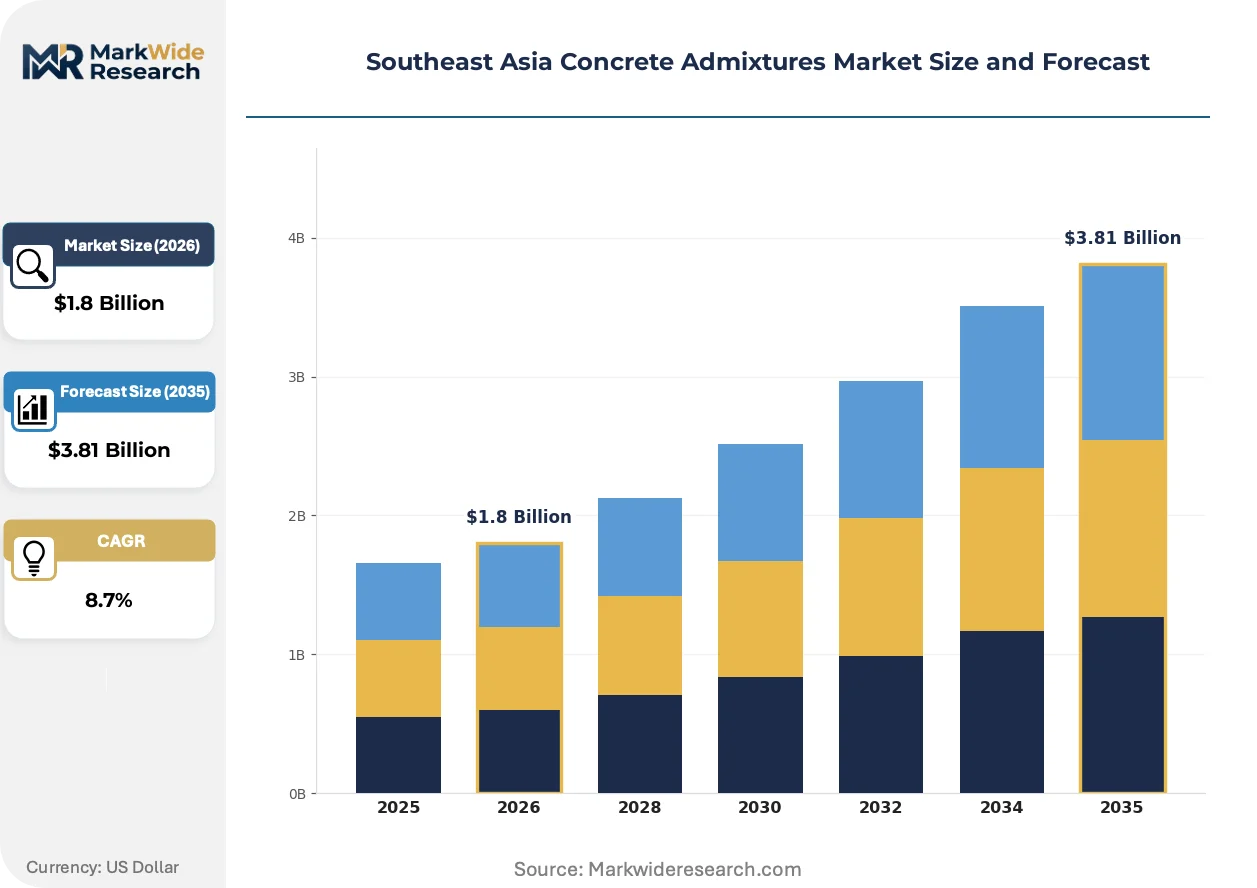
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superplasticizers, Retarding Admixtures, Accelerating Admixtures, Air-Entraining Agents Application: High-Performance Concrete, Precast Concrete, Ready-Mix Concrete, Residential Construction End User: Construction Companies, Civil Engineering Firms, Infrastructure Developers, Specialty Contractors Sales Channel: Direct Sales, Distributors, Online Sales, Retail Stores |
| Companies Covered | Sika AG, BASF SE, Fosroc Inc., MAPEI SpA, GCP Applied Technologies Inc., CEMEX SAB de CV, MBCC Group, Saint-Gobain, RPM International Inc., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Concrete Admixtures Market Evolving Landscape
Admixture functionality is converging with digital concrete monitoring systems, creating specification packages where chemical performance ties directly to real-time batch quality verification. This integration rewards suppliers with embedded technical service capabilities.
Hybrid PCE-silica fume nanocomposite superplasticizers achieve 40% water reduction while maintaining 4-hour slump retention in tropical conditions. Infrastructure contractors on Indonesia's Trans-Java toll road are specifying these formulations exclusively. Older melamine-based alternatives are rendering obsolete for projects above grade 50 concrete strength.
Thailand's Industrial Standards Institute revised TIS 280-2563 to mandate admixture performance declarations under accelerated carbonation testing. Imported formulations now require Bangkok-based laboratory validation. Specialty accelerator suppliers are establishing captive testing facilities in Samut Prakan to circumvent approval delays.
Batching plant procurement teams are consolidating annual contracts across multiple project sites, replacing project-by-project spot purchasing. This concentration shifts bargaining power to ready-mix networks in Ho Chi Minh City and Jakarta. Technical service bundling now determines supplier selection more than unit chemistry pricing.
Southeast Asia Concrete Admixtures Market Segmentation
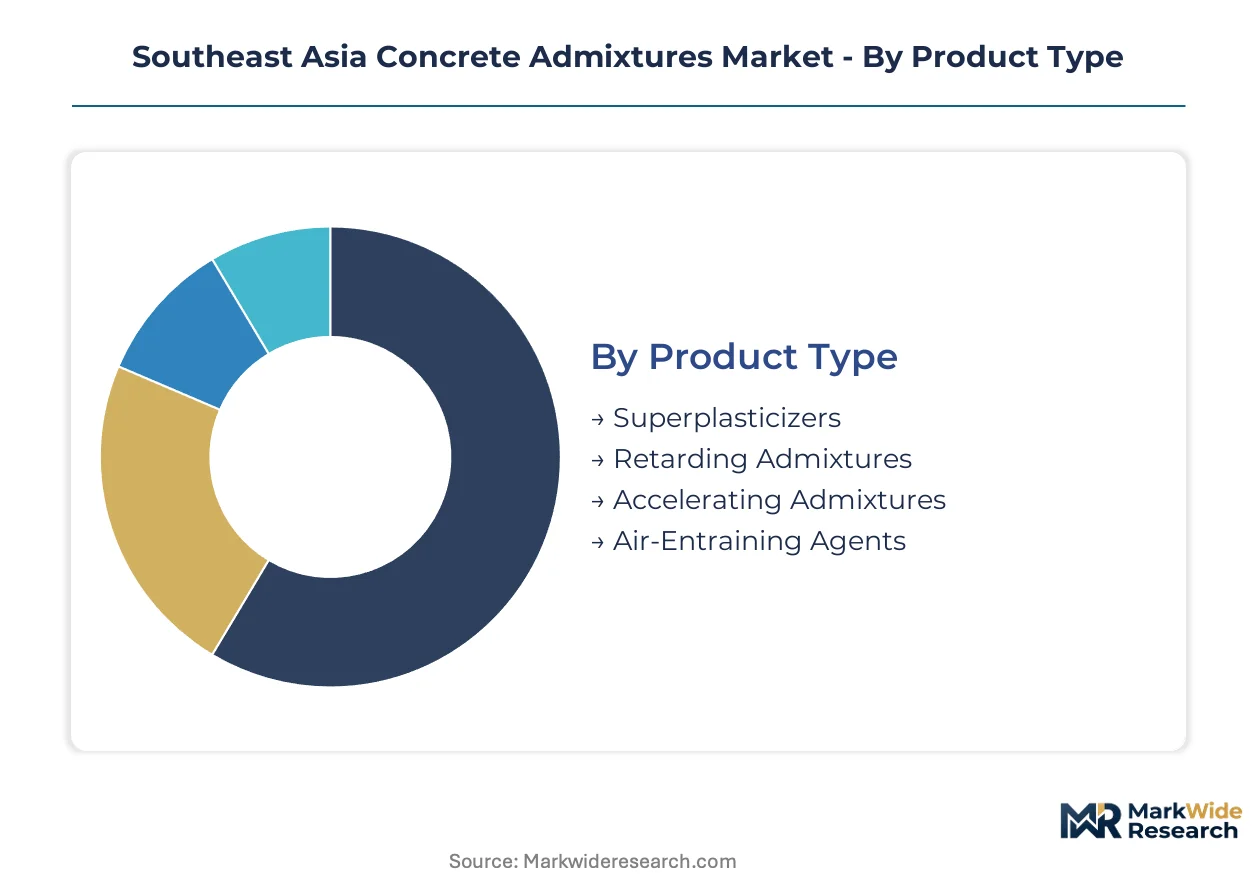
Segmentation in the Southeast Asia concrete admixtures market reveals distinct technical service requirements across product chemistries and end-use applications. Procurement patterns diverge sharply between infrastructure megaprojects demanding embedded formulation support and residential channels accepting commodity distribution.
Product Type:
After-sales service intensity varies dramatically across admixture chemistries, with superplasticizer deployments requiring continuous batch optimization support while air-entraining agents function through standardized dosing protocols.
- Superplasticizers:Polycarboxylate ether formulations achieve 25-40% water reduction through comb polymer architectures with polyethylene glycol side chains. Demand concentrates in Jakarta's elevated transit corridors and Bangkok's high-rise foundations, where self-consolidating concrete specifications mandate viscosity retention beyond 90 minutes in tropical heat.
- Retarding Admixtures:Sucrose-based and hydroxycarboxylic acid formulations delay cement hydration to manage slump loss during extended transport. Procurement clusters with ready-mix networks in Vietnam's Binh Duong province, where batching plants serving multiple project sites require set-time flexibility across varying pour schedules.
- Accelerating Admixtures:Alkali-free calcium nitrate and lithium silicate formulations enable early form stripping in Indonesia's rapid-cycle high-rise construction.
- Air-Entraining Agents:Vinsol resin and synthetic surfactant chemistries stabilize freeze-thaw resistance for infrastructure in the Philippines' elevated terrain.
Superplasticizers hold the largest share; momentum sits with accelerating admixtures as Indonesia's SNI durability mandates compress construction schedules.
Application:
Application segmentation tracks margin stratification across performance tiers, with high-performance concrete commanding formulation premiums while residential construction operates on volume-driven commodity economics.
- High-Performance Concrete:Grade 50+ mixes incorporating silica fume and metakaolin require multi-component admixture systems for rheology control. Specification dominance in Singapore's Marina Bay financial district and Jakarta's MRT tunnel linings drives technical service bundling as the primary supplier selection criterion.
- Ready-Mix Concrete:Centralized batching plant networks in Ho Chi Minh City and Jakarta displace site-mixed alternatives through quality consistency and logistics efficiency. Annual contract consolidation across project portfolios shifts procurement authority to plant technical managers.
- Precast Concrete:Factory-controlled curing environments favor early-strength accelerators and controlled retarders for just-in-time mold cycling.
- Residential Construction:Low-rise housing developments in Thailand's secondary cities accept naphthalene sulfonate superplasticizers despite PCE performance advantages.
Ready-mix concrete holds the largest share; momentum is climbing fastest with high-performance concrete as foundation depths increase across Southeast Asian megaprojects.
End User:
End-user segmentation reflects procurement sophistication gradients, with civil engineering firms maintaining captive laboratory capabilities while specialty contractors rely on supplier technical delegation.
- Civil Engineering Firms:State-owned contractors on Indonesia's Trans-Java toll road and Vietnam's North-South Expressway maintain in-house concrete technology departments. These organizations specify performance-based contracts requiring admixture suppliers to guarantee 28-day strength achievement rather than chemical dosage compliance.
- Infrastructure Developers:Private concession holders for Manila's Skyway and Bangkok's Orange Line embed admixture suppliers within design-build consortia. Technical risk transfer to chemical partners accelerates specification of hybrid PCE-silica fume nanocomposites.
- Construction Companies:General contractors on commercial high-rises in Kuala Lumpur and Singapore prioritize logistics reliability over formulation innovation.
- Specialty Contractors:Tunneling and marine specialists in the Philippines source lithium-based ASR mitigators for volcanic aggregate compatibility.
Civil engineering firms hold the largest share; momentum sits with infrastructure developers as public-private partnership procurement expands across ASEAN.
Sales Channel:
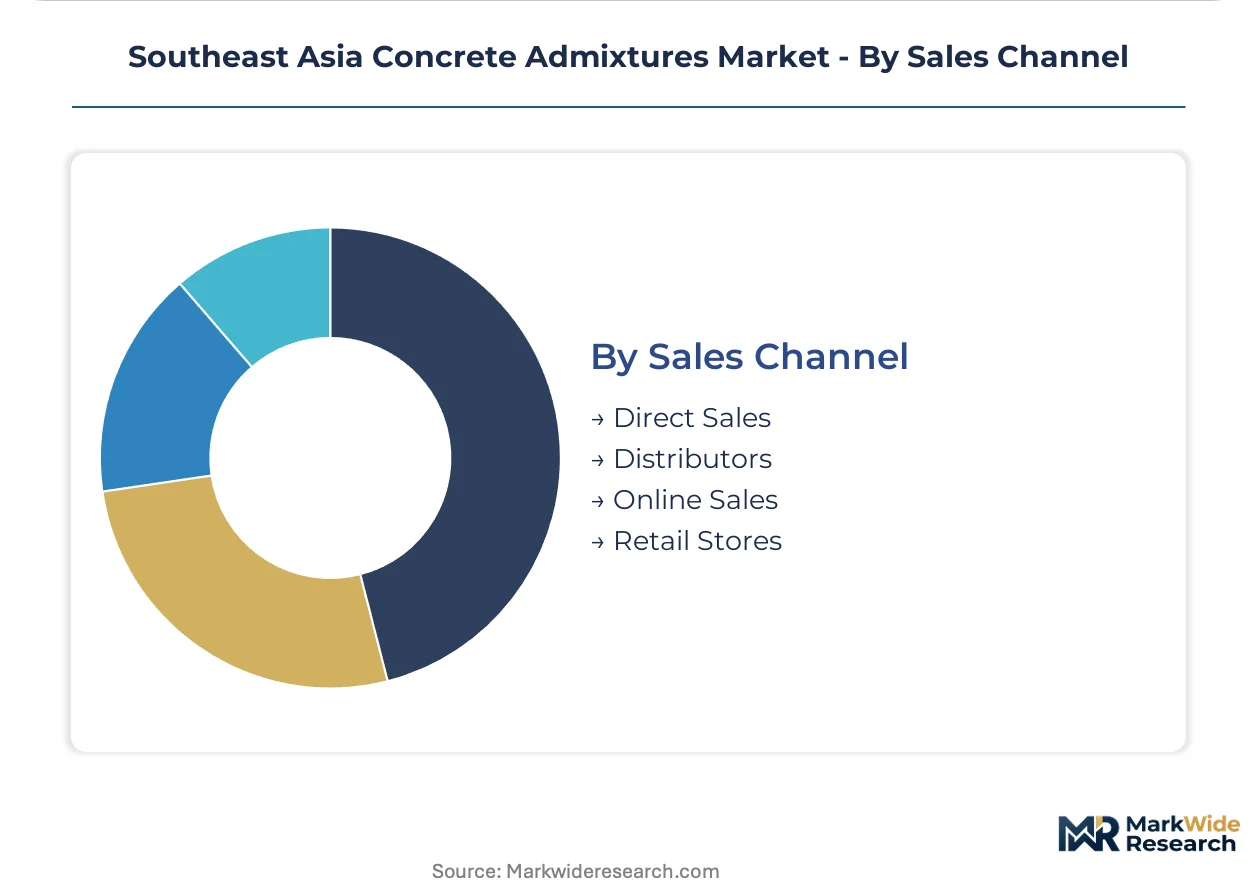
Sales channel segmentation tracks supply chain control requirements, with direct relationships dominating performance-critical applications while distributors serve fragmented geographic markets.
- Direct Sales:Supplier technical staff embedded with batching plant quality control teams enable real-time dosage adjustment. This channel captures Indonesia's SNI-mandated infrastructure projects where formulation liability rests with admixture manufacturers.
- Distributors:Regional chemical distributors in Thailand's upcountry provinces and Vietnam's Da Nang corridor stock commodity retarders and accelerators for small-batch ready-mix operations.
- Online Sales:Digital procurement platforms serve research laboratories and university concrete testing facilities requiring specialty admixture samples.
- Retail Stores:Construction material retailers in Philippine provincial capitals package consumer-grade waterproofing admixtures for residential repair markets.
Direct sales holds the largest share; momentum is expanding most quickly with distributors as independent batching plant networks proliferate in secondary Vietnamese and Indonesian cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thai admixture exporters supply Vietnam's industrial corridor while Indonesian SNI-certified producers capture domestic infrastructure tenders. Cross-border technical service partnerships now determine supplier selection more than freight costs.
Indonesia
Jakarta's MRT Phase 2 and Trans-Java toll road extensions consume corrosion-inhibiting admixtures for chloride-exposed tunnel linings. BSN administers SNI 7656 durability certification requiring 14-18 month laboratory validation timelines for foreign formulations. Surabaya's emerging batching plant cluster imports PCE superplasticizers through Singapore transshipment hubs.
Vietnam
Ho Chi Minh City-Binh Duong industrial corridor drives ready-mix concrete expansion with 60-story foundation specifications. Ministry of Construction technical regulations mandate performance testing for imported admixtures at Hanoi-based laboratories. Da Nang's secondary city batching networks seek technical service partnerships absent from commodity distributors.
Thailand
Bangkok's high-rise residential towers exceeding 60 stories require self-consolidating concrete with viscosity-modifying admixtures. TISI revised TIS 280-2563 to mandate accelerated carbonation testing declarations. Samut Prakan province hosts captive testing facilities established by specialty accelerator suppliers circumventing Bangkok validation delays.
Philippines
Manila's Skyway Stage 3 and Cebu-Cordova bridge embed admixture suppliers within design-build consortia. DPWH infrastructure standards specify lithium-based ASR mitigators for volcanic aggregate compatibility. Tunneling specialists in Baguio source alkali-free accelerators for rapid-cycle form stripping in elevated terrain.
Singapore
Marina Bay financial district specifications drive technical service bundling for grade 50+ high-performance concrete. BCA green mark incentives reward CO2-cured concrete technologies with embodied carbon thresholds. Jurong Island chemical parks anchor regional PCE polymer feedstock distribution.
Southeast Asia Concrete Admixtures Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement authority at batching plant networks. The market structures around three tiers: Swiss-German chemical conglomerates with captive R&D pipelines, regional construction-material integrators with backward cement-admixture linkages, and specialty chemical houses focused on tropical-climate formulations. Consolidation pressures intensify as annual contract consolidation shifts bargaining power to ready-mix technical managers. Strategic moves center on laboratory accreditation pre-positioning and embedded technical service staffing.
Within the premium-formulation tier, Sika AG and BASF SE occupy positions anchored by European R&D heritage and regional production footprints. MBCC Group exemplifies the specialty-chemical archetype with climate-specific accelerator portfolios. Fosroc Inc. represents the technical-service-embedded model through infrastructure developer partnerships. These three patterns—conglomerate scale, formulation specialization, and service integration—define competitive positioning across Indonesian SNI-mandated projects and Vietnamese ready-mix consolidation.
| Leading Market Players |
|---|
| Sika AG |
| BASF SE |
| Fosroc Inc. |
| MAPEI SpA |
| GCP Applied Technologies Inc. |
| CEMEX SAB de CV |
| MBCC Group |
| Saint-Gobain |
| RPM International Inc. |
| Others |
Value Network & Pricing Analysis
Singapore-Jurong transshipment corridors feed PCE polymer feedstock into Indonesian batching plants at freight premiums that widen the gap between SNI-certified premium formulations and commodity naphthalene alternatives. This logistics architecture concentrates pricing power with incumbents holding captive laboratory accreditation, while downstream buyers face tiered cost structures tied to certification status rather than chemistry alone.
Pricing Analysis
Polycarboxylate ether superplasticizers command 40-60% premiums over legacy naphthalene sulfonate bases, with hybrid PCE-silica fume nanocomposites occupying an emerging ultra-premium tier. Pricing stratifies across SNI-certified premium formulations, TISI-validated standard grades, and uncertified economy imports from Chinese legacy producers. Cost compression in the economy tier is intensifying because naphthalene oversupply from Chinese exporters erodes price floors in Vietnam and Thailand. Civil engineering firms on Indonesia's Trans-Java toll road demonstrate the least price sensitivity due to performance-based contracting, while independent batching plants in Vietnam's secondary cities exhibit acute sensitivity to unit chemistry costs.
Supply Chain Analysis
Tariff exposure between China and ASEAN member states dominates supply chain risk planning for ethylene oxide derivative feedstocks. PCE polymer production draws from petrochemical complexes in Singapore, South Korea, and Thailand, with ethylene oxide and methoxy polyethylene glycol anchoring formulation economics. Single-source vulnerability concentrates in Singapore's Jurong Island chemical parks, where regional PCE feedstock distribution hinges on refinery output stability. Distribution runs through direct technical service teams for SNI-mandated infrastructure projects, while regional chemical distributors serve fragmented ready-mix networks in Thailand's upcountry provinces and Vietnam's Da Nang corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Southeast Asia's admixture market creates niche capture opportunities as ready-mix channel consolidation displaces project-by-project procurement with annual contract bundling. This demand-side shift fragments specification authority between plant technical managers and centralized procurement teams, opening service-model differentiation gaps.
For Market Incumbents: Entrench laboratory accreditation advantages by pre-positioning SNI validation capacity ahead of Indonesia's infrastructure tender waves. Establish captive testing facilities in Samut Prakan and Surabaya to circumvent 14-18 month foreign certification timelines that threaten market access. Deepen backward integration into ethylene oxide feedstock through Singapore-Jurong supply partnerships, insulating margin pressure from petrochemical volatility.
For New Entrants and Emerging Players: Pursue technical service partnerships with independent batching plants in Vietnam's Binh Duong province and Indonesia's secondary cities, where commodity distributors lack embedded formulation support. Target Myanmar's Yangon-Mandalay corridor for import substitution plays, leveraging post-conflict cement demand and absent local blending capacity. Lead with alkali-free accelerator specialization for tropical humidity conditions, mirroring MBCC Group's climate-specific positioning.
For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical conglomerates divesting non-core construction chemical divisions amid portfolio rebalancing toward specialty materials. Long-term viability hinges on technical service bundling capabilities rather than commodity chemistry scale, favoring targets with embedded batching plant relationships over pure manufacturing assets. Monitor Indonesia's BSN accreditation queue depth as an inflection signal—backlogs exceeding 18 months indicate regulatory moat widening that rewards pre-certified incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| SNI Laboratory Pre-Positioning | Captive Jakarta and Surabaya testing facilities circumvent 18-month foreign certification delays. |
| Backward Integration into Feedstock | Singapore-Jurong ethylene oxide partnerships insulate PCE polymer margins from ASEAN refinery volatility. |
| Technical Service Embedding | Plant-level quality control teams capture ready-mix contract consolidation in Ho Chi Minh City. |
| Climate-Specialized Formulation Development | Alkali-free accelerators for tropical humidity replicate MBCC Group's differentiated positioning. |
| Myanmar Distribution Partnership | Yangon-Mandalay corridor access exploits post-conflict cement demand and absent local blending. |
Research Methodology
A standing panel of admixture formulation chemists, ready-mix plant technical managers, civil engineering procurement directors, and BSN/TISI laboratory accreditation officers provided ongoing calibration across the research cycle. Primary interviews with batching plant operators in Jakarta, Ho Chi Minh City, and Bangkok combined with secondary validation from Indonesian SNI documentation, Thai Industrial Standards Institute regulatory filings, Vietnam Ministry of Construction technical bulletins, and ASEAN customs trade data. Bottom-up volume builds from project-level admixture specification tracking triangulated against top-down chemical industry production estimates.
Scenario-bracketing framed demand trajectories across conservative, baseline, and accelerated infrastructure investment cases without fixed-year anchors. Segmentation dimensions spanned product chemistry tier, application performance grade, end-user procurement sophistication, and sales channel control structure. CAGRs derived from slope-intercept modeling of historical specification adoption curves, with ethylene oxide feedstock cost indices and SNI certification timeline data serving as industry-specific forecast inputs.
Sensitivities concentrate around Indonesia's BSN accreditation processing speeds, Chinese naphthalene sulfonate export pricing volatility, and ASEAN refinery output fluctuations affecting ethylene oxide availability. Forecasts reflect documented assumptions on infrastructure tender award timing and green building code adoption trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Foam Concrete Market
Building Materials
East Africa Wall Putty Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Global FRP Rebar Market
Building Materials
UK Aluminum Door and Window Market
Building Materials
Pozzolana Cement Market
Building Materials
Aluminum Door and Window Market
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Latin America Facade Market
Building Materials
Global Pozzolan Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Timber Frames Market
Building Materials
Blind Bolts Market
Building Materials
Construction Repair Composites Market