
 Foam Concrete Market | 2026-2036
Foam Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Concrete Market Analysis
European precast producers is hardening supply discipline after energy cost shocks reshaped cement economics. Heidelberg Materials AG anchors its foam concrete portfolio through captive limestone reserves and clinker substitution programs. BASF SE differentiates via polymer-modified foaming agents that stabilize air void distribution across variable ambient temperatures. Sika AG competes on admixture integration, bundling superplasticizers with its foam generator systems to cut water demand.
Foam concrete is a cementitious slurry with uniformly distributed air voids created through mechanical foaming or chemical reaction, typically achieving dry densities between 300 and 1600 kg per cubic meter for structural and non-structural applications. Its engineered porosity delivers thermal insulation, fire resistance, and reduced dead loads in floor slabs, roof decks, and trench backfill. Pre-mixed formulations command margin premiums in commercial construction where batch consistency governs specification compliance, while pumpable grades are gaining share in infrastructure void filling where site access limits traditional placement. Aerated variants retain dominance in residential buildings across Northern Europe where fabricators prize dimensional stability for prefabricated wall panels.
REACH compliance in Europe governs foaming agent chemistry and restricts residual surfactant migration, pushing reformulation toward bio-based stabilizers. China's GB standards for green building materials enforce thermal conductivity ceilings that favor lower-density foam concrete in envelope applications. India's BIS certification for cellular concrete products mandates compressive strength testing protocols that filter out informal producers. Stakeholders must monitor how building energy codes in Indonesia, Vietnam, and the Philippines converge on insulation performance thresholds that foam concrete can satisfy at lower installed cost than extruded polystyrene systems.
Market Dynamics
European cement producers are hardening supply discipline after energy cost shocks reshaped clinker economics, forcing specification engineers toward lower-density formulations that cut transport and placement costs.
Growth Catalysts
- GB Standards Tightening:China's green building material thresholds enforce thermal conductivity ceilings that favor foam concrete in envelope applications over traditional insulation systems.
- Urban Vertical Construction:Indonesia's Jakarta-Bandung corridor concentrates demand as developers specify foam concrete for lightweight floor slabs in high-rise residential towers.
- Mechanical Foaming Advancement:Pre-mixed formulations with stabilized air void distribution now command specification preference in commercial projects where batch consistency governs compliance.
Market Restraints
- Clinker Cost Volatility:Energy price exposure in European cement kilns transmits directly to foam concrete margin compression, limiting producer pricing flexibility.
- REACH Compliance Friction:Residual surfactant restrictions under ECHA rules force foaming agent reformulation toward bio-based stabilizers with unproven long-term performance records.
- Extruded Polystyrene Substitution:XPS systems retain installed cost advantages in Southeast Asian markets where thermal code enforcement remains inconsistent.
Strategic Opportunities
- Vietnam Infrastructure Void Filling:Pumpable foam concrete grades gain share in highway embankment and utility trench applications where site access limits traditional placement methods.
- Polymer-Modified Foaming Convergence:Synthetic stabilizer chemistry combined with ambient-temperature curing protocols opens specification in climates previously hostile to air-void retention.
- BIS Certification Filtering:India's compressive strength testing mandates for cellular concrete products create formal market entry barriers that advantage organized producers over informal competitors.
Industry Challenges
- Batch Consistency Control:Site-mixed foam concrete suffers density variation that triggers rejection by commercial specifiers demanding pre-mixed supply chain guarantees.
- Skilled Technician Scarcity:Foam generator operation and air-void monitoring require trained personnel unavailable in remote construction markets, constraining geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Concrete Market |
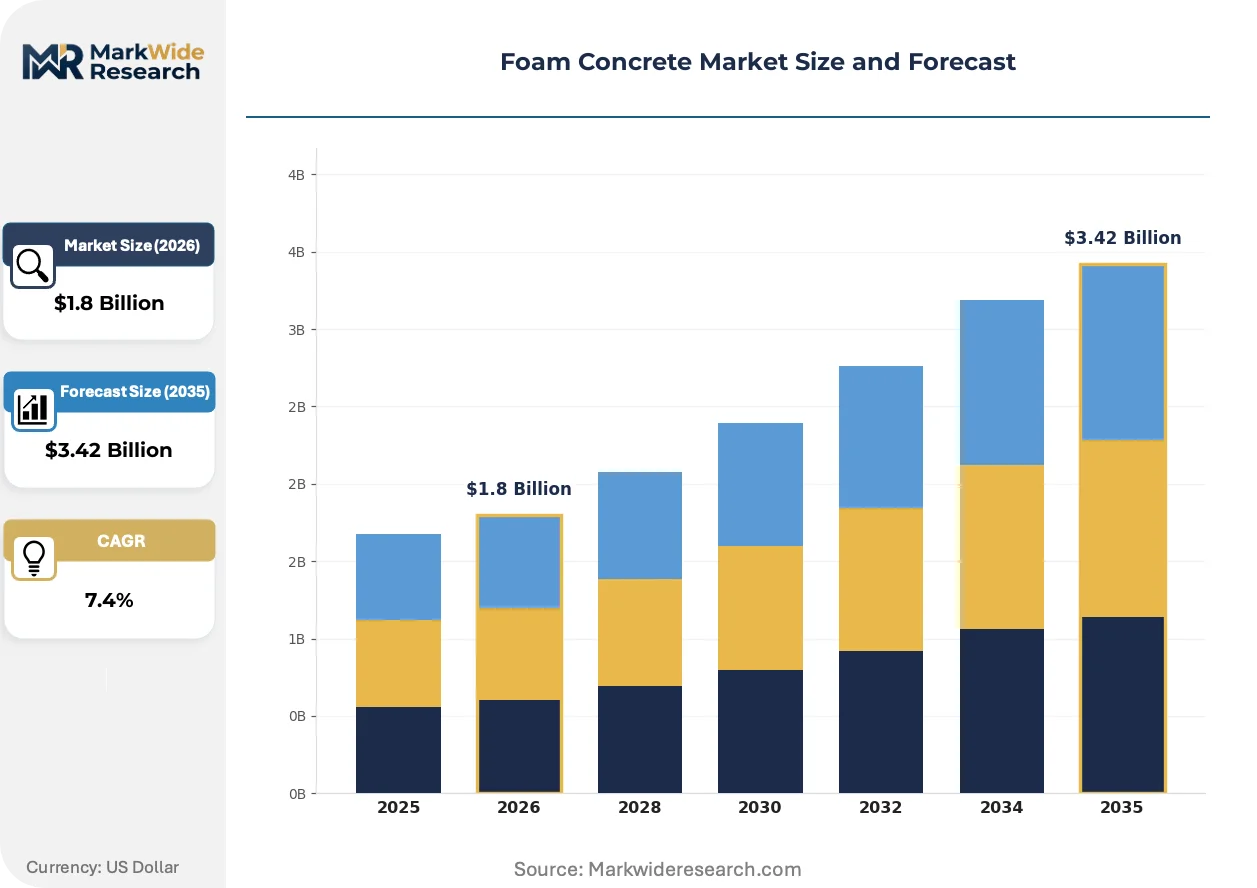
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.42 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Mixed, Aerated, Lightweight, Pumpable End User: Residential Buildings, Commercial Construction, Infrastructure, Repair Works Application: Insulation, Void Filling, Soil Stabilization, Sound Proofing Packaging Type: Bags, Totes, Bulk, Containers |
| Companies Covered | CEMEX S.A.B. de C.V., Heidelberg Materials AG, BASF SE, Boral Limited, ACC Limited, Saint-Gobain SA, Sika AG, Xella Group, Holcim Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Concrete Market Emerging Trajectories
Specification engineers are rotating toward material systems that compress installation timelines while satisfying tightening thermal performance codes across tropical and temperate climate zones.
Alkali-activated binders are expanding into foam concrete formulations as clinker substitution intensifies under carbon accounting pressure. Infrastructure contractors in Northern Europe specify these systems for non-structural void filling where strength requirements permit. The technology is expanding into commercial precast markets previously reserved for Portland cement blends.
REACH restrictions on residual surfactants are forcing foaming agent chemistry toward bio-based stabilizers derived from agricultural waste streams. ECHA compliance timelines compress reformulation windows for European producers. German and French precast fabricators now require supplier certification of surfactant biodegradability prior to contract award.
Performance-based specification is displacing prescriptive density grades in commercial envelope applications. Building energy modelers in the Philippines and Vietnam now procure foam concrete by thermal conductivity targets rather than kg per cubic meter ratings. This behavior shift compresses supplier qualification cycles and rewards producers with in-house thermal testing capability.
Foam Concrete Market Segmentation
Foam concrete specification varies sharply by placement method, thermal performance targets, and site logistics. Buyers select formulations based on density requirements, curing conditions, and whether batch consistency or pumpability governs project economics.
Product Type:
Cost tier separates specification-grade pre-mixed supply from site-blended alternatives where labor arbitrage dominates.
- Pre-Mixed:Factory-controlled air-void distribution achieves batch-to-batch density tolerances within 5%. Commercial envelope projects in Germany and France mandate pre-mixed supply chain certification under ECHA surfactant traceability rules.
- Pumpable:Extended flow retention enables continuous placement through 500-meter pipeline runs. Vietnam's highway embankment contractors specify pumpable grades where equipment access limits traditional methods.
- Aerated:Autoclaved variants deliver dimensional stability for prefabricated wall panels. Northern European fabricators prize aerated concrete for residential modular construction.
- Lightweight:Density-optimized formulations reduce structural dead loads in high-rise floor slabs. Jakarta-Bandung corridor developers specify lightweight grades for vertical residential towers.
Pre-mixed leads volumes today; pumpable is gaining share fastest.
End User:
Application maturity and code enforcement stringency shape procurement patterns across customer types.
- Commercial Construction:Performance-based thermal conductivity specifications now dominate envelope procurement. Philippine building energy modelers procure by U-value targets rather than density grades, compressing supplier qualification cycles.
- Infrastructure:Void filling and trench backfill applications prioritize placement speed over strength. Northern European contractors specify alkali-activated binders for non-structural void filling where carbon accounting pressures intensify.
- Residential Buildings:Fabricators in Indonesia and Vietnam specify foam concrete for lightweight floor slabs in high-rise towers. Thermal code convergence across Southeast Asia favors foam concrete over extruded polystyrene where enforcement tightens.
- Repair Works:Low-strength, high-flow formulations enable injection into confined structural voids. Applications concentrate in aging European building stock requiring thermal retrofit.
Commercial construction leads volumes today; infrastructure is climbing the fastest.
Application:
Functional performance requirements determine density specifications and binder chemistry selection.
- Insulation:Thermal conductivity ceilings in China's GB standards enforce low-density formulations for building envelopes. Lower-density grades under 600 kg per cubic meter satisfy green building material thresholds.
- Void Filling:Pumpable grades with extended flow retention enable continuous placement in utility trenches and highway embankments. Site access limitations in Vietnam's infrastructure corridor drive specification preference.
- Soil Stabilization:Cementitious slurry injection improves bearing capacity in soft ground conditions. Applications concentrate in urban expansion zones with challenging geotechnical profiles.
- Sound Proofing:Engineered porosity absorbs airborne and impact noise transmission. German and French precast fabricators integrate acoustic layers into modular wall systems.
Insulation leads volumes today; void filling is expanding most quickly.
Packaging Type:
Volume scale and site logistics determine whether bulk delivery or unitized packaging optimizes total cost.
- Bulk:Tanker delivery minimizes packaging cost for large continuous pours. Major infrastructure projects in Indonesia and Vietnam specify bulk supply for highway and utility applications.
- Bags:Unitized packaging enables precise batch control on remote sites with limited storage. Distributed residential construction across Southeast Asia relies on bagged supply.
- Totes:Intermediate bulk containers balance mobility with volume efficiency. Mid-scale commercial projects specify totes where site access permits mechanical handling.
- Containers:Modular shipping enables intermodal logistics for island and remote markets. Philippine and Indonesian archipelago construction depends on containerized supply chains.
Bulk leads volumes today; totes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's construction material demand dwarfs Germany's precast output by an order of magnitude, yet both markets are tightening thermal performance codes that favor foam concrete substitution in building envelopes.
China
GB standards for green building materials enforce thermal conductivity ceilings below 0.10 W/m·K for envelope applications, favoring low-density foam concrete over traditional insulation. MIIT's dual carbon goals accelerate clinker substitution programs in state-backed construction projects. The Yangtze River Delta concentrates prefabrication capacity where foam concrete panel production scales for residential high-rises.
Germany
REACH compliance under ECHA rules restricts residual surfactant migration, forcing foaming agent reformulation toward bio-based stabilizers. The country's national building energy regulator enforces stringent U-value targets for commercial envelopes. Bavaria's precast fabricators in the Munich-Stuttgart corridor specify certified foam concrete supply chains under ECHA traceability protocols.
Indonesia
Jakarta-Bandung corridor developers specify lightweight foam concrete for floor slabs in vertical residential towers where dead load reduction governs structural economics. The national building code convergence on insulation performance thresholds favors foam concrete over XPS where enforcement tightens. Surabaya's infrastructure contractors trial pumpable grades for highway embankment void filling.
Vietnam
Highway and utility trench applications drive pumpable foam concrete specification where site access limits traditional placement methods. The country's national construction ministry is drafting thermal performance standards for commercial buildings that align with ASEAN green building protocols. Ho Chi Minh City's urban rail expansion specifies foam concrete for soil stabilization in soft ground conditions.
India
BIS certification for cellular concrete products mandates compressive strength testing protocols that filter informal producers from formal supply chains. The national green building council's rating system awards credits for low-density envelope materials. Maharashtra's Mumbai-Pune industrial corridor concentrates precast capacity where organized producers gain specification preference.
Foam Concrete Market Vendor Landscape
European producers anchor the premium specification tier; Southeast Asian specialists hold the cost-optimized volume segment. The market structures around three tiers: multinational cement conglomerates with captive raw material reserves, regional precast fabricators with formulation expertise, and equipment-technology licensors supplying foaming systems. Consolidation pressure intensifies as energy cost volatility compresses margins. Two dominant competitive moves define positioning: backward integration into limestone reserves and clinker substitution programs, and technology licensing partnerships that transfer foaming agent chemistry to regional licensees.
Among European-based conglomerates, Heidelberg Materials AG and Holcim Group exemplify the integrated-reserve archetype, controlling upstream limestone supply and downstream precast distribution. Sika AG occupies a position within the specialty chemicals tier, bundling admixtures with foam generator systems. These three anchors represent distinct competitive vectors: raw material security, formulation integration, and equipment-chemical bundling.
| Leading Market Players |
|---|
| CEMEX S.A.B. de C.V. |
| Heidelberg Materials AG |
| BASF SE |
| Boral Limited |
| ACC Limited |
| Saint-Gobain SA |
| Sika AG |
| Xella Group |
| Holcim Group |
| Others |
Supply Flow & Price Mechanics
Mechanical foaming advancement toward pre-mixed formulations simultaneously compresses batch-to-batch density variation costs and concentrates specification-grade supply among certified European producers. China's GB standards enforcement and REACH compliance timelines in Germany are bifurcating the market into premium certified tiers and cost-optimized site-blended alternatives.
Pricing Analysis
Capacity additions in Indonesia and Vietnam are reshaping price floors for pumpable grades in Southeast Asian infrastructure corridors. Three-tier pricing structure across ECHA-certified pre-mixed, BIS-compliant standard, and informal economy site-blended levels separates procurement tiers. Cost compression in European kiln operations is intensifying because energy price exposure transmits directly to clinker-based formulations. Infrastructure contractors in Vietnam exhibit highest price sensitivity; commercial envelope specifiers in Germany demonstrate lowest sensitivity due to compliance mandates.
Supply Chain Analysis
Domestic-content mandates in India's Mumbai-Pune corridor and Indonesia's Jakarta-Bandung zone are reshaping sourcing toward local precast fabricators. Manufacturing gravity centers on China, Germany, and Indonesia for specification-grade supply. Raw material dependencies rest on Portland cement clinker, synthetic foaming agents, and bio-based surfactant stabilizers. Single-source vulnerability concentrates in European synthetic stabilizer chemistry under REACH transition timelines. Distribution runs through bulk tanker networks for infrastructure scale and bagged unit packaging for remote residential sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in polymer-modified foaming agent chemistry and alkali-activated binder substitution as carbon accounting pressure reshapes specification premiums.
For Market Incumbents: Hedge clinker cost volatility through captive limestone reserve control in the Yangtze River Delta and Bavaria's Munich-Stuttgart corridor. Deepen formulation integration by bundling superplasticizer admixtures with foam generator systems to defend against specialty chemical competitors. Prioritize ECHA surfactant traceability certification ahead of compliance deadlines to lock out reformulation-lagged rivals. For New Entrants and Emerging Players: Alkali-activated binder technology for non-structural void filling offers entry into Northern European infrastructure procurement previously reserved for Portland cement incumbents. Target Vietnam's highway embankment corridor where pumpable grade demand outruns certified supply. Pursue equipment-technology licensing partnerships that transfer foaming agent chemistry to regional licensees without capital-intensive kiln investment. For Investors and Strategic Acquirers: Roll-up economics work for regional precast fabricators with formulation expertise because BIS certification and ECHA traceability mandates are filtering informal competitors from formal supply chains. Acquisition focus centers on mid-scale Indonesian and Vietnamese producers with existing MIIT or national green building council alignment. Monitor GB standards enforcement consistency across China's provincial construction bureaus as inflection indicator for premium-tier volume shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Reserves | Heidelberg Materials AG anchors cost position through captive raw material security in European kiln networks. |
| Polymer-Modified Foaming Agent Development | BASF SE stabilizes air void distribution across variable ambient temperatures in tropical Southeast Asian climates. |
| Alkali-Activated Binder Scale-Up | Carbon accounting pressure in Northern Europe opens specification for clinker-substituted formulations in void filling. |
| ECHA Traceability Certification Investment | German and French precast fabricators now mandate supplier biodegradability certification prior to contract award. |
| Equipment-Technology Licensing Partnerships | Sika AG bundles foam generator systems with admixture integration to cut water demand in commercial projects. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with precast fabricators, cement plant managers, specification engineers at commercial developers, and procurement leads at infrastructure contractors combined with secondary validation. Secondary sources encompassed MIIT dual carbon policy filings, ECHA REACH substance registrations, BIS cellular concrete certification records, and ASEAN green building protocol drafts. Cross-referencing customs trade data for foaming agent imports against provincial construction bureau project approvals enabled demand triangulation.
Input-output matrices mapped density-grade production capacity against thermal conductivity specification requirements across commercial envelope, infrastructure void filling, and residential floor slab applications. Segmentation dimensions encompassed product type tier, end-use vertical, application function, and packaging logistics format. CAGRs were derived from elasticity-adjusted demand curves incorporating clinker substitution rates and building energy code enforcement trajectories. Forecast inputs included GB standards tightening timelines and Jakarta-Bandung corridor high-rise construction permits.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH surfactant reformulation performance validation and bio-based stabilizer long-term durability records. Forecasts reflect documented assumptions regarding thermal code enforcement consistency across Southeast Asian markets. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Natural Stone Market
Building Materials
North America Cement Market
Building Materials
Europe Fiber Cement Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Granite Market
Building Materials
Timber Frames Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
Italy Facade Market
Building Materials
Latin America Facade Market
Building Materials
Cementitious Waterproofing Market
Building Materials
Italy Architectural Coatings Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Glass Facade Market