
 Mining Hoses Market | 2026-2036
Mining Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Hoses Market Outlook
Underground slurry transport is rebalancing the Mining Hoses Market as open-pit operators deepen pits and face higher dewatering volumes. Trelleborg Group anchors its position through advanced polymer compounding capabilities for abrasive media. Continental AG competes on manufacturing scale across large-diameter reinforced constructions. Parker Hannifin Corp specializes in integrated hose-and-coupling systems for high-pressure mine water networks.
Mining hoses are reinforced flexible conduits manufactured from synthetic rubber compounds, thermoplastic layers, or steel-wire braiding, engineered to withstand internal pressures exceeding 40 bar and external abrasion from ore slurries, tailings, and process chemicals. Their primary industrial purpose is to convey abrasive fluids, compressed air, and hydraulic power across fixed and mobile mining infrastructure. Rubber hoses dominate installed base volume due to resilience in slurry transport, while composite hoses capture expanding share in chemical leaching circuits where corrosion resistance commands premium positioning. Large-diameter segments concentrate margin pools in custom-engineered orders for mine dewatering, whereas small-diameter standardized lines face price compression from contractor procurement consolidation.
ISO 6807 sets global benchmark specifications for rubber hoses in rotary drilling and slurry service, while MSHA in the United States mandates flame-resistance certification for underground deployment, directly shaping product development roadmaps and testing expenditures. Australia's state-based mining safety regulators enforce additional pressure-testing protocols that extend qualification timelines for new suppliers. Stakeholders must monitor how China's evolving GB standards for hydraulic hose construction interact with REACH-mandated restrictions on aromatic process oils, as compliance divergence threatens to fragment supply chain configurations across major producing regions.
Market Dynamics
Declining ore grades across major copper and iron ore belts are forcing operators to pump higher slurry volumes over longer distances, intensifying demand for abrasion-resistant hose assemblies with extended service intervals.
Growth Catalysts
- REACH-mandated material specifications:The EU's restrictions on aromatic process oils are accelerating reformulation of rubber compounds toward bio-based plasticizers, opening premium positioning for compliant suppliers.
- Underground dewatering intensity:Pit deepening in Chile's Atacama operations is expanding procurement of high-pressure mine water networks rated above 40 bar.
- Polymer compounding advances:Advanced elastomer blends with ceramic particle reinforcement are extending mean time between replacement in Pilbara iron ore slurry lines.
Market Restraints
- Synthetic rubber feedstock volatility:Butadiene and styrene price swings compress margin predictability for compounders serving contract-heavy mining procurement.
- Supplier concentration in textile reinforcement:High-tenacity aramid yarn production clusters in limited manufacturing bases, creating single-source vulnerability for large-diameter hose constructors.
- Steel-wire braiding substitution ceiling:Composite thermoplastic constructions face pressure rating limitations above 60 bar in deep-shaft hydraulic service.
Strategic Opportunities
- Leaching circuit chemical resistance:Sulfuric acid and cyanide recovery operations in Nevada gold districts are creating demand for fluoropolymer-lined hose architectures.
- Integrated hose-and-coupling systems:Modular quick-connect assemblies are displacing field-fabricated joints in Australian contractor fleets, reducing installation labor.
- China's evolving GB standards:Tighter hydraulic hose construction rules are forcing import substitution, creating opening for domestic compounders with certified test facilities.
Industry Challenges
- MSHA flame-resistance certification timelines:Underground deployment approvals require extended burn-testing protocols that delay new product introductions by 8-14 months.
- ISO 6807 testing facility scarcity:Limited third-party laboratories capable of rotary drilling slurry simulation create bottlenecks for qualification of novel reinforcement geometries.
- Legacy coupling interchange standards:Proprietary thread forms from incumbent suppliers lock contractor fleets into single-source maintenance patterns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Hoses Market |
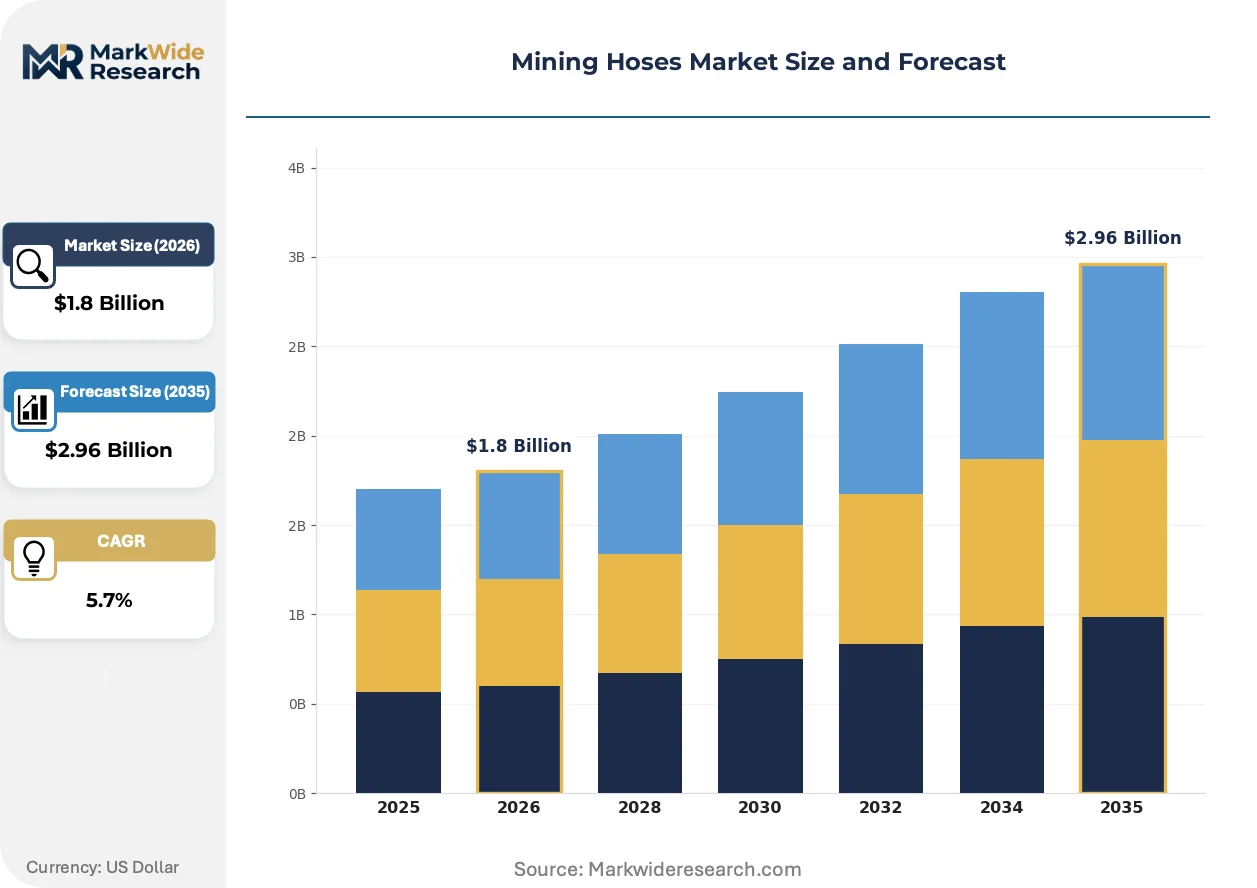
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Hoses, PVC Hoses, Composite Hoses, Steel Hoses Application: Slurry Transport, Water Supply, Dust Suppression, Ventilation End User: Mining Companies, Contractors, Equipment Manufacturers, Service Providers Diameter: Small Diameter, Medium Diameter, Large Diameter, Custom Diameter |
| Companies Covered | Trelleborg Group, Continental AG, Parker Hannifin Corp, Gates Corporation, Eaton, Weir Group PLC, Metso, Danfoss, Semperit AG Holding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Hoses Market Strategic Shifts
Material science convergence with digital monitoring capabilities is redefining hose lifecycle economics, shifting buyer value calculations from upfront unit cost to total cost of ownership metrics.
Thermoplastic elastomer composites with embedded fiber-optic strain sensors are modularizing condition monitoring into slurry transport infrastructure. Underground contractors in South African platinum operations are piloting these assemblies for real-time wear detection. This architecture is modularizing predictive maintenance workflows, compressing emergency replacement incidents and reconfiguring spare parts inventory strategies.
Australia's state-based mining safety regulators are extending pressure-testing protocols beyond ISO 6807 baselines to include dynamic impulse verification. This mandates additional qualification expenditures for suppliers seeking entry into Queensland and Western Australia procurement frameworks. Large-diameter dewatering segments face the steepest compliance burden, favoring established compounders with captive test facilities.
Contractor procurement consolidation across Chilean copper operations is compressing supplier rosters and unbundling aftermarket service from hardware supply. Major mining services firms are centralizing hose assembly fabrication in captive workshops, displacing distributed field-splicing practices. This concentration is most visible in the Antofagasta region, where integrated maintenance contracts now specify supplier-managed inventory programs.
Mining Hoses Market Segmentation
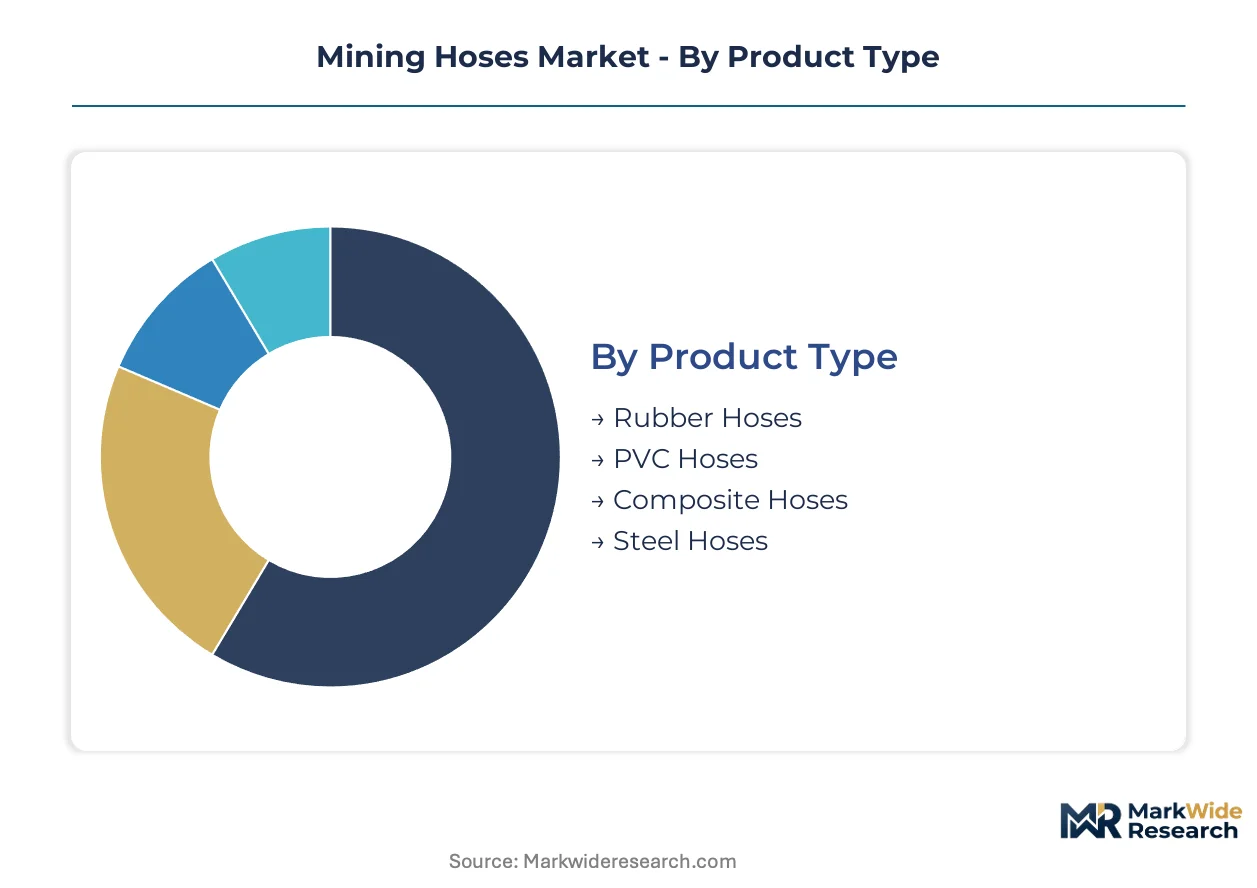
Mining hose procurement decisions pivot on abrasive media compatibility, pressure ratings, and regulatory compliance across deployment environments. Specification mismatches between product categories and operational demands drive replacement cycles and total cost divergence. Understanding segment boundaries clarifies where compounders capture premium positioning versus where standardization compresses margins.
Product Type:
Material composition determines abrasion resistance, chemical compatibility, and pressure tolerance in slurry and hydraulic service.
- Rubber Hoses:Reinforced synthetic rubber constructions with textile or steel-wire braiding withstand internal pressures exceeding 40 bar in Pilbara iron ore slurry transport. Declining ore grades force operators to pump higher volumes over longer distances, intensifying demand for extended service intervals in abrasive media.
- Composite Hoses:Multi-layer thermoplastic and fluoropolymer architectures deliver corrosion resistance in sulfuric acid and cyanide recovery circuits. Nevada gold leaching operations specify these for chemical containment where rubber compounds degrade.
- PVC Hoses:Lightweight thermoplastic constructions serve low-pressure dust suppression and ventilation lines where abrasion exposure remains minimal.
- Steel Hoses:Rigid metallic assemblies anchor fixed infrastructure in deep-shaft hydraulic networks above 60 bar pressure thresholds.
Mature deployment sits with rubber hoses across established open-pit and underground slurry networks. Newer deployment is concentrated in composite architectures for aggressive chemical leaching circuits.
Application:
Functional role in mine operations dictates pressure requirements, coupling standards, and replacement frequency.
- Slurry Transport:Abrasive ore and tailings conveyance demands abrasion-resistant linings with ceramic particle reinforcement. Chilean copper operators in the Atacama deepen pits and face escalating dewatering volumes, expanding procurement of slurry-rated assemblies.
- Water Supply:High-pressure mine water networks require assemblies rated above 40 bar for pit dewatering and process water distribution. Queensland and Western Australia regulators extend pressure-testing protocols beyond ISO 6807 baselines, adding qualification burden.
- Dust Suppression:Low-pressure spray lines for haul road and crushing circuit dust control utilize lightweight constructions with rapid deployment coupling systems.
- Ventilation:Flexible ducting for underground air circulation prioritizes flame-resistance certification under MSHA burn-testing protocols.
Slurry transport commands the steepest specification requirements and replacement expenditure. Water supply networks are expanding most quickly as pit deepening intensifies dewatering demands.
End User:
Procurement authority and technical capability shape specification complexity and aftermarket service bundling.
- Mining Companies:Owner-operators with captive engineering teams specify custom-engineered large-diameter assemblies for fixed infrastructure. Pilbara iron ore majors centralize hose assembly fabrication in captive workshops, displacing field-splicing practices.
- Contractors:Fleet-based operators prioritize modular quick-connect systems for rapid deployment and reduced installation labor. Australian contractor procurement consolidation compresses supplier rosters and unbundles aftermarket service from hardware supply.
- Equipment Manufacturers:OEM integrators specify standardized hose-and-coupling bundles for mobile mining equipment production lines.
- Service Providers:Maintenance specialists stock inventory for emergency replacement, favoring interchangeability with legacy coupling standards.
Direct procurement by mining companies dominates large-diameter custom orders. Contractor fleets are gaining share fastest in integrated maintenance contracts with supplier-managed inventory programs.
Diameter:
Scale of conveyance determines manufacturing complexity, reinforcement geometry, and margin structure.
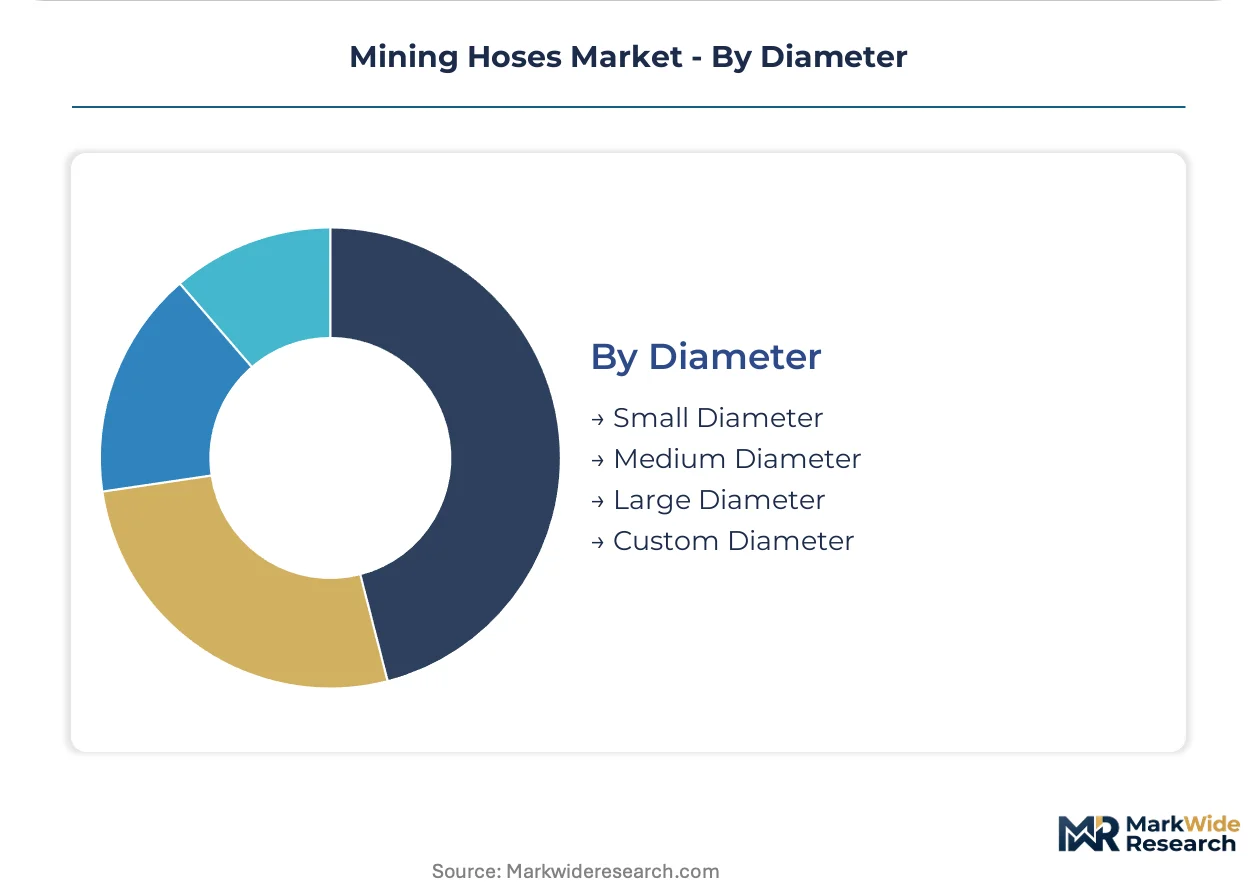
- Large Diameter:Custom-engineered constructions above 300mm internal diameter serve mine dewatering and tailings transport with multi-layer textile and steel-wire reinforcement. Australia's state-based regulators impose dynamic impulse verification requirements, favoring established compounders with captive test facilities.
- Medium Diameter:Standardized 100-300mm segments balance volume production with application flexibility across slurry and process water service.
- Small Diameter:Mass-produced lines below 100mm face price compression from contractor procurement consolidation and standardized specification.
- Custom Diameter:Non-standard geometries address retrofit installations and proprietary equipment interfaces with extended lead times and premium positioning.
Large-diameter segments concentrate margin pools in qualified supply relationships. Small-diameter standardization is accelerating fastest under procurement rationalization pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Chile's Atacama region concentrate mining hose procurement as copper operators deepen extraction. Tax incentives for mining equipment suppliers cluster manufacturing capacity near Antofagasta and Calama.
Australia
Pilbara iron ore majors drive demand for large-diameter slurry assemblies with ceramic-reinforced linings. Queensland and Western Australia regulators impose dynamic impulse verification beyond ISO 6807 baselines. Perth-based procurement offices centralize captive hose fabrication workshops, displacing field-splicing practices across contractor fleets.
Chile
Atacama copper operations expand high-pressure dewatering networks rated above 40 bar as pit depths exceed 1,000 meters. The country's mining safety regulator enforces pressure-testing protocols for underground deployment. Antofagasta contractor consolidation compresses supplier rosters toward integrated maintenance contracts with managed inventory programs.
China
Domestic compounders advance import substitution as GB standards tighten hydraulic hose construction rules. MIIT mandates certified test facilities for mining equipment suppliers. Shanxi and Inner Mongolia coal belts concentrate procurement for slurry-rated textile-reinforced constructions.
United States
Nevada gold leaching operations specify fluoropolymer-lined architectures for sulfuric acid and cyanide recovery circuits. MSHA mandates flame-resistance certification with 8-14 month burn-testing timelines for underground deployment. Elko and Battle Mountain mining clusters anchor demand for quick-connect modular systems.
South Africa
Platinum belt underground contractors pilot fiber-optic strain sensor embedded thermoplastic assemblies for real-time wear detection. The country's mining regulator extends pressure-testing protocols for deep-shaft hydraulic service. Rustenburg and Limpopo operations concentrate procurement for abrasion-resistant slurry transport.
Mining Hoses Market Competitive Environment
Top-tier vendors anchor polymer compounding and integrated system capabilities, while mid-tier fabricators compete on regional proximity and customization speed. The vendor base stratifies across three tiers: multinational elastomer specialists with captive R&D facilities, regional hose constructors with textile braiding expertise, and local assembly shops serving maintenance contracts. Two dominant competitive moves define positioning: backward integration into synthetic rubber compounding to secure feedstock margins, and strategic partnerships with mining contractors for supplier-managed inventory programs.
Among European-based elastomer specialists, Trelleborg Group and Continental AG occupy positions reflecting advanced polymer formulation capabilities. Parker Hannifin Corp exemplifies the integrated system archetype through hose-and-coupling bundling. These three represent distinct competitive vectors: Trelleborg anchors ceramic-reinforced slurry expertise, Continental exemplifies manufacturing scale across large-diameter reinforced constructions, and Parker Hannifin sits within high-pressure hydraulic network specialization.
| Leading Market Players |
|---|
| Trelleborg Group |
| Continental AG |
| Parker Hannifin Corp |
| Gates Corporation |
| Eaton |
| Weir Group PLC |
| Metso |
| Danfoss |
| Semperit AG Holding |
| Others |
Value Chain & Pricing Dynamics
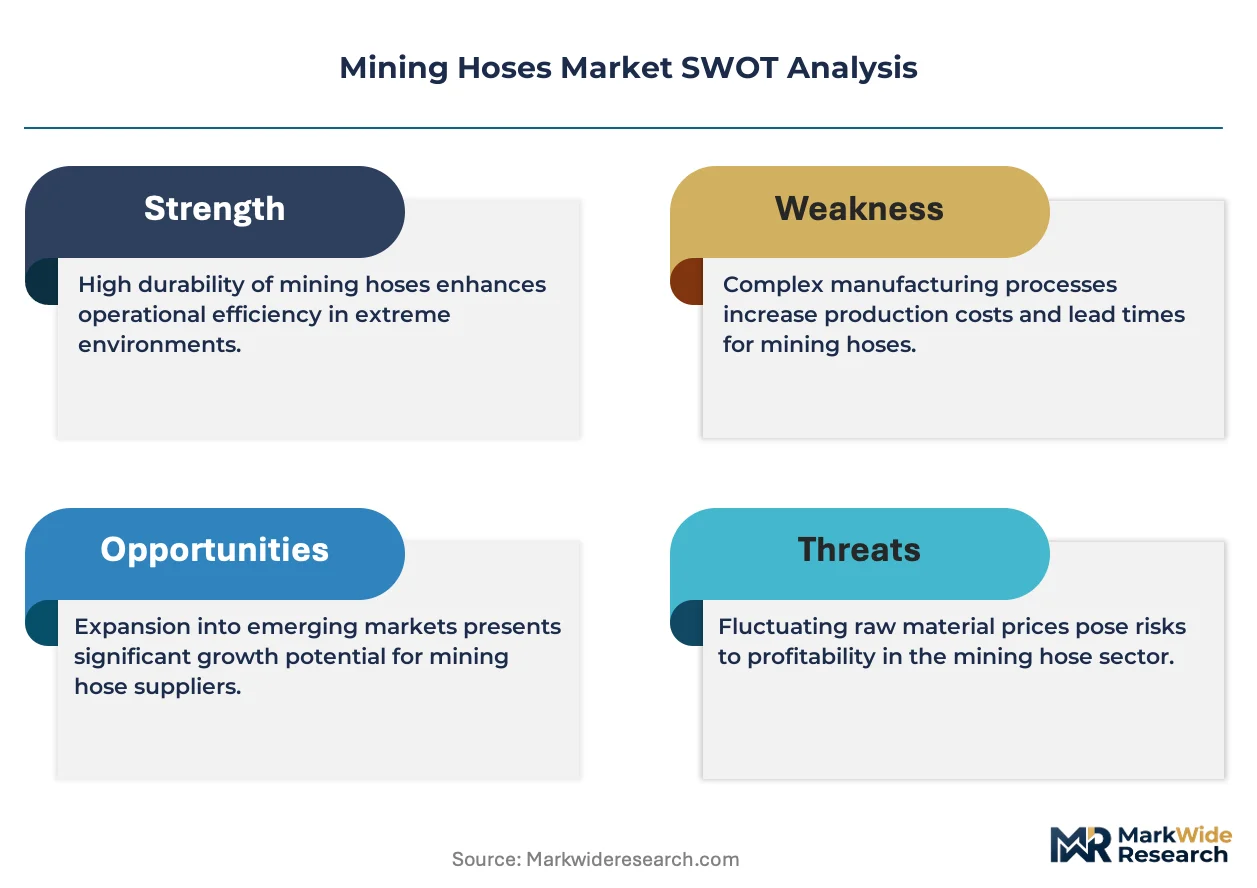
Embedded fiber-optic strain sensors in thermoplastic elastomer composites are simultaneously elevating qualification costs for compounders and concentrating procurement authority among mining contractors with captive test facilities. This technology transition compresses margins for standardized rubber hose producers while opening premium positioning for suppliers with integrated condition-monitoring capabilities.
Pricing Analysis
Short lead-time premiums dominate pricing architecture for large-diameter custom-engineered assemblies, while spot inventory of small-diameter standardized lines trades at discounts. Three-tier pricing structure across premium ceramic-reinforced, standard textile-braided, and economy PVC constructions differentiates by certification grade and abrasion resistance. Cost compression in small-diameter segments is intensifying because contractor procurement consolidation centralizes volume purchasing. Fleet-based operators exhibit highest price sensitivity, whereas owner-operators with captive engineering teams prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Freight costs from aramid yarn production centers in the United States, Germany, and Japan compound margin pressure for large-diameter hose constructors sourcing high-tenacity textile reinforcement. Synthetic rubber compounding draws from butadiene and styrene feedstocks concentrated in Northeast Asian petrochemical corridors. Single-source vulnerability in aramid yarn supply creates structural risk for multi-layer reinforcement geometries. Distribution runs through mining contractor procurement offices in Perth, Antofagasta, and Shanghai, with captive fabrication workshops displacing field-splicing intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic elastomer composites with embedded sensors are displacing legacy rubber constructions in abrasion-critical slurry service, creating a technology-transition window that reconfigures competitive positioning across compounder tiers.
For Market Incumbents: Lock in procurement relationships with Pilbara iron ore majors and Chilean copper operators through supplier-managed inventory programs. Deepen backward integration into synthetic rubber compounding to secure feedstock margins against butadiene price volatility. Invest in captive ISO 6807 test facilities to defend qualification timelines against Australian state-based regulatory extensions. For New Entrants and Emerging Players: Capture white-space in fluoropolymer-lined architectures for Nevada gold leaching circuits and South African platinum underground sensor-embedded deployments. China's tightening GB standards for hydraulic hose construction represent the most penetrable entry point for domestic compounders with certified test facilities. Pursue OEM integration partnerships with mobile mining equipment manufacturers seeking standardized hose-and-coupling bundles. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational elastomer specialists seeking regional manufacturing footprints and technology access. Long-term viability hinges on differentiation through polymer formulation capabilities rather than commodity fabrication scale. Watch for inflection signals in MSHA flame-resistance certification timeline compression, which would accelerate new product introduction velocity and reshape incumbent competitive moats.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Particle Reinforcement R&D | Extends mean time between replacement in Pilbara iron ore slurry lines beyond standard elastomer baselines. |
| Backward Integration into Compounding | Secures margin control over synthetic rubber feedstocks subject to butadiene and styrene price swings. |
| Captive Test Facility Investment | Compresses qualification timelines for Australian state-based dynamic impulse verification requirements. |
| Supplier-Managed Inventory Programs | Locks contractor procurement consolidation in Chilean Antofagasta region and Australian Pilbara belt. |
| Fluoropolymer Lining Capability | Captures premium positioning in Nevada gold leaching sulfuric acid and cyanide recovery circuits. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with mining procurement directors, hose assembly fabrication supervisors, polymer compounding R&D leads, and aftermarket maintenance specialists. MSHA certification databases, Australian state mining safety regulator pressure-test protocols, and EU REACH compliance filings provided regulatory trajectory inputs. Bottom-up unit economics triangulated against top-down sector expenditure patterns derived from mining operator capital project disclosures.
Data-stream reconciliation across product type, application function, end-user procurement authority, and diameter scale informed segmentation-level projections. Volume and value outputs across the analysis window reflect elasticity-adjusted demand curves incorporating ore grade decline rates and pit deepening intensity in Chile and Australia. CAGRs were derived from replacement cycle compression in abrasion-critical service and penetration trajectories for composite architectures in chemical leaching circuits.
The model holds under stable regulatory compliance timelines and feedstock price corridors; deviation in MSHA burn-testing protocol extensions or aramid yarn supply disruptions would shift replacement expenditure timing and margin distribution. Stakeholders should weight assumptions against their own operating context and captive engineering capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Elevator Component Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Heavy Duty Ramp Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Robotic Palletizers Market
Material Handling Equipment
Global Automatic Palletizer and Depalletizer Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Global Forklift Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Wood Chipper Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
Loading Platform Canopies Market
Material Handling Equipment
Pipelayer Market
Material Handling Equipment
Bale Clamp Intensive Market