
 Concrete Mixer Market | 2026-2036
Concrete Mixer Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Mixer Market Intelligence
The bundling of telematics and predictive maintenance services with new equipment purchases is broadening the value proposition for large construction companies and rental service providers. Liebherr International AG specializes in high-capacity, technologically advanced mixer systems for complex projects. Sany Group leverages its manufacturing scale to offer competitive pricing in high-volume markets. Oshkosh Corporation differentiates through its integrated chassis and mixer body solutions, providing a single-source vehicle for customers.
A concrete mixer is a device that combines cement, aggregates such as sand or gravel, and water to form a homogenous concrete slurry. These machines use a rotating drum or pan, operating at specific speeds to ensure consistent mixture quality and prevent premature setting. Their primary purpose is to produce ready-mix concrete for immediate use at construction sites. Drum mixers remain the most common product type for residential projects, while twin shaft mixers are gaining share in infrastructure development due to superior mixing speed and consistency.
Product design and market access are governed by a complex set of regulations. The US EPA's Tier 4 and the EU's Stage V emission standards dictate engine requirements for diesel-powered mixers, pushing manufacturers toward cleaner technologies. Concurrently, CE marking is mandatory for equipment sold within the European Economic Area, ensuring compliance with safety and health standards. The critical decision for fleet managers involves balancing the initial capital outlay for new, compliant equipment against the total cost of ownership and regulatory risk.
Market Dynamics
The central tension in the concrete mixer market is the drive for electrification and advanced telematics, spurred by emissions regulations like the EU's Stage V, against the intense cost-sensitivity of high-volume construction projects in South Asia.
Growth Catalysts
- Government Infrastructure Spending:National programs, such as India's National Infrastructure Pipeline, are mandating the construction of new roads, bridges, and public works, directly fueling demand for new mixer fleets.
- Twin Shaft Mixer Adoption:The technical requirement for high-strength, consistent concrete in large-scale civil engineering projects is driving the adoption of twin shaft mixers over traditional drum types.
- Rapid Urbanization:Concentrated urban development in South Asian megacities requires a continuous supply of ready-mix concrete for residential high-rises and commercial complexes, sustaining equipment demand.
Market Restraints
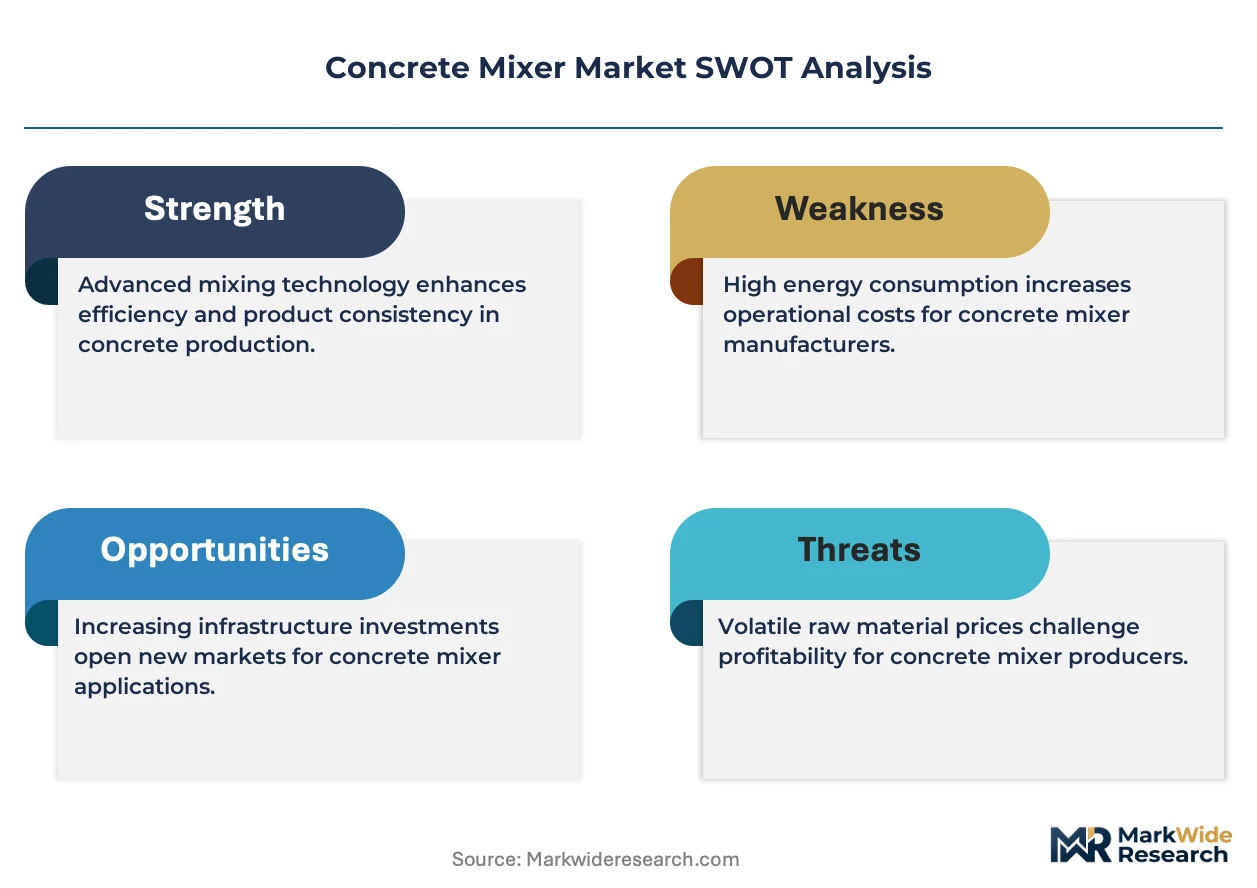
- High Capital Outlay:The initial purchase price of mixers compliant with US EPA Tier 4 and EU Stage V emission standards presents a significant financial barrier for small and mid-sized contractors.
- Raw Material Price Volatility:Fluctuations in global steel prices directly impact manufacturing costs for mixer drums and frames, creating pricing instability and margin pressure for OEMs.
- Electrification Infrastructure Gaps:The lack of reliable, high-capacity charging infrastructure at many construction sites limits the practical deployment of battery-electric concrete mixer models, especially for continuous operation.
Strategic Opportunities
- Predictive Maintenance Services:Integrating telematics and IoT sensors into mixer fleets offers a new revenue stream through subscription-based predictive maintenance and fleet optimization services for rental companies.
- Fleet Electrification Retrofits:Developing standardized kits to retrofit existing diesel-powered mixer fleets with electric or hybrid-electric powertrains can capture value from operators seeking compliance without full vehicle replacement.
- African Infrastructure Development:Expanding distribution and service networks in Sub-Saharan African countries addresses an underpenetrated market with emerging large-scale transportation and energy infrastructure projects.
Industry Challenges
- Skilled Technician Shortage:A deficit of mechanics and technicians trained to diagnose and repair complex electronic control units and advanced hydraulic systems is a key operational bottleneck.
- Regulatory Fragmentation:Fleet operators face complexity in managing compliance with varying local and municipal regulations concerning vehicle gross weight, axle loads, and delivery time restrictions in urban areas.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Mixer Market |
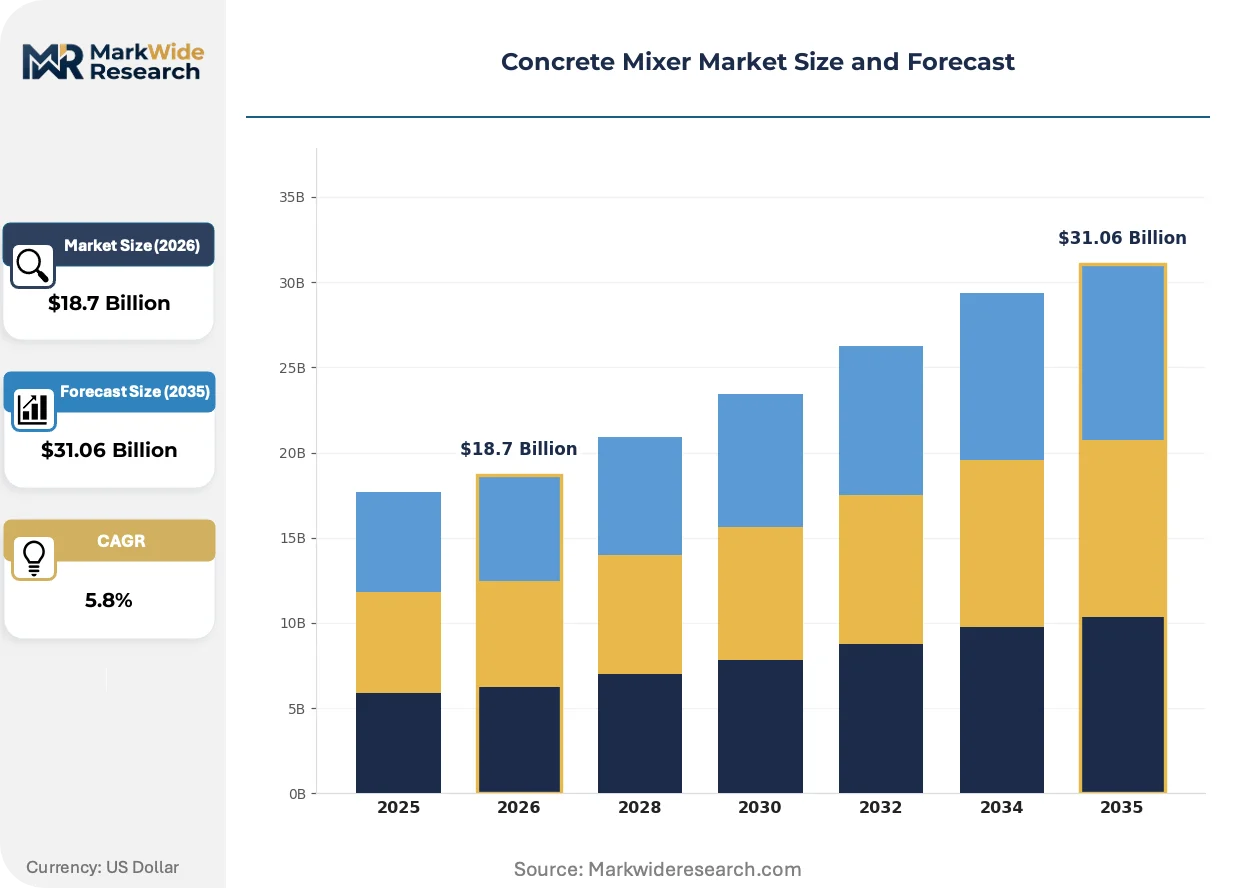
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drum Mixers, Pan Mixers, Twin Shaft Mixers, Continuous Mixers Technology: Hydraulic, Electric, Diesel Engine, Pneumatic Application: Infrastructure Development, Commercial Construction, Residential Projects, Road Construction End User: Construction Companies, Real Estate Developers, Public Works Departments, Rental Service Providers |
| Companies Covered | XCMG Group, Terex Corporation, Sany Group, Oshkosh Corporation, Schwing GmbH, Liebherr International AG, Zoomlion Heavy Industry, Putzmeister Concrete Pumps, AB Volvo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Mixer Market Strategic Shifts & Innovations
Evolution in the concrete mixer market is shifting from mechanical improvements to a focus on digitalization and electrification. This is driven by regulatory pressures for cleaner operation and customer demand for greater operational intelligence.
Onboard sensor systems monitor drum speed, slurry viscosity, and water content in real-time. Large-scale ready-mix suppliers and infrastructure contractors are primary adopters, seeking to minimize waste and ensure project specification compliance. This technology is automating critical quality control processes previously dependent on manual operator skill and post-pour testing.
The European Union's Stage V emission standards set stringent limits on particulate matter and NOx from non-road mobile machinery. This regulation compels manufacturers to integrate advanced diesel aftertreatment systems or shift to electric powertrains. Equipment manufacturers selling into the European Economic Area are directly impacted, re-engineering product lines to meet these mandatory requirements.
A clear behavioral shift is occurring from outright equipment purchase to long-term rental and leasing agreements. This model allows construction companies to manage capital expenditure and access the latest technology without a large upfront investment. The trend is most visible in North America and Europe, where large rental corporations are a major channel for manufacturers.
Concrete Mixer Market Segmentation
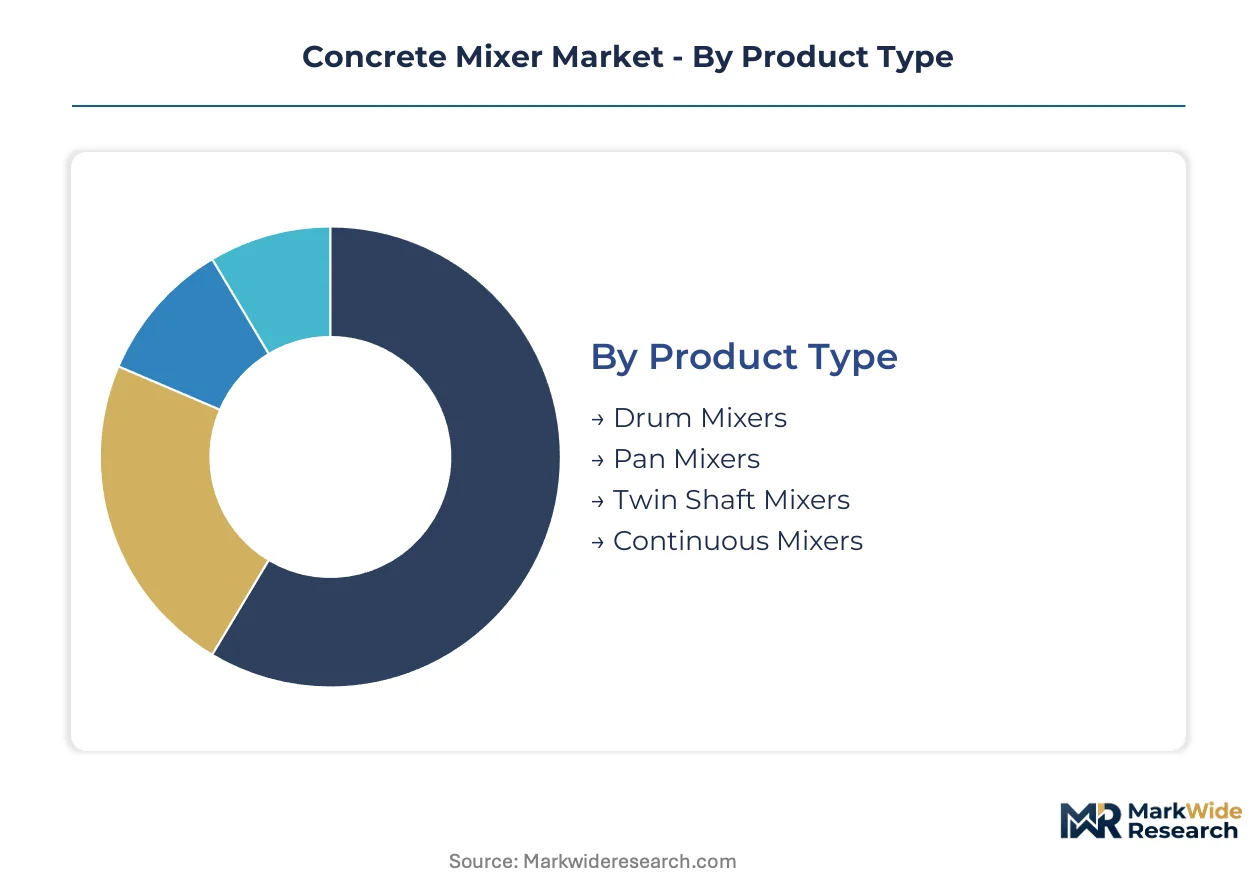
The concrete mixer market's segmentation reveals diverse operational needs and technological preferences across construction activities. Understanding these distinct segments allows manufacturers to tailor product development and market access strategies effectively. Each category reflects specific demands from project scales and regulatory environments.
Product Type:
The product type category spans a spectrum from highly standardized, widely adopted designs to specialized systems for complex concrete formulations.
- Twin Shaft Mixers:These mixers utilize two horizontal shafts with paddles, counter-rotating to achieve rapid, homogenous mixing, particularly for high-strength concrete. Demand concentrates in large-scale infrastructure projects like bridges and dams, driven by stringent quality requirements.
- Drum Mixers:Characterized by a rotating drum, these mixers lift and drop materials to combine them, offering a cost-effective solution for standard concrete. Residential projects and small to mid-sized construction sites represent a significant demand base, valuing their operational simplicity.
- Pan Mixers:Featuring a rotating pan and stationary blades, pan mixers are suitable for stiff and semi-dry concrete mixes, often used in precast concrete production.
- Continuous Mixers:These machines process materials continuously, ideal for projects requiring a constant, high volume supply of concrete, such as road paving.
Leading the category by volume: Drum Mixers. Growing fastest: Twin Shaft Mixers.
Technology:
The technology segment delineates the power sources and operational mechanisms driving concrete mixer performance and efficiency.
- Electric:Electric mixers use battery power or grid connections, eliminating direct emissions and reducing noise levels, aligning with urban construction mandates. Demand for these models is expanding in European markets due to stringent EU Stage V emission standards and increasing site electrification.
- Diesel Engine:These mixers rely on internal combustion diesel engines for power, offering robust performance and widespread availability across diverse construction sites. Despite regulatory pressures from US EPA Tier 4 and EU Stage V, diesel remains dominant in regions lacking electrification infrastructure.
- Hydraulic:Hydraulic systems provide precise control over mixing functions and drum rotation, enhancing operational flexibility and durability in heavy-duty applications.
- Pneumatic:Pneumatic mixers use compressed air to agitate and convey concrete, often chosen for specialized applications requiring precise material placement or low impact.
Electric technology is gaining share fastest, while Diesel Engine technology maintains the largest installed base.
Application:
The application segment highlights the diverse end-uses for concrete mixers, ranging from large-scale public works to individual housing developments.
- Infrastructure Development:This application involves large-scale public projects like highways, bridges, and dams, requiring high-volume and consistent concrete delivery. Government infrastructure spending in countries like India directly fuels demand for advanced mixer fleets in this segment.
- Residential Projects:This segment encompasses the construction of single-family homes, multi-unit dwellings, and low-rise apartments, typically utilizing standard concrete mixes. Drum mixers find extensive use here, valued for their cost-effectiveness and ease of operation.
- Commercial Construction:This category covers office buildings, retail centers, and industrial facilities, often demanding specialized concrete for structural integrity and aesthetic finishes.
- Road Construction:Mixers in this application support the building and repair of roads, runways, and other paved surfaces, often requiring continuous mixing for long stretches.
Infrastructure Development commands the largest share, with Residential Projects also exhibiting significant volume.
End User:
The end user category distinguishes the primary entities procuring and operating concrete mixing equipment across the construction ecosystem.
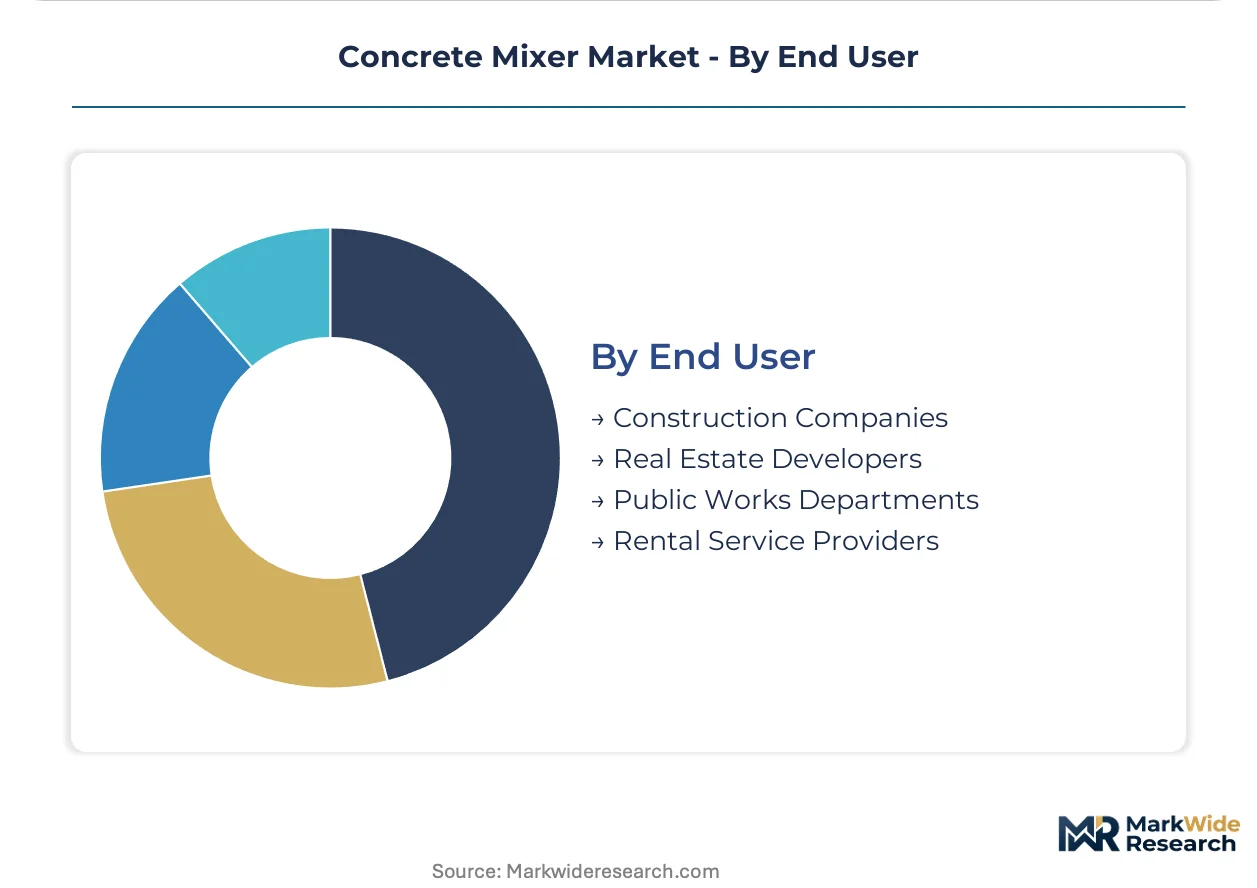
- Construction Companies:These firms directly purchase and operate mixers for their diverse project portfolios, seeking equipment that balances capital outlay with operational efficiency. Their procurement decisions are often influenced by project scale and regulatory compliance.
- Rental Service Providers:These companies acquire mixer fleets for lease to other construction entities, offering flexibility and access to modern equipment without significant upfront investment. This segment is expanding in North America and Europe, driven by capital expenditure management trends.
- Real Estate Developers:These entities oversee residential and commercial property developments, often contracting construction companies but influencing equipment specifications.
- Public Works Departments:Government agencies responsible for public infrastructure projects procure mixers for maintenance and new construction, prioritizing durability and regulatory adherence.
Construction Companies represent the largest customer base, while Rental Service Providers exhibit the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global concrete mixer market exhibits a distinct divide between production centers and high-consumption geographies. Demand for new equipment is concentrating in rapidly urbanizing economies, while manufacturing and advanced technological development often originate from established industrial nations. This dynamic shapes investment and distribution strategies.
India
India's robust infrastructure development projects, such as the National Infrastructure Pipeline, drive substantial demand for concrete mixers. The Bureau of Indian Standards (BIS) sets quality and safety benchmarks for construction equipment, influencing local manufacturing. Major construction hubs like Mumbai and Delhi require continuous supplies of ready-mix concrete for high-rise developments.
China
China's vast construction market and significant manufacturing capacity position it as a key player in concrete mixer production and consumption. The country's dual carbon goals encourage the adoption of more energy-efficient and electric models. Industrial clusters in provinces like Jiangsu and Shandong are centers for heavy machinery innovation and export.
Germany
Germany represents a hub for advanced concrete mixer technology, driven by stringent environmental regulations and a focus on engineering excellence. The EU's Stage V emission standards mandate cleaner engine technologies for equipment sold within the European Economic Area. Manufacturers in regions like Bavaria and North Rhine-Westphalia develop high-capacity and specialized mixing systems.
United States
The United States market is characterized by a strong rental sector and significant investment in public works and residential construction. US EPA Tier 4 emission standards dictate engine requirements for diesel-powered mixers, pushing manufacturers toward compliance. Major metropolitan areas such as New York City and Los Angeles continuously demand concrete for urban expansion and infrastructure repair.
France
France's infrastructure modernization initiatives and urban development projects sustain demand for concrete mixing equipment. CE marking is mandatory for all machinery placed on the European market, ensuring adherence to health and safety standards. Construction activity in regions like Île-de-France and Auvergne-Rhône-Alpes benefits from government-backed housing and transportation programs.
Concrete Mixer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the concrete mixer market. This creates a tiered structure where global manufacturers with broad portfolios coexist with regional players serving specific niches. Strategic archetypes include large-scale integrated machinery providers and technology-focused innovators. Geographic expansion and strategic partnerships remain dominant competitive moves across the industry.
Within the high-capacity, technologically advanced segment, Liebherr International AG represents a key player, often targeting complex civil engineering projects. Sany Group, a Chinese heavy machinery manufacturer, exemplifies the scale-driven end of the market, leveraging its manufacturing prowess for competitive pricing in high-volume regions. Oshkosh Corporation, particularly through its integrated chassis and mixer body solutions, occupies a position focused on single-source vehicle provision for customers in North America.
| Leading Market Players |
|---|
| XCMG Group |
| Terex Corporation |
| Sany Group |
| Oshkosh Corporation |
| Schwing GmbH |
| Liebherr International AG |
| Zoomlion Heavy Industry |
| Putzmeister Concrete Pumps |
| AB Volvo |
Cost & Logistics Intelligence
Electrification mandates, driven by EU Stage V emission standards, reshape concrete mixer cost economics by increasing initial capital outlay. This transition simultaneously shifts supply chain dependencies towards specialized component manufacturers.
Pricing Analysis
Cost-down pressure on standard drum mixers intensifies due to high-volume competition from manufacturers like Sany Group. The dominant pricing model remains per-unit transactional for new equipment purchases. Price differentiation stems from quality grade, particularly between twin shaft and drum mixers, and the bundling of after-sales services like predictive maintenance. Small and mid-sized contractors exhibit the highest price sensitivity, balancing initial capital outlay against regulatory compliance.
Supply Chain Analysis
Direct sales channels to large construction companies and rental service providers dominate concrete mixer distribution. Geographic supply concentration centers in China, Germany, and the United States, reflecting manufacturing prowess and technological development. The industry relies on key raw materials such as steel for drums and frames, alongside specialized diesel engines and electronic control units. Raw material price volatility, particularly for steel, presents a significant supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The concrete mixer market presents a consolidation play, driven by escalating regulatory compliance costs for emission standards. This pressure disproportionately impacts smaller manufacturers and pushes for market rationalization.
For Market Incumbents: Cement market leadership by investing heavily in R&D for electric and hybrid powertrains, addressing stricter emission standards like EU Stage V. Expand global service and support networks, particularly in emerging markets, to counter regional competitors. Deepen control over critical component manufacturing to mitigate supply chain risks. Offer comprehensive telematics and predictive maintenance services to enhance customer loyalty against new entrants.
For New Entrants and Emerging Players: Rental service providers offer a strong entry point for specialized mixer technologies. Target underpenetrated markets in Sub-Saharan Africa, focusing on localized solutions for emerging infrastructure projects. Develop standardized retrofit kits for existing diesel fleets, allowing operators to meet compliance without full vehicle replacement. Emphasize lower total cost of ownership through advanced telematics for fleet optimization.
For Investors and Strategic Acquirers: Exit pathways concentrate in technology specialists offering electrification solutions or regional leaders with strong distribution networks. The market exhibits long-term viability, driven by sustained global infrastructure development and urbanization. Identify acquisition targets with robust intellectual property in battery technology or advanced mixing systems. Watch the adoption rate of electric mixer models as a key inflection indicator for future market direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Electrification R&D | Meets stringent emission standards and positions for future urban construction mandates. |
| Expand Predictive Maintenance Services | Creates recurring revenue streams and enhances equipment uptime for fleet operators. |
| Develop Retrofit Electrification Kits | Addresses compliance needs for existing diesel fleets, extending equipment lifecycle value. |
| Enter Sub-Saharan African Markets | Capitalizes on emerging infrastructure spending in an underpenetrated geographic region. |
| Consolidate Regional Manufacturing | Achieves economies of scale and optimizes production for specific market demands. |
Research Approach
Multi-period observation of equipment sales volumes and regulatory changes anchored the trend analysis, supplemented by interviews with construction company executives, rental fleet managers, and OEM product development leads. This primary research, alongside insights from regulatory compliance officers, validated market dynamics. Secondary data sources included government infrastructure reports, industry association publications, and manufacturer annual reports. A blend of bottom-up and top-down triangulation ensured robust data integrity.
Segment-weighting across product type, technology, application, end user, and regional demand formed the core analytical framework over the projection horizon. Compound Annual Growth Rates (CAGRs) were derived from historical data analysis and projected growth drivers. Key inputs included government infrastructure spending projections and urbanization rates, influencing future demand. The framework integrated these factors to model market evolution.
Caveats apply where geopolitical instability or raw material supply disruptions could materially shift the outlook. Forecasts reflect assumptions regarding regulatory stability and sustained infrastructure investment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Backhoes Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Plastic Molding Machine Market
Construction Equipment
Shield Machines Market
Construction Equipment
Global Construction Dumper Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Global Welding Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Snow Pushers Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Global Wheel Aligner Equipment Market