
 Global Wheel Aligner Equipment Market | 2026-2036
Global Wheel Aligner Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wheel Aligner Equipment Market Outlook
Multi-source procurement among tier-one distributors is expanding as wheel aligner manufacturers diversify component supply beyond traditional single-source relationships. Hunter Engineering Company leverages captive production of optical sensor arrays to sustain margin control across North American service networks. Snap-on Incorporated competes through dense dealer-franchise coverage that anchors aftermarket loyalty. Launch Tech Co., Ltd. dominates price-sensitive segments in Asia-Pacific through vertically integrated manufacturing of CCD-based alignment heads.
Wheel aligner equipment comprises precision measurement systems that quantify camber, caster, toe, and thrust angle deviations using optical, laser, or ultrasonic sensors, typically achieving resolution below 0.01 degrees for commercial vehicle applications. These systems correct wheel geometry to reduce tire wear, improve fuel efficiency, and ensure steering stability across passenger and commercial fleets. Three-dimensional aligners now lead product type demand as vehicle suspensions grow more complex, while portable installation types capture the fastest growth by enabling roadside fleet maintenance and pop-up service operations. Laser technology retains the largest installed base among technology segments, though CCD systems claim expanding share in mid-tier workshops seeking faster calibration cycles.
FCC equipment authorization requirements govern wireless data transmission in connected aligner systems across the United States, while CE marking under the EU Machinery Directive mandates electromagnetic compatibility and operator safety protocols for European market access. China's GB standards, administered by SAMR, specify metrological accuracy thresholds that domestic and imported aligners must satisfy before commercial deployment. Stakeholders must monitor divergence between regional certification regimes as connected diagnostics and cloud-based calibration databases complicate cross-border equipment compliance.
Market Dynamics
The EU Green Deal's tire efficiency mandates are forcing alignment precision upgrades across European service networks, while China's fleet modernization sustains procurement cycles for high-resolution 3D aligners.
Growth Catalysts
- EU Green Deal tire standards:Mandatory rolling resistance targets require sub-0.01-degree alignment accuracy, compelling workshop equipment replacement across Germany, France, and Italy.
- China's commercial fleet electrification:Heavy EV buses and trucks impose uneven weight distributions that accelerate wheel misalignment, driving demand for robust commercial-grade aligners in Shenzhen and Chengdu service hubs.
- CCD sensor maturation:Faster calibration cycles reduce bay downtime, making mid-tier workshops in India and Brazil viable upgrade candidates previously priced out of laser systems.
Market Restraints
- Optical component supply concentration:Precision lens arrays and CMOS sensors concentrate in Japanese and South Korean component foundries, exposing aligner manufacturers to single-source fragility.
- FCC equipment authorization timelines:Wireless-enabled aligners face 6-12 month certification delays for connected diagnostics features, slowing US product launches against wired alternatives.
- Ultrasonic measurement substitution:Lower-cost ultrasonic wheel position sensors capture price-sensitive fleet maintenance contracts in Southeast Asia, compressing entry-level optical aligner margins.
Strategic Opportunities
- Roadside fleet maintenance channels:Portable aligner installations enable pop-up service operations at logistics hubs and highway corridors, bypassing fixed workshop real estate constraints.
- Cloud-based calibration databases:Connected aligners transmitting measurement data to central repositories create recurring software revenue streams and predictive maintenance hooks for commercial fleet managers.
- India's PLI scheme for automotive components:Domestic manufacturing incentives reduce import duties on alignment equipment, opening price-competitive positioning for localized assembly operations.
Industry Challenges
- Metrology technician scarcity:Advanced 3D aligner operation requires certified calibration specialists, creating hiring bottlenecks in US Rust Belt and Eastern European industrial zones.
- Legacy bay integration complexity:Older lift installations lack the structural tolerances and power specifications for camera-based alignment systems, forcing costly infrastructure overhauls.
- Cross-border certification divergence:Separate FCC, CE marking, and SAMR GB standard compliance paths fragment product development resources and delay synchronized global launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wheel Aligner Equipment Market |
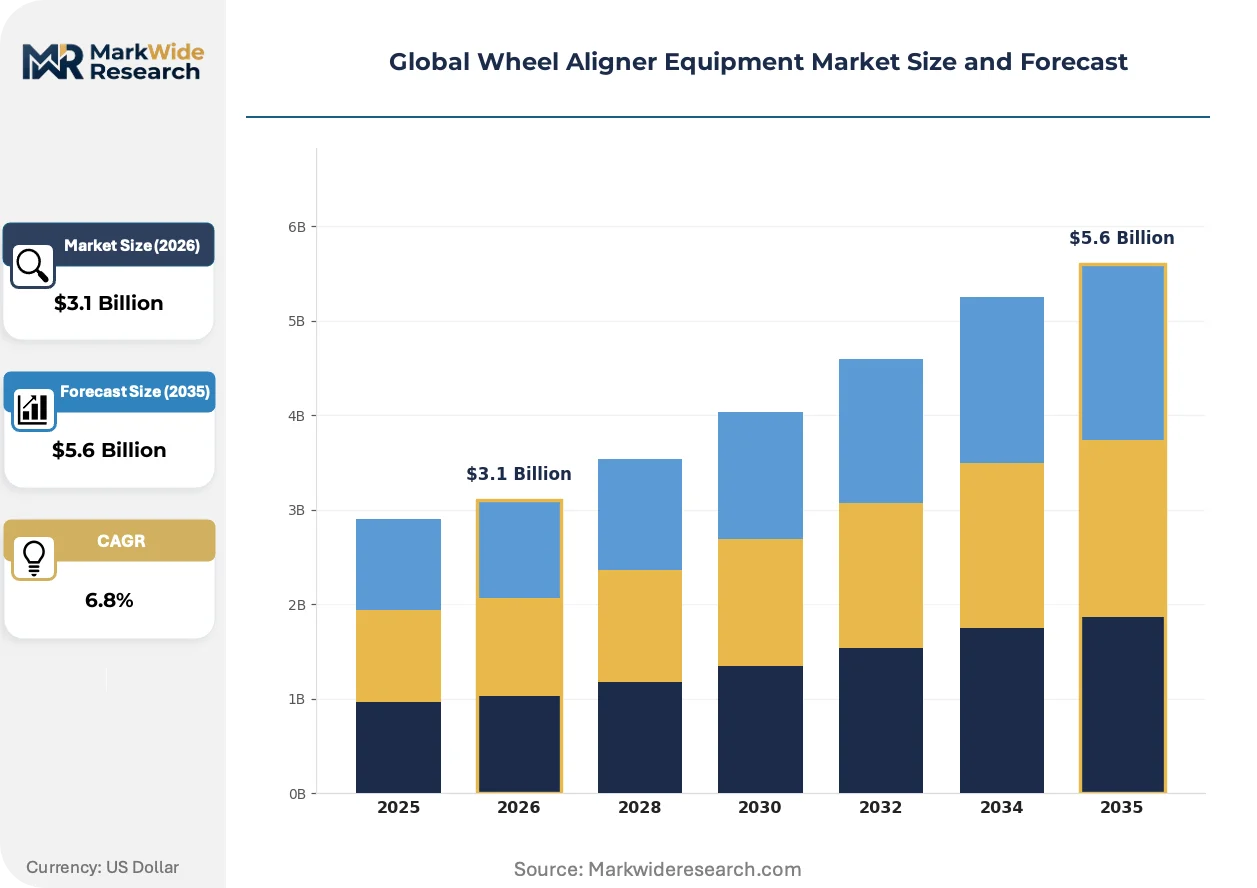
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Aligners, 3D Aligners, Diagnostic Equipment, Software Solutions End User: Automobile Workshops, OEMs, Tire Retailers, Fleet Operators Technology: Laser Technology, Infrared Technology, CCD Technology, ultrasonic Technology Installation Type: Portable Aligners, Permanent Stations, Mobile Units, Fixed Systems |
| Companies Covered | Hunter Engineering Company, Snap-on Incorporated, Beissbarth GmbH, CORGHI, Delta Equipments, MAHA Maschinenbau Haldenwang GmbH Co. KG, Launch Tech Co., Ltd., CEMB Spa, Bee Line Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wheel Aligner Equipment Market Strategic Shifts
Measurement automation and connected diagnostics are compressing service bay cycle times while regulatory precision mandates reshape equipment specifications across major automotive markets.
Three-dimensional imaging aligners is expanding into independent automobile workshops previously served by conventional laser systems. These camera-based systems capture complete vehicle geometry in single measurement cycles, cutting alignment procedure time by half. Mid-tier buyers in Spain, Poland, and Mexico are adopting the technology to handle complex multi-link suspensions on European and Asian vehicle platforms.
CE marking under the EU Machinery Directive now mandates electromagnetic compatibility testing for wireless data transmission features in connected aligners. The requirement adds certification complexity for manufacturers integrating cloud diagnostics but creates competitive moats against uncertified imports. German and French distributor networks are prioritizing compliant equipment to avoid liability exposure under operator safety protocols.
Service contract unbundling is fragmenting traditional equipment-plus-maintenance bundles into separate hardware, software, and calibration subscription tiers. Fleet operators in California and Texas are driving this shift, preferring per-alignment pricing over capital expenditure commitments. The model pressures manufacturers to develop recurring revenue architectures while exposing them to churn risk from third-party calibration service providers.
Global Wheel Aligner Equipment Market Segmentation
Wheel aligner equipment segments diverge sharply in regulatory burden, with wireless-enabled 3D systems requiring FCC authorization while portable units face lighter compliance loads. Understanding these certification boundaries helps manufacturers prioritize development resources and distributors anticipate stocking requirements across customer tiers.
Product Type:
FCC equipment authorization applies strictly to connected 3D aligners transmitting diagnostic data wirelessly, while CE marking under the EU Machinery Directive governs all automated measurement systems sold in Europe regardless of dimensionality.
- 3D Aligners:Camera-based systems capture complete vehicle geometry through triangulated optical sensor arrays, achieving sub-0.01-degree resolution demanded by EU Green Deal tire efficiency mandates. Fleet operators in Germany and France are replacing legacy 2D installations to meet these precision thresholds.
- 2D Aligners:Conventional laser-based systems measure individual wheel angles sequentially. Independent automobile workshops in India and Brazil retain these units for basic passenger vehicle service where suspension complexity remains limited.
- Diagnostic Equipment:Integrated systems combining alignment measurement with suspension health monitoring.
- Software Solutions:Cloud-based calibration databases and predictive maintenance platforms requiring data transmission compliance.
Leading the category by volume: 3D Aligners. Growing fastest: Software Solutions.
End User:
Cost tier stratification separates capital-rich fleet operators from price-sensitive independent workshops, with OEMs occupying a midpoint defined by warranty compliance requirements rather than procurement budget constraints.
- Fleet Operators:Commercial vehicle managers operating centralized maintenance depots for logistics and transit systems. Heavy EV bus deployments in Shenzhen and Chengdu generate uneven weight distributions that accelerate alignment frequency, sustaining procurement of robust commercial-grade systems.
- Automobile Workshops:Independent service facilities handling diverse vehicle platforms. These buyers in Spain, Poland, and Mexico are upgrading to 3D aligners to address complex multi-link suspensions on European and Asian vehicle platforms.
- OEMs:Vehicle manufacturers requiring alignment verification during final assembly and warranty service networks.
- Tire Retailers:Point-of-sale service providers bundling alignment with tire replacement transactions.
Volume concentrates with Automobile Workshops. Steepest expansion trajectory belongs to Fleet Operators.
Technology:
Maturity curves separate established laser installations from emerging CCD adoption, with ultrasonic systems capturing price-sensitive niches through simplified component sourcing.
- CCD Technology:Charge-coupled device sensors enable faster calibration cycles through simultaneous multi-point measurement. Mid-tier workshops in India and Brazil find these systems accessible at price points previously reserved for laser alternatives.
- Laser Technology:Established optical measurement using coherent light projection onto mechanical targets. This segment retains the largest installed base globally despite slower single-point measurement sequences.
- Infrared Technology:Non-visible spectrum sensing for specialized industrial applications.
- Ultrasonic Technology:Lower-cost wheel position sensors capturing fleet maintenance contracts in Southeast Asia, compressing margins for entry-level optical aligners.
CCD Technology gains share fastest. Laser Technology maintains installed base leadership.
Installation Type:
Supply concentration in Japanese and South Korean optical component foundries constrains portable system production, while fixed installations leverage more commoditized structural materials.
- Portable Aligners:Compact systems enabling roadside fleet maintenance and pop-up service operations at logistics hubs. California and Texas fleet operators are driving unbundled service contracts that favor per-alignment pricing over fixed bay investment.
- Mobile Units:Vehicle-mounted alignment systems for on-site commercial vehicle service.
- Permanent Stations:Fixed bay installations integrated with hydraulic lifts in dedicated workshop facilities.
- Fixed Systems:Hardwired equipment requiring structural bay modifications and power infrastructure upgrades.
Permanent Stations dominate current volume. Portable Aligners are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese and South Korean optical component foundries supply precision lens arrays and CMOS sensors that anchor wheel aligner manufacturing across major automotive markets. Equipment procurement concentrates where fleet electrification and regulatory precision mandates intersect.
United States
FCC equipment authorization timelines of 6-12 months delay wireless-enabled aligner launches, favoring wired alternatives in the near term. California and Texas fleet operators drive unbundled service contracts toward per-alignment pricing models. Rust Belt industrial zones face metrology technician scarcity that constrains 3D aligner deployment.
Germany
EU Green Deal tire efficiency mandates force alignment precision upgrades to sub-0.01-degree accuracy thresholds. CE marking under the EU Machinery Directive mandates electromagnetic compatibility testing for connected systems. Stuttgart and Munich service networks prioritize compliant equipment to avoid liability exposure under operator safety protocols.
China
Heavy EV bus and truck deployments in Shenzhen and Chengdu generate uneven weight distributions that accelerate wheel misalignment frequency. SAMR-administered GB standards specify metrological accuracy thresholds for domestic and imported aligners. Fleet modernization and domestic automotive production expansion sustain procurement cycles for high-resolution 3D systems.
India
PLI scheme incentives for automotive components reduce import duties on alignment equipment, opening price-competitive positioning for localized assembly. Mid-tier workshops in Mumbai and Pune adopt CCD systems at price points previously reserved for laser alternatives. BIS certification requirements govern equipment safety and electromagnetic compatibility for commercial deployment.
Brazil
Independent automobile workshops retain 2D laser systems for basic passenger vehicle service where suspension complexity remains limited. Price-sensitive fleet maintenance contracts in São Paulo compress margins for entry-level optical aligners against ultrasonic measurement substitution. ANVISA regulates electromagnetic emissions for connected diagnostic equipment in commercial service networks.
Global Wheel Aligner Equipment Market Competitive Environment
Global majors compete with regional champions across technology tiers and distribution density. The vendor base separates into optical sensor specialists, dense dealer-franchise operators, and vertically integrated price leaders. Three archetypes dominate: captive component producers controlling upstream supply, franchise-anchored aftermarket loyalty builders, and integrated manufacturers serving cost-sensitive segments. Competitive moves concentrate on geographic expansion through distributor partnerships and portfolio diversification into cloud-based calibration services.
Within the captive production archetype, Hunter Engineering Company exemplifies margin control through in-house optical sensor array manufacturing. Snap-on Incorporated anchors the franchise-anchored tier through North American dealer network density. Launch Tech Co., Ltd. occupies the integrated manufacturer position, representing price-competitive positioning in Asia-Pacific markets. These three companies illustrate how supply chain configuration, distribution architecture, and manufacturing integration separate competitive positioning across customer tiers.
| Leading Market Players |
|---|
| Hunter Engineering Company |
| Snap-on Incorporated |
| Beissbarth GmbH |
| CORGHI |
| Delta Equipments |
| MAHA Maschinenbau Haldenwang GmbH Co. KG |
| Launch Tech Co., Ltd. |
| CEMB Spa |
| Bee Line Co. |
| Others |
Value Chain & Pricing Dynamics
Metrology technician scarcity in the US Rust Belt and Eastern European industrial zones widens labor-cost differentials that separate premium 3D aligner service contracts from economy-tier 2D laser installations. Warranty bundling and calibration subscription tiers further stratify pricing across independent automobile workshops and fleet operators.
Pricing Analysis
Warranty and calibration service bundling separates capital expenditure models from recurring revenue architectures across buyer segments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with CE-marked connected systems commanding premiums over basic laser alternatives. Pricing pressure stems from ultrasonic measurement substitution capturing Southeast Asian fleet contracts. Independent automobile workshops in India and Brazil exhibit highest price sensitivity, while German fleet operators prioritize precision compliance over procurement cost.
Supply Chain Analysis
Freight costs for precision optical assemblies from Japanese and South Korean component foundries inflate landed costs for North American and European aligner manufacturers. Camera sensor arrays, CMOS modules, and triangulated lens systems draw from concentrated East Asian supply bases. Single-source vulnerability in optical component sourcing exposes manufacturers to foundry allocation constraints. Distribution runs through tier-one distributor networks and OEM-authorized dealer franchises.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where CE marking under the EU Machinery Directive and FCC equipment authorization requirements erect regulatory moats that favor incumbents with certification infrastructure investments.
For Market Incumbents: Extend cloud-based calibration database offerings to capture recurring software revenue streams and deepen customer switching costs. Invest in captive optical sensor production to defend margin position against supply concentration risks. Address ultrasonic substitution threats in Southeast Asia through portable aligner product line expansion.
For New Entrants and Emerging Players: Independent automobile workshops in Poland, Mexico, and Spain represent the most penetrable upgrade path as these facilities transition from 2D laser to 3D camera-based systems. Target India's PLI scheme incentives for localized assembly operations to bypass import duty barriers. Partner with regional tire retail chains for bundled point-of-sale service contracts.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated manufacturers possessing in-house optical sensor production given supply chain fragility in East Asian component foundries. Long-term viability favors players with recurring revenue architectures spanning software subscriptions and predictive maintenance platforms. Monitor FCC authorization timeline compression as an inflection signal for wireless-enabled aligner adoption acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Sensors | In-house CMOS and lens array production insulates margins from Japanese and South Korean foundry allocation constraints. |
| Cloud Calibration Database Deployment | Connected aligners transmitting measurement data to central repositories generate recurring software revenue from commercial fleet operators. |
| Portable Aligner Product Line Expansion | Compact systems enable roadside fleet maintenance at California and Texas logistics hubs bypassing fixed bay real estate requirements. |
| Regional Certification Infrastructure Investment | Simultaneous FCC, CE marking, and SAMR GB standard compliance capabilities accelerate synchronized global product launches. |
| Dealer-Franchise Network Density Expansion | Dense aftermarket coverage anchors loyalty among independent automobile workshops in North American service territories. |
Study Parameters
Independent corroboration across equipment manufacturer interviews, tier-one distributor consultations, and fleet operator procurement assessments underwrites the qualitative findings. Primary fieldwork engaged aftermarket service heads, OEM platform engineers, metrology calibration specialists, and automotive workshop owners across Germany, China, India, and the United States. Secondary validation drew from vehicle production databases, customs import records for optical components, FCC equipment authorization filings, and EU Machinery Directive compliance registries. Bottom-up unit economics triangulated against top-down market sizing across product type, end user, technology, and installation type segmentation dimensions.
Comparable historical reference periods anchored the projection horizon to observed replacement cycles for laser and CCD alignment systems. The analytical framework modeled demand across 3D aligners, 2D aligners, diagnostic equipment, and software solutions segments intersecting with fleet operator, automobile workshop, OEM, and tire retailer end users. CAGRs derived from equipment procurement intensity ratios tied to commercial vehicle fleet electrification trajectories and EU Green Deal regulatory compliance deadlines. Industry-specific forecast inputs included GB standard metrological accuracy thresholds and PLI scheme incentive qualification criteria.
Caveats apply where FCC authorization timeline delays, optical component supply disruptions, or ultrasonic measurement technology substitution could materially shift the outlook. Forecasts reflect assumptions regarding technician certification availability and workshop infrastructure upgrade rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Southern Africa Construction Equipment Rental Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Construction Pump Market
Construction Equipment
Cable Winches Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Italy Metal Fabrication Equipment Market
Construction Equipment
Bulldozer Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
CNC Machine Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
South Korea Aerial Work Platform (AWP) Rental Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Stamping Machines Market
Construction Equipment
Stud Welding Guns Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Fixed Crane Market