
 US Welding Consumables Market | 2026-2036
US Welding Consumables Market Size, Share, and Industry Trends Forecast 2026-2036
US Welding Consumables Market Intelligence
Buyer concentration among national construction firms and energy EPC contractors is hardening procurement standards for welding consumables. Lincoln Electric Holdings Inc. leverages its extensive distributor network to sustain channel control across maintenance workshops and metal fabricators. ESAB Corporation differentiates through specialized filler wire formulations for high-strength steel applications in heavy equipment fabrication. Hobart Brothers LLC anchors its position with strong brand recognition among independent welding supply houses serving repair services.
US welding consumables encompass electrodes, filler wires, fluxes, and cored wires engineered to specific AWS classifications with controlled chemical compositions and mechanical property requirements, serving primarily to join metallic components in structural and pressure-boundary applications. Solid wire products dominate volume in automated MIG welding cells at OEM manufacturers, while flux-cored wires capture margin pools in field construction where wind and position complexity demand all-position capability. Cored wires represent the fastest-growing form segment as infrastructure contractors adopt higher-deposition processes to address skilled labor constraints.
AWS certification requirements, OSHA hexavalent chromium exposure standards, and EPA air quality regulations collectively elevate demand for low-fume and manganese-reduced consumable formulations. The Department of Transportation's pipeline safety rules further tighten traceability and qualification documentation for energy sector welding materials. Stakeholders must monitor evolving EPA metal fabrication MACT standards and assess qualification investments against the pace of automated welding adoption in shipbuilding and aerospace manufacturing.
Market Dynamics
AWS D1.1 structural welding code revisions and OSHA hexavalent chromium exposure limits are tightening qualification requirements, forcing fabricators to retool consumable portfolios and retrain workforces at accelerated cadence.
Growth Catalysts
- Pipeline Infrastructure Expansion:Utilities across Texas and Louisiana are accelerating natural gas and renewable hydrogen pipeline construction, driving demand for high-strength steel consumables with full AWS traceability documentation.
- OSHA Workplace Exposure Limits:Tighter manganese fume standards are compelling maintenance workshops to convert from stick electrodes to low-fume flux-cored wire formulations, expanding premium product penetration.
- Automated MIG Adoption:OEM manufacturers in heavy equipment fabrication are deploying robotic welding cells at scale, concentrating volume demand for precision-engineered solid wire products with tight diameter tolerances.
Market Restraints
- Alloy Raw Material Volatility:Nickel and manganese price swings compress margin pools for consumable manufacturers, particularly affecting specialty formulations for high-strength low-alloy steel applications.
- Gulf Coast Supply Concentration:Fabrication yard clustering near Port Houston and Corpus Christi creates geographic demand vulnerability to hurricane disruption and port congestion events.
- AWS Qualification Friction:Extended welder re-certification timelines under revised D1.1 codes delay project staffing and extend contract completion cycles for structural steel contractors.
Strategic Opportunities
- Appalachian Shale Field Services:Midstream compressor station construction in Pennsylvania and Ohio offers underpenetrated demand for all-position flux-cored wires serving remote field welding conditions.
- EPA MACT Compliance Tailwinds:Pending air quality standards for metal fabrication facilities will mandate fume capture upgrades, accelerating conversion to low-emission consumable formulations with documented emission profiles.
- Digital Weld Traceability Convergence:Integration of consumable lot tracking with welding parameter monitoring systems creates premium positioning for suppliers offering blockchain-verified material certificates.
Industry Challenges
- Certified Welder Shortage:AWS qualification bottlenecks and aging workforce demographics constrain deployment velocity for infrastructure contractors facing compressed project timelines.
- Dual-Certification Complexity:Fabricators serving both structural and pressure-boundary applications must maintain parallel ASME Section IX and AWS D1.1 consumable inventories, elevating working capital requirements.
- Legacy Equipment Retrofit Costs:Transition from SMAW to FCAW processes in field construction requires power source upgrades and shielding gas logistics that strain smaller independent welding contractor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Welding Consumables Market |
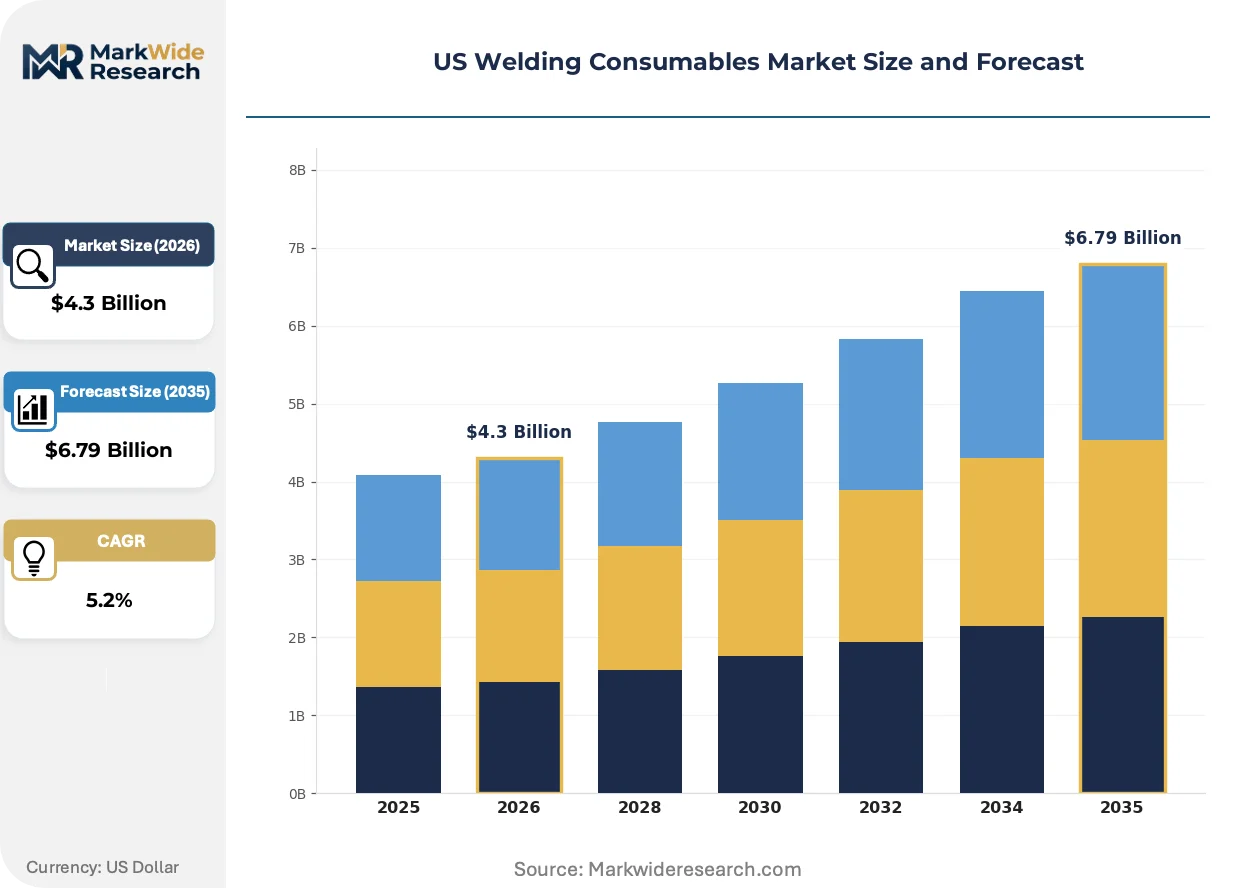
| Market Size in 2026 | $4.3 Billion |
| Market Size in 2035 | $6.79 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrodes, Filler Wires, Fluxes, Cored Wires, Brazing Alloys Application: Shipbuilding, Infrastructure, Aerospace Manufacturing, Heavy Equipment Fabrication, Energy Sector End User: Metal Fabricators, Maintenance Workshops, Construction Firms, OEM Manufacturers, Repair Services Form: Solid, Flux-Coated, Tubular, Powder, Wire Spools |
| Companies Covered | voestalpine Böhler Welding USA, Colfax Corporation, Lincoln Electric Holdings Inc., Hobart Brothers LLC, Miller Electric, ESAB Corporation, Kobe Steel Ltd., Arcos, Illinois Tool Works Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Welding Consumables Market Strategic Shifts & Innovations
Metal-cored wire formulations and digital weld monitoring systems are actively displacing conventional processes, while regulatory pressure on fume emissions accelerates formulation chemistry shifts across the US fabrication base.
Metal-cored wire technology combines the deposition efficiency of solid wire with the all-position capability of flux-cored products, delivering higher travel speeds in automated cells. Heavy equipment OEMs in the Midwest are adopting these formulations at accelerated pace to offset skilled labor constraints. This technology is rewriting competitive positioning in high-volume structural fabrication by compressing cycle times and reducing rework rates.
EPA metal fabrication MACT standards are tightening volatile organic compound and particulate emission thresholds for welding operations. The regulatory consequence is a forced migration toward low-fume consumable formulations and enhanced local exhaust ventilation systems. Gulf Coast petrochemical fabricators face the steepest compliance timelines, driving accelerated procurement of manganese-reduced electrode products.
Integrated supply contracts are consolidating procurement authority among national construction firms and energy EPC contractors, displacing traditional distributor relationships. Independent welding supply houses serving repair services are losing share to direct manufacturer agreements with volume-backed pricing structures. This concentration is most visible in Texas and Louisiana, where pipeline construction contractors are centralizing consumable specification authority at the corporate engineering level.
US Welding Consumables Market Segmentation
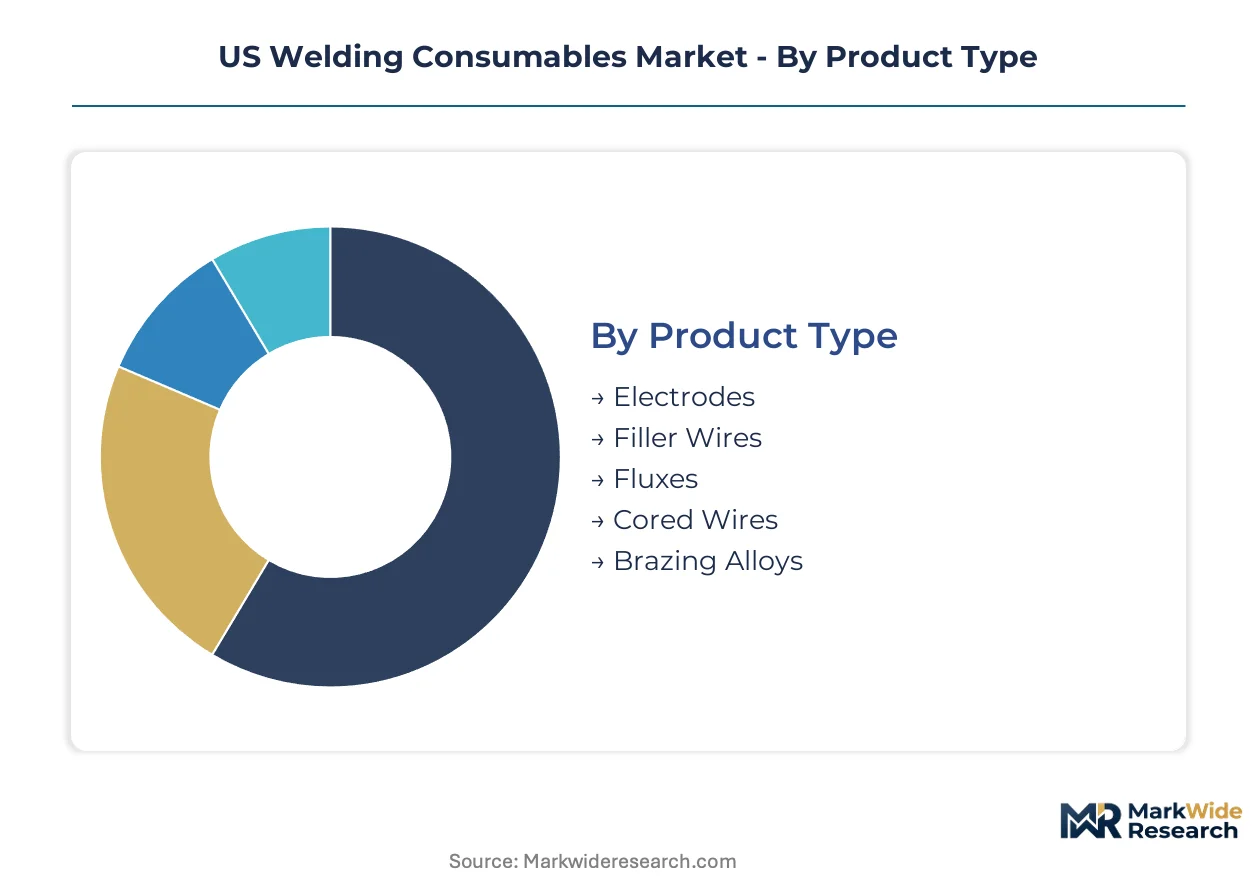
Welding consumables segmentation reveals divergent margin structures across product chemistry and deployment context. Formulation requirements shift dramatically between automated OEM cells and field construction environments. Understanding these splits enables targeted portfolio positioning against distinct qualification burdens and price sensitivity profiles.
Product Type:
Solid wire commands volume leadership in automated settings while flux-cored and metal-cored formulations capture premium pools in position-critical fieldwork.
- Electrodes:SMAW stick electrodes remain indispensable for maintenance workshops and remote pipeline repair where shielding gas logistics prove impractical. Demand concentrates in Texas Gulf Coast petrochemical corridors where wind exposure and outdoor positioning favor all-position rutile and basic-coated formulations.
- Cored Wires:Tubular wire products combine high deposition rates with out-of-position capability, gaining share fastest among infrastructure contractors facing skilled welder shortages. Metal-cored variants specifically are displacing solid wire in heavy equipment robotic cells seeking faster travel speeds.
- Filler Wires:Precision-drawn solid products serve TIG and robotic MIG applications with tight AWS chemistry specifications for aerospace and pressure-boundary welding.
- Fluxes:Submerged arc welding fluxes support high-deposition pipeline girth welding and structural beam fabrication in energy sector construction.
- Brazing Alloys:Silver and copper-phosphorus formulations serve HVAC and refrigeration system joining where base metal properties must be preserved.
Mature deployment sits with electrodes. Newer deployment is concentrated in cored wires.
Application:
Energy infrastructure and heavy equipment fabrication anchor volume demand while aerospace and shipbuilding impose the steepest qualification barriers.
- Energy Sector:Pipeline construction across Texas and Louisiana drives specification-grade consumable procurement with full AWS traceability documentation. Compressor station and renewable hydrogen infrastructure projects are accelerating demand for high-strength low-alloy steel formulations.
- Heavy Equipment Fabrication:Midwest OEM manufacturers deploy robotic MIG cells at scale, concentrating demand for precision solid wire with tight diameter tolerances and consistent cast helix characteristics.
- Shipbuilding:Naval and commercial vessel construction in Gulf Coast and Virginia yards requires dual-certified consumables meeting both AWS D1.1 and military specifications.
- Infrastructure:Bridge and building construction favors flux-cored wire for field welding flexibility, with DOT structural codes mandating specific toughness grades.
- Aerospace Manufacturing:Titanium and nickel-alloy welding for airframe and engine components demands vacuum-melted filler materials with extensive lot certification.
Volume concentration rests with energy sector applications. Margin expansion is steepest in aerospace manufacturing.
End User:
Procurement authority is hardening among national construction firms while independent repair services retain price sensitivity and brand loyalty patterns.
- Construction Firms:National EPC contractors centralize consumable specification at corporate engineering levels, displacing traditional distributor relationships with direct manufacturer agreements.
- OEM Manufacturers:Heavy equipment producers integrate consumable procurement into robotic welding cell deployments, prioritizing diameter consistency and feedability over unit cost.
- Metal Fabricators:Job shops serving mixed structural and pressure-boundary applications maintain parallel AWS and ASME Section IX consumable inventories.
- Maintenance Workshops:OSHA manganese fume compliance is driving conversion from stick electrodes to low-fume flux-cored formulations among independent repair facilities.
- Repair Services:Independent welding supply houses anchor brand recognition for Hobart Brothers and similar legacy names in aftermarket stick electrode demand.
Contract consolidation is reshaping construction firm procurement. Workshop compliance pressures are accelerating maintenance sector product mix shifts.
Form:
Physical delivery format determines automation compatibility, deposition efficiency, and field logistics burden across deployment environments.
- Solid:Precision-drawn wire on precision-layered spools serves robotic MIG applications where consistent feed and arc stability determine cycle time.
- Tubular:Cored wire construction enables all-position welding with self-shielding or gas-shielded variants, dominating field construction where wind and access constraints apply.
- Flux-Coated:Stick electrode form factor persists in maintenance and repair where equipment portability outweighs deposition rate considerations.
- Powder:Metal powder feedstocks support laser cladding and additive repair applications in aerospace and tool remanufacturing.
- Wire Spools:Standardized packaging formats range from 1 lb hobby spools to 1000 lb bulk drums for high-volume automated cells.
Established form factors dominate solid and flux-coated segments. Tubular configurations are climbing fastest in infrastructure deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along the Texas Gulf Coast petrochemical corridor, where fabrication yards cluster near Port Houston and Corpus Christi. OSHA workplace exposure limits and AWS D1.1 structural welding code revisions are tightening qualification requirements across all major production zones. Regional differentiation stems from proximity to energy infrastructure, automated manufacturing density, and compliance timeline acceleration.
Texas Gulf Coast
Natural gas and renewable hydrogen pipeline construction drives specification-grade consumable procurement with full AWS traceability documentation. EPA air quality regulations for metal fabrication facilities mandate fume capture upgrades, accelerating conversion to low-emission formulations. Fabrication yards near Port Houston and Corpus Christi anchor national volume demand for high-strength low-alloy steel consumables.
Appalachian Basin
Midstream compressor station construction in Pennsylvania and Ohio generates underpenetrated demand for all-position flux-cored wires serving remote field welding conditions. Department of Transportation pipeline safety rules tighten traceability and qualification documentation for energy sector welding materials. Field welding crews in the Marcellus and Utica shale regions face extended re-certification timelines under revised D1.1 codes.
Midwest Manufacturing Belt
Heavy equipment OEMs in Michigan, Ohio, and Illinois deploy robotic MIG cells at scale, concentrating demand for precision-engineered solid wire with tight diameter tolerances. OSHA hexavalent chromium exposure limits compel maintenance workshops to convert from stick electrodes to low-fume flux-cored wire formulations. Automated welding adoption in Detroit-area automotive supplier parks compresses cycle times and reduces rework rates.
Southeast Shipbuilding Corridor
Naval and commercial vessel construction in Virginia and Mississippi yards requires dual-certified consumables meeting both AWS D1.1 and military specifications. EPA metal fabrication MACT standards tighten volatile organic compound and particulate emission thresholds for welding operations. Newport News and Pascagoula fabrication facilities face accelerated procurement timelines for manganese-reduced electrode products.
California Industrial Coast
Aerospace manufacturing in Los Angeles and San Diego counties demands vacuum-melted filler materials with extensive lot certification for titanium and nickel-alloy welding. California Air Resources Board regulations exceed federal EPA thresholds for welding fume emissions, forcing earlier adoption of low-fume consumable formulations. Precision fabrication clusters in El Segundo and Torrance prioritize feedability consistency over unit cost in robotic cell deployments.
US Welding Consumables Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized high-strength formulations and digital traceability services. The vendor base stratifies across three archetypes: diversified industrial conglomerates with captive welding divisions, pure-play consumable specialists with deep AWS certification expertise, and regional distributors leveraging local fabrication relationships. Competitive intensity centers on qualification documentation capabilities and automated cell feedability performance. Consolidation pressure is mounting as national EPC contractors centralize procurement authority at corporate engineering levels.
Among US-based industrial conglomerates, Lincoln Electric Holdings Inc. and Illinois Tool Works Inc. exemplify scale-driven archetypes with extensive distributor networks sustaining channel control. ESAB Corporation and voestalpine Böhler Welding USA represent specialized formulation expertise anchored in premium high-strength steel applications. Hobart Brothers LLC and Miller Electric occupy positions within the independent welding supply house ecosystem, where brand recognition among repair services creates defensive moats against direct manufacturer agreements.
| Leading Market Players |
|---|
| voestalpine Böhler Welding USA |
| Colfax Corporation |
| Lincoln Electric Holdings Inc. |
| Hobart Brothers LLC |
| Miller Electric |
| ESAB Corporation |
| Kobe Steel Ltd. |
| Arcos |
| Illinois Tool Works Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap consumable specialists anchor supply discipline across the US fabrication base, translating AWS certification investments into pricing power that resists commodity erosion. Their concentrated ownership structures enable long-term formulation R&D without quarterly margin pressure, while captive relationships with Gulf Coast fabrication yards sustain premium positioning against distributor competition.
Pricing Analysis
Volume-mass solid wire products trade on thin margins through automated OEM channels, while flux-cored and metal-cored formulations command premium pools in field construction where AWS qualification documentation adds service value. Price differentiation hinges on certification grade—dual ASME Section IX and AWS D1.1 qualified consumables extract 15-30% premiums over structural-only grades—and volume scale, with national EPC contractors negotiating direct manufacturer agreements that displace distributor markups. Cost compression in standard electrode tiers is intensifying because nickel and manganese alloy volatility squeezes specialty formulation margins, though low-fume premium lines retain pricing resilience. Independent welding supply houses serving repair services exhibit highest price sensitivity, while aerospace and nuclear-certified buyers prioritize lot traceability over unit cost.
Supply Chain Analysis
AWS D1.1 and ASME Section IX qualification gating restricts viable supply sources to a narrow tier of domestic producers with documented WPS/PQR libraries, effectively filtering out unqualified imports regardless of cost advantage. Raw material supply draws from nickel mining operations in Indonesia and the Philippines, manganese ore processing in South Africa and Gabon, and domestic steel rod drawing capacity concentrated in Ohio and Pennsylvania. Single-source vulnerability sits with specialty alloy master batches for high-strength low-alloy steel formulations, where qualified secondary suppliers require 18-24 month certification cycles. Distribution runs through three channels: direct manufacturer agreements with national EPC contractors, authorized distributor networks serving independent fabricators, and welding supply houses anchoring aftermarket repair demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US welding consumables sector sits in a technology-transition phase as metal-cored wire formulations displace solid wire in robotic cells and low-fume chemistry shifts displace legacy electrodes under EPA compliance pressure.
For Market Incumbents: Anchor channel control through backward integration into precision wire drawing and AWS-certified filler metal production, defending against distributor disintermediation by national EPC contractors. Prioritize R&D investment in manganese-reduced formulations ahead of OSHA enforcement acceleration, while consolidating distributor relationships in Texas Gulf Coast petrochemical corridors where fabrication yard clustering creates captive demand pools. For New Entrants and Emerging Players: Independent welding supply houses in the Appalachian Basin represent the most penetrable channel partner type, offering localized relationships that national manufacturers have neglected in favor of direct EPC agreements. Target midstream compressor station construction in Pennsylvania and Ohio with all-position flux-cored wire formulations priced below Lincoln Electric and ESAB premiums, leveraging digital lot traceability as a service differentiator against legacy distributor inventories. For Investors and Strategic Acquirers: Distressed-cycle entries favor AWS-certified specialty alloy formulators with stranded WPS libraries in the Midwest Manufacturing Belt, where aging owner-operators face succession gaps without qualified management continuity. Long-term viability hinges on automation exposure—suppliers with robotic cell feedability expertise will outgrow field-construction-dependent peers. Watch EPA MACT standard finalization as the inflection signal triggering accelerated low-fume conversion capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Drawing | Captures margin pools from steel rod to finished spool while tightening AWS chemistry control. |
| Low-Fume Formulation R&D Investment | Positions suppliers ahead of EPA MACT compliance deadlines in Gulf Coast fabrication yards. |
| Digital Weld Traceability Platform | Integrates consumable lot tracking with robotic parameter monitoring for EPC contract differentiation. |
| Appalachian Basin Channel Partnership | Secures underpenetrated midstream construction demand before national competitors redirect focus. |
| Dual Certification Inventory Expansion | Captures parallel AWS D1.1 and ASME Section IX demand from mixed-application fabricators. |
Research Approach
Document review covered AWS certification databases, EPA regulatory dockets, and DOT pipeline safety filings, complemented by interviews with welding engineers at Gulf Coast fabrication yards, procurement directors at national EPC contractors, technical sales managers at distributor networks, and compliance officers at OSHA-regulated maintenance workshops. Secondary validation drew from SEC 10-K filings of Lincoln Electric and Illinois Tool Works, American Welding Society technical committee minutes, and Bureau of Labor Statistics welding occupation data. Bottom-up demand modeling triangulated against top-down energy infrastructure capex projections.
Historical shipment data cross-referenced against primary panel input from consumable manufacturers and distributor inventory managers shaped the analytical framework across the analysis window. Segmentation dimensions modeled included product chemistry tier, automation deployment context, end-use industry vertical, and regional regulatory compliance cluster. CAGRs derived from regression analysis of energy infrastructure investment cycles and robotic welding adoption curves in heavy equipment manufacturing, with sensitivity testing against nickel price volatility scenarios and AWS code revision implementation timelines.
Caveats apply where EPA MACT standard finalization, OSHA manganese exposure limit enforcement acceleration, or hurricane disruption to Gulf Coast fabrication yards could materially shift the outlook. Forecasts reflect assumptions about pipeline construction permitting velocity and robotic welding cell deployment rates in Midwest OEM facilities. A model refresh is warranted upon material change in AWS D1.1 code revision implementation schedules or Department of Transportation traceability documentation requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
LAMEA Water Pump Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Global Industrial Parts Washer Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Piling Machine Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
Construction Helmet Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Hydraulic Cylinders Market
Construction Equipment
Boom Lifts Market
Construction Equipment
Rubber Track Pads for Construction Machinery Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market
Construction Equipment
North America Construction Equipment Rental Market
Construction Equipment
North America Construction Equipment Market