
 US HVAC Field Device Market | 2026-2036
US HVAC Field Device Market Size, Share, and Industry Trends Forecast 2026-2036
US HVAC Field Device Market Insights
Domestic sensor foundries in Arizona and Texas are rebalancing capacity toward HVAC-grade temperature and pressure transducers after years of automotive allocation. Honeywell International Inc. leverages its distributed sensing architecture to capture retrofit contracts across federal building portfolios. Johnson Controls International PLC anchors its position through captive production of BACnet-native actuators. Siemens AG competes on integrated Desigo platform deployments that bundle field hardware with cloud analytics.
US HVAC field devices encompass thermostats, sensors, actuators, and valves that translate environmental conditions into control signals for heating, ventilation, and air conditioning systems, typically operating across 24VAC power loops with 0-10V or 4-20mA signal outputs to manage airflow, temperature, and refrigerant distribution in commercial and residential envelopes. Wired device installations still dominate existing building stock, though wireless and smart segments are capturing the fastest growth as IoT-enabled commissioning reduces labor cost in multi-zone retrofits. Contractors remain the largest end-user channel, but OEMs command superior margin pools through specification control in new construction.
EPA enforcement of the AIM Act HFC phasedown, DOE appliance efficiency standards, and ASHRAE 90.1 code adoptions across state jurisdictions are collectively forcing device replacement cycles and refrigerant-compatible material specifications. OSHA indoor air quality guidance post-pandemic has amplified demand for CO2 and particulate sensors in commercial mechanical systems. Stakeholders must monitor state-level stretch code adoptions that exceed federal baselines, as these jurisdictions will dictate the pace of smart device penetration and wireless protocol standardization.
Market Dynamics
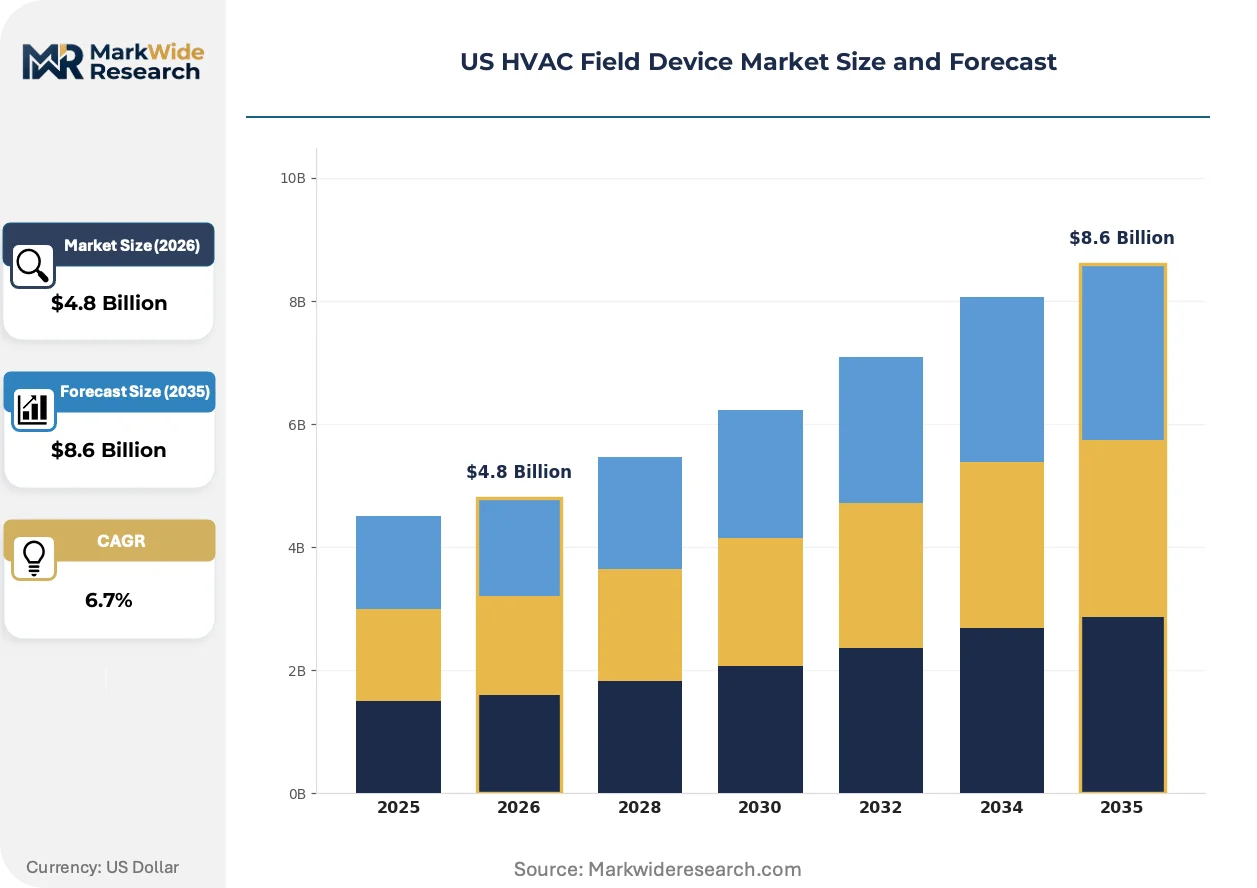
EPA enforcement of the AIM Act HFC phasedown is compressing replacement cycles across installed commercial building stock, forcing simultaneous upgrades to sensors, actuators, and refrigerant-compatible valves that were previously decoupled purchases.
Growth Catalysts
- Data center cooling retrofits:Hyperscale facilities across Texas and Virginia are accelerating procurement of pressure transducers and smart actuators for precision thermal management.
- OSHA indoor air quality guidance:Post-pandemic mandates for CO2 and particulate monitoring in commercial mechanical systems are expanding sensor deployment density per square foot.
- Sun Belt commercial construction:Office and mixed-use development across Arizona, Florida, and Georgia is driving specification of BACnet-native field devices in new mechanical systems.
Market Restraints
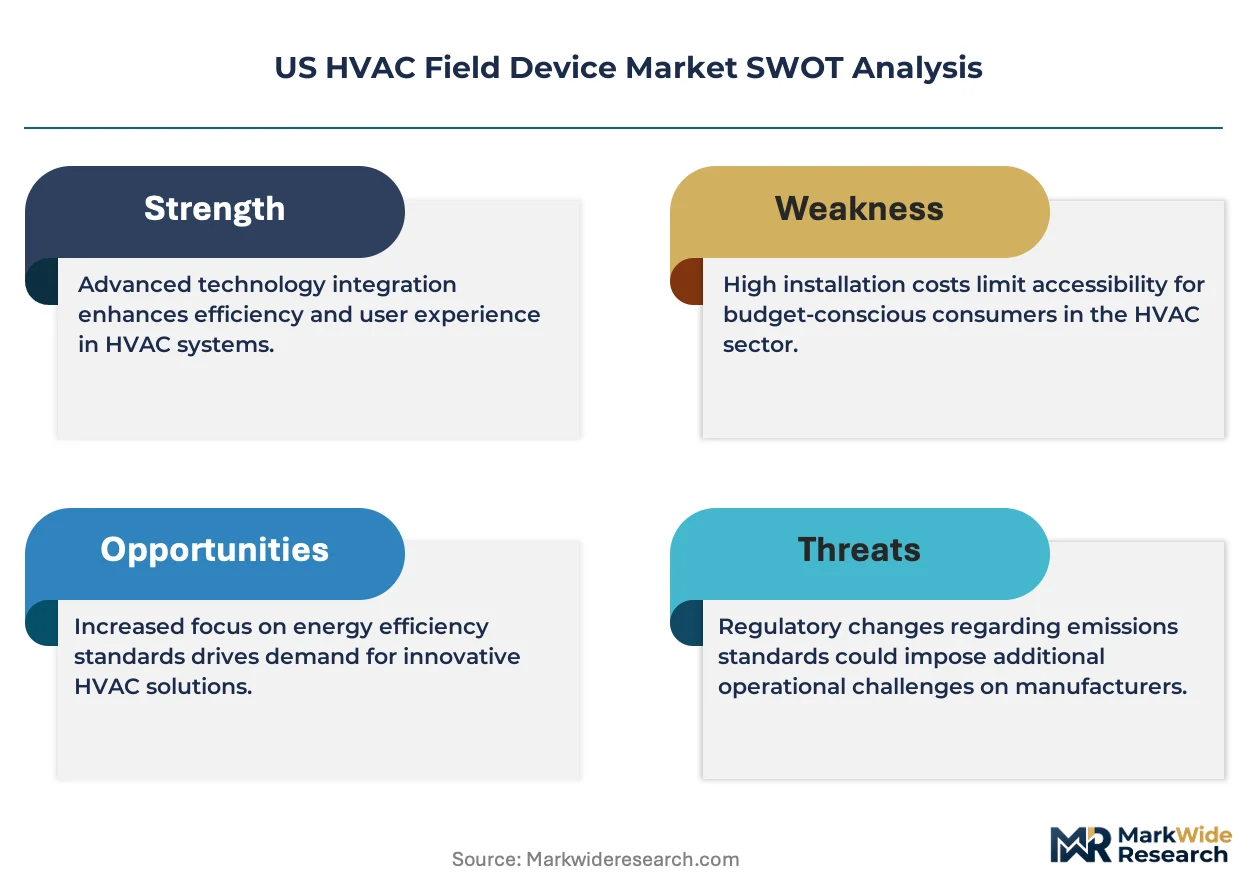
- Copper and semiconductor input volatility:HVAC-grade temperature sensors and actuator motor windings face margin pressure from commodity price swings in raw materials.
- Domestic foundry concentration:Arizona and Texas sensor fabrication capacity remains tight after automotive allocation shifts, creating lead time risk for volume contractors.
- Wireless protocol fragmentation:Competing standards between BACnet/IP, LoRaWAN, and proprietary mesh networks delay commissioning and raise integration costs for multi-vendor retrofits.
Strategic Opportunities
- Smart building integration:Convergence of edge computing with 0-10V/4-20mA signal loops enables predictive maintenance contracts that bundle hardware with analytics subscriptions.
- Federal building portfolio electrification:GSA energy performance contracts create concentrated demand for sensor-actuator packages compatible with heat pump retrofits.
- Wireless commissioning in multi-zone retrofits:Battery-powered sensors reduce labor hours in existing commercial stock where wired infrastructure replacement is cost-prohibitive.
Industry Challenges
- Controls technician shortage:Qualified commissioning engineers for BACnet and Modbus integration are scarce relative to retrofit project volume, extending project timelines.
- Dual refrigerant compatibility testing:Device manufacturers must validate seals, elastomers, and lubricant compatibility across R-410A, R-32, and emerging A2L blends simultaneously.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US HVAC Field Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Thermostats, Sensors, Actuators, Valves Application: Residential, Commercial, Industrial, Agricultural Technology: Wired, Wireless, Smart, Analog End User: Contractors, OEMs, Distributors, Maintenance Providers |
| Companies Covered | Siemens AG, Honeywell International Inc., Johnson Controls International PLC, Schneider Electric, Robert Bosch GmbH, KMC Controls, Belimo, Trane Technologies, Emerson Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US HVAC Field Device Market Trends and Innovations
Digital twin architectures are reshaping how field devices generate value, transforming standalone sensors and actuators into continuous data streams that feed cloud-based building optimization platforms.
Edge-enabled pressure and temperature transducers are integrating local analytics that preprocess signal data before transmission to building management systems. Data center operators in Northern Virginia are deploying these devices at scale to reduce bandwidth load and enable sub-second thermal response. This distributed intelligence is integrating predictive algorithms directly into device firmware, compressing the traditional separation between field hardware and software analytics layers.
EPA's phasedown schedule for hydrofluorocarbon refrigerants under the AIM Act is mandating material specification changes across valve and seal portfolios. Equipment manufacturers must recertify devices for lower-GWP alternatives including R-32 and A2L blends with modified flame propagation testing. The commercial retrofit segment bears the highest compliance burden, as legacy R-410A systems require complete actuator and sensor replacement rather than drop-in refrigerant swaps.
Mechanical contractors are consolidating vendor relationships to reduce specification complexity across multi-site portfolios. National service firms are displacing fragmented local distributors by negotiating direct procurement agreements with sensor and actuator manufacturers. This channel compression is most visible in the Sun Belt, where volume-driven contractors serving federal and commercial office clients prioritize single-source accountability over product variety.
US HVAC Field Device Market Segmentation
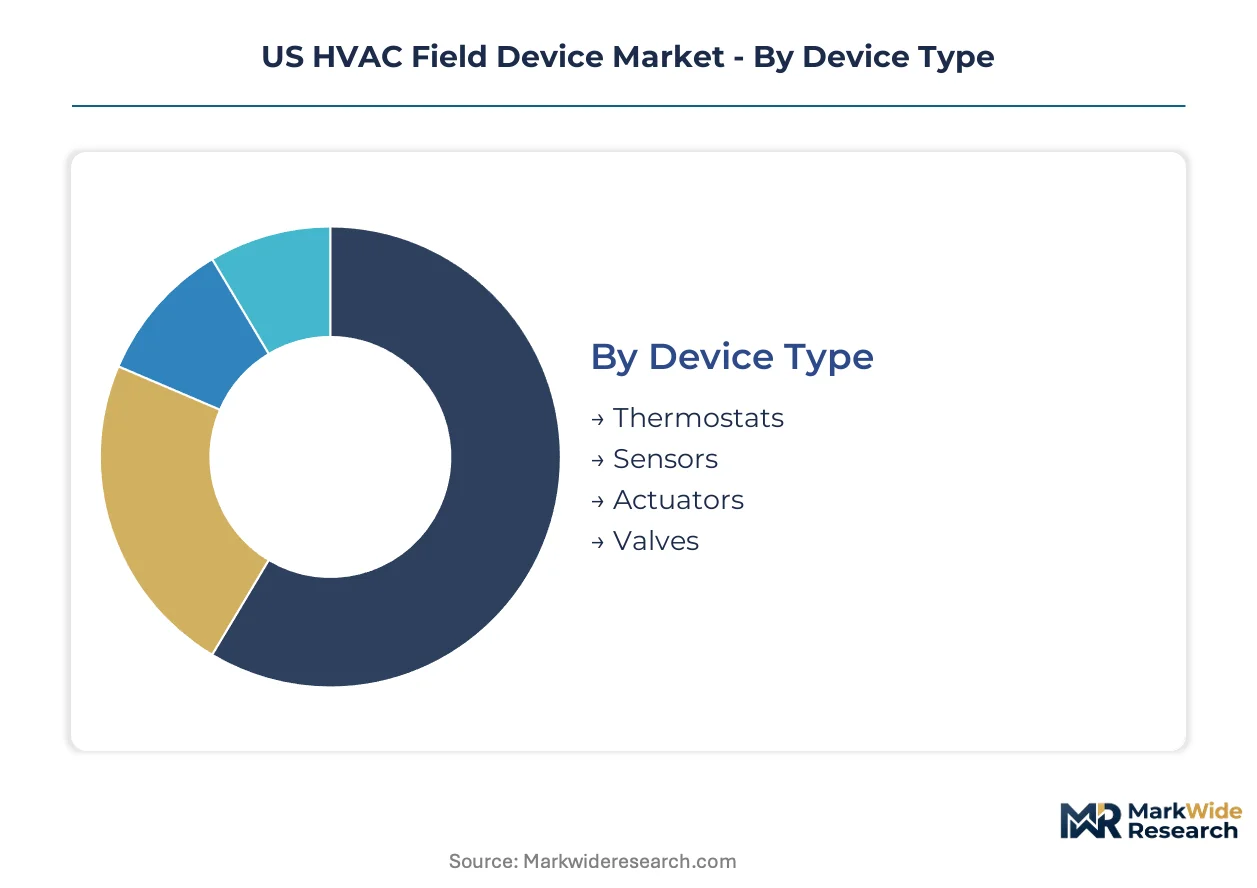
Device replacement cycles across the US commercial building stock create divergent demand profiles by segment. The EPA's HFC phasedown compresses upgrade timelines, forcing simultaneous procurement across multiple categories that previously decoupled.
Device Type:
Replacement cycles for refrigerant-compatible hardware are shortening as building operators confront simultaneous system upgrades.
- Sensors:Temperature, pressure, and CO2 transducers translate environmental conditions into 0-10V or 4-20mA control signals. Data center cooling retrofits across Texas and Virginia are accelerating procurement of precision-grade pressure sensors for thermal management.
- Actuators:Motor-driven damper and valve positioners regulate airflow and refrigerant distribution through 24VAC power loops. Federal building portfolio electrification is concentrating demand for BACnet-native actuators compatible with heat pump retrofits.
- Thermostats:Wall-mounted temperature controllers with programmable setpoint logic for residential and light commercial zones.
- Valves:Refrigerant and hydronic flow control devices with elastomer seals requiring recertification for R-32 and A2L blend compatibility.
Volume placements concentrate in Sensors; the faster expansion belongs to Actuators.
Application:
Cost tier differentiation separates specification-grade commercial deployments from price-sensitive residential volumes.
- Commercial:Office buildings, retail centers, and hospitality properties specify BACnet-integrated field devices with cloud analytics connectivity. Sun Belt states—Arizona, Florida, Georgia—drive new construction specification of native digital control hardware.
- Industrial:Manufacturing facilities and process cooling applications demand heavy-duty actuators and corrosion-resistant sensors for harsh environments.
- Residential:Single-family and multi-family dwellings prioritize cost-optimized thermostats and basic temperature sensors with limited interoperability.
- Agricultural:Greenhouse and livestock ventilation systems require humidity-resistant sensors with extended calibration intervals.
Commercial applications absorb the dominant share of value; Industrial is climbing the fastest on process automation requirements.
Technology:
Wireless protocol adoption is reshaping labor economics in multi-zone retrofit scenarios where wired infrastructure replacement proves cost-prohibitive.
- Smart:IoT-enabled devices with edge computing, predictive firmware, and cloud analytics integration. Data center operators in Northern Virginia deploy these at scale for sub-second thermal response with reduced bandwidth load.
- Wireless:Battery-powered sensors and actuators using LoRaWAN or proprietary mesh networks. Post-pandemic OSHA indoor air quality mandates are expanding deployment density per square foot in existing commercial mechanical systems.
- Wired:Traditional 24VAC power loops with 0-10V or 4-20mA signal outputs dominating existing building stock.
- Analog:Basic electromechanical devices without digital communication protocols, concentrated in legacy residential and small commercial systems.
Wired technology retains the installed base dominance; Smart is gaining share fastest on predictive maintenance bundling.
End User:
Channel structure is compressing as national service firms displace fragmented local distributors through direct procurement agreements.
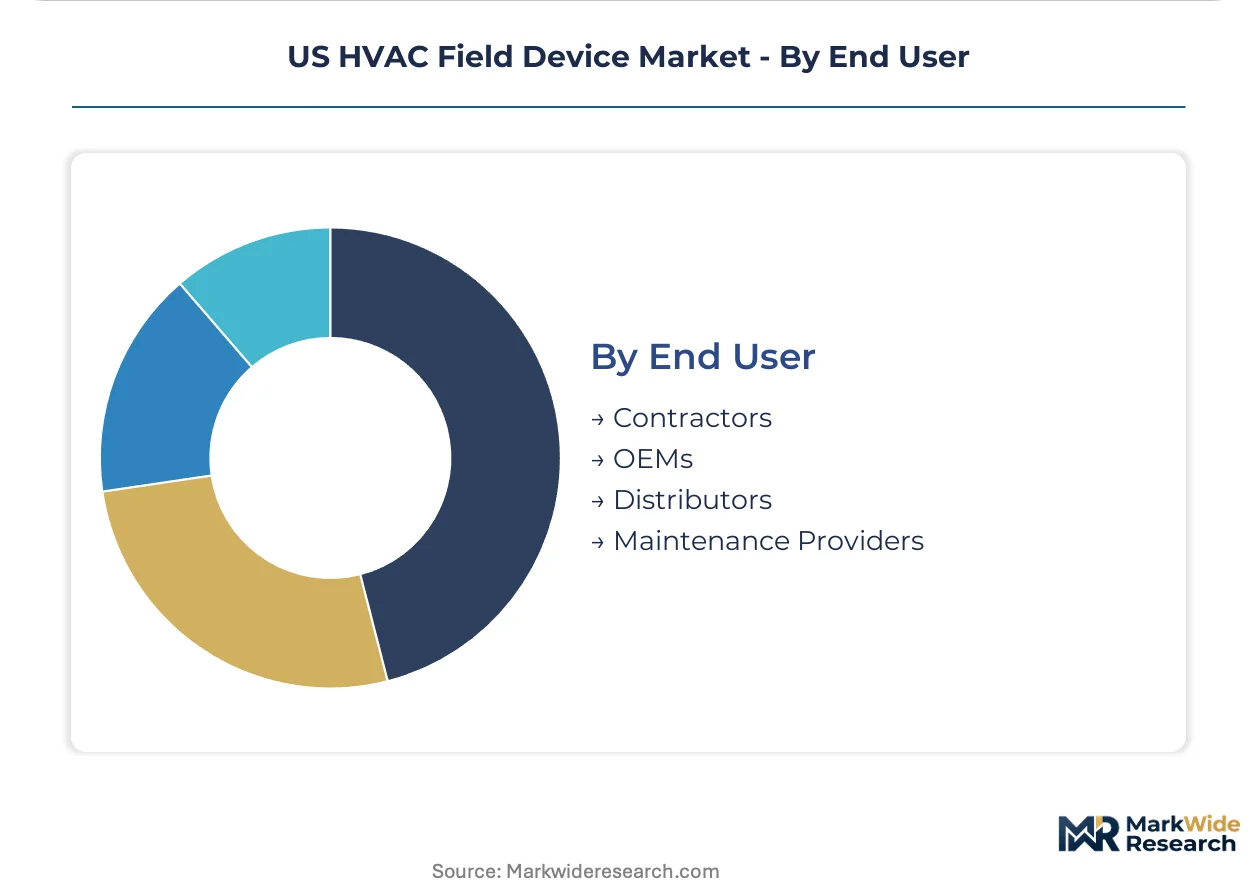
- Contractors:Mechanical installation and retrofit firms serving commercial and residential building owners. The Sun Belt contractor base is consolidating vendor relationships to reduce specification complexity across multi-site federal and office portfolios.
- OEMs:Original equipment manufacturers integrating field devices into packaged HVAC systems for new construction. OEMs command superior margin pools through specification control in new mechanical system builds.
- Distributors:Wholesale channels supplying fragmented local contractors with multi-brand product availability.
- Maintenance Providers:Service firms executing predictive maintenance contracts with hardware-analytics subscription bundling.
Contractor channel volumes lead; Maintenance Providers are expanding most quickly on outcome-based service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper mining districts in Arizona anchor domestic sensor fabrication capacity, while semiconductor foundries in Texas reallocate wafer output toward HVAC-grade transducers after years of automotive prioritization.
Texas
Hyperscale data centers in Dallas-Fort Worth and Austin drive precision pressure transducer procurement for thermal management systems. The state's environmental regulator enforces ASHRAE 90.1 stretch codes exceeding federal baselines. Houston's petrochemical corridor repurposes process instrumentation expertise toward commercial HVAC sensor production.
Virginia
Northern Virginia's data center cluster demands edge-enabled temperature sensors with sub-second response latency for cooling optimization. The Virginia Department of Environmental Quality implements EPA AIM Act compliance timelines for commercial building retrofits. Loudoun County hosts the densest concentration of mission-critical cooling infrastructure in North America.
Arizona
Phoenix-area sensor foundries rebalance capacity toward HVAC temperature and pressure transducers as automotive demand moderates. The Arizona Department of Health Services enforces indoor air quality monitoring mandates in public buildings. Tucson's precision manufacturing base supplies calibration services for commercial-grade sensing equipment.
Georgia
Atlanta's commercial office construction pipeline specifies BACnet-native actuators for new mechanical systems. The Georgia Environmental Protection Division enforces refrigerant management protocols under federal AIM Act delegation. Savannah's port logistics support import distribution of European valve and actuator components.
Florida
Miami-Dade and Orlando metropolitan areas drive humidity-resistant sensor deployment in hospitality and healthcare facilities. The Florida Building Commission adopts enhanced efficiency standards for commercial envelope systems. Tampa's contractor consolidation trend favors direct procurement agreements with national sensor manufacturers over fragmented distribution.
US HVAC Field Device Market Competitive Landscape
Global majors compete with regional champions across specification control and retrofit service bundling. The market structure concentrates around diversified industrial conglomerates with captive building automation platforms, while mid-tier specialists defend position through refrigerant compatibility certification and wireless protocol expertise. Three archetypes dominate: integrated platform providers, component specialists with foundry control, and national service firms with specification influence. Competitive moves center on backward integration into sensor fabrication and exclusive procurement agreements with consolidating mechanical contractors.
Among diversified industrial conglomerates, Siemens AG, Honeywell International Inc., and Johnson Controls International PLC exemplify the platform-integrated archetype. Siemens occupies a position defined by cloud-analytics bundling. Honeywell exemplifies distributed sensing architecture deployment across federal building portfolios. Johnson Controls anchors the BACnet-native actuator segment through captive production capabilities. These three represent divergent strategic postures within the same consolidated tier.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| Johnson Controls International PLC |
| Schneider Electric |
| Robert Bosch GmbH |
| KMC Controls |
| Belimo |
| Trane Technologies |
| Emerson Electric |
| Others |
Pricing and Supply Chain Analysis
Copper pricing volatility in Arizona and Texas sensor foundries cascades through three distinct hardware tiers, compressing margins on economy-grade temperature transducers while premium BACnet-native actuators absorb cost shocks through predictive maintenance bundling.
Pricing Analysis
Warranty and calibration service bundling separates premium sensor-actuator packages from unbundled transactional hardware. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade—UL-listed and ASHRAE-compliant devices command substantial premiums over uncertified alternatives. Cost compression in economy-grade wired sensors is intensifying because domestic foundry capacity remains tethered to automotive allocation shifts. Residential contractors exhibit the highest price sensitivity, while federal building portfolio managers prioritize specification compliance over unit economics.
Supply Chain Analysis
Domestic-content mandates under federal procurement rules are reshaping sourcing toward Arizona and Texas fabrication facilities. Copper windings, semiconductor wafers, and elastomer seal compounds draw from concentrated North American suppliers. Single-source vulnerability in HVAC-grade pressure transducer MEMS fabrication creates lead time exposure for volume contractors. Distribution runs through consolidating national service firms that negotiate direct procurement agreements, displacing fragmented local distributors across Sun Belt markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA's HFC phasedown enforcement is compressing weaker component manufacturers unable to fund simultaneous R-32 and A2L blend recertification, accelerating consolidation toward platform-integrated conglomerates.
For Market Incumbents: Anticipate refrigerant compatibility certification as the primary defensive moat. Johnson Controls International PLC and Honeywell International Inc. should deepen backward integration into Arizona sensor foundries to secure captive supply of HVAC-grade transducers. Channel control through exclusive procurement agreements with consolidating Sun Belt contractors represents the secondary lever against mid-tier specialists.
For New Entrants and Emerging Players: Agricultural greenhouse operators represent an underserved buyer archetype with humidity-resistant sensor requirements and extended calibration intervals. Wireless battery-powered CO2 sensors for livestock ventilation systems offer the most penetrable application segment. A direct-to-contractor go-to-market angle bypasses entrenched distributor relationships in Florida and Georgia.
For Investors and Strategic Acquirers: GSA energy performance contract awards are the leading indicator that federal building electrification demand is accelerating beyond supply response capacity. The five-to-ten-year viability window favors acquisition targets with captive BACnet-native actuator production and established refrigerant compatibility test labs. Monitor EPA enforcement actions against commercial retrofit non-compliance as the inflection signal for replacement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Fabrication | Arizona foundry acquisitions secure captive supply of HVAC-grade pressure transducers against automotive allocation competition. |
| Refrigerant Compatibility Certification Program | Dual R-32 and A2L blend validation opens federal building retrofit contracts under EPA AIM Act enforcement. |
| Predictive Maintenance Platform Launch | Edge-enabled firmware subscriptions bundle hardware with analytics, capturing recurring revenue from data center operators. |
| Wireless Protocol Standardization Partnership | LoRaWAN-BACnet convergence reduces commissioning friction for multi-zone commercial retrofits. |
| Channel Consolidation via Direct Procurement | National contractor agreements displace fragmented distribution, concentrating specification influence in Sun Belt markets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study. Primary interviews with HVAC controls technicians, federal GSA procurement officers, mechanical contractors, and sensor foundry operations managers combined with ASHRAE standard documentation, EPA enforcement databases, and DOE appliance efficiency filings. Bottom-up device shipment analysis and top-down building stock modeling enabled triangulation across independent estimation streams.
Data-stream reconciliation across sensor unit volumes, actuator replacement rates, and refrigerant system upgrade timelines shaped the analytical framework. Segmentation dimensions modeled include device type, application tier, technology protocol, and end-user channel structure across the projection horizon. CAGRs derived from historical replacement cycle analysis and regulatory compliance timeline acceleration, with specific inputs from data center cooling capex disclosures and federal building electrification contract awards.
Revisions become necessary when EPA phasedown enforcement intensity shifts, copper and semiconductor input costs destabilize, or wireless protocol standardization accelerates beyond modeled adoption curves. Forecasts reflect documented assumptions about regulatory timelines and foundry capacity reallocation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Strip Warmer Market
HVAC Equipment
Fabric Air Ducts Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
HVAC System Analyzer Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
Global Commercial Heat Pump Water Heater Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
Automatic Ducting Machine Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
HVAC Centrifugal Compressors Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Modular Refrigeration Unit Market