
 Earthmoving Equipment Tyres Market | 2026-2036
Earthmoving Equipment Tyres Market Size, Share, and Industry Trends Forecast 2026-2036
Earthmoving Equipment Tyres Market Analytics
Original equipment supply agreements is rewriting how earthmoving tyre manufacturers secure long-term volume commitments. Continental leverages its integrated rubber compounding facilities to control raw material quality from source to finished tread. Michelin sustains premium positioning through deep partnerships with European mining OEMs. Titan International anchors North American aftermarket demand through its extensive dealer network serving contractors and rental fleets.
Earthmoving equipment tyres are reinforced rubber structures engineered to withstand extreme load indices exceeding 100 tons per tyre while operating on abrasive, uneven terrain at low speeds under high torque. Radial construction dominates high-value mining applications due to superior heat dissipation and extended service intervals compared to bias-ply alternatives. The 29 inch and 35 inch size categories concentrate margin pools where specialized compounds command pricing premiums from large-scale extraction operators. Construction and mining applications lead volume absorption, while agriculture represents a smaller but steady replacement cycle segment.
FDA guidelines on aromatic extract oils in rubber manufacturing, EPA emissions standards for off-road equipment, and ISO 4250 dimensional specifications collectively shape product compliance thresholds for suppliers accessing regulated markets. China's GB standards and MIIT tyre labeling requirements add further certification layers for manufacturers serving state-procurement channels. Stakeholders must monitor how evolving carbon-border adjustments and embedded-emissions tracking reshape sourcing decisions across multinational supply networks.
Market Dynamics
Original equipment supply agreements are consolidating procurement power among mining OEMs, forcing tyre manufacturers to commit multi-year volume contracts with fixed pricing tiers and embedded service obligations.
Growth Catalysts
- Deepening ore extraction:Australian, Canadian, and Chilean mining companies are accelerating fleet renewals as open-pit operations transition to underground reserves, extending replacement cycles for ultra-class haul truck tyres.
- EU F-Gas Regulation:Stricter compliance thresholds on tyre composition are pushing manufacturers toward low-aromatic oil formulations, creating premium positioning for suppliers with certified compound portfolios.
- Radial construction technology:Superior heat dissipation and extended service intervals compared to bias-ply alternatives are capturing high-value mining applications where downtime costs exceed tyre replacement economics.
Market Restraints
- Natural rubber price volatility:Concentrated sourcing from Southeast Asian plantations exposes compounders to weather-driven supply shocks and currency fluctuation risks.
- Specialized curing press scarcity:Limited global manufacturing capacity for 63-inch and larger tyre molds constrains expansion plans for new market entrants.
- REACH compliance costs:Extended substance registration timelines and testing requirements for novel compound formulations delay product launches by 18-24 months.
Strategic Opportunities
- China's western mining provinces:State-backed infrastructure projects in Xinjiang and Inner Mongolia require heavy earthmoving capacity, creating procurement windows for suppliers with GB-standard certification.
- Sensor-embedded intelligent tyres:Integration of pressure and temperature monitoring systems enables predictive maintenance contracts and recurring revenue streams.
- Rental fleet aftermarket channels:North American equipment rental networks represent underserved replacement demand with consolidated purchasing authority and standardized specification requirements.
Industry Challenges
- Compounder chemist scarcity:Specialized expertise in abrasion-resistant tread formulations for high-silica ore environments commands premium compensation and limits R&D team scaling.
- ISO 4250 dimensional certification timelines:Extended validation protocols for new size categories delay commercialization and tie up engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Earthmoving Equipment Tyres Market |
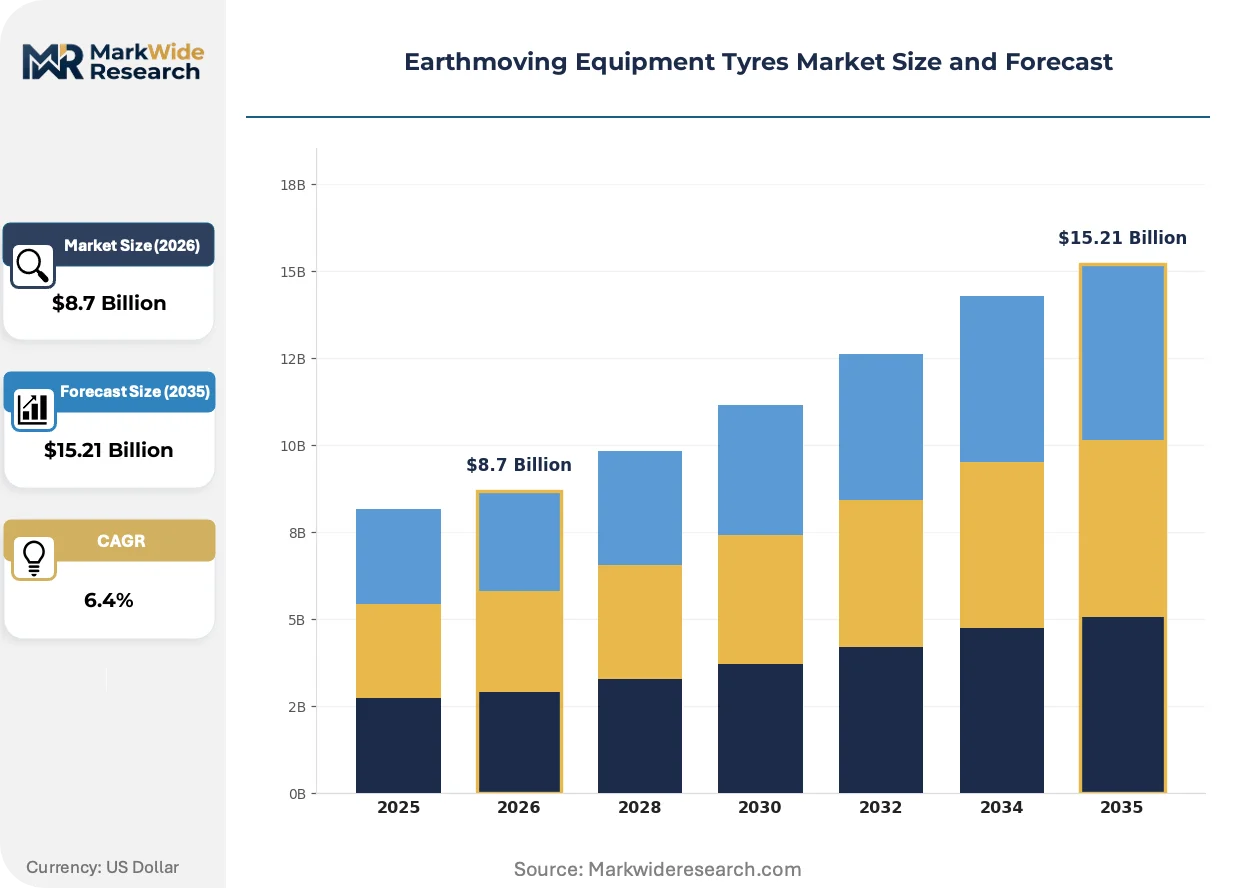
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial, Bias, Solid, Pneumatic Size: 23 inch, 25 inch, 29 inch, 35 inch Application: Construction, Mining, Agriculture, Demolition End User: Contractors, Rental Services, Mining Companies, Government |
| Companies Covered | Continental, Balkrishna Industries Limited (BKT), Michelin, Hankook Tire & Technology Group, Yokohama Rubber Company, Bridgestone, Sumitomo Rubber Industries, Titan International, Goodyear, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Earthmoving Equipment Tyres Market Evolving Landscape
Compound formulation science and embedded sensing systems are redefining how earthmoving tyres deliver value beyond basic load-bearing function, shifting competitive advantage toward data-enabled service integration.
Dual-layer tread compounds with variable hardness gradients are hybridizing traditional single-compound construction, allowing outer layers to resist cutting while base layers maintain structural integrity under cyclic loading. Large-scale copper and iron ore operators in Western Australia are specifying these configurations for haul routes exceeding 80 kilometers round-trip. The technology is hybridizing supplier business models toward guaranteed-cost-per-hour contracts that internalize wear-rate risk.
EU F-Gas Regulation phase-down schedules are accelerating substitution of aromatic process oils with bio-based alternatives derived from rapeseed and tall oil feedstocks. Compounders serving European mining OEMs must reformulate curing packages to maintain scorch safety and vulcanization kinetics. Underground hard-rock operations in Sweden and Finland are first-movers, specifying low-aromatic certification in procurement tenders.
Buying committees at diversified mining majors are consolidating tyre specifications across multiple mine sites, compressing supplier rosters from six-plus vendors to two or three strategic partners with global service networks. This concentration is displacing regional distributors who lack balance-sheet capacity for consignment inventory and field engineering support. The pattern is most visible among copper producers with cross-border operations spanning Chile, Peru, and the Democratic Republic of Congo.
Earthmoving Equipment Tyres Market Segmentation
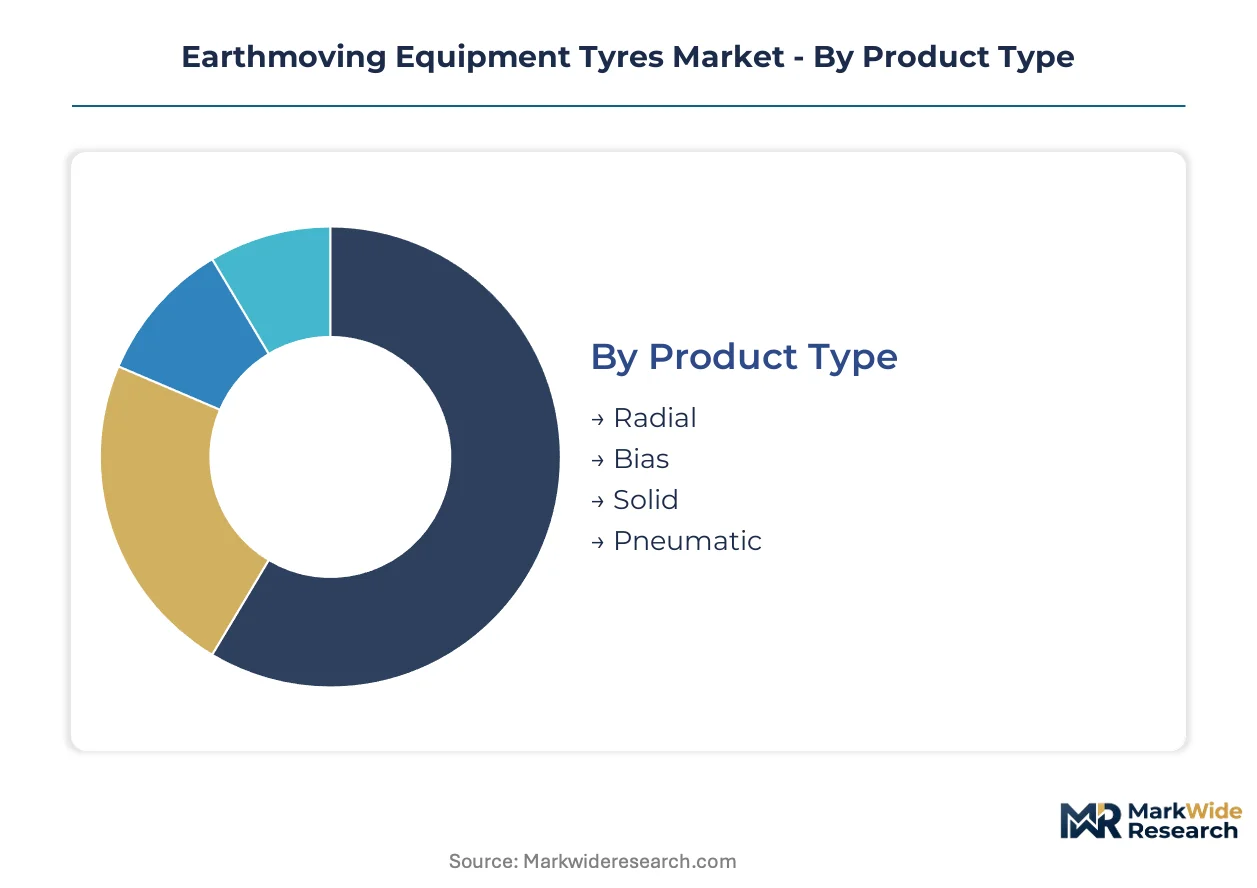
Earthmoving equipment tyres fragment across construction, mining, and agriculture applications where load indices, terrain abrasiveness, and duty cycles dictate specification requirements. Procurement committees at diversified mining majors now consolidate specifications across multiple sites, compressing supplier rosters and amplifying volume concentration within preferred segments.
Product Type:
Construction technology separates load-bearing capacity from heat management performance across four distinct architectures.
- Radial:Steel-belted carcass construction delivers superior heat dissipation and extended service intervals under cyclic loading. Australian iron ore operators in Western Australia's Pilbara region specify radial configurations for haul routes exceeding 80 kilometers, where downtime costs dwarf replacement economics. The technology commands premium positioning in high-value mining procurement tenders.
- Bias:Cross-ply nylon or polyester cord layers provide structural rigidity at lower acquisition cost for intermittent-duty construction fleets. Demand concentrates among North American rental services and municipal contractors where capital constraints outweigh lifecycle cost optimization. Bias construction retains share in emerging markets with limited service infrastructure.
- Solid:Rubber-filled cores eliminate puncture risk in demolition and scrap-handling environments with dispersed debris. Waste management contractors in Germany's industrial zones specify solid tyres for materials recovery facilities.
- Pneumatic:Air-cushioned designs balance ride quality and ground pressure distribution for mixed-surface agriculture and light construction. Brazilian soybean operations in Mato Grosso deploy pneumatic configurations during planting windows.
Radial commands the established base. The steepest expansion runs through solid configurations as demolition and recycling activity intensifies.
Size:
Dimensional categories align with equipment class hierarchies from compact loaders to ultra-class haul trucks.
- 23 inch:Compact wheel loader and skid-steer specifications serve urban construction and landscaping contractors. Municipal fleets in Toronto and Vancouver standardize 23-inch formats for snow removal and park maintenance equipment.
- 25 inch:Mid-size excavator and articulated dump truck applications bridge commercial construction and small-scale mining. Chilean copper operations in the Atacama deploy 25-inch tyres on support vehicles and light haulage.
- 29 inch:Specialized compounds for this size category concentrate margin pools where abrasion-resistant tread formulations command pricing premiums. Large-scale extraction operators in Western Australia's goldfields specify 29-inch configurations for underground haulage where heat buildup constraints favor radial construction with enhanced carcass durability.
- 35 inch:Ultra-class haul truck and large wheel loader specifications absorb the highest absolute dollar volumes per unit. Surface mining operations in Alberta's oil sands and Kazakhstan's coal basins require 35-inch tyres with load indices exceeding 100 tons per tyre.
35 inch captures the revenue concentration. The steepest expansion trajectory belongs to 29 inch as underground mining transitions deepen ore extraction profiles.
Application:
End-use environments dictate compound hardness, tread pattern depth, and sidewall reinforcement requirements.
- Construction:Mixed-surface duty cycles with frequent starts, stops, and tight turns demand cut-resistant tread compounds. Infrastructure contractors on China's western rail corridor projects in Sichuan and Gansu provinces drive replacement volume.
- Mining:Continuous high-load operation on abrasive haul roads generates the most intensive wear rates and shortest replacement cycles. Copper producers spanning Chile, Peru, and the Democratic Republic of Congo consolidate procurement across border operations.
- Agriculture:Seasonal usage patterns with extended storage intervals create steady but lower-velocity replacement demand. Midwest US grain operations and Ukrainian Black Sea port logistics represent core consumption zones.
- Demolition:Impact and puncture hazards from rebar and concrete debris require solid or severe-service pneumatic configurations. European decommissioning projects under EU circular economy directives expand specification requirements.
Mining commands the established base. The steepest expansion runs through demolition as urban renewal and industrial site remediation accelerate.
End User:
Customer type determines procurement authority structure, specification standardization, and service attachment expectations.
- Contractors:Project-based purchasing with price-sensitive bidding constraints and limited inventory carrying capacity. General contractors on Australia's east coast infrastructure pipeline negotiate fleet-wide tyre supply agreements.
- Rental Services:Consolidated purchasing authority with standardized specification requirements and high replacement velocity. United Rentals and Sunbelt Networks in North America represent underserved aftermarket channels with captive demand.
- Mining Companies:Multi-year volume contracts with embedded service obligations and guaranteed cost-per-hour structures. BHP and Rio Tinto procurement committees compress supplier rosters to two or three strategic partners with global field engineering networks.
- Government:State-procurement channels with certification requirements and domestic content preferences. China's MIIT tyre labeling requirements and GB standards filter supplier eligibility for western province infrastructure projects.
Mining companies command the established base. The steepest expansion runs through rental services as equipment-as-a-service models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy haul rail network underwrites Australia's centrality in ultra-class tyre demand, moving iron ore from inland mines to Port Hedland export terminals. China's western rail corridor through Sichuan and Gansu channels equipment procurement for state-backed infrastructure. The Alberta oil sands' dedicated haul roads sustain North American replacement cycles for severe-service compounds.
Australia
Western Australia's Pilbara iron ore operations drive fleet renewal for 35-inch and larger configurations as BHP and Rio Tinto deepen pit extraction profiles. The country's national mining regulator enforces strict vehicle safety standards for autonomous haul truck operations. Perth-based field engineering networks service mine sites across the Pilbara and Goldfields regions, embedding technicians within operator maintenance facilities.
Canada
Alberta's oil sands surface mining requires specialized tread compounds resisting bitumen adhesion and thermal degradation during continuous 24-hour operations. Environment and Climate Change Canada imposes emissions standards on off-road equipment that filter tyre supplier eligibility for provincial procurement. Fort McMurray's industrial corridor concentrates equipment depots and retreading facilities serving Suncor and Syncrude operations.
Chile
Atacama Desert copper mines accelerate replacement cycles as ore grades decline and haul distances extend from pit to concentrator plants. The country's national mining regulator supervises workplace safety protocols affecting tyre specification requirements for underground transitions. Antofagasta's mining services cluster hosts distributor networks supplying Codelco and BHP's Escondida complex.
China
Xinjiang and Inner Mongolia coal basins expand heavy earthmoving capacity under state-directed infrastructure investment programs. MIIT tyre labeling requirements and GB standards create certification barriers for foreign suppliers accessing western province procurement channels. Ordos Basin mining cities standardize radial configurations for 100-ton-class haul trucks operating in high-altitude, low-temperature environments.
Germany
Industrial decommissioning and urban renewal projects expand demand for solid and severe-service pneumatic configurations in demolition applications. EU F-Gas Regulation and REACH compliance thresholds on aromatic process oils compel compound reformulation for European market access. The Ruhr industrial zone's materials recovery facilities specify puncture-resistant tyres for scrap-handling operations under circular economy directives.
Earthmoving Equipment Tyres Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in compound formulation and curing press capacity. The supplier base consolidates around three to four strategic partners per major mining OEM, displacing regional distributors lacking consignment inventory scale. Archetypes separate integrated rubber compounders with captive raw material sourcing from specialized tread designers and aftermarket service networks. Dominant competitive moves include multi-year volume contracting with embedded field engineering obligations and backward integration into carbon black and steel cord supply.
Among European compounders, Continental and Michelin exemplify integrated manufacturing archetypes with in-house rubber compounding facilities. Titan International anchors North American aftermarket positioning through dealer network density. Balkrishna Industries occupies a distinct tier serving price-sensitive emerging market demand with standardized specifications.
| Leading Market Players |
|---|
| Continental |
| Balkrishna Industries Limited (BKT) |
| Michelin |
| Hankook Tire & Technology Group |
| Yokohama Rubber Company |
| Bridgestone |
| Sumitomo Rubber Industries |
| Titan International |
| Goodyear |
| Others |
Value Network & Pricing Analysis
Southeast Asian rubber plantation belts anchor raw material availability for earthmoving tyre compounders, concentrating pricing power among integrated manufacturers with captive sourcing agreements and long-term offtake contracts with Thai and Indonesian suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement contracts, with premium tiers commanding spreads based on ISO 4250 dimensional certification and embedded field engineering services. Price differentiation hinges on compound formulation grade and guaranteed cost-per-hour contracting structures. Cost compression in economy tiers is intensifying because Balkrishna Industries and emerging Asian compounders are scaling standardized radial production for price-sensitive mining contractors. Rental services and municipal fleets exhibit highest price sensitivity, while diversified mining majors with consolidated supplier rosters prioritize lifecycle cost optimization over unit acquisition pricing.
Supply Chain Analysis
Tariff exposure between Thailand and major importing jurisdictions dominates supply chain risk assessment for natural rubber feedstocks. Manufacturing concentration rests on Thailand, Indonesia, and Vietnam for raw latex and ribbed smoked sheet supply, with China and South Korea hosting steel cord and carbon black production. Compound formulation draws from aromatic process oils, synthetic rubber polymers, and specialized curing agents subject to REACH registration timelines. Single-source vulnerability persists for 63-inch and larger curing press capacity, concentrated among German and Japanese equipment builders. Distribution runs through OEM-embedded supply agreements and authorized dealer networks serving aftermarket replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized compound chemist expertise represents the critical bottleneck constraining R&D scaling and new product commercialization timelines, making human capital retention and technical training infrastructure strategic imperatives for all market participants.
For Market Incumbents: Pre-empt supplier roster compression at diversified mining majors by embedding field engineering teams within BHP and Rio Tinto maintenance facilities across Western Australia and Chile, while securing captive carbon black supply through backward integration into Southeast Asian feedstock processing to defend margin position against aromatic oil price volatility. For New Entrants and Emerging Players: North American rental fleet aftermarket channels represent the most penetrable entry point, with United Rentals and Sunbelt Networks consolidating purchasing authority and standardizing specifications that reduce certification barriers. China's western mining provinces offer secondary white-space for suppliers achieving MIIT tyre labeling compliance and GB standard certification. Go-to-market execution should prioritize consignment inventory partnerships with regional distributors lacking balance-sheet capacity for direct OEM engagement. For Investors and Strategic Acquirers: Long-term, this sits as a compound-formulation-capability play because abrasion-resistant tread science for high-silica ore environments commands durable competitive moats and premium pricing power. Target acquisition archetypes include mid-tier radial specialists with proven 29-inch and 35-inch moulding capacity and established mining OEM technical qualification. Monitor sensor-embedded intelligent tyre adoption rates as the signal indicating shift from product-transaction to predictive-maintenance-service revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Black Supply | Captive sourcing from Southeast Asian feedstock processors insulates Continental and Michelin from commodity price shocks. |
| Sensor-Embedded Intelligent Tyre Development | Pressure and temperature monitoring systems enable Titan International to capture recurring predictive maintenance revenue streams. |
| GB Standard Certification Investment | MIIT compliance unlocks state-procurement channels for Xinjiang and Inner Mongolia coal basin equipment tenders. |
| Field Engineering Network Expansion | Perth-based technical teams embedded at Pilbara mine sites secure multi-year volume contracts with embedded service obligations. |
| Low-Aromatic Oil Formulation Transition | Rapeseed and tall oil feedstock substitution addresses EU F-Gas Regulation phase-down schedules for European mining OEM access. |
Research Methodology
Desk research of customs trade databases, mining equipment procurement records, and rubber industry association reports preceded structured interviews with tyre plant managers, mining procurement directors, OEM technical qualification teams, and aftermarket service heads. Primary fieldwork across Western Australia, Chile, and Germany validated compound formulation trends and regulatory compliance timelines. Secondary sources included SEC filings from publicly traded manufacturers, ECHA substance registration databases, and ISO certification registries. Bottom-up volume modeling triangulated against top-down mining fleet expansion projections.
Assumptions held fixed include sustained ore extraction depth transitions in Australian and Chilean operations, REACH compliance enforcement timelines, and radial construction technology adoption curves across underground mining applications. Segmentation dimensions modeled encompass product architecture, dimensional category, end-use environment, and customer procurement authority structure. CAGRs were derived from equipment replacement cycle analysis and fleet expansion disclosures across the projection horizon. Forecast inputs incorporated natural rubber price volatility scenarios and curing press capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in commodity supercycle intensity, currency fluctuation in Southeast Asian sourcing jurisdictions, or autonomous haul truck deployment acceleration would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement consistency and mining capital expenditure commitments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Small Bulldozers Market
Construction Equipment
Industrial Hydraulic Equipment Market
Construction Equipment
Crane Pumps Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Extrusion Machinery Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Trenchers Market
Construction Equipment
France Metal Fabrication Equipment Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Automatic Clay Brick Making Machine Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Concrete Pumps Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market