
 Plastic Molding Machine Market | 2026-2036
Plastic Molding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Molding Machine Market Analytics
Automotive OEMs are collapsing their historical reliance on job-shop molders and bringing medium-tonnage capacity in-house. ENGEL AUSTRIA GmbH leverages its vertical integration into servo-electric drive trains to capture this captive demand. HAITIAN INTERNATIONAL anchors its competitive position through manufacturing scale in Asia that undercuts European labor costs. Arburg GmbH + Co KG differentiates via modular machine architectures that let automakers reconfigure lines between interior and powertrain polymer applications.
A plastic molding machine is an industrial press that heats thermoplastic or thermoset polymers to a viscous flow state, then forces the melt into a precision-machined metal cavity under clamping pressures typically ranging from 500 to 5,000 metric tons, where it cools and solidifies into a net-shape part. Its primary purpose is to mass-produce complex geometries with tight dimensional tolerances for sectors that demand high repeatability at unit costs below machining or casting alternatives. Injection molding commands the dominant value share because automotive and electronics buyers specify multi-cavity tools with sub-second cycle times that only reciprocating-screw injection units can deliver. Electric technology is the fastest-expanding segment as factory energy audits in Germany and Japan expose the kilowatt-hour penalty of legacy hydraulic pumps. Packaging end users gravitate toward hybrid systems that pair servo-electric metering with hydraulic clamping to handle thin-wall containers at the speed lines require.
The EU F-Gas Regulation and REACH restrict fluorinated greenhouse gases in cooling circuits and mandate material traceability for polymer contact surfaces, pushing molders toward all-electric machines with water-based temperature control. China's MIIT enforces GB energy-efficiency standards that disqualify older hydraulic models from state procurement tenders, redirecting domestic demand toward hybrid and electric platforms. Japan's METI funds JIS-certified smart factory retrofits that embed molding machines with real-time viscosity sensors. Stakeholders must monitor how carbon-border adjustment mechanisms reshape the geography of mold production and whether captive OEM toolrooms erode the independent molder base that has historically sustained aftermarket service revenues.
Market Dynamics
Automotive OEMs are internalizing medium-tonnage molding capacity for lightweight polymer components, collapsing the historical job-shop ecosystem that supplied their toolrooms. This captive shift concentrates demand among fewer buyers with stricter performance specifications.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of fluorinated greenhouse gases in cooling circuits accelerates replacement of hydraulic machines with all-electric platforms using water-based temperature control.
- Automotive lightweighting:OEMs specify multi-cavity tools with sub-second cycle times for interior and powertrain polymer applications, driving injection molding equipment demand.
- China's dual carbon goals:MIIT enforcement of GB energy-efficiency standards redirects procurement toward hybrid and electric platforms by disqualifying legacy hydraulic models from state tenders.
Market Restraints
- Copper and rare-earth magnet costs:Servo-electric drive trains depend on permanent magnet motors whose input materials face price volatility and concentrated supply from limited geographies.
- Precision machining bottleneck:Multi-cavity tool production requires specialized five-axis machining centers concentrated in Germany's Stuttgart-Nuremberg corridor, creating capacity constraints.
- REACH material traceability:Polymer contact surface documentation mandates extend compliance timelines and raise qualification costs for molders serving EU automotive and medical buyers.
Strategic Opportunities
- India's PLI scheme for auto components:Domestic manufacturing incentives attract molding capacity to serve emerging electric vehicle supply chains with localized tooling support.
- Real-time viscosity sensing:METI-funded JIS-certified smart factory retrofits embed process control sensors that enable predictive maintenance and quality assurance services.
- Medical device molding:MDR compliance requirements for polymer contact surfaces create premium demand for all-electric machines with validated process repeatability.
Industry Challenges
- Servo-electric technician scarcity:Maintenance and commissioning of all-electric drive systems require specialized skills that vocational training programs have not scaled to match installation rates.
- Legacy hydraulic integration:Factory energy audits expose efficiency penalties of aging pump systems, yet full line replacement demands capital allocation competing with toolroom expansion budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Molding Machine Market |
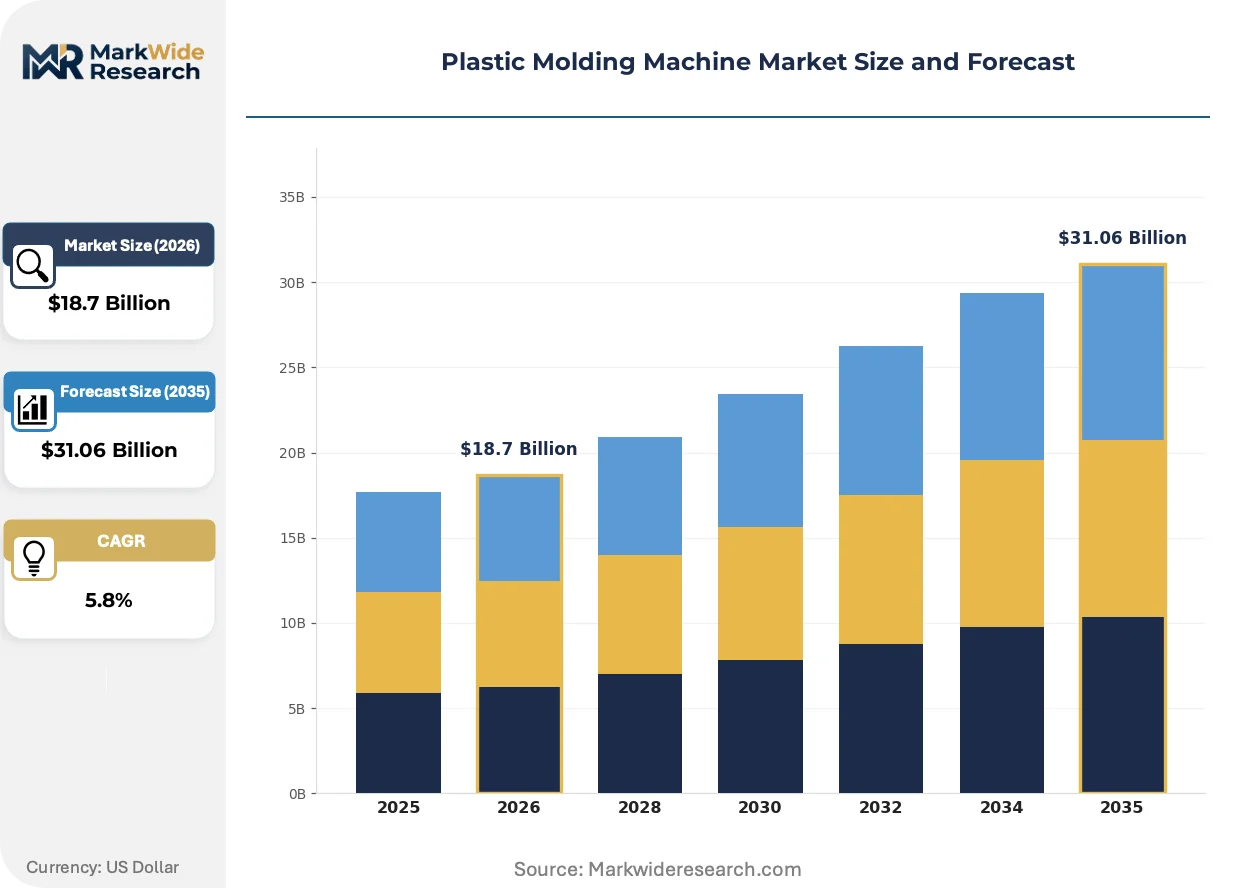
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Blow Molding, Extrusion Molding, Rotational Molding Technology: Hydraulic, Electric, Hybrid, Pneumatic End User: Consumer Goods, Automotive, Electronics, Packaging Size: Small, Medium, Large, Custom |
| Companies Covered | ENGEL AUSTRIA GmbH, HAITIAN INTERNATIONAL, Milacron, Arburg GmbH + Co KG, Husky Technologies, KraussMaffei, NISSEI PLASTIC INDUSTRIAL CO., LTD., Chen Hsong Holdings Limited, Sumitomo Demag, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Molding Machine Market Evolving Landscape
Electrification of machine architectures and embedded process intelligence are compressing cycle economics while regulatory compliance layers add specification complexity. Buyers now prioritize platforms that satisfy multiple jurisdiction standards without reconfiguration.
All-electric injection units are miniaturizing. These systems replace hydraulic pumps with servo motors driving ball-screw mechanisms, delivering precision at clamp forces below 500 metric tons. Packaging producers in Japan and Germany adopt them for thin-wall container lines. The technology is miniaturizing auxiliary equipment footprints and enabling cell-based factory layouts that reduce material handling distances.
REACH and the EU F-Gas Regulation now restrict fluorinated compounds in temperature control circuits and mandate full material traceability for polymer contact surfaces. Molded medical and food-contact parts face extended qualification timelines. European automotive suppliers respond by specifying all-electric machines with water-based cooling exclusively, eliminating refrigerant compliance risk entirely.
Automotive procurement teams now unbundle aftermarket service contracts from initial equipment purchases, treating maintenance as a separate competitive bid. Tier-1 suppliers in Germany's precision engineering corridor negotiate multi-year service agreements with independent technicians rather than OEM service arms. This shift is most visible among Stuttgart-based molders supplying powertrain polymer components to captive OEM toolrooms.
Plastic Molding Machine Market Segmentation
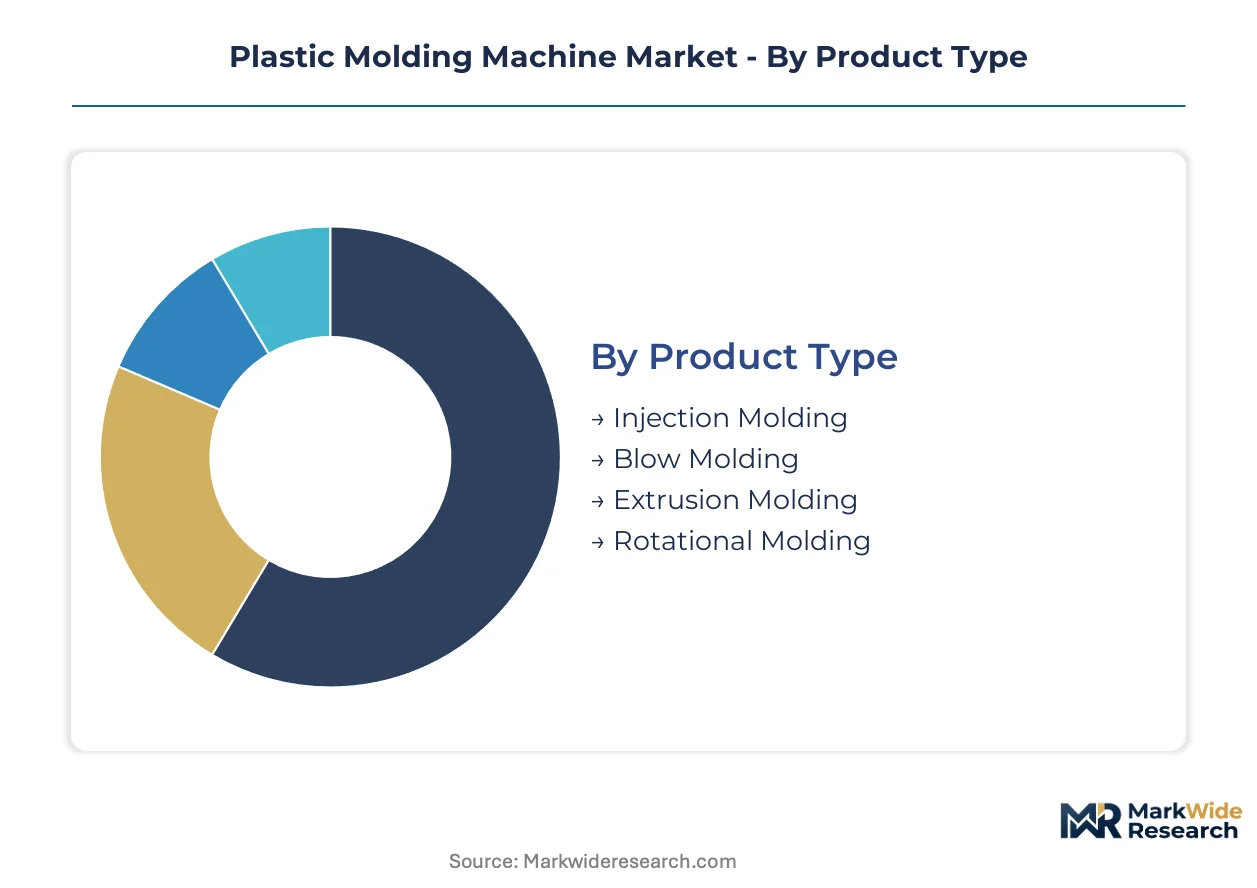
Segmentation in the plastic molding machine market reveals how equipment specifications align with distinct procurement channels. Automotive buyers route through captive toolrooms, while packaging and consumer goods segments flow through independent molders with different service expectations.
Product Type:
Injection molding machines dominate capital flows through automotive OEM direct procurement channels. Blow and extrusion equipment channels more heavily through distributor networks serving packaging and construction material processors.
- Injection Molding:Reciprocating-screw units force polymer melt into precision-machined cavities under clamping pressures from 500 to 5,000 metric tons. Demand concentrates in Germany's Stuttgart-Nuremberg corridor where automotive suppliers specify multi-cavity tools with sub-second cycle times for interior and powertrain polymer applications.
- Blow Molding:Extrusion or injection-stretch processes inflate heated parisons into hollow containers and technical parts. European packaging producers facing EU F-Gas Regulation compliance are redirecting procurement toward all-electric blow molding lines with water-based temperature control.
- Extrusion Molding:Continuous screw mechanisms push polymer through shaped dies for profiles, films, and pipes.
- Rotational Molding:Biaxial rotation distributes polymer powder across heated mold interiors for large hollow parts.
By volume, Injection Molding leads. By growth pace, Blow Molding is ahead.
Technology:
Technology segmentation maps directly to customer energy audit maturity and capital replacement cycles. Early adopters in Japan and Germany have accelerated electric platform procurement, while cost-sensitive buyers in emerging manufacturing economies retain hydraulic dominance.
- Electric:Servo motors driving ball-screw mechanisms replace hydraulic pumps, delivering precision positioning with reduced energy consumption. Japanese packaging producers and German automotive suppliers specify these platforms to satisfy METI-funded smart factory requirements and factory energy audit mandates.
- Hydraulic:Traditional pump-driven systems maintain installed base dominance where technician scarcity and lower capital thresholds delay replacement cycles.
- Hybrid:Combines servo-electric metering with hydraulic clamping for thin-wall container production at speed lines demand. China's MIIT enforcement of GB energy-efficiency standards redirects state procurement tenders toward these platforms.
- Pneumatic:Compressed air actuation serves niche low-tonnage applications with simplified maintenance requirements.
Electric platforms command premium pricing. Hybrid systems are gaining share fastest in packaging applications.
End User:
End user segmentation determines specification complexity and aftermarket service bundling. Automotive procurement teams now unbundle service contracts, while medical and food-contact segments demand validated process documentation.
- Automotive:OEM captive toolrooms specify medium-tonnage capacity for lightweight polymer components in interior trim and powertrain applications. REACH material traceability mandates extend qualification timelines for polymer contact surfaces.
- Electronics:Miniaturization trends drive demand for precision micro-molding platforms with sub-50 ton clamping forces.
- Packaging:Thin-wall container production favors hybrid systems pairing electric metering with hydraulic clamping speed.
- Consumer Goods:Price-sensitive procurement through independent molders sustains hydraulic installed base.
Automotive generates the highest equipment value per installation. Electronics is expanding most quickly.
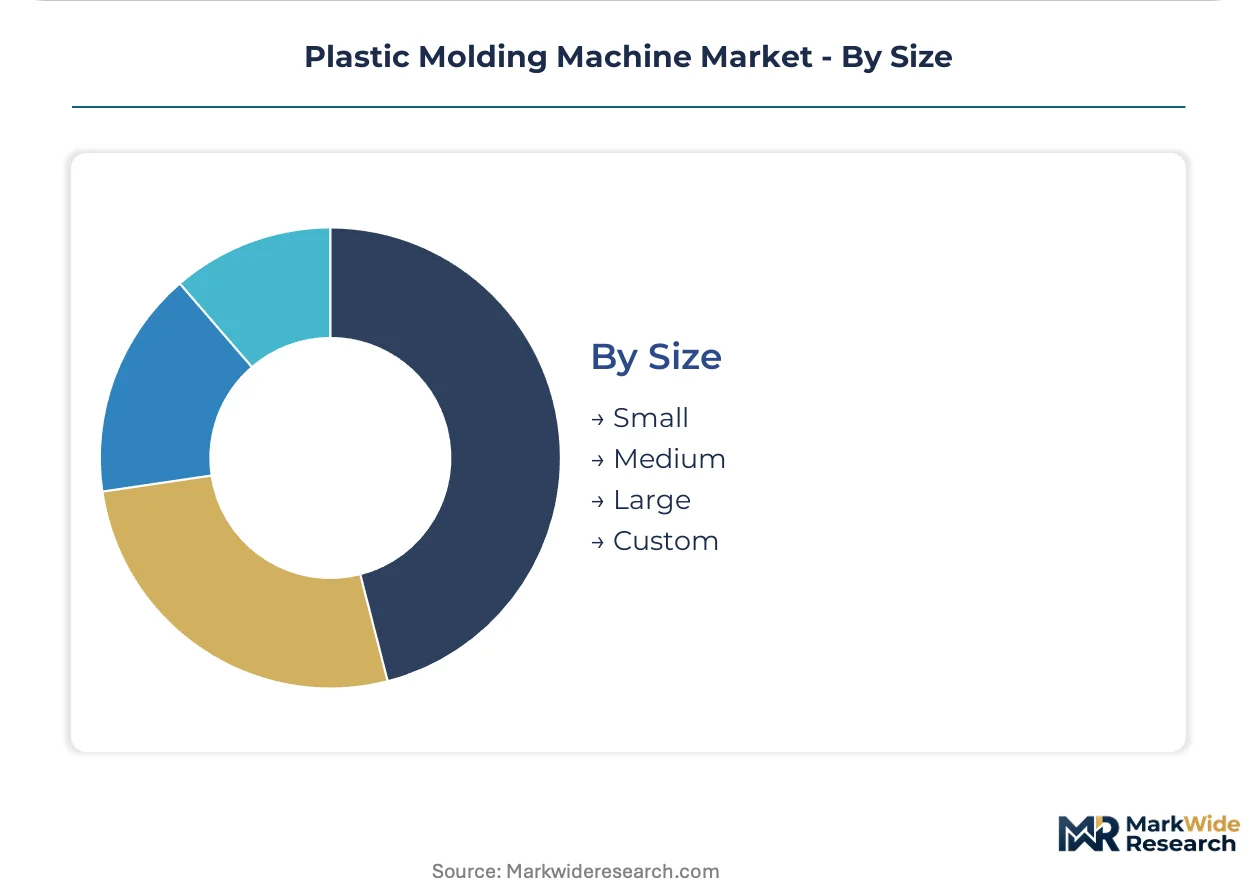
Size:
Machine size segmentation correlates with customer scale and application complexity. Large tonnage units concentrate among automotive OEMs, while small machines serve distributed electronics and medical device molding.
- Large:Exceeding 1,000 metric tons clamping force for structural automotive components and industrial pallets. Germany's precision engineering corridor hosts concentrated demand for these platforms.
- Medium:200-1,000 ton range capturing automotive lightweighting applications as OEMs internalize capacity.
- Small:Below 200 tons for electronics connectors, medical devices, and precision consumer components.
- Custom:Application-specific configurations for unusual part geometries or multi-material processing.
Medium tonnage leads in unit shipments. Small tonnage shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway and Stuttgart's rail-freight terminals anchor Germany's dominance in precision molding equipment distribution. China's high-speed rail network links the Yangtze and Pearl River Delta manufacturing belts. Japan's container ports at Yokohama and Nagoya handle specialized machinery exports.
Germany
Automotive OEMs specify multi-cavity tools with sub-second cycle times for interior and powertrain applications. The EU F-Gas Regulation accelerates replacement of hydraulic machines with all-electric platforms using water-based temperature control. The Stuttgart-Nuremberg precision engineering corridor concentrates demand for large-tonnage platforms serving captive OEM toolrooms.
China
Domestic electric vehicle manufacturers expand in-house molding capacity for lightweight polymer components. MIIT enforcement of GB energy-efficiency standards disqualifies legacy hydraulic models from state procurement tenders. The Yangtze River Delta industrial belt around Shanghai hosts concentrated hybrid and electric platform production for packaging and automotive end users.
Japan
Packaging producers adopt miniaturized all-electric injection units for thin-wall container lines. METI funds JIS-certified smart factory retrofits that embed real-time viscosity sensors for predictive maintenance. The Nagoya-Toyota industrial corridor concentrates precision machinery demand from automotive and electronics sectors.
United States
Medical device manufacturers specify all-electric machines with validated process repeatability for MDR-compliant polymer contact surfaces. FDA qualification requirements extend tooling validation timelines for molded healthcare components. The Midwest automotive belt spanning Michigan and Ohio internalizes medium-tonnage capacity previously outsourced to job-shop molders.
India
Domestic auto component suppliers scale molding operations to serve emerging electric vehicle supply chains. The PLI scheme for auto components attracts tooling investment with localized support infrastructure. The Gujarat-Maharashtra industrial corridor concentrates new capacity for consumer goods and automotive polymer applications.
Plastic Molding Machine Market Competitive Landscape
Concentration sits with vertically integrated European specialists and Asian scale manufacturers. The vendor base splits between premium-tier precision engineering houses and cost-optimized volume producers. Two strategic archetypes dominate: servo-electric technology leaders and manufacturing-scale cost competitors. Competitive moves center on captive supply of drive train components and unbundling of aftermarket service contracts from initial equipment sales.
Among European precision engineering houses, ENGEL AUSTRIA GmbH and Arburg GmbH + Co KG exemplify the technology-led archetype with modular machine architectures. HAITIAN INTERNATIONAL anchors the scale-driven competitive position through manufacturing concentration in Asia. These three occupy distinct positioning vectors that reflect divergent customer procurement priorities across automotive captive toolrooms and independent packaging molders.
| Leading Market Players |
|---|
| ENGEL AUSTRIA GmbH |
| HAITIAN INTERNATIONAL |
| Milacron |
| Arburg GmbH + Co KG |
| Husky Technologies |
| KraussMaffei |
| NISSEI PLASTIC INDUSTRIAL CO., LTD. |
| Chen Hsong Holdings Limited |
| Sumitomo Demag |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts between automotive OEMs and German precision engineering houses lock in multi-year supply access while freezing price visibility for servo-electric drive train components. This contract structure concentrates procurement power among Stuttgart-Nuremberg corridor buyers facing EU F-Gas Regulation compliance deadlines.
Pricing Analysis
Volume-discount tiering structures separate premium all-electric platforms from standard hybrid systems and economy hydraulic units. Pricing stratifies across certification levels, with JIS-certified and CE-marked machines commanding 15-25% premiums over uncertified alternatives. Cost compression in the hydraulic tier is intensifying because China's MIIT enforcement disqualifies legacy models from state tenders. Independent packaging molders in Asia exhibit highest price sensitivity, while captive automotive toolrooms prioritize performance specifications over unit cost.
Supply Chain Analysis
Five-axis machining center availability in Germany's Stuttgart-Nuremberg corridor constitutes the critical chokepoint constraining multi-cavity tool production timelines. Supply concentrates in Germany, China, and Japan for precision-machined platens, servo motors, and control systems respectively. Permanent magnet motors draw from concentrated rare-earth processing capacity, creating single-source vulnerability for electric platform manufacturers. Distribution runs through OEM direct procurement channels for automotive and electronics segments, while independent molders source through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH material traceability and EU F-Gas compliance create certification barriers that extend qualification timelines beyond 18 months for new entrants.
For Market Incumbents: Fortify captive supply of servo-electric drive trains through backward integration into permanent magnet motor production. Deepen channel control by unbundling aftermarket service contracts from equipment sales to independent technicians, countering emerging Asian scale competitors threatening margin structures through manufacturing concentration.
For New Entrants and Emerging Players: CE marking fast-track programs for medical device molding applications offer the most penetrable entry vector. Target India's PLI scheme for auto components with localized tooling support infrastructure. Pursue partnership-based go-to-market approaches with Gujarat-Maharashtra industrial corridor distributors rather than direct OEM engagement.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with in-house drive train production and established JIS certification pathways. Long-term viability favors entities with proven smart factory retrofit capabilities across the 5-10 year technology replacement cycle. Monitor carbon-border adjustment mechanism implementation as the primary inflection signal reshaping mold production geography.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Drive Trains | Captive supply of permanent magnet motors insulates ENGEL and Arburg from rare-earth price volatility. |
| CE Marking Fast-Track Investment | Accelerated EU compliance pathways unlock medical device molding premiums ahead of MDR enforcement. |
| India PLI Localization | Gujarat-Maharashtra corridor capacity serves emerging electric vehicle supply chains with reduced logistics exposure. |
| Aftermarket Service Unbundling | Independent technician networks in Stuttgart erode OEM service arm pricing power. |
| Real-Time Viscosity Sensor Integration | METI-funded JIS retrofits enable predictive maintenance revenue streams for Japanese packaging producers. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and distributor channel partners anchors the qualitative findings. Secondary sources include customs/trade data for machinery imports, SEC 10-K filings from listed equipment manufacturers, VDMA industry association reports, and MIIT GB standard enforcement announcements. Bottom-up triangulation across installed base estimates and top-down validation through capital expenditure disclosures ensure methodological robustness.
Sensitivity analysis around copper and rare-earth magnet price trajectories tests forecast stability across the projection horizon. Segmentation dimensions modeled include product type, technology platform, end-user industry, machine tonnage class, and regional regulatory cluster. CAGRs derive from regression analysis of historical replacement cycles against energy-efficiency mandate phase-in schedules. Industry-specific inputs incorporate automotive lightweighting content per vehicle trends and packaging thin-wall container speed requirements.
Decision-makers should treat outputs as directional under base assumptions of sustained EU F-Gas Regulation enforcement and China's dual carbon policy continuity; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as carbon-border adjustment mechanisms and captive OEM toolroom expansion rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
China Elevator Ropes Market
Construction Equipment
Tower Crane Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Foundry Sand Cleaning Machine Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Track Laying Equipment Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Static and Rotating Equipment Market