
 Advanced Building Materials Market | 2026-2036
Advanced Building Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Building Materials Market Analysis
The EU Green Deal is consolidating the cost-of-entry calculus for suppliers of low-carbon concrete and engineered timber across European construction markets. CRH Public Limited Company leverages its vertically integrated cement-to-concrete network to pre-certify products under evolving EU taxonomy rules. BASF SE anchors its position through polymer admixture R&D that cuts clinker content while maintaining compressive strength thresholds. Saint-Gobain Group specializes in multi-functional insulation systems that simultaneously address thermal performance and fire safety mandates.
Advanced building materials encompass engineered substances and composite systems designed to exceed conventional performance benchmarks for strength, durability, energy efficiency, or environmental impact, typically manufactured through controlled chemical synthesis, precision curing, or fiber-reinforcement processes such as pultrusion and autoclaved aeration. These materials serve primary commercial and industrial purposes including structural load-bearing, thermal envelope optimization, and lifecycle carbon reduction in built assets. Concrete dominates current volume flows but faces margin compression from energy-intensive production, while composites command premium positioning in facade and seismic applications where strength-to-weight ratios justify higher unit costs. Wood segments, particularly cross-laminated and glue-laminated systems, are capturing share in mid-rise residential and commercial applications as certification schemes like LEED and CE Mark create procurement preference for biogenic carbon storage.
EPA emissions standards for Portland cement kilns and the EU F-Gas Regulation on blowing agents for insulation foams are reshaping formulation requirements and equipment upgrade cycles for North American and European manufacturers. China's MEE enforces GB standards on building material recyclability that restrict market access for non-compliant imports. Stakeholders must monitor divergence between regional carbon accounting methodologies, as inconsistent embodied carbon measurement rules threaten to fragment supply chain compliance costs and create arbitrage risks for multi-jurisdictional project portfolios.
Market Dynamics
Cross-laminated timber is consolidating structural market share as EU Green Deal embodied carbon limits tighten procurement specifications for mid-rise residential projects across Germany, Austria, and Scandinavia.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for high-GWP blowing agents are accelerating mineral wool and aerogel insulation substitution in facade retrofits across France and the Netherlands.
- China's dual carbon goals:Provincial infrastructure bids now embed GB-standard recyclability requirements that filter supplier pools for low-carbon cement and steel reinforcement.
- Mass timber engineering:Fire-rated CLT floor assemblies are capturing specification share in German residential construction as building codes align biogenic carbon accounting with lifecycle assessment protocols.
Market Restraints
- Clinker input volatility:Energy-intensive calcination processes expose cement margins to natural gas and carbon credit price swings in European production zones.
- Resin supply concentration:Epoxy and polyurethane precursors for fiber-reinforced composites cluster in Gulf Coast petrochemical corridors, creating hurricane-related disruption exposure.
- Seismic code incompatibility:Mass timber lateral systems face height restrictions in Japanese high-rise zones where JIS standards privilege steel moment frames.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for green building materials are opening import-substitution pathways for domestic AAC block and low-carbon glass manufacturing.
- 3D-printed concrete:Binder jetting convergence with robotic placement is enabling geometrically complex structural elements for stadium and airport terminal applications.
- Digital material passports:Blockchain-verified embodied carbon tracking is creating specification premiums for suppliers pre-certified under evolving EU taxonomy disclosure rules.
Industry Challenges
- Fire engineering talent scarcity:Mass timber projects require specialized structural-fire interaction modeling that outpaces current university program output in timber-producing regions.
- CE Mark timeline compression:Novel insulation formulations face extended notified body review cycles that delay product launch windows by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Building Materials Market |
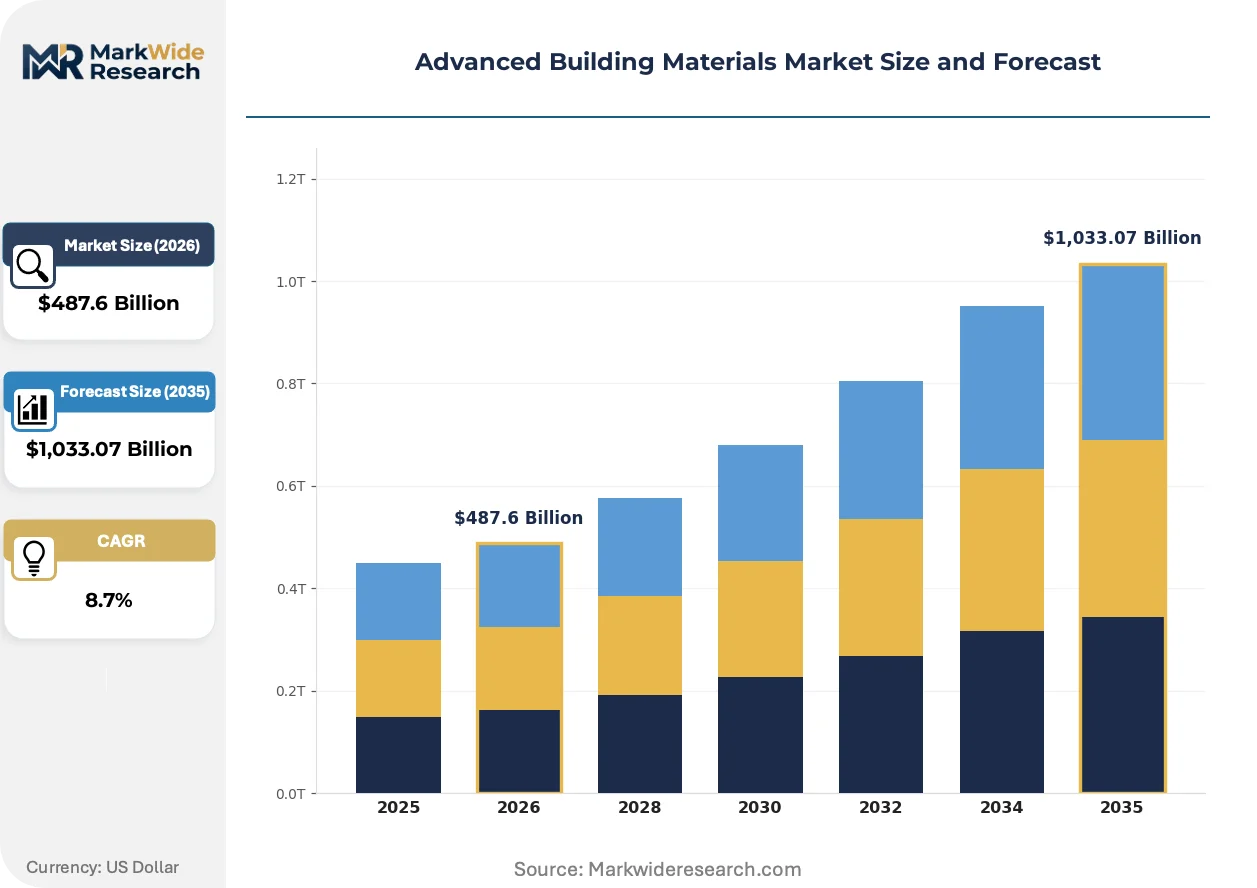
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,033.07 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Concrete, Steel, Wood, Composites Application: Residential, Commercial, Industrial, Infrastructure Functionality: Insulation, Load-bearing, Aesthetic, Waterproofing Certification: LEED, ISO, CE Mark, ANSI |
| Companies Covered | CRH Public Limited Company, BASF SE, Holcim Ltd, PPG Industries, Kingspan Group PLC, Martin Marietta Materials, Saint-Gobain Group, Cemex, Vulcan Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Building Materials Market Emerging Trajectories
Material informatics and generative design are compressing formulation development cycles while regulatory carbon accounting forces transparency through digital supply chain infrastructure.
Photocatalytic cement formulations that degrade airborne NOx pollutants are consolidating specification share in urban facade applications. Municipal infrastructure departments in Milan and Mexico City specify these surfaces for tunnel linings and sound barriers. The technology is consolidating competitive positioning for suppliers with in-house photocatalyst synthesis capabilities versus commodity concrete blenders.
REACH authorization requirements for chromium VI in cement grinding aids are forcing reformulation across European production networks. The restriction eliminates legacy corrosion inhibitors from supply chains by 2026. Spanish and Italian producers accelerate alternative mineral activator testing to maintain compressive strength performance without authorization-dependent additives.
Performance-based specification contracts now dominate institutional procurement for envelope systems in Nordic markets. Building owners contract guaranteed thermal transmittance outcomes rather than material thickness inputs. Danish and Swedish housing associations lead this shift, transferring technical risk to subsystem suppliers who warrant operational energy performance across 15-20 year horizons.
Advanced Building Materials Market Segmentation
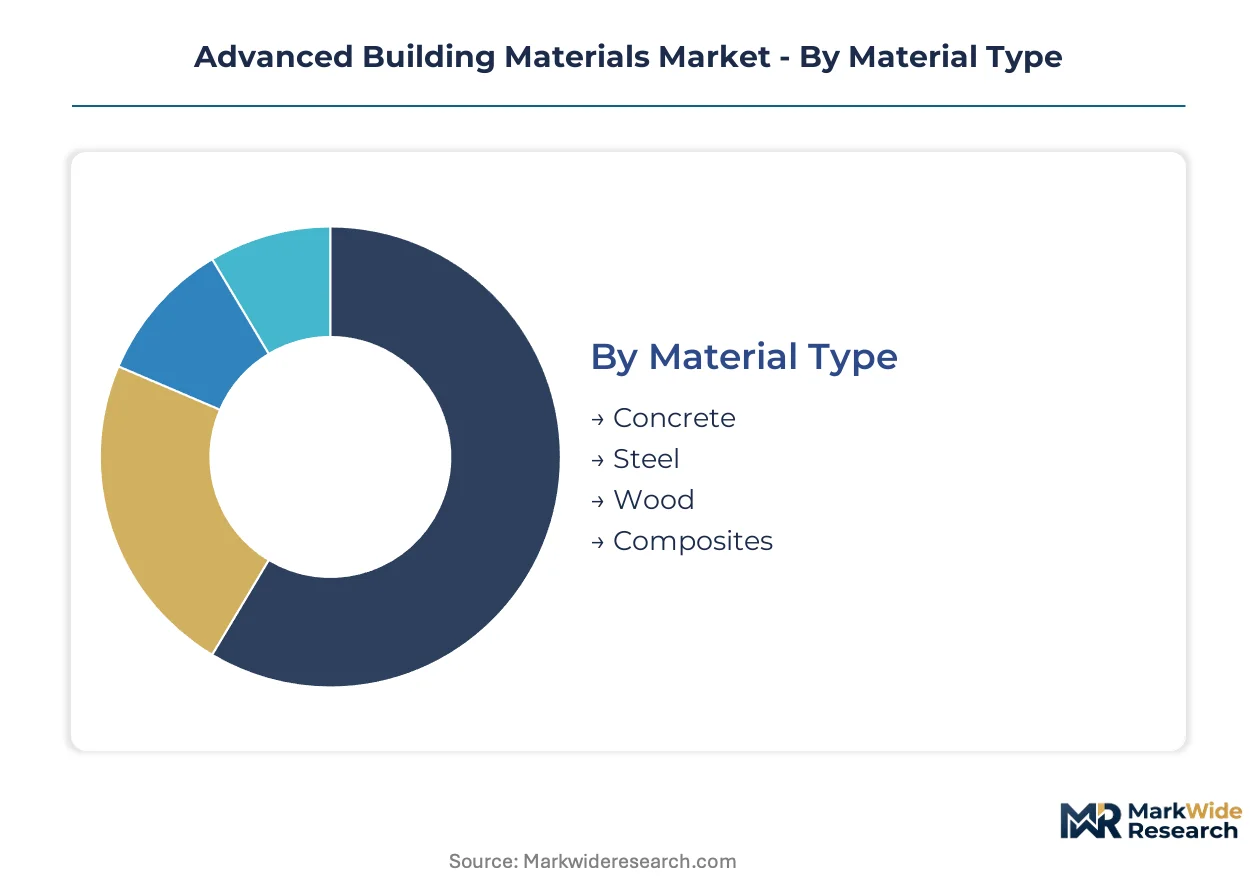
Material differentiation determines capital allocation, regulatory compliance pathways, and procurement specifications across construction value chains. Segmentation reveals where embodied carbon constraints concentrate specification power and where formulation R&D yields defensible margin positions.
Material Type:
Concrete and steel demand the heaviest upfront capital for kiln operations and electric arc furnace installations, while wood processing and composite manufacturing operate at lower asset intensity.
- Concrete:Portland and blended cement formulations dominate volume flows but face margin compression from energy-intensive calcination. Chinese provincial infrastructure bids now embed GB-standard low-carbon cement requirements that filter supplier pools.
- Steel:High-strength rebar and structural sections serve seismic and high-rise applications where JIS standards in Japan privilege moment frames over timber alternatives. Electric arc furnace capacity expansion is reshaping scrap-fed production economics.
- Wood:Cross-laminated and glue-laminated systems capture mid-rise residential share in Germany and Austria as EU Green Deal embodied carbon limits tighten procurement specifications.
- Composites:Fiber-reinforced polymer systems command premium positioning in facade and seismic retrofit applications where strength-to-weight ratios justify higher unit costs.
Concrete absorbs the bulk of installed capacity; wood segments are expanding most quickly.
Application:
Residential construction concentrates demand for standardized, cost-optimized materials, while infrastructure projects impose the most stringent certification and performance warranty requirements.
- Residential:Mass timber framing and high-performance insulation systems dominate mid-rise construction in Nordic markets where building codes align biogenic carbon accounting with lifecycle protocols.
- Commercial:Curtain wall assemblies and raised floor systems specify aerogel and vacuum insulation panels where thermal transmittance guarantees drive procurement decisions.
- Industrial:Chemical-resistant flooring and corrosion-protected structural steel serve process manufacturing facilities with aggressive service environments.
- Infrastructure:Photocatalytic cement formulations for tunnel linings and sound barriers consolidate specification share in Milan and Mexico City municipal departments.
Residential construction channels the highest material tonnage; infrastructure applications command the steepest specification premiums.
Functionality:
Load-bearing functions require the most extensive testing and certification investment, while aesthetic and waterproofing applications permit faster product iteration cycles.
- Insulation:Mineral wool and aerogel substitution accelerates across France and the Netherlands as EU F-Gas Regulation phase-down mandates eliminate high-GWP blowing agents from facade retrofits.
- Load-bearing:Engineered timber and ultra-high-performance concrete serve hybrid structural systems where fire-rated assemblies must satisfy extended egress time requirements.
- Aesthetic:Self-cleaning photocatalytic surfaces and textured fiber-cement panels differentiate premium facade specifications in urban infill projects.
- Waterproofing:Crystalline admixtures and bentonite membrane systems protect below-grade structures in high water table conditions.
Load-bearing materials lock up the longest certification timelines; insulation products are climbing the fastest as energy code stringency tightens.
Certification:
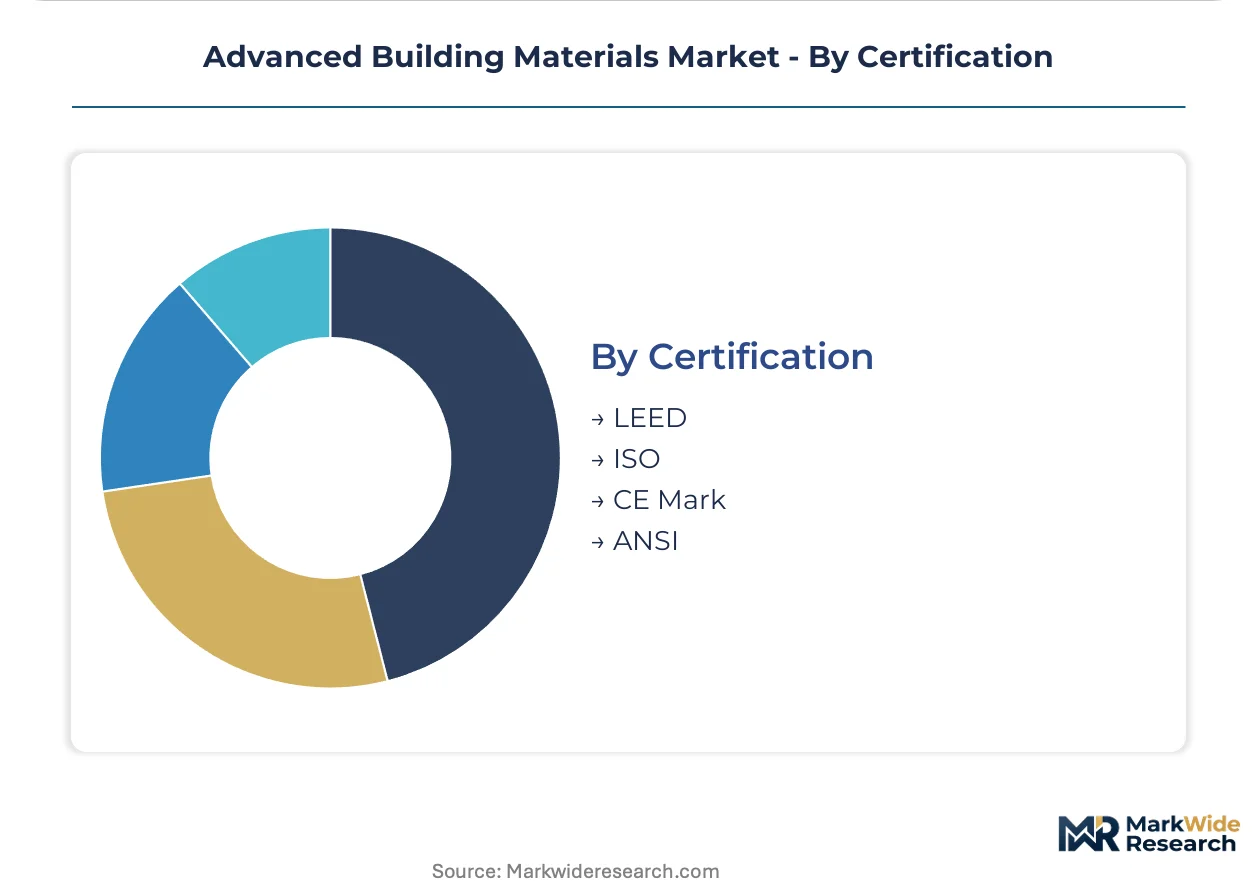
CE Mark and LEED impose the most extensive documentation burdens, while ANSI and ISO standards offer more modular compliance pathways for multi-jurisdictional suppliers.
- LEED:Biogenic carbon storage credits and regional material sourcing points drive specification preference for certified timber and low-carbon concrete in North American commercial development.
- ISO:Environmental management and lifecycle assessment standards provide baseline credibility for suppliers entering new geographic markets without full local certification.
- CE Mark:Construction Products Regulation conformity marking remains mandatory for structural components placed on the European market, with extended notified body review cycles delaying novel insulation launches.
- ANSI:Voluntary consensus standards govern composite testing protocols and quality assurance systems in US commercial and infrastructure procurement.
CE Mark compliance consumes the most regulatory bandwidth; LEED specification is gaining share fastest as green building mandates proliferate across North American jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate low-carbon cement capacity expansion as provincial infrastructure bids embed GB-standard recyclability requirements. Germany's Ruhr Valley and Bavaria anchor European engineered timber manufacturing clusters.
China
Provincial infrastructure procurement in Jiangsu and Zhejiang provinces now mandates NMPA-aligned green building codes for low-carbon cement in state-funded projects. The Ministry of Ecology and Environment enforces GB standards on building material recyclability that filter supplier pools for steel reinforcement and concrete additives. Shanghai's Pudong district hosts pilot projects for 3D-printed concrete structural elements in airport terminal expansions.
Germany
Residential construction in Bavaria and Baden-Württemberg accelerates cross-laminated timber panel uptake as the EU Green Deal tightens embodied carbon limits for structural components. The KBA coordinates with federal building regulators to align biogenic carbon accounting with lifecycle assessment protocols for mid-rise housing. The Black Forest region supplies certified timber feedstock to CLT fabrication facilities serving Austrian and Swiss export markets.
United States
EPA emissions standards for Portland cement kilns drive equipment upgrade cycles across Texas and California production corridors. The Inflation Reduction Act tax credits for low-carbon construction materials concentrate project finance in the Pacific Northwest mass timber cluster. Seattle and Portland municipal departments specify photocatalytic cement formulations for highway sound barriers and tunnel linings.
India
The PLI scheme for green building materials opens import-substitution pathways for domestic AAC block manufacturing in Gujarat and Maharashtra. BIS certification requirements for structural concrete components tighten as highway and metro rail projects accelerate in the Delhi-Mumbai Industrial Corridor. Hyderabad's construction technology hub hosts pilot programs for digital material passports tracking embodied carbon through blockchain verification.
Japan
METI building energy codes drive vacuum insulation panel specification in Tokyo and Osaka commercial retrofits. JIS standards for seismic performance privilege steel moment frames over mass timber lateral systems in high-rise zones above 12 stories. The Nagoya industrial corridor concentrates fiber-reinforced polymer composite manufacturing for facade applications requiring strength-to-weight optimization.
Advanced Building Materials Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation R&D, certification pre-approval, and regional distribution density. The vendor base organizes around three strategic archetypes: vertically integrated cement-to-concrete networks, polymer chemistry specialists supplying admixture systems, and multi-functional insulation subsystem providers. Capacity expansion and M&A consolidation dominate competitive moves as players secure notified body pre-certification under evolving EU taxonomy disclosure rules.
Among European-based material conglomerates, CRH Public Limited Company and BASF SE exemplify divergent strategic positioning within the advanced building materials value chain. CRH occupies a position representing vertically integrated infrastructure material supply, while BASF anchors the specialty chemicals tier supplying polymer admixture formulations. Saint-Gobain Group sits within the multi-functional building envelope specialist archetype, concentrating insulation and glass systems expertise.
| Leading Market Players |
|---|
| CRH Public Limited Company |
| BASF SE |
| Holcim Ltd |
| PPG Industries |
| Kingspan Group PLC |
| Martin Marietta Materials |
| Saint-Gobain Group |
| Cemex |
| Vulcan Materials |
| Others |
Supply Flow & Price Mechanics
3D-printed concrete binder jetting convergence with robotic placement simultaneously compresses unit production costs and concentrates fabrication capacity around specialized equipment clusters in Germany and China. This production-method transition reshapes both input procurement patterns and buyer negotiation leverage across structural component markets.
Pricing Analysis
Lead-time premiums dominate pricing differentiation in mass timber and engineered concrete segments, with German CLT fabricators commanding 15-20% markups for sub-8-week delivery against standard 14-week schedules. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier—CE Mark structural ratings versus non-certified architectural grades—while volume-scale discounts concentrate among Nordic housing associations. Cost compression in commodity cement intensifies because energy-intensive calcination exposes margins to natural gas volatility. Infrastructure contractors exhibit highest price sensitivity due to fixed-bid procurement, while commercial developers prioritize lifecycle carbon performance over unit cost.
Supply Chain Analysis
China's GB-standard recyclability mandates and India's PLI scheme local-content rules are forcing multinationals to establish domestic blending facilities rather than rely on import-only distribution. Geographic supply concentration centers on China for low-carbon cement precursors, Germany for engineered timber feedstock, and the US Gulf Coast for epoxy resin systems. Raw material dependencies rest on calcined clay, certified timber feedstock, and polyurethane blowing agents. Single-source vulnerability clusters around Gulf Coast petrochemical corridors exposed to hurricane disruption. Distribution runs through project-direct channels for large infrastructure, with regional distributors serving fragmented residential contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The advanced building materials sector sits in a technology-transition phase where cross-laminated timber lateral systems displace steel moment frames in mid-rise residential construction across EU and North American markets.
For Market Incumbents: Deploy backward integration into certified timber feedstock to secure biogenic carbon accounting credibility as EU Green Deal embodied carbon limits tighten. Cement conglomerates must accelerate low-carbon clinker substitution R&D to defend margin position against emerging geopolymer competitors. Capacity addition in Poland and Romania captures EU taxonomy-aligned project flows before CE Mark review cycles delay competitor launches. For New Entrants and Emerging Players: Launch via performance-based specification contracts targeting Danish and Swedish housing associations that contract guaranteed thermal transmittance outcomes rather than material inputs. White-space concentrates in India's AAC block manufacturing under PLI scheme protection and in 3D-printed concrete geometrically complex elements for airport terminals. Go-to-market angle: blockchain-verified digital material passports that command specification premiums under evolving EU taxonomy disclosure rules. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified material conglomerates seeking CE Mark pre-certification assets. Long-term viability favors specialists with captive low-carbon formulation IP and notified body relationships over commodity blenders exposed to energy price volatility. Signal to watch: acceleration of EU F-Gas Regulation enforcement triggering mineral wool substitution demand spikes in France and Netherlands retrofit markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Timber Feedstock | Secures biogenic carbon accounting credibility for EU Green Deal compliance. |
| Low-Carbon Clinker Substitution R&D | Defends cement margins against geopolymer competitors and carbon pricing exposure. |
| CE Mark Pre-Certification Investment | Compresses product launch windows by 12-18 months against delayed competitors. |
| Digital Material Passport Development | Creates specification premiums through blockchain-verified embodied carbon tracking. |
| Performance-Based Specification Contracts | Transfers technical risk to subsystem suppliers in Nordic housing association procurement. |
Methodological Framework
Independent corroboration across plant managers at cement and CLT fabrication facilities, procurement leads at downstream construction OEMs, and distribution channel partners underwrites the qualitative findings. Primary interviews with technical R&D directors at admixture suppliers and secondary validation through customs/trade data, SEC 10-K filings, and Cefic industry reports anchor supply-side assessments. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Rate-of-change decomposition separates volume growth from price-mix effects across material type, application, functionality, and certification segmentation dimensions. CAGRs derive from installed capacity expansion schedules, regulatory mandate implementation timelines, and substitution elasticity estimates for timber-versus-steel structural systems. Forecast inputs incorporate EU F-Gas Regulation phase-down enforcement intensity and China's dual carbon goal provincial implementation variance.
The model assumes a particular technology adoption path; alternative pathways for mass timber lateral systems in seismic zones would alter the outlook. Forecasts reflect assumptions regarding CE Mark review cycle durations, clinker substitution technical ceilings, and blockchain verification adoption rates in procurement. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Pervious Concrete Market
Building & Construction Materials
Metal Roofing Market
Building & Construction Materials
France Ceramic Tiles Market
Building & Construction Materials
US Metal Stadium Seating Market
Building & Construction Materials
Hydraulic Binder Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
European Cross-Laminated Timber Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Global Stucco Market
Building & Construction Materials
Architectural Acoustic Panels Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Tower Bolt Market
Building & Construction Materials
Europe Industrial Flooring Market