
 Backhoes Market | 2026-2036
Backhoes Market Size, Share, and Industry Trends Forecast 2026-2036
Backhoes Market Intelligence
The performance gap between premium, feature-rich backhoes and lower-cost, standard models is broadening, segmenting the competitive landscape. Caterpillar leverages its advanced telematics and integrated technology to command the premium tier for large-scale contractors. JCB competes across a broader spectrum, offering specialized compact models for niche applications. John Deere sustains a strong presence by focusing on the agricultural and landscaping sectors with durable, versatile machines.
A backhoe is an excavator-loader, a piece of heavy equipment consisting of a tractor fitted with a front-mounted shovel and a rear-mounted articulated arm with a digging bucket. These machines are characterized by digging depths typically ranging from 14 to over 20 feet and are powered by diesel engines. Standard backhoes continue to form the core of the market for general construction sites. However, the compact backhoe segment represents the fastest-growing category, driven by demand from landscaping firms and for utility works in dense urban areas.
Engine emission standards from the US EPA and the EU's Stage V regulations are forcing powertrain redesigns toward cleaner diesel and hybrid options. Concurrently, safety certifications like CE marking and standards from India's BIS govern market access and operator safety protocols. The critical path for manufacturers involves balancing investment in electrification against the persistent demand for cost-effective diesel models in key developing economies.
Market Dynamics
The central dynamic in the backhoe market is the bifurcation driven by powertrain technology. Strict emissions regulations in developed nations push manufacturers toward high-cost electric and hybrid systems, while persistent demand for cost-effective, easily serviceable diesel models in developing economies creates a divided engineering and supply chain strategy.
Growth Catalysts
- Infrastructure Investment:Large-scale public works programs, particularly in India for smart city and transportation network development, are creating sustained demand for backhoes in trenching, grading, and material handling applications.
- Urban Utility Works:The expansion of utility infrastructure for telecommunications, water, and gas in dense urban environments requires compact, maneuverable equipment, stimulating demand for smaller backhoe models.
- Compact Model Versatility:The adoption of compact backhoes by landscaping firms and residential contractors is expanding the user base beyond traditional construction, valued for their ability to perform multiple tasks on smaller job sites.
Market Restraints
- High Electrification Cost:The significant price premium for electric and hybrid backhoes, stemming from expensive battery systems and power electronics, limits their adoption, especially among small to mid-sized contractors.
- Charging Infrastructure Gaps:The lack of reliable and accessible high-capacity charging infrastructure at remote or temporary construction sites presents a major logistical barrier to the deployment of electric backhoe fleets.
- Regulatory Compliance Burden:Meeting divergent and evolving engine emission standards, such as the EU's Stage V and the US EPA's Tier 4, increases R&D expenditure and manufacturing complexity for OEMs.
Strategic Opportunities
- Telematics-as-a-Service:Developing subscription-based services around integrated telematics data for predictive maintenance, fuel efficiency optimization, and asset tracking offers a new recurring revenue stream for manufacturers.
- Autonomous Feature Integration:Introducing semi-autonomous functions for repetitive tasks like digging or grading can enhance operator productivity, reduce fatigue, and improve job site safety, creating a new tier of premium features.
- Southeast Asia Expansion:Underpenetrated markets in Southeast Asian countries with growing infrastructure investment provide a significant opportunity for market entry and expansion, particularly for durable, mid-range diesel models.
Industry Challenges
- Skilled Operator Scarcity:A shortage of operators trained to utilize the advanced digital controls, telematics dashboards, and precision guidance systems featured in modern backhoes limits the realization of their full efficiency potential.
- Powertrain Supply Chain:Reconfiguring supply chains to secure a stable and cost-effective supply of batteries, electric motors, and control units for hybrid and electric models is a critical operational hurdle.
- R&D Investment Balancing:Manufacturers face the challenge of allocating capital investment between developing next-generation electric powertrains and continuing to refine cost-effective diesel engines for key developing markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Backhoes Market |
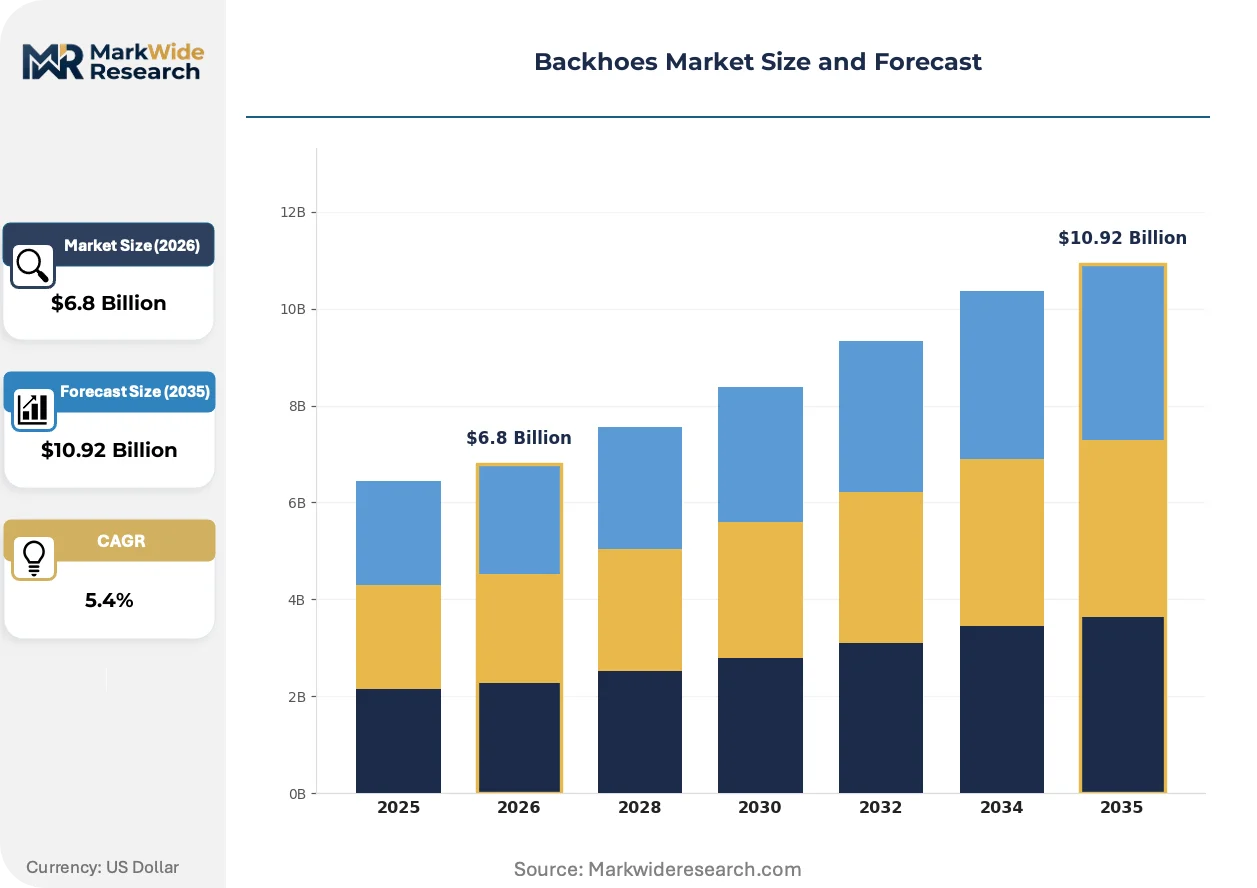
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compact Backhoes, Standard Backhoes, Wheeled Backhoes, Mini Backhoes, Tracked Backhoes Technology: Hydraulic, Mechanical, Pneumatic, Electric, Hybrid Application: Construction Sites, Landscaping Projects, Road Maintenance, Agricultural Operations, Utility Works End User: General Contractors, Landscaping Firms, Municipal Authorities, Utility Providers, Agricultural Enterprises |
| Companies Covered | Caterpillar Inc., JCB, John Deere, Case, Volvo Construction Equipment, Komatsu Ltd., CNH Industrial, Hitachi Construction Machinery, Kubota, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Backhoes Market Strategic Shifts & Innovations
Technological development in the backhoe market is bifurcating. Advanced telematics and electrification are defining the premium segment in regulated markets, while demand for robust, simple diesel machines continues to dominate volume in developing economies.
Integrated telematics systems provide real-time data on machine health, fuel consumption, and operator performance. Large-scale contractors and equipment rental fleets are adopting this technology to optimize asset utilization and schedule predictive maintenance. The focus on operational efficiency data is overtaking raw engine power as the primary differentiator in the premium equipment tier.
Mandates from the EU's Stage V and the US EPA's Tier 4 Final emission standards require significant reductions in diesel exhaust pollutants. This regulatory pressure is forcing powertrain redesigns toward advanced after-treatment systems and hybrid-electric architectures. The compact backhoe segment is particularly affected, where integrating bulky emissions control hardware into a small frame presents a considerable engineering challenge.
A behavioral shift from outright equipment ownership toward short-term rental and long-term leasing is gaining momentum among contractors. This trend elevates equipment rental companies into powerful procurement influencers, disrupting traditional manufacturer-to-dealer sales channels. This pattern is most pronounced in North America and Europe, where contractors seek greater flexibility in managing capital expenditures and fleet composition.
Backhoes Market Segmentation
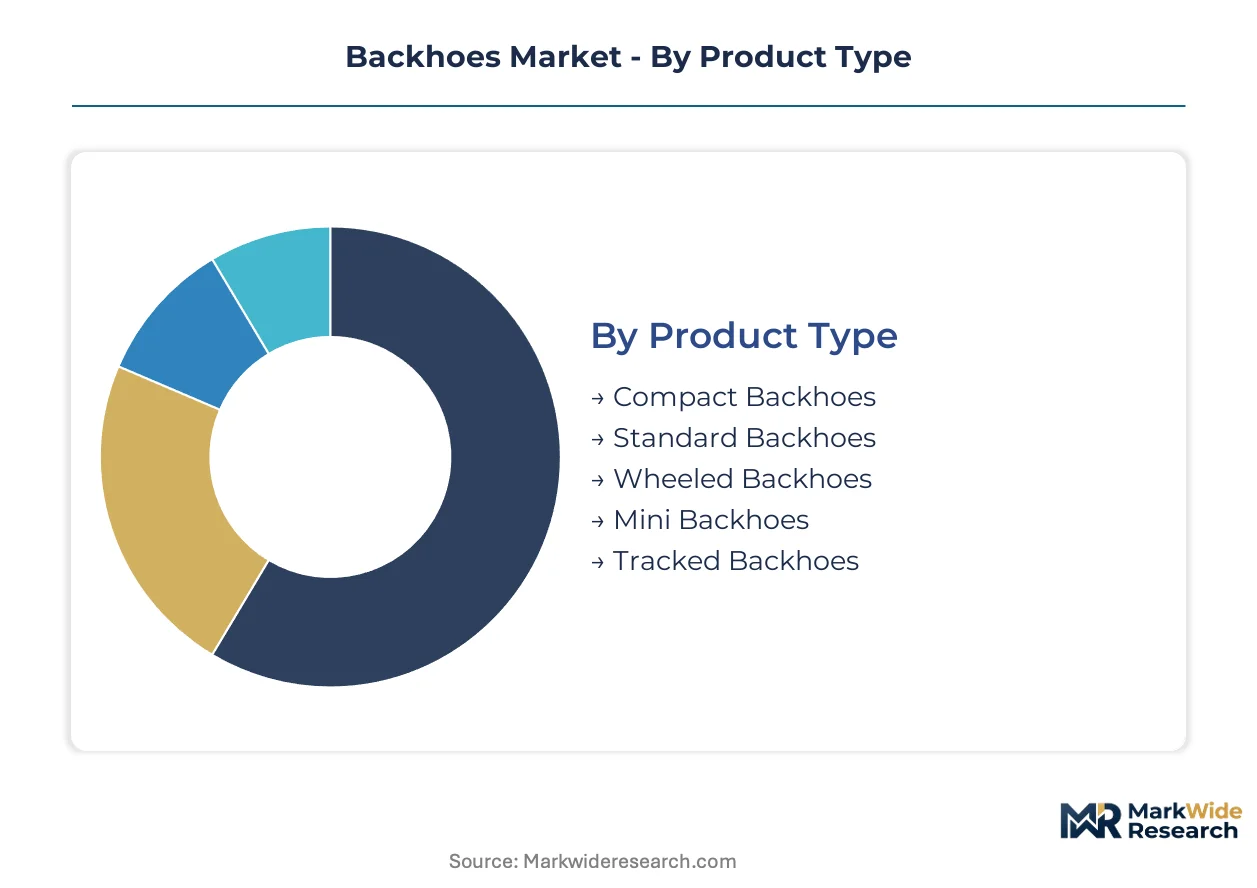
The Backhoes Market exhibits clear segmentation across product type, technology, application, and end-user categories. Understanding these distinctions is crucial for manufacturers to tailor product development and for contractors to optimize equipment selection. Each segment reflects unique operational demands and technological preferences.
Product Type:
Backhoe product types differentiate primarily by their operational scale and mobility characteristics, addressing diverse job site requirements.
- Compact Backhoes:These machines are characterized by their smaller footprint and enhanced maneuverability, making them ideal for confined spaces and urban utility work. Demand for compact models is expanding most quickly, driven by landscaping firms and residential contractors requiring versatile equipment.
- Standard Backhoes:These robust machines form the core of the market, designed for general construction tasks with digging depths typically ranging from 14 to over 20 feet. General contractors heavily rely on standard backhoes for trenching, excavation, and material handling on large construction sites.
- Wheeled Backhoes:These models offer superior on-road mobility and faster travel speeds between job sites, favored by road maintenance crews and municipal authorities.
- Mini Backhoes:Smaller than compact models, mini backhoes cater to highly restricted access areas and precision tasks, often used in gardening or indoor demolition.
- Tracked Backhoes:Providing enhanced stability and traction on uneven or soft terrain, tracked backhoes are preferred for heavy-duty excavation and challenging ground conditions.
Standard Backhoes lead on scale; Compact Backhoes lead on momentum.
Technology:
Technological advancements within backhoes are increasingly driven by specific operational requirements and environmental mandates.
- Electric:These backhoes utilize battery-electric powertrains, eliminating direct emissions and reducing noise pollution, particularly gaining traction in regulated markets like Europe and North America. The transition to electric models is spurred by stricter emissions regulations from the US EPA and the EU's Stage V.
- Hybrid:Combining a diesel engine with an electric motor, hybrid backhoes offer improved fuel efficiency and lower emissions compared to conventional diesel models. This technology provides a bridge solution for manufacturers balancing performance with environmental compliance and cost considerations.
- Hydraulic:The dominant technology, hydraulic systems power the digging arm and front loader, providing robust force and precise control for heavy-duty tasks.
- Mechanical:Older or simpler backhoe designs may incorporate mechanical linkages for certain functions, valued for their durability and ease of maintenance in developing economies.
- Pneumatic:While less common for primary functions, pneumatic systems can power auxiliary tools or specific control mechanisms, offering lightweight and flexible solutions.
The market for backhoe technology is evolving towards cleaner powertrain solutions, driven by regulatory pressures.
Application:
Backhoe applications are expanding beyond traditional construction, reflecting diverse demand patterns across various sectors.
- Utility Works:This segment includes trenching for telecommunications, water, and gas lines, particularly in dense urban environments requiring compact and precise equipment. Large-scale public infrastructure projects in India are driving significant demand for backhoes in utility installations.
- Construction Sites:The foundational application, encompassing excavation, material handling, and grading for commercial, residential, and industrial building projects. General contractors continue to rely on backhoes for their versatility on diverse construction tasks.
- Landscaping Projects:Backhoes are utilized for digging ponds, shaping terrain, and installing irrigation systems, valued by landscaping firms for their multi-functional capabilities.
- Road Maintenance:These machines assist in road repair, pothole filling, and shoulder work, offering efficiency for municipal authorities and private road contractors.
- Agricultural Operations:Backhoes support tasks like ditch digging, fence post installation, and material moving on farms, providing versatility for agricultural enterprises.
The versatility of backhoes across these applications underpins their continued relevance in infrastructure development.
End User:
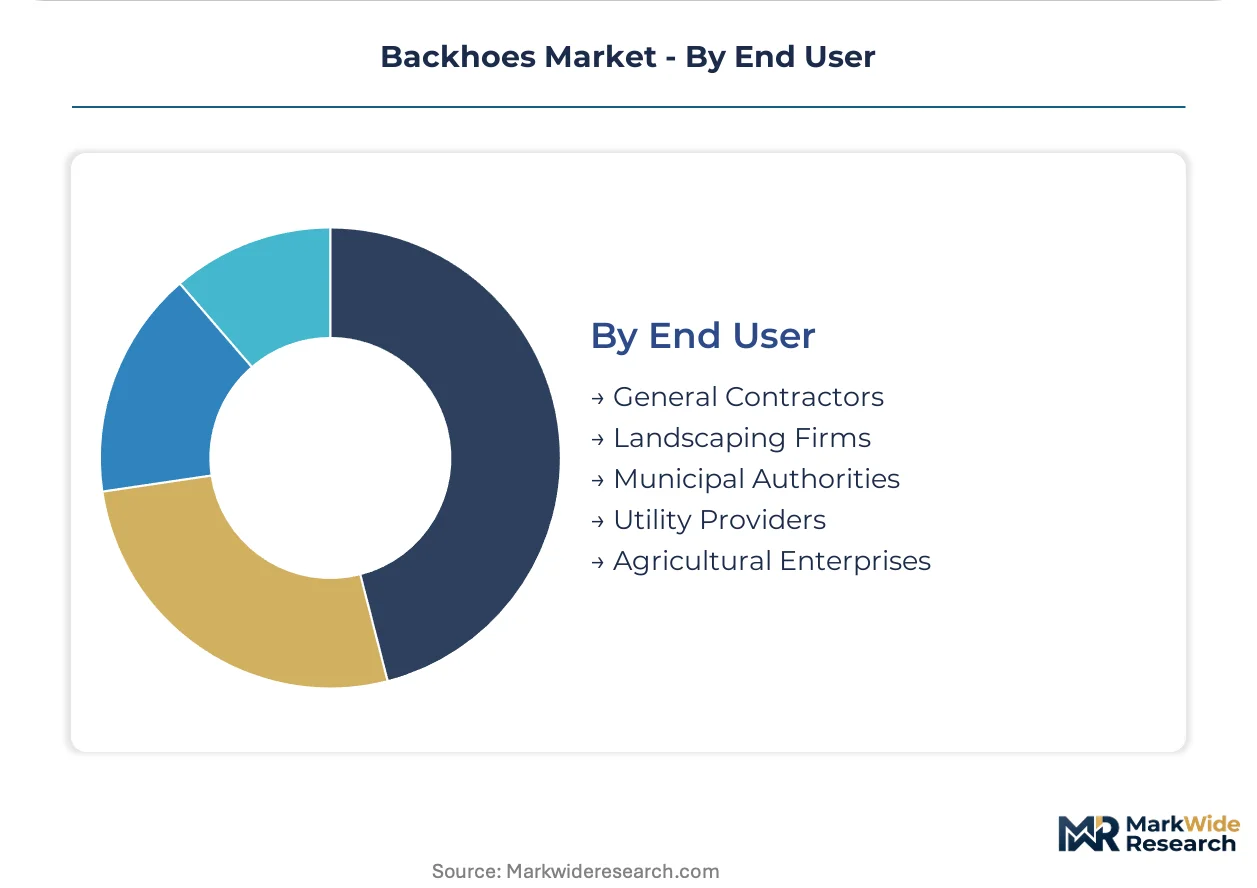
The procurement patterns for backhoes vary significantly among different end-user segments, each with distinct operational priorities.
- General Contractors:These large-scale operators demand high-performance, durable backhoes, often with advanced telematics, for a wide range of construction projects. They frequently invest in premium models from manufacturers like Caterpillar for efficiency and reliability.
- Utility Providers:Focused on infrastructure development and maintenance, these entities require compact and maneuverable backhoes for trenching and pipe-laying in urban areas. Their procurement decisions emphasize machine reliability and compliance with safety certifications like CE marking.
- Landscaping Firms:These businesses prioritize compact and versatile backhoes that can perform multiple tasks on smaller job sites, valuing ease of transport and operational flexibility.
- Municipal Authorities:Responsible for public works like road maintenance and urban development, municipalities seek durable and cost-effective backhoes for a variety of tasks.
- Agricultural Enterprises:Farmers and agricultural businesses utilize backhoes for diverse farm tasks, valuing robust and versatile machines that can withstand demanding conditions.
These diverse end-user groups collectively shape demand for both specialized and general-purpose backhoe models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global backhoe market sees talent concentrations in regions driving innovation and infrastructure development. Skilled operators and engineering expertise anchor regional growth. These concentrations facilitate the deployment of advanced machinery and sophisticated project management.
India
Large-scale public infrastructure projects and smart city initiatives are creating sustained demand for backhoes in India. The PLI scheme for manufacturing supports domestic production capabilities. The Delhi-NCR region, alongside Mumbai's ongoing infrastructure expansion, drives significant equipment deployment.
United States
General construction, landscaping, and utility works continue to drive demand for backhoes across the United States. US EPA's Tier 4 emission standards influence powertrain redesigns for cleaner operations. Texas's booming construction sector and California's urban development projects represent major consumption hubs.
Germany
Demand for compact and emission-compliant backhoes is strong within Germany, particularly for urban utility works. EU's Stage V regulations mandate cleaner engine technologies, impacting product development. Bavaria's industrial manufacturing base and the Rhine-Ruhr metropolitan area are key areas for equipment utilization.
Brazil
Agricultural operations and infrastructure projects across Brazil generate consistent demand for robust backhoe models. Environmental licensing requirements and national infrastructure programs influence procurement decisions. São Paulo state's diverse industrial and agricultural activities anchor significant market volume.
Australia
Mining operations and ongoing infrastructure development projects necessitate backhoe usage throughout Australia. National safety standards and environmental impact assessments govern equipment deployment. Western Australia's resource sector and New South Wales' infrastructure expansion drive equipment demand.
Backhoes Market Key Industry Players
Top-tier vendors anchor the premium segment, while mid-tier manufacturers address cost-sensitive markets. The backhoes market exhibits a tiered structure, with distinct competitive dynamics across segments. Manufacturers differentiate through technological sophistication and product versatility. Strategic archetypes include premium innovators, broad-spectrum providers, and specialized compact equipment suppliers. Companies engage in portfolio diversification and strategic partnerships to expand their market reach.
Within the premium and broad-spectrum tiers, Caterpillar Inc. exemplifies leadership in advanced telematics and integrated technology solutions. JCB occupies a position across a broader product range, including specialized compact models for niche applications. John Deere, a US-based company, represents a strong presence in the agricultural and landscaping sectors with durable, versatile machines.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| JCB |
| John Deere |
| Case |
| Volvo Construction Equipment |
| Komatsu Ltd. |
| CNH Industrial |
| Hitachi Construction Machinery |
| Kubota |
| Others |
Cost & Logistics Intelligence
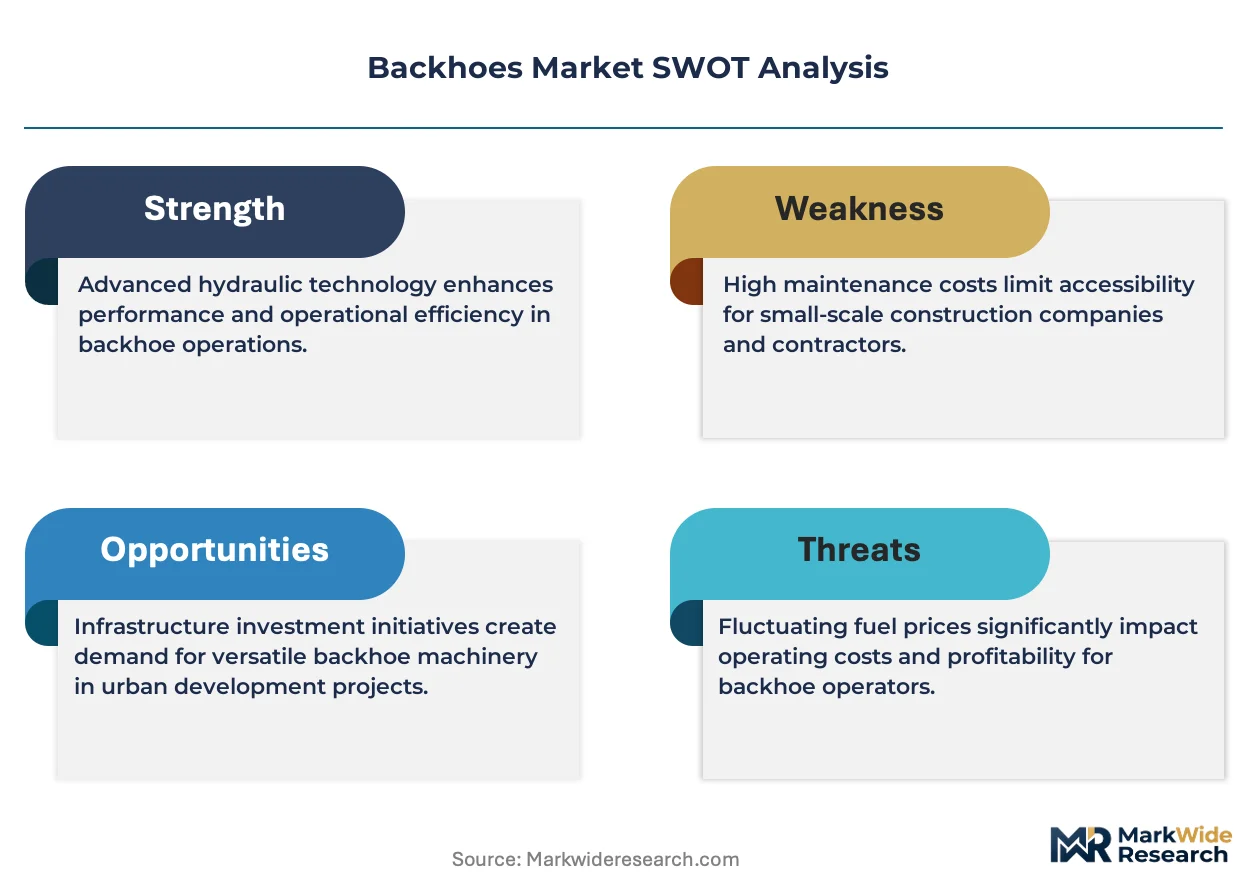
Diesel fuel price fluctuations directly impact backhoe operational costs, cascading into rental rates and equipment pricing for end-users, influencing demand for cleaner powertrains.
Pricing Analysis
Bundled after-sales service and telematics packages differentiate premium backhoe pricing from unbundled, transactional sales for standard models. The dominant pricing structure exhibits premium-mid-economy pricing differentiation across machine tiers. Brand premium and CE marking certification levels drive price differentiation in regulated markets. Pricing softness stems from intense competition among mid-tier manufacturers for cost-sensitive contractors. Landscaping firms are highly price-sensitive, while large general contractors prioritize long-term value.
Supply Chain Analysis
Elevated global logistics and ocean freight costs directly impact the landed price of backhoes and their components. Geographic supply concentration for critical components draws from China, Japan, and Germany. The market relies on specialized hydraulic systems and advanced engine control units. Single-source vulnerability for rare earth minerals used in electric motors presents a structural risk. Distribution runs through a network of regional dealers and rental fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The backhoe market is transforming into a late-cycle quality story, driven by a demand-shift towards premium specifications and advanced telematics for operational efficiency. Contractors increasingly seek sophisticated features for project optimization.
For Market Incumbents:To counter the threat of powertrain technology bifurcation, incumbents should deepen vertical integration into battery and electric motor production. Invest in advanced telematics R&D to maintain a premium tier advantage, offering subscription-based services. Pursue strategic partnerships with charging infrastructure providers to alleviate adoption barriers for electric models. Expand localized manufacturing in India to serve cost-sensitive, high-volume markets.
For New Entrants and Emerging Players:A significant price-point gap exists between premium, feature-rich backhoes and lower-cost, standard models, creating entry opportunities. Target the compact backhoe segment in Southeast Asian markets, which are underpenetrated and value durability. Focus on developing cost-effective hybrid models with essential digital features. A direct-to-contractor sales model, supported by strong local service networks, offers a compelling go-to-market angle.
For Investors and Strategic Acquirers:Consolidation pressure builds where regulatory compliance costs for powertrain redesigns strain smaller manufacturers. The long-term viability favors entities capable of balancing electrification investments with persistent diesel demand. Identify mid-sized specialized compact backhoe manufacturers as acquisition targets, particularly those with strong regional distribution. The signal to watch is the accelerated adoption rate of electric models in urban utility fleets.
| Strategic Initiative | Industry Significance |
|---|---|
| Powertrain Electrification Investment | This initiative addresses global emissions regulations, securing market access in developed economies. |
| Telematics-as-a-Service Offering | This initiative creates new recurring revenue streams and enhances asset utilization for large contractors. |
| Localized Manufacturing Expansion in India | This initiative captures demand from large-scale infrastructure projects and reduces logistics costs. |
| Compact Model Portfolio Diversification | This initiative penetrates landscaping firms and urban utility works, expanding the customer base. |
| Global Supply Chain Optimization | This initiative mitigates component scarcity and reduces manufacturing costs for key backhoe systems. |
Research Approach
Multiple input streams — primary interviews, industry reports, and trade statistics — were reconciled to construct a robust market view. Primary research involved discussions with equipment rental fleet managers, general contractors, and R&D directors at OEMs. Secondary data sources included government infrastructure spending reports, company financial filings, and regulatory body publications like US EPA and EU Stage V documents. This approach utilized both bottom-up market sizing and top-down validation.
Data-stream reconciliation integrated historical market performance with future projections across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, and end-user categories. Compound annual growth rates were derived from a multi-factor regression analysis. Key forecast inputs included infrastructure investment budgets and urban population growth rates.
Caveats apply where global economic slowdowns or unforeseen regulatory shifts could materially shift the outlook. Forecasts reflect assumptions regarding technological adoption rates and raw material price stability. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Smart Crane Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Baler Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
Static Crane Market
Construction Equipment
Global Desktop CNC Machines Market
Construction Equipment
Construction Power Rental Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Latin America Heavy Construction Equipment Rental Market
Construction Equipment
Global Construction Industry Core Drill Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Crawler Dozers Market