
 Commercial Sanitizing Equipment Market | 2026-2036
Commercial Sanitizing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Sanitizing Equipment Market Analysis
Multi-source procurement among hospital systems is hardening as supply-chain resilience replaces cost minimization in capital-equipment planning. STERIS plc sustains dominant manufacturing scale across autoclave and hydrogen peroxide vapor platforms. Getinge AB leverages integrated life-science and clinical workflows to anchor premium positioning in European healthcare infrastructure. Belimed specializes in washer-disinfector systems for central sterile supply departments, competing on validated cycle performance.
Commercial sanitizing equipment encompasses electromechanical and photochemical systems engineered to reduce pathogenic bioburden on surfaces, instruments, and ambient air through validated kill-log reductions, typically achieving 99.99% elimination of vegetative bacteria and enveloped viruses. These systems deploy ultraviolet-C irradiation at 253.7 nanometers, hydrogen peroxide vapor at 30-35% concentration, or electrostatically charged droplets at 40-80 microns for comprehensive coverage in occupied and unoccupied spaces. Ultraviolet Light technology leads installed base value due to proven efficacy against multidrug-resistant organisms in patient rooms. Chemical Disinfection via electrostatic sprayers represents the fastest-expanding segment as hospitality and retail operators seek rapid turnaround protocols between customer cycles. Surface Disinfection applications command the largest revenue pool, though Air Purification is gaining share as building ventilation standards tighten.
FDA 510(k) clearance requirements for sterilization devices shape product development timelines and clinical validation costs for manufacturers targeting US healthcare. EPA registration under FIFRA governs disinfectant chemistry claims and device compatibility, while OSHA bloodborne pathogen standards mandate employer provision of engineering controls including automated sanitizing equipment. EU MDR and REACH compliance add layers of biocompatibility and substance restriction testing for CE-marked systems. Stakeholders must monitor evolving state-level healthcare-acquired infection reporting mandates and building-code ventilation amendments that will redirect procurement budgets toward integrated sanitizing infrastructure.
Market Dynamics
Hospital procurement departments now prioritize validated kill-log documentation over capital cost minimization, forcing manufacturers to restructure R&D budgets toward clinical efficacy trials rather than feature differentiation.
Growth Catalysts
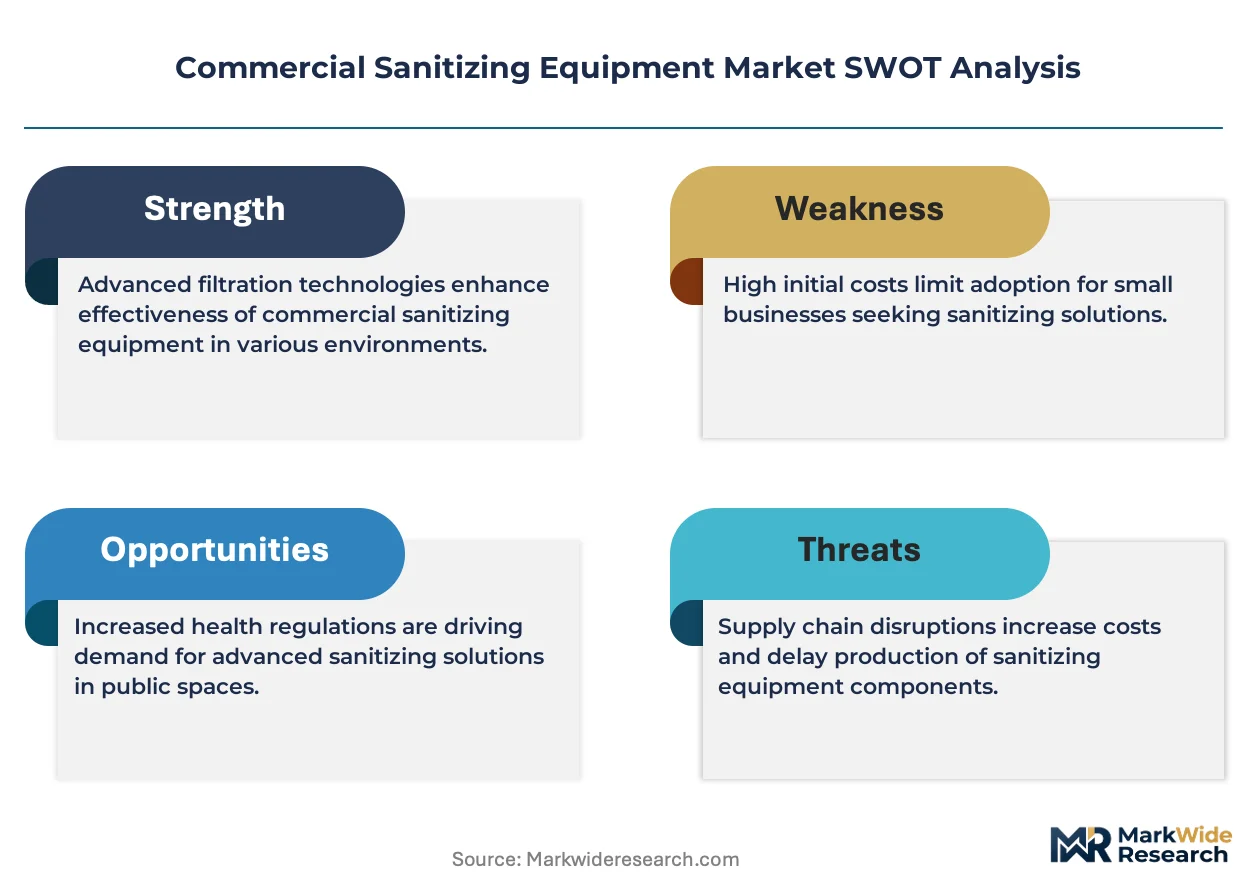
- Joint Commission Infection-Control Protocols:Tightened accreditation standards in United States healthcare facilities mandate automated sterilization documentation, pulling capital toward UV-C and hydrogen peroxide vapor platforms.
- Electrostatic Sprayer Chemistry:Precision-applied disinfection systems are displacing manual wiping protocols in German hospital networks, reducing surface contact time while improving coverage uniformity.
- Supply-Chain Resilience Mandates:Multi-source procurement requirements among consolidated hospital systems are expanding vendor qualification pools beyond traditional single-source relationships.
Market Restraints
- Copper and Rare-Earth Magnet Costs:UV-C lamp ballasts and electrostatic charging assemblies depend on concentrated upstream supply from limited smelter capacity, creating input price volatility.
- Technical Efficacy Limitations:Shadowing effects in UV-C systems and humidity-dependent hydrogen peroxide vapor distribution restrict validated performance in complex architectural geometries.
- FDA 510(k) Timeline Friction:Clinical validation requirements for new sterilization claims extend product development cycles by 18-36 months, compressing effective patent windows.
Strategic Opportunities
- Air Purification Infrastructure:Tightened building ventilation standards in commercial real estate are redirecting procurement budgets toward integrated sanitizing systems for occupied spaces.
- UV-C LED Convergence:Solid-state ultraviolet sources merging with IoT sensor networks enable dynamic dosage adjustment based on real-time bioburden detection.
- India Hospital Modernization:Central government health infrastructure programs are creating first-mover advantage for automated sterilization vendors in tier-2 and tier-3 city networks.
Industry Challenges
- Validation Engineer Scarcity:Microbiological efficacy testing and regulatory submission expertise concentrates among a limited pool of specialists, constraining manufacturer scale-up velocity.
- Legacy Building Integration:Retrofitting hydrogen peroxide vapor systems into existing HVAC infrastructure requires structural modifications that disrupt facility operations during installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Sanitizing Equipment Market |
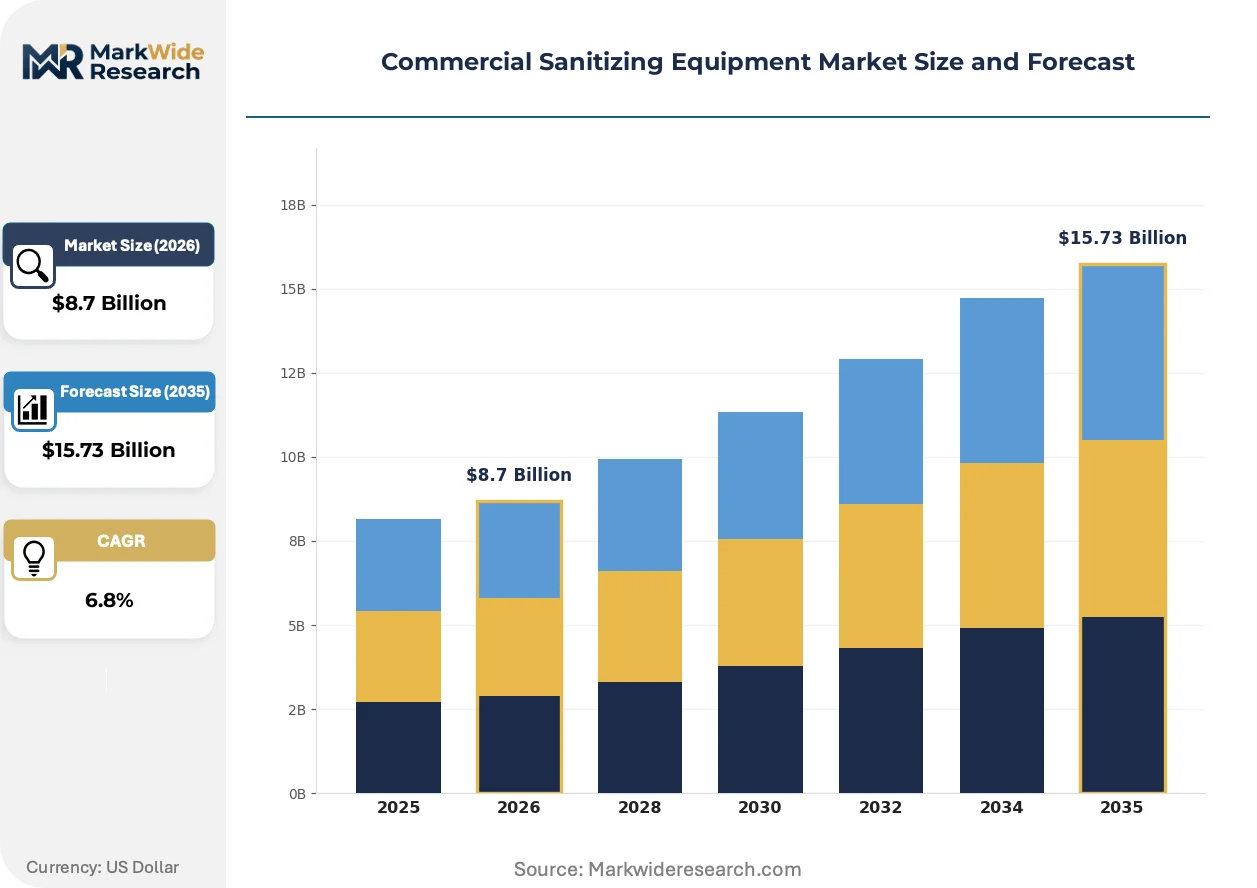
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Disinfectors, Fogging Machines, UV-C Sterilizers, Electrostatic Sprayers Technology: Ultraviolet Light, Chemical Disinfection, Ozone Treatment, Heat Treatment End User: Healthcare Facilities, Hospitality Industry, Educational Institutions, Retail Stores Application: Surface Disinfection, Air Purification, Equipment Sterilization, Vehicle Sanitization |
| Companies Covered | STERIS plc, Getinge AB, Belimed, Cantel Medical Corp., CISA production srl, Bactronix Corporation, TSO3 Inc., Matachana Group, SAKURA SI Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Sanitizing Equipment Market Emerging Trajectories
Equipment manufacturers are converging photochemical and electromechanical modalities into single-platform systems, collapsing the traditional segmentation between surface and air sanitization while compressing facility footprint requirements.
Pulsed xenon ultraviolet systems are overtaking continuous low-pressure mercury lamps in United States healthcare settings. These solid-state sources deliver higher peak irradiance with reduced warm-up latency. Academic medical centers in Texas and California are piloting installations that compress terminal room disinfection cycles from 45 minutes to under 15 minutes.
EU MDR biocompatibility testing requirements for sterilization devices are forcing manufacturers to revalidate legacy product lines under stricter substance restriction protocols. The REACH authorization list now governs nickel and chromium release from stainless-steel chamber components. German and French notified bodies are extending CE-marking review timelines, compressing product launch windows for European market entry.
Facility managers are unbundling equipment purchase from validation service contracts, treating clinical efficacy documentation as a separately procured professional service. This disintermediation is fragmenting vendor relationships in United States hospital networks. Group purchasing organizations are responding by certifying independent microbiological testing laboratories, creating alternative pathways to procurement compliance.
Commercial Sanitizing Equipment Market Segmentation
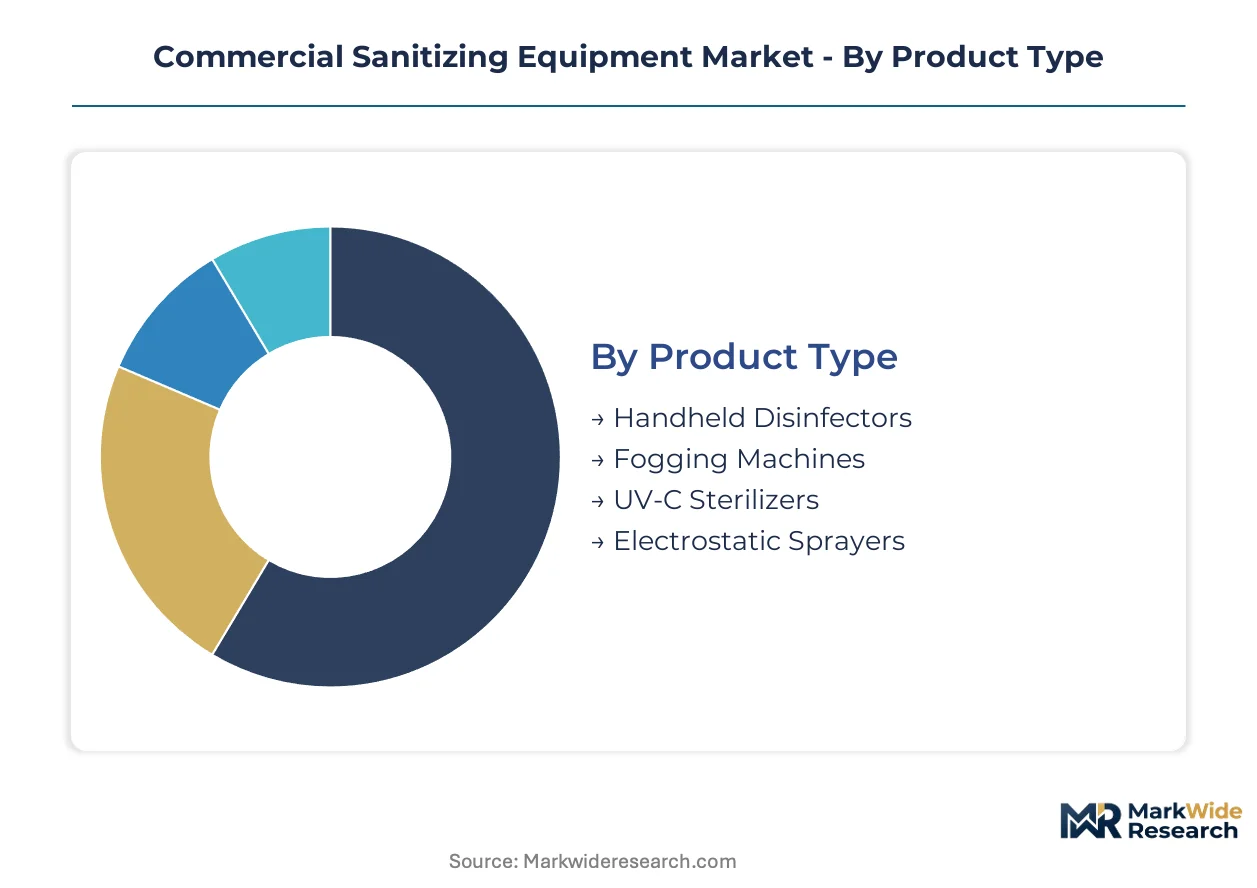
Segmentation in commercial sanitizing equipment reveals how technology integration depth varies across deployment contexts. Standalone units serve mobile remediation needs while embedded infrastructure dominates permanent facility installations. Procurement patterns diver sharply between these modalities.
Product Type:
Integration depth splits sharply: handheld and electrostatic units operate as portable point solutions, while UV-C sterilizers and fogging machines embed into fixed infrastructure or scheduled protocols.
- UV-C Sterilizers:These systems deploy 253.7-nanometer irradiation through mercury vapor or pulsed xenon sources to achieve validated 6-log pathogen reduction. Demand concentrates in United States academic medical centers where Joint Commission documentation requirements mandate automated sterilization records. Tightened infection-control protocols are displacing manual terminal cleaning in California and Texas hospital networks.
- Electrostatic Sprayers:Charged droplet systems at 40-80 microns deliver precision-applied chemical disinfection with 360-degree surface coverage. German hospital networks are replacing manual wiping protocols with these units to reduce surface contact time while improving coverage uniformity in patient rooms and surgical suites.
- Handheld Disinfectors:Portable chemical application devices serve spot-sanitization needs in retail and hospitality settings where rapid turnaround between customer cycles is essential.
- Fogging Machines:Aerosol dispersion systems enable whole-room treatment in unoccupied spaces, finding placement in educational institutions and vehicle fleets where area coverage speed outweighs precision requirements.
Volume placements concentrate in UV-C Sterilizers; the faster expansion belongs to Electrostatic Sprayers.
Technology:
Cost stratification follows energy input and consumable requirements: photochemical methods carry higher capital intensity while thermal and chemical approaches spread operating expenses across recurring supply chains.
- Ultraviolet Light:UV-C irradiation at germicidal wavelengths achieves 99.99% elimination of vegetative bacteria and enveloped viruses without chemical residue. United States healthcare facilities expanding automated sterilization procurement favor this modality for multidrug-resistant organism control in patient rooms.
- Chemical Disinfection:EPA-registered disinfectant chemistry delivered through electrostatic or mechanical means enables rapid deployment across hospitality and retail operator networks. This segment is climbing the fastest as facility managers prioritize turnaround speed over capital investment minimization.
- Ozone Treatment:O3 generation systems provide unoccupied-space sanitization through oxidative degradation of organic contaminants, constrained by OSHA exposure limits requiring post-treatment ventilation cycles.
- Heat Treatment:Thermal inactivation via steam or dry heat achieves sporicidal efficacy in instrument processing, anchoring central sterile supply department workflows in hospital infrastructure.
Capital deployment tilts toward Ultraviolet Light in permanent installations; Chemical Disinfection captures the steepest expansion trajectory in mobile and contract applications.
End User:
Customer type determines validation rigor and procurement channel: healthcare demands FDA 510(k) documentation while hospitality and retail prioritize speed and operational simplicity.
- Healthcare Facilities:Hospitals and outpatient clinics require validated kill-log documentation and automated sterilization records for Joint Commission compliance. United States procurement departments now prioritize clinical efficacy trials over feature differentiation in capital-equipment planning.
- Hospitality Industry:Hotels and food-service operators seek rapid turnaround protocols between guest or customer cycles, driving electrostatic sprayer adoption for surface coverage speed.
- Educational Institutions:Schools and universities balance budget constraints with occupancy safety, favoring fogging and chemical systems for periodic deep-cleaning protocols.
- Retail Stores:High-traffic commercial spaces deploy handheld and electrostatic units for point-of-sale and fitting room sanitization between customer interactions.
Procurement volume concentrates in Healthcare Facilities; Hospitality Industry represents the fastest-growing customer category as service-sector sanitization protocols normalize.
Application:
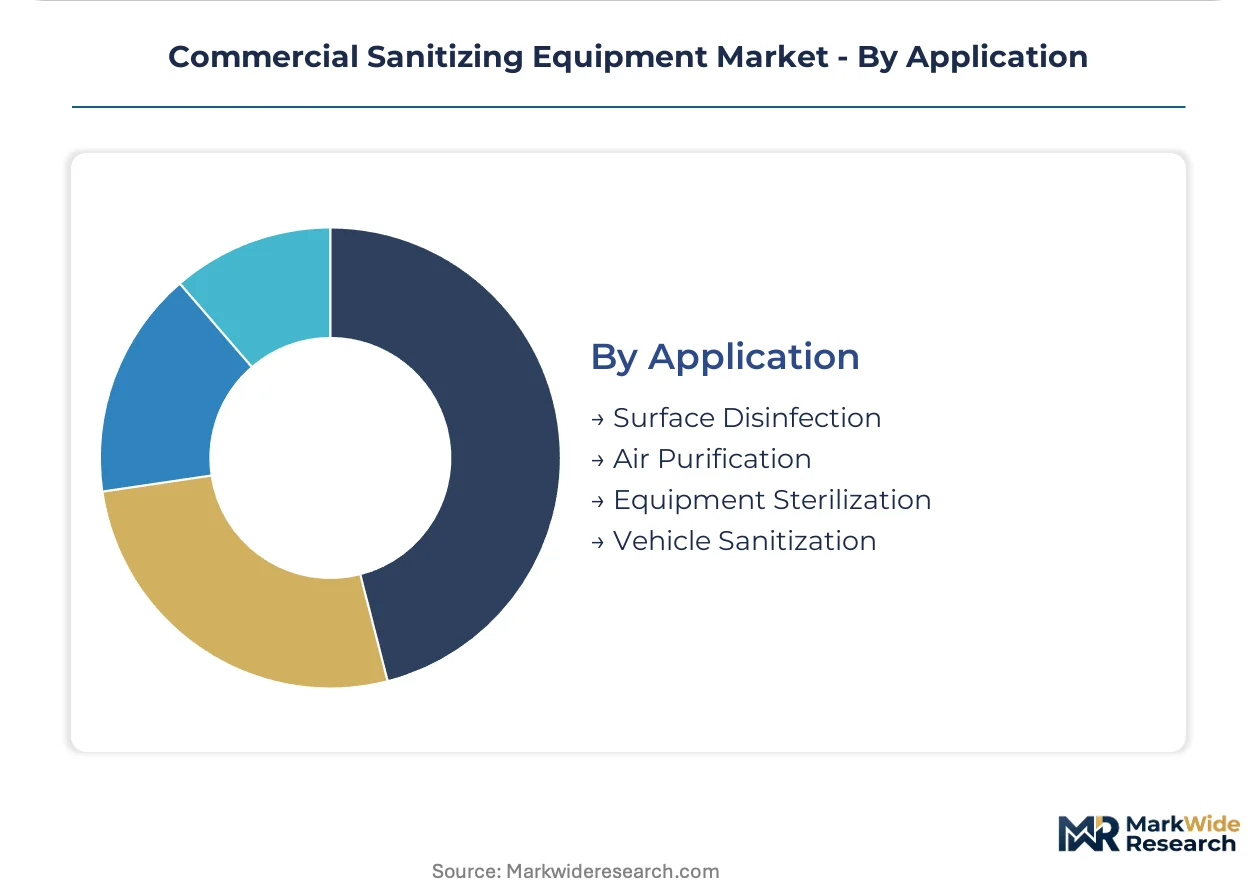
Application scope spans surface contact, airborne, and instrument-specific domains, with regulatory frameworks diverging between EPA FIFRA registration for chemical claims and FDA device clearance for sterilization assertions.
- Surface Disinfection:Direct-contact sanitization of high-touch environmental surfaces commands the largest revenue pool across all end-user categories. German hospital networks exemplify the shift from manual wiping to precision-applied electrostatic systems.
- Air Purification:Ambient air treatment through UV-C upper-room fixtures or filtration-irradiation hybrids is gaining share as building ventilation standards tighten in commercial real estate.
- Equipment Sterilization:Instrument and device processing in central sterile supply departments relies on validated autoclave and hydrogen peroxide vapor cycles.
- Vehicle Sanitization:Fleet and public-transport treatment protocols employ fogging and electrostatic systems for rapid interior coverage.
Revenue concentration sits with Surface Disinfection; Air Purification is expanding most quickly as HVAC-integrated sanitizing infrastructure receives procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in the United States are expanding automated UV-C sterilizer installations faster than any other geography. German hospital networks are replacing manual wiping protocols with electrostatic sprayer systems at comparable velocity. India's central government health infrastructure programs are creating first-mover opportunities in tier-2 and tier-3 city networks.
United States
Academic medical centers in Texas and California are piloting pulsed xenon UV-C installations that compress terminal room disinfection cycles from 45 minutes to under 15 minutes. FDA 510(k) clearance requirements shape product development timelines and clinical validation costs for manufacturers targeting healthcare facilities. Group purchasing organizations are certifying independent microbiological testing laboratories in response to facility managers unbundling equipment purchase from validation service contracts.
Germany
Hospital networks are concentrating electrostatic sprayer demand as facilities replace manual wiping protocols with precision-applied chemical disinfection systems. EU MDR biocompatibility testing requirements are forcing manufacturers to revalidate legacy product lines under stricter substance restriction protocols. Notified bodies in Frankfurt and Munich are extending CE-marking review timelines, compressing product launch windows for European market entry.
India
Central government health infrastructure programs are creating first-mover advantage for automated sterilization vendors in tier-2 and tier-3 city networks. CDSCO medical device regulations are tightening registration requirements for imported sterilization equipment. Hospital modernization clusters in Maharashtra and Karnataka are expanding procurement of washer-disinfector systems for central sterile supply departments.
Japan
Healthcare facilities are integrating UV-C upper-room fixtures into building ventilation upgrades as METI tightens commercial real estate sanitation standards. PMDA consultation procedures for novel sterilization devices are extending pre-market review durations for foreign manufacturers. Medical device distributors in Osaka and Nagoya are building validation service capabilities to support imported equipment compliance.
United Kingdom
NHS procurement frameworks are prioritizing validated kill-log documentation over capital cost minimization in infection-control equipment tenders. MHRA post-Brexit medical device regulations are creating parallel registration pathways distinct from EU MDR processes. Hospital trusts in London and Manchester are piloting hydrogen peroxide vapor systems for multidrug-resistant organism control in intensive care units.
Commercial Sanitizing Equipment Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers respond to hardened multi-source procurement requirements among consolidated hospital systems. The vendor base stratifies across three tiers: multinational platform specialists with integrated life-science workflows, regional washer-disinfector specialists competing on validated cycle performance, and emerging electrostatic sprayer fabricators serving hospitality and retail operators. Strategic archetypes include scale-driven autoclave manufacturers, precision-chemistry application specialists, and solid-state UV-C technology developers. M&A activity and geographic licensing partnerships represent the dominant competitive moves as firms seek to compress FDA 510(k) timeline friction through acquired regulatory expertise.
Within the multinational platform tier, STERIS plc and Getinge AB occupy positions as scale-driven archetypes with dominant manufacturing footprints across autoclave and hydrogen peroxide vapor platforms. Belimed represents the regional specialist archetype, anchoring washer-disinfector system supply for central sterile supply departments. These three entities exemplify how competitive positioning hardens around validated clinical efficacy documentation rather than feature differentiation as hospital procurement departments restructure vendor qualification pools.
| Leading Market Players |
|---|
| STERIS plc |
| Getinge AB |
| Belimed |
| Cantel Medical Corp. |
| CISA production srl |
| Bactronix Corporation |
| TSO3 Inc. |
| Matachana Group |
| SAKURA SI Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Copper and rare-earth magnet costs in UV-C lamp ballasts and electrostatic charging assemblies flow through concentrated smelter capacity in China and the Democratic Republic of Congo, compressing margins for mid-tier manufacturers while premium-tier vendors pass through input volatility via long-term service contracts with United States hospital systems.
Pricing Analysis
Volume placements concentrate in standard-tier autoclave and washer-disinfector systems sold through group purchasing organizations, while premium-tier hydrogen peroxide vapor platforms capture disproportionate margin through bundled validation services. Price differentiation hinges on FDA 510(k) clearance tier and Joint Commission documentation capabilities. Cost compression in the electrostatic sprayer segment is intensifying as hospitality procurement shifts toward rapid-turnover chemical application systems. Healthcare facilities demonstrate lowest price sensitivity due to accreditation compliance mandates, whereas educational institutions and retail operators prioritize capital minimization.
Supply Chain Analysis
Validation engineer scarcity across Germany, the United States, and Switzerland constrains manufacturer scale-up velocity for clinical efficacy documentation. Component sourcing draws from mercury vapor lamp foundries in China, precision pump assemblies in Germany, and stainless-steel chamber fabrication in India. Single-source vulnerability concentrates in EPA-registered disinfectant chemistry supply for electrostatic systems. Distribution runs through medical device distributors with GPO contracting capabilities in United States hospital networks and specialized hygiene service providers in European healthcare infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commercial sanitizing equipment supply is tightening around validation engineering capacity, with microbiological efficacy testing bottlenecks propping pricing power for incumbents with in-house regulatory expertise.
For Market Incumbents: Cement dominance through backward integration into UV-C LED solid-state source manufacturing and captive validation service capabilities in Texas and California academic medical center corridors. Acquire regulatory submission expertise to compress FDA 510(k) timeline friction. Channel control through exclusive GPO contracting relationships defends against emerging electrostatic sprayer fabricators. For New Entrants and Emerging Players: Enter via India's tier-2 and tier-3 city hospital modernization programs where CDSCO registration requirements are tightening but first-mover advantage remains available. Target hospitality sector electrostatic sprayer demand in German networks replacing manual wiping protocols. White-space exists in IoT-integrated UV-C dosage adjustment systems for occupied-space air purification. For Investors and Strategic Acquirers: Pulsed xenon UV-C installation velocity in Texas and California academic medical centers is the leading indicator that solid-state technology convergence will reshape platform economics. Position for five-to-ten year horizon around vendors with integrated photochemical-electromechanical modalities and software companion development capabilities. Acquisition target archetype: regional washer-disinfector specialists with validated cycle performance documentation and European CE-marking expertise.| Strategic Initiative | Industry Significance |
|---|---|
| UV-C LED Technology Convergence | Solid-state sources merging with IoT sensor networks enable dynamic dosage adjustment based on real-time bioburden detection in patient rooms. |
| Validation Service Unbundling Response | Independent microbiological testing laboratory certification through GPOs creates alternative procurement compliance pathways for hospital networks. |
| India Hospital Modernization Entry | Central government health infrastructure programs in Maharashtra and Karnataka create first-mover advantage for automated sterilization vendors. |
| EU MDR Revalidation Investment | Biocompatibility testing under stricter REACH substance restriction protocols extends CE-marking timelines for European market entry. |
| Multi-Source Procurement Qualification | Supply-chain resilience mandates among consolidated United States hospital systems expand vendor qualification pools beyond traditional relationships. |
Methodological Framework
Independent corroboration across hospital procurement database analysis, EPA FIFRA registration records, and FDA 510(k) submission filings underwrites the qualitative findings. Primary interviews with biomedical engineers, GPO contracts managers, hospital purchasing committee chairs, and aftermarket service heads combined with secondary validation from customs trade data, SEC 10-K equipment manufacturer disclosures, and Joint Commission accreditation reports. Bottom-up installation tracking and top-down market sizing triangulate volume estimates.
Comparable-period anchoring to historical procurement cycles in United States academic medical centers and German hospital networks structured the projection horizon. Segmentation modeling spanned technology modality, integration depth, end-user category, and application scope across surface disinfection, air purification, and equipment sterilization. CAGRs derived from regression analysis against tightened infection-control protocol adoption curves and building ventilation standard amendment timelines. Forecast inputs incorporated copper and rare-earth magnet price volatility indices alongside validation engineer labor market tightness metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt FDA 510(k) timeline extensions or REACH authorization list amendments affecting stainless-steel component sourcing. Material deviation in Joint Commission protocol enforcement intensity or central government health infrastructure program disbursement velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Grinding Machinery Market
Construction Equipment
India Crane Market
Construction Equipment
Construction Equipment Rental Market
Construction Equipment
Construction Lasers Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Global Crane Market
Construction Equipment
United States Completion Equipment and Services Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Manual Welding Positioner Market
Construction Equipment
Backhoes Market
Construction Equipment
Street Cleaning Machine Market
Construction Equipment
Boring Bar Market
Construction Equipment
India Construction Equipment Market