
 Snow Pushers Market | 2026-2036
Snow Pushers Market Size, Share, and Industry Trends Forecast 2026-2036
Snow Pushers Market Outlook
Skilled welder and fabricator availability is reorganizing production capacity across the snow pushers supply base. Pro-Tech Manufacturing and Distribution Inc leverages its Wisconsin-based fabrication network to sustain year-round output despite seasonal demand spikes. Kage Innovation LLC anchors its position through proprietary quick-attach systems that differentiate its product line in the contractor segment. Fisher Engineering competes aggressively in the municipal procurement channel where specifications favor heavy-duty steel construction.
A snow pusher is a wheeled or vehicle-mounted blade attachment designed to displace accumulated snow across horizontal surfaces, typically fabricated from hardened steel or high-density polyethylene with operating widths ranging from six to thirty feet and reinforced cutting edges for pavement contact. Its primary commercial purpose is bulk snow relocation for parking lots, roadways, and industrial yards where precision grading is secondary to volume throughput. Motorized and heavy-duty configurations dominate municipal and industrial procurement due to their durability under continuous operation, while plastic and composite materials represent the fastest-growing material category as operators seek reduced fuel consumption and corrosion resistance. Contractors and landscaping services drive replacement demand toward lighter aluminum and composite variants that permit faster mounting on mid-size utility vehicles.
FAA snow removal standards for airport operations, NHTSA transport regulations for oversize attachment hauling, and OSHA workplace safety requirements for operator visibility and guarding collectively shape product certification and market access thresholds across North America. Municipal procurement codes in Minnesota, Wisconsin, and Michigan increasingly mandate domestic steel content and ISO-compliant welding protocols, tightening vendor qualification criteria. Stakeholders must monitor how state-level Buy American provisions and evolving EPA Tier 4 emissions compliance for host vehicles reshape attachment compatibility requirements and replacement cycle timing.
Market Dynamics
EPA Tier 4 emissions standards for host vehicles are compressing attachment compatibility windows and accelerating replacement cycles across municipal and contractor fleets.
Growth Catalysts
- Municipal fleet modernization:Upper Midwest municipalities in Minnesota, Wisconsin, and Michigan are replacing legacy equipment with ISO-compliant welded attachments that meet domestic steel procurement codes.
- REACH-compliant material substitution:High-density polyethylene and aluminum alloys are displacing traditional steel in mid-size utility vehicle configurations, reducing fuel consumption and corrosion maintenance.
- Airport surface operations:FAA snow removal standards for Part 139 certificated airports mandate specialized blade geometries and visibility requirements that sustain premium equipment demand.
Market Restraints
- Steel input cost volatility:Hardened steel plate and cutting edge alloy prices fluctuate with scrap metal and energy markets, compressing fabrication margins.
- Welder supply concentration:Skilled AWS-certified welder availability concentrates in the Great Lakes manufacturing corridor, limiting production scaling outside this geography.
- OSHA visibility compliance:Operator sightline requirements for blade-mounted equipment create design constraints that increase engineering cycle times.
Strategic Opportunities
- Quick-attach system convergence:Proprietary coupling mechanisms that interface with multiple OEM loader arms create aftermarket attachment ecosystems.
- Canadian municipal expansion:Prairie provinces are adopting US-style fleet standardization programs, opening cross-border procurement channels.
- Lightweight composite penetration:Carbon fiber-reinforced polymer blades offer corrosion immunity for coastal and chemically treated roadway applications.
Industry Challenges
- AWS D1.1 certification timelines:Welding procedure qualification and welder performance qualification delays extend production ramp-up for new fabrication facilities.
- Legacy hydraulic integration:Attachment compatibility with aging municipal loader fleets requires adaptive valve and coupler engineering that fragments product SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Snow Pushers Market |
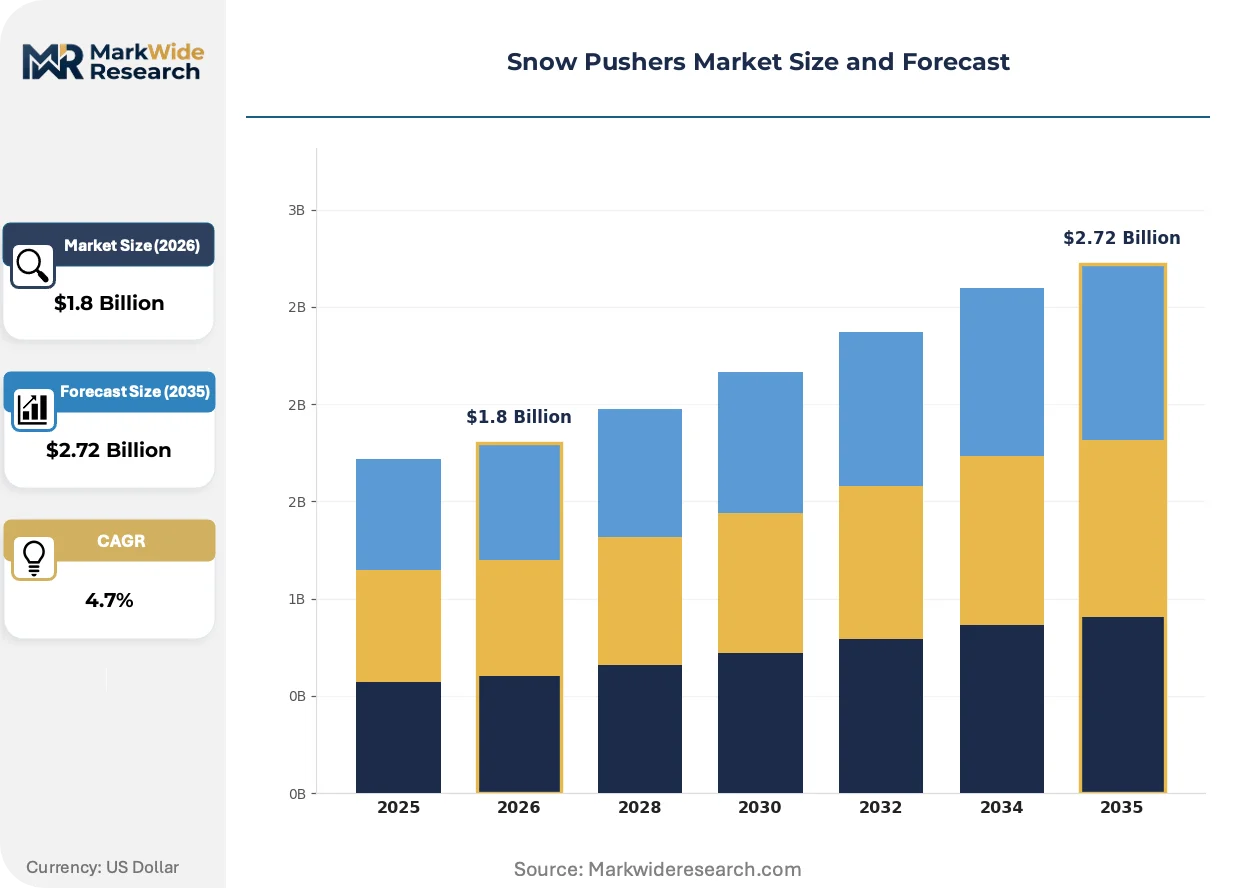
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Snow Pushers, Motorized Snow Pushers, Heavy-Duty Snow Pushers, Commercial Snow Pushers Material: Plastic, Steel, Aluminum, Composite End User: Residential Customers, Contractors, Municipalities, Landscaping Services Application: Residential Use, Commercial Use, Industrial Use, Municipal Use |
| Companies Covered | Craig Manufacturing Ltd, HLA Snow, Pro-Tech Manufacturing and Distribution Inc, Rockland Manufacturing Company, SnowWolf, Rylind Manufacturing Inc, Kage Innovation LLC, BD Manufacturing, Fisher Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Snow Pushers Market Strategic Shifts
Attachment material science and procurement digitization are restructuring how fleets specify, source, and deploy snow removal equipment across seasonal contracting operations.
Polyethylene blade technology is fragmenting traditional steel-dominated product hierarchies. Municipal operators in corrosion-prone regions are specifying molded high-density polyethylene cutting edges for salt-resistant performance. This material shift is fragmenting supplier bases as polymer processors enter a market previously controlled by metal fabricators.
EPA enforcement of Tier 4 Final standards for off-road diesel engines is forcing municipal procurement departments to verify attachment weight compatibility with newer, emissions-compliant host vehicles. Procurement specifications now routinely cite axle load limits and hydraulic flow requirements that exclude legacy heavy steel designs. Midwestern state DOTs are revising bid documents to prioritize lighter attachments that preserve vehicle emissions certification.
Seasonal contractor purchasing behavior is compressing traditional equipment replacement cycles. Landscaping services that previously operated 7-10 year attachment lifespans are now cycling equipment at 4-5 year intervals to maintain fleet eligibility for municipal subcontracting opportunities. This pattern concentrates demand spikes in late summer procurement windows, straining fabrication capacity and reshaping distributor inventory strategies across the Upper Midwest.
Snow Pushers Market Segmentation
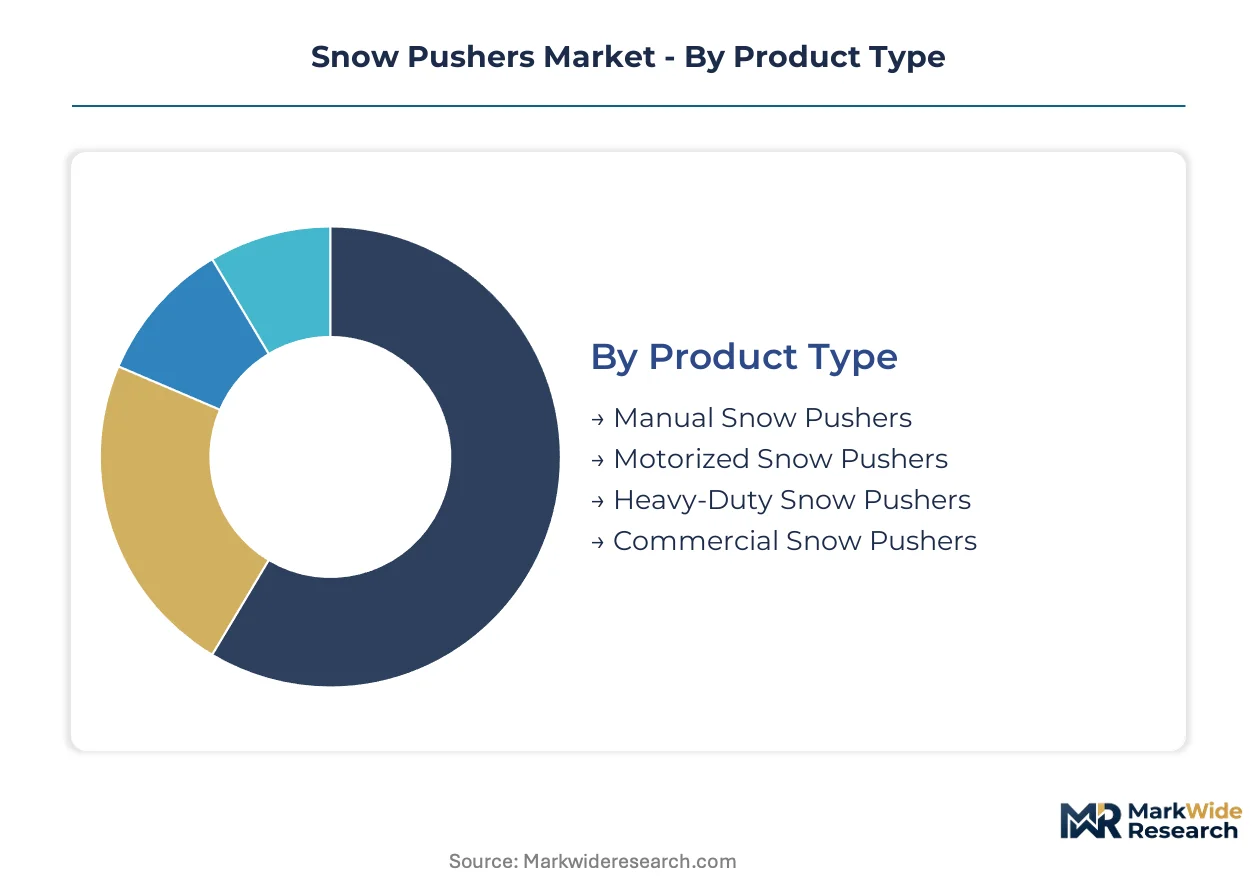
Segmentation in snow pushers determines procurement channel access and margin structure. Material substitution and end-user specification divergence are fragmenting traditional product hierarchies across municipal, contractor, and residential demand pools.
Product Type:
Heavy-duty steel configurations face acute substitution pressure from lightweight motorized alternatives as EPA Tier 4 axle load limits tighten procurement specifications.
- Motorized Snow Pushers:Hydraulic-actuated blade systems integrate with loader arms and skid steers through standardized quick-attach interfaces. Municipal fleets in Minnesota and Wisconsin specify these for continuous-duty roadway clearing where hydraulic flow rates and vehicle emissions certification determine bid eligibility.
- Heavy-Duty Snow Pushers:Reinforced steel construction with hardened cutting edges withstands curb impact and abrasive pavement contact. Industrial yard operators in Michigan's manufacturing corridors specify these for 24-hour snow relocation during lake-effect storm events.
- Manual Snow Pushers:Human-propelled wheeled blades for residential driveway clearing.
- Commercial Snow Pushers:Mid-duty configurations balancing durability with mounting versatility for contractor fleet flexibility.
Heavy-duty snow pushers anchor the volume base while motorized snow pushers gain share at the steepest rate.
Material:
Cost tier stratification separates premium corrosion-resistant alloys from commodity steel as fuel efficiency and maintenance burden reshape lifecycle economics.
- Steel:Hardened plate construction with alloy cutting edges delivers maximum impact resistance and field repairability. Municipal procurement codes in the Upper Midwest increasingly mandate domestic steel content and AWS D1.1 welding protocols, tightening vendor qualification.
- Composite:Carbon fiber-reinforced polymer and fiberglass hybrid structures eliminate corrosion maintenance for coastal and chemically treated roadway applications. Landscaping services in corrosion-prone regions specify these to extend replacement cycles and reduce fuel consumption on mid-size utility vehicles.
- Plastic:Molded high-density polyethylene cutting edges and blade surfaces for salt-resistant performance.
- Aluminum:Lightweight alloy structures permitting faster mounting and reduced axle loading.
Steel dominates installed base volume while composite materials climb the fastest as specification standards evolve.
End User:
Customer type concentration varies sharply by procurement channel, with municipal bid processes imposing certification barriers that exclude residential and small-contractor suppliers.
- Municipalities:State DOT and county highway departments procure through formal bid processes specifying ISO-compliant welding, domestic steel content, and Tier 4 vehicle compatibility. Minnesota, Wisconsin, and Michigan DOTs revise specifications annually to prioritize lighter attachments that preserve emissions certification.
- Contractors:Seasonal snow removal services cycle equipment at compressed 4-5 year intervals to maintain municipal subcontracting eligibility. These operators concentrate demand spikes in late summer procurement windows, straining fabrication capacity.
- Residential Customers:Individual property owners purchasing manual or light-duty motorized units for driveway and sidewalk clearing.
- Landscaping Services:Multi-service grounds maintenance firms seeking mounting versatility across seasonal equipment fleets.
Municipalities anchor the volume base while contractors expand most quickly through subcontracting network growth.
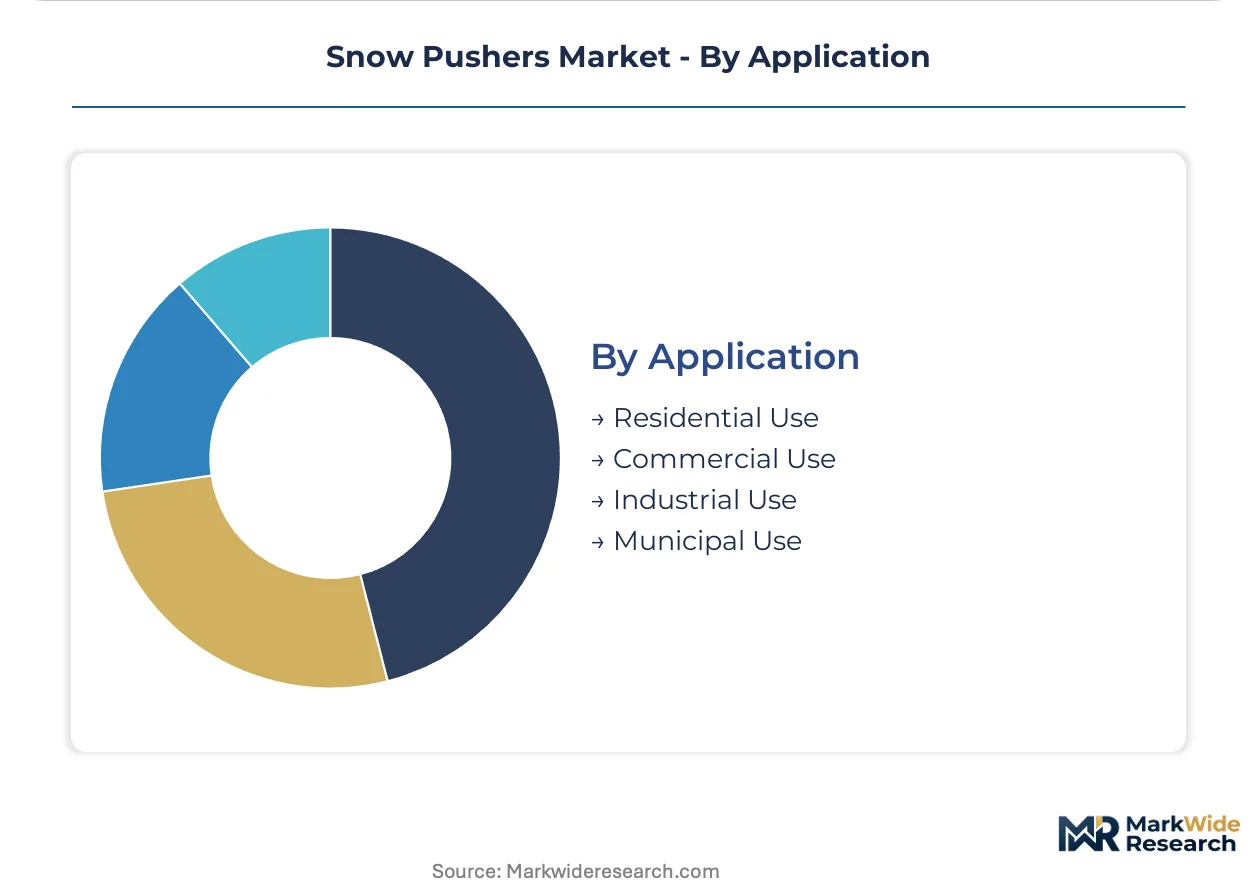
Application:
Geographic storm pattern intensity and surface area throughput requirements segment demand by operational scale and precision requirements.
- Municipal Use:Roadway, airport, and public facility clearing governed by FAA Part 139 standards and state DOT specifications. FAA snow removal standards mandate specialized blade geometries and operator visibility requirements that sustain premium equipment demand.
- Industrial Use:Manufacturing yard, logistics hub, and distribution center clearing where 24-hour operational continuity requires durable steel construction.
- Commercial Use:Retail parking lot and office campus clearing prioritizing speed and surface protection over precision grading.
- Residential Use:Individual property clearing with manual or light-duty equipment where volume throughput is secondary to storage and cost constraints.
Municipal use anchors the volume base while industrial use gains share at the steepest rate through logistics sector expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Tier 4 emissions standards anchor procurement patterns across the northern United States and Canada. Municipal fleet modernization programs concentrate demand in the Upper Midwest, where domestic steel content mandates and ISO-compliant welding protocols tighten vendor qualification. Canadian prairie provinces are adopting US-style standardization, opening cross-border procurement channels.
United States
Upper Midwest municipalities in Minnesota, Wisconsin, and Michigan drive fleet replacement cycles. State DOTs revise bid documents annually to prioritize lighter attachments that preserve vehicle emissions certification. The Great Lakes manufacturing corridor concentrates fabrication capacity, with Milwaukee and Minneapolis-St. Paul anchoring skilled welder availability.
Canada
Prairie provinces including Alberta, Saskatchewan, and Manitoba are expanding municipal fleet standardization programs. Health Canada and provincial transportation authorities align procurement codes with US domestic steel requirements. Winnipeg and Calgary serve as distribution hubs for cross-border equipment flows from Upper Midwest fabricators.
Germany
Industrial yard operators in Bavaria and North Rhine-Westphalia specify heavy-duty steel configurations for 24-hour logistics clearing. The KBA enforces transport regulations for oversize attachment hauling that exceed NHTSA thresholds. Munich-based equipment distributors source quick-attach systems from North American specialists.
Sweden
Arctic climate municipalities prioritize corrosion-resistant composite materials for coastal roadway maintenance. The Swedish Transport Administration mandates ISO-compliant welding protocols for state procurement. Gothenburg's polymer processing cluster supplies high-density polyethylene cutting edges to Nordic municipal fleets.
Japan
Airport surface operations at Narita and Kansai International sustain demand for FAA-equivalent blade geometries. METI standards for off-road equipment emissions accelerate lightweight attachment adoption. Nagoya's industrial machinery corridor integrates snow pusher fabrication with construction equipment manufacturing.
Snow Pushers Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with municipal procurement channels favoring heavy-duty fabricators and contractor segments rewarding quick-attach innovators. The market structures around three archetypes: steel-focused municipal suppliers, polymer-integrated lightweight specialists, and quick-attach system developers. Competitive moves concentrate on backward integration into captive steel supply and geographic expansion into Canadian prairie provinces.
Within the municipal-tier fabricators, Pro-Tech Manufacturing and Distribution Inc and Fisher Engineering exemplify heavy-duty steel construction positioning. Kage Innovation LLC occupies a specialist position through proprietary coupling mechanisms. These three companies represent the dominant competitive vectors: domestic fabrication networks, municipal procurement channel depth, and aftermarket attachment ecosystem development.
| Leading Market Players |
|---|
| Craig Manufacturing Ltd |
| HLA Snow |
| Pro-Tech Manufacturing and Distribution Inc |
| Rockland Manufacturing Company |
| SnowWolf |
| Rylind Manufacturing Inc |
| Kage Innovation LLC |
| BD Manufacturing |
| Fisher Engineering |
| Others |
Value Chain & Pricing Dynamics
Fabrication capacity utilization in the Great Lakes corridor concentrates pricing power among Wisconsin and Minnesota-based producers while compressing margins for distant competitors. Year-round production scheduling at anchor facilities sustains price floors that seasonal operators cannot match, locking in municipal procurement advantages for integrated fabricators.
Pricing Analysis
Geographic price spreads between Upper Midwest fabricators and peripheral suppliers widen during late-summer procurement windows when contractor demand spikes strain regional welding capacity. Three-tier pricing structure across premium ISO-compliant, standard domestic-steel, and economy import-dependent levels separates municipal bids from contractor fleet purchases. Cost compression in the economy tier is intensifying because scrap metal volatility and energy input fluctuations squeeze fabrication margins. Contractors exhibit highest price sensitivity due to compressed 4-5 year replacement cycles, while municipalities prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time polymer resin stocking for polyethylene blade processors and strategic steel plate stockpiling among heavy-duty fabricators hedging against scrap price swings. Supply concentrates in the United States, Canada, and Sweden, with the Great Lakes corridor anchoring skilled welder availability and Gothenburg's polymer cluster feeding Nordic composite demand. Raw material dependencies center on hardened steel plate, high-density polyethylene resin, and carbon fiber-reinforced polymer feedstock. Single-source vulnerability in AWS-certified welder pools constrains production scaling outside established manufacturing corridors. Distribution runs through municipal procurement channels, contractor equipment dealers, and airport authority direct contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as EPA Tier 4 axle load limits and material substitution trends fragment traditional steel-dominated product hierarchies, creating specialist niches for composite-integrated and quick-attach innovators.
For Market Incumbents: Consolidate fabrication capacity through captive steel supply arrangements and backward integration into polymer processing capabilities. Municipal procurement codes tightening domestic content requirements favor incumbents with established Wisconsin and Minnesota production footprints. Threat from REACH-compliant material substitution demands investment in composite welding hybrid capabilities to defend bid eligibility across corrosion-prone coastal markets. For New Entrants and Emerging Players: Anchor in Canadian prairie province municipal expansion, where Alberta and Saskatchewan fleet standardization programs replicate Upper Midwest procurement patterns with less entrenched supplier relationships. The penetrable segment lies in mid-size utility vehicle attachments for landscaping services seeking aluminum and composite variants. Go-to-market execution should leverage quick-attach system licensing to bypass proprietary coupling barriers erected by established players. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among quick-attach system developers with proprietary coupling ecosystems that lock in aftermarket attachment sales. Long-term viability over the projection horizon favors acquisition targets with ISO-compliant welding infrastructure and established municipal channel relationships. The signal to watch is state DOT specification revisions prioritizing lighter attachments, which accelerates replacement demand and expands addressable market for composite-integrated specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Processing | Captive high-density polyethylene supply secures REACH-compliant material substitution margins against steel volatility. |
| AWS D1.1 Certification Investment | ISO-compliant welding protocols unlock Minnesota, Wisconsin, and Michigan municipal procurement channels. |
| Quick-Attach System Licensing | Proprietary coupling ecosystems create aftermarket attachment revenue streams across contractor segments. |
| Canadian Prairie Province Expansion | Alberta and Saskatchewan fleet standardization opens cross-border procurement with less supplier concentration. |
| Lightweight Composite R&D Partnership | Carbon fiber-reinforced polymer development addresses EPA Tier 4 axle load compliance requirements. |
Study Parameters
The analysis maps motorized, heavy-duty, manual, and commercial snow pusher configurations, each validated through municipal fleet managers, snow removal contractors, welding shop supervisors, and airport ground operations directors. Primary interviews with fabrication facility owners and polymer processing specialists combined with secondary validation against EPA Tier 4 compliance documentation, FAA Part 139 standards, state DOT procurement databases, and AWS certification registries. Bottom-up attachment unit demand triangulation against top-down municipal budget allocation analysis ensures cross-verified output consistency.
Consistency checks validated volume and value outputs against equipment replacement cycle surveys and seasonal contracting employment data across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user procurement channel, and application intensity. CAGRs derive from equipment stock depreciation curves and fleet modernization program announcements. Industry-specific forecast inputs incorporate EPA enforcement timelines for off-road diesel emissions and state-level Buy American provision adoption rates.
Material uncertainties — steel input cost volatility, welder supply concentration disruptions, and regulatory specification revisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding municipal budget continuity and Tier 4 vehicle adoption curves. Revision becomes warranted when EPA enforcement intensity or state domestic content mandates cross thresholds that accelerate or delay replacement cycle timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Vertical Grinding Mills Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Asphalt Testing Equipment Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Backhoes Market
Construction Equipment
Mexico Heavy Construction Equipment Rental Market
Construction Equipment
Hydraulic Breaker for Excavator Market
Construction Equipment
Wood Milling Machine Market
Construction Equipment
Mini Excavators Market
Construction Equipment
Fully Automatic Metal Band Saw Machine Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Pressure Washer Market