
 Log Splitters Rental Market | 2026-2036
Log Splitters Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Log Splitters Rental Market Insights
Modular rental packages combining log splitters with chippers and stump grinders is recalibrating how landscaping contractors configure job-site equipment. United Rentals leverages its national branch network to bundle attachments and transport services. Sunbelt Rentals anchors its competitive stance through dense coverage in the southeastern United States. Herc Rentals differentiates via telematics integration that tracks splitter utilization and schedules preventive maintenance.
A log splitter is a mechanical device that applies force to a log via a hydraulic ram, electric motor, or gasoline engine to split wood along the grain for firewood or biomass processing. Hydraulic models generate splitting forces between 20 and 35 tons and dominate commercial rental inventories due to cycle speed and hardwood capacity. Gas-powered splitters retain share in remote forestry applications where electrical access remains limited. Electric splitters represent the fastest-growing rental category as noise ordinances and indoor storage restrictions tighten across municipal jurisdictions.
EPA Phase 3 emissions standards for small spark-ignition engines constrain gasoline-powered fleet additions and redirect capital toward electric and hydraulic alternatives. OSHA logging and tree-care safety guidelines influence operator training requirements that rental providers must bundle with equipment handoffs. Stakeholders should monitor battery energy density improvements and municipal decarbonization timelines to time fleet transitions and pricing structures.
Market Dynamics
Project-based equipment access is displacing ownership models among residential landscaping contractors, compressing capital deployment cycles and forcing rental fleets to optimize utilization metrics through telematics integration.
Growth Catalysts
- EPA Phase 3 emissions standards:Small spark-ignition engine restrictions redirect fleet investment toward electric and hydraulic alternatives, expanding compliant inventory categories.
- Storm cleanup demand:Severe weather frequency sustains seasonal utilization spikes across the southeastern United States, stabilizing revenue predictability for regional operators.
- Biomass processing:Commercial firewood operations and pellet manufacturers drive commercial-grade hydraulic splitter rentals for hardwood throughput efficiency.
Market Restraints
- Battery energy density limitations:Electric splitter runtime constraints restrict deployment to sub-20-ton applications, capping addressable commercial segments.
- Steel price volatility:Hydraulic ram and I-beam fabrication costs fluctuate with commodity cycles, compressing equipment margin stability.
- Rural electrical infrastructure gaps:Remote forestry sites lack grid access, preserving gasoline dependency despite regulatory pressure.
Strategic Opportunities
- Municipal decarbonization timelines:City-level net-zero commitments accelerate electric fleet transition subsidies, creating first-mover positioning windows.
- Attachment bundling:Chippers and stump grinders packaged with splitters raise contract values and lock in contractor loyalty.
- Telematics-enabled predictive maintenance:Sensor-based wear monitoring reduces downtime penalties and extends equipment service intervals.
Industry Challenges
- OSHA logging safety certification:Operator training mandates extend handoff protocols, inflating per-rental labor costs and branch staffing requirements.
- Fleet standardization friction:Mixed manufacturer inventories complicate parts procurement and technician cross-training across branch networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Log Splitters Rental Market |
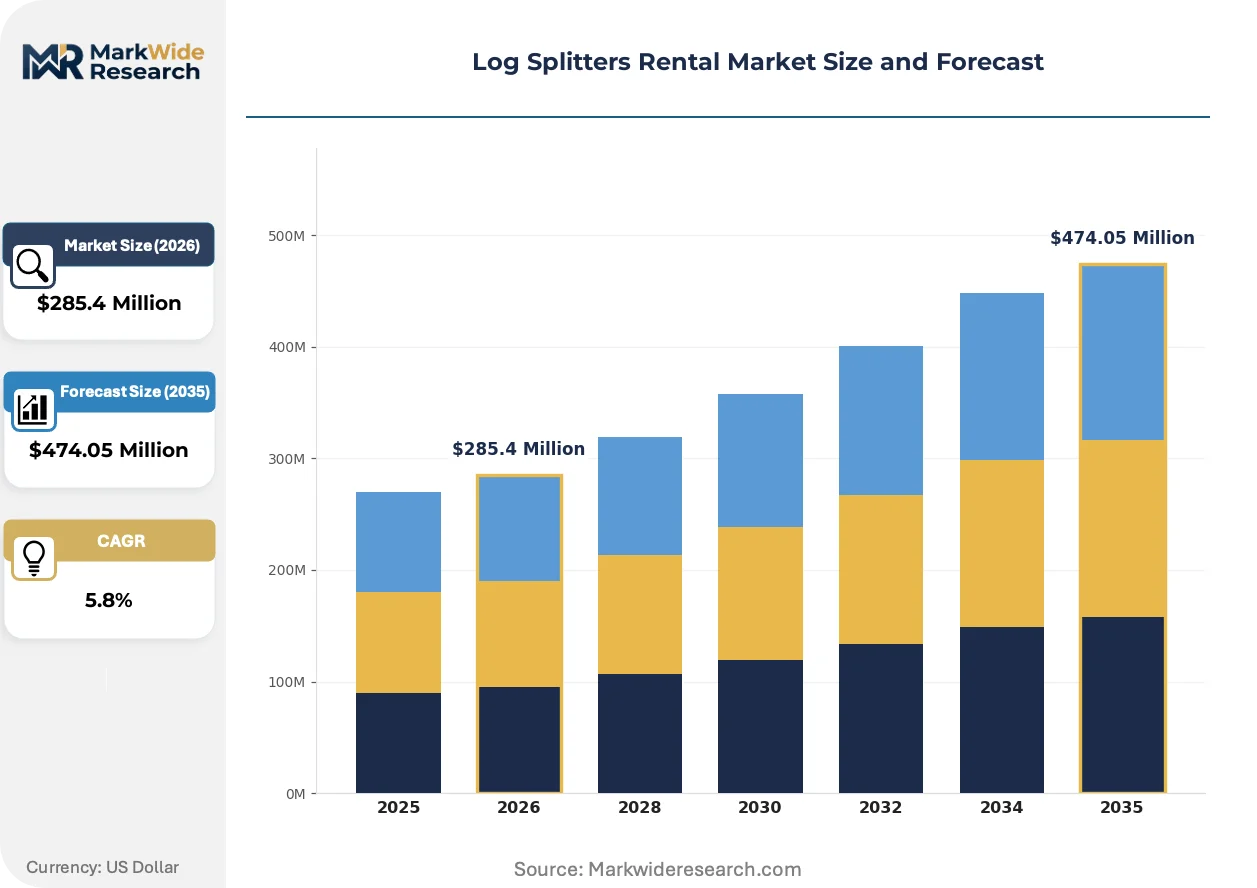
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Log Splitters, Electric Log Splitters, Gas-Powered Splitters, Manual Log Splitters Application: Residential Landscaping, Commercial Forestry, Landscaping Services, Firewood Processing End User: Contractors, Property Managers, Landscape Architects, DIY Homeowners Rental Duration: Hourly, Daily, Weekly, Monthly |
| Companies Covered | United Rentals, Sunbelt Rentals, Herc Rentals, BlueLine Rental, A-Plant, HSS Hire, Coates Hire, Kennards Hire, The Home Depot Rental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Log Splitters Rental Market Trends and Innovations
Equipment configuration is fragmenting into flexible component systems. Rental providers now compete on assembly speed and transport logistics rather than unit specifications alone.
Battery-electric splitter platforms are modularizing around swappable power packs and interchangeable wedge configurations. Landscaping contractors in noise-restricted municipalities adopt these systems for overnight staging near residential zones. The technology is modularizing fleet procurement into subsystem sourcing, decoupling powertrain from splitting mechanism investment cycles.
OSHA logging and tree-care safety guidelines tighten operator qualification requirements nationwide. Rental providers must bundle certified training with equipment handoffs, extending transaction duration but reducing liability exposure. Commercial contractors absorb these compliance costs more readily than residential DIY segments, shifting demand mix toward professional accounts.
Job-site equipment bundling is compressing single-item rental frequency. Contractors now specify multi-attachment packages through digital portals, replacing branch counter negotiations. This pattern concentrates in the southeastern United States, where storm response crews prioritize rapid deployment over brand loyalty.
Log Splitters Rental Market Segmentation
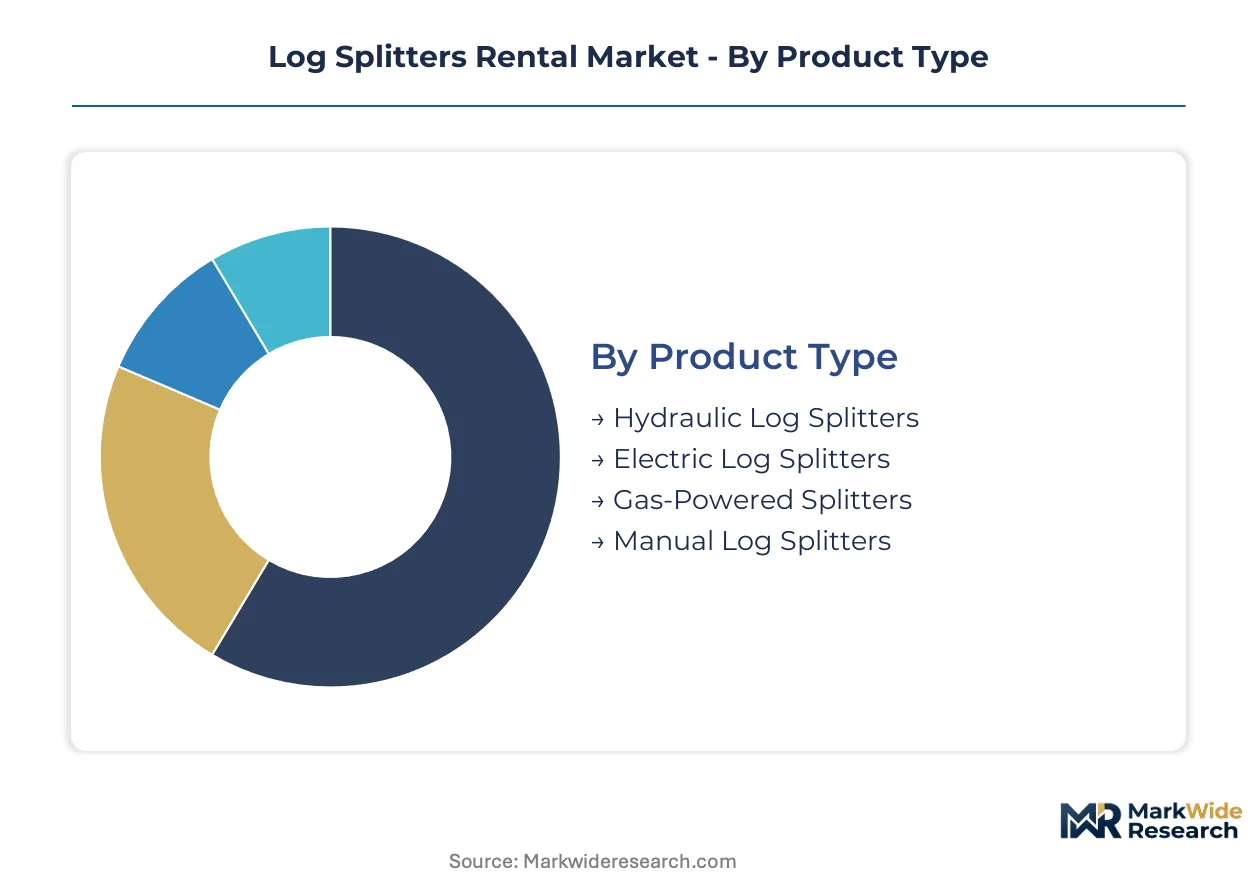
Segmentation in log splitter rentals reveals how equipment specifications, contract structures, and user capabilities intersect to determine fleet composition and pricing power. Rental providers optimize inventory mix across these dimensions to match utilization patterns with capital deployment cycles.
Product Type:
Supply concentration in hydraulic systems shapes competitive positioning across rental networks, with force ratings and cycle speeds determining branch-level procurement priorities.
- Hydraulic Log Splitters:These systems deploy pressurized fluid through a ram mechanism generating 20-35 tons of splitting force. Commercial forestry contractors in the southeastern United States favor hydraulic units for oak and hickory processing where cycle speed determines job economics. Fleet managers prioritize hydraulic inventory for storm response contracts due to reliability under sustained load.
- Electric Log Splitters:Corded and battery-electric platforms deliver 5-10 tons of force with near-silent operation. Municipalities with noise ordinances in California and New York metropolitan areas drive adoption for overnight staging near residential zones. EPA Phase 3 compliance costs accelerate electric procurement timelines for fleet renewals.
- Gas-Powered Splitters:Small spark-ignition engines provide mobility for remote sites lacking grid infrastructure. Rural property managers in Montana and Idaho retain gasoline dependency for backcountry access despite regulatory pressure.
- Manual Log Splitters:Screw-type and slide-hammer mechanisms serve DIY homeowners with occasional firewood needs. These units occupy minimal warehouse footprint and require zero maintenance scheduling.
Today's leader: Hydraulic Log Splitters. Tomorrow's challenger: Electric Log Splitters.
Application:
Cost tier differentiation separates premium hydraulic deployments from economy electric contracts, with force requirements and job duration determining rental rate structures.
- Residential Landscaping:Seasonal pruning and tree removal projects generate intermittent demand for sub-20-ton electric units. Landscape contractors in suburban Atlanta and Charlotte bundle splitter rentals with chipper attachments for complete job-site packages.
- Commercial Forestry:Sustained hardwood processing demands 30+ ton hydraulic capacity with rapid cycle times. Pellet manufacturers in Maine and Vermont contract monthly rentals for winter feedstock preparation.
- Landscaping Services:Multi-crew operations require flexible equipment access with transport logistics support. Regional providers in Florida and Georgia compete on assembly speed and same-day delivery windows.
- Firewood Processing:Small-scale commercial operations and homesteaders rent electric units for weekend production runs. This segment shows highest sensitivity to per-day pricing thresholds.
Commercial Forestry commands rate premiums. Residential Landscaping drives volume velocity.
End User:
Customer type determines training bundle requirements and liability exposure, with professional accounts absorbing compliance costs more readily than consumer segments.
- Contractors:Licensed landscaping and tree-care professionals generate recurring rental relationships with predictable seasonal patterns. OSHA logging safety certification requirements extend handoff protocols for this segment, inflating per-rental labor costs.
- Property Managers:Multi-site residential and commercial portfolios require coordinated equipment deployment across dispersed locations. This segment values telematics-enabled utilization tracking for cost allocation.
- Landscape Architects:Design-phase specifications influence contractor equipment choices, creating upstream influence on rental demand. Project-based engagement limits direct rental frequency.
- DIY Homeowners:Price-sensitive occasional users favor daily or weekend rentals with minimal training overhead. Electric splitters with simplified controls dominate this segment due to reduced liability exposure.
Contractors anchor revenue stability. Property Managers represent the fastest-growing trajectory for bundled service contracts.
Rental Duration:
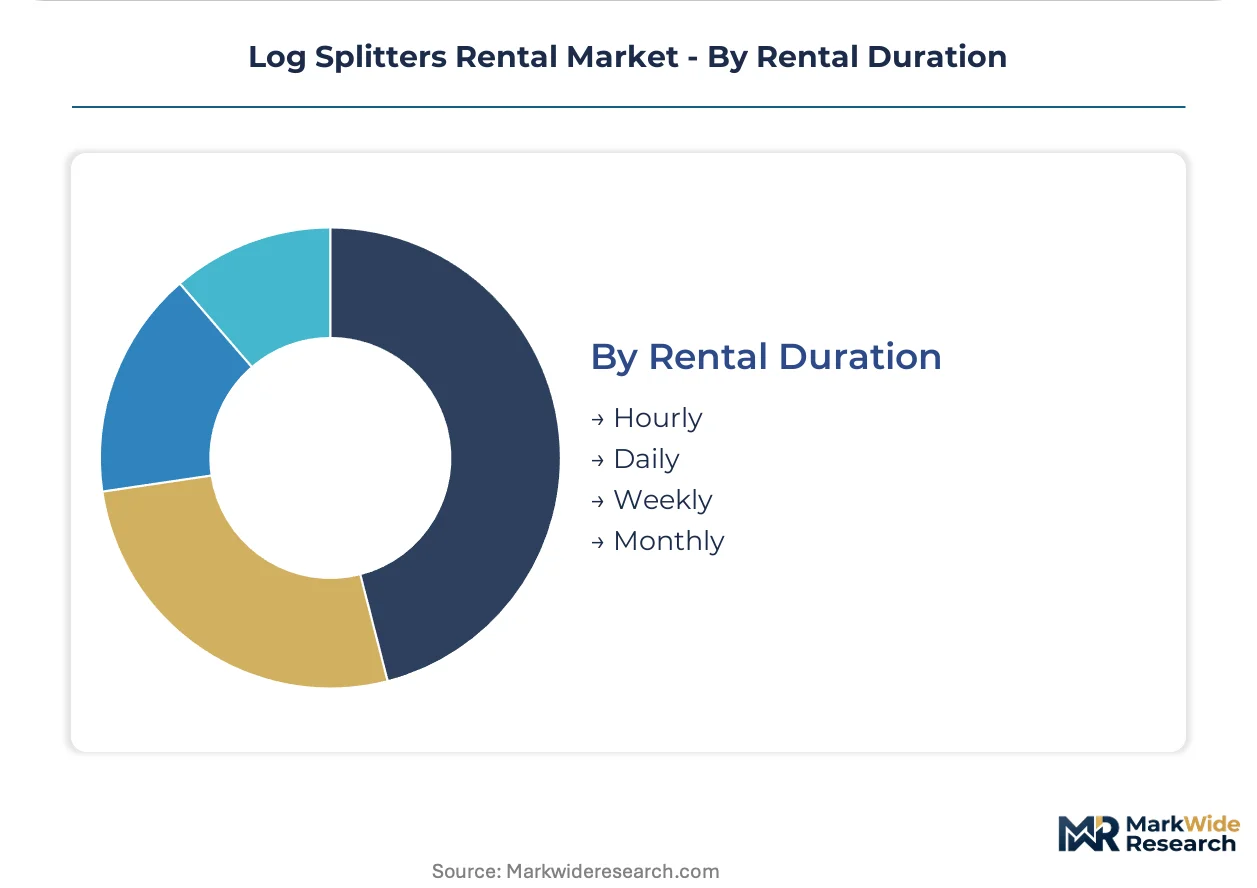
Volume concentration in weekly contracts reflects project-based equipment access patterns, with duration flexibility serving as a key competitive differentiator.
- Hourly:Emergency storm response and equipment testing scenarios drive minimal but high-margin transactions. Limited availability constrains segment expansion.
- Daily:DIY homeowners and small contractors favor single-day access for discrete tasks. Pricing transparency and online reservation systems determine provider selection.
- Weekly:Standard project duration for residential landscaping crews balances utilization efficiency with capital flexibility. This duration captures the highest share of contract value across rental networks.
- Monthly:Commercial forestry and biomass processing operations secure equipment for entire seasons. Long-term contracts enable preventive maintenance scheduling and reduced per-day rates.
Weekly contracts dominate current mix. Monthly structures gain traction in commercial segments seeking budget predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Log splitter rental operations trace their commercial scale to post-war American suburban expansion, where seasonal firewood culture and storm-response infrastructure created the first organized equipment pools. This North American foundation established operational templates later adapted to European forestry cooperatives and Australian rural property management.
United States
Seasonal firewood preparation and hurricane cleanup sustain utilization rates across the Southeast and Northeast. EPA Phase 3 emissions standards for small spark-ignition engines redirect fleet investment toward electric and hydraulic alternatives. Atlanta and Charlotte landscaping corridors drive demand for bundled chipper-splitter packages with same-day deployment logistics.
Germany
Commercial forestry contractors and biomass pellet manufacturers anchor hydraulic splitter demand for hardwood processing efficiency. REACH chemical regulations and EU Green Deal decarbonization timelines accelerate electric fleet procurement in municipal jurisdictions. Bavarian forestry cooperatives concentrate equipment-sharing pools that influence rental contract standardization across Central Europe.
Canada
Rural property management and remote cabin maintenance sustain gasoline-powered splitter dependency where electrical infrastructure remains limited. Health Canada environmental guidelines align with EPA emission trajectories, pressuring fleet transitions in populated provinces. Ontario and Quebec rental networks optimize for seasonal firewood peaks and ice-storm response mobilization.
Australia
Bushfire recovery operations and commercial firewood operations drive hydraulic unit demand for eucalyptus hardwood capacity. State-level environmental protection agencies impose noise restrictions that favor electric deployment near residential zones. New South Wales and Victoria rental markets concentrate around Sydney and Melbourne peri-urban corridors with rapid storm-damage response requirements.
United Kingdom
Arborist contractors and estate management services generate demand for compact electric units with reduced noise signatures. HSE safety certification requirements extend operator training protocols for commercial accounts. Southeast England rental networks cluster around London commuter belt properties with wood-burning stove installation trends.
Log Splitters Rental Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fleet telematics integration and bundled service capabilities. National branch networks with dense geographic coverage command rate premiums through logistics reliability and rapid replacement availability. Three archetypes dominate: integrated equipment rental conglomerates with multi-category portfolios, regional specialists with storm-response mobilization expertise, and retail-anchored operations leveraging consumer foot traffic. Consolidation pressure intensifies through telematics-enabled utilization optimization and cross-category attachment bundling.
Among North American rental conglomerates, United Rentals, Sunbelt Rentals, and Herc Rentals exemplify divergent strategic positioning within the premium tier. United Rentals anchors national coverage density, Sunbelt Rentals concentrates southeastern storm-response capability, and Herc Rentals occupies telematics-forward positioning through sensor-based fleet monitoring. These three structures represent the dominant competitive templates against which mid-scale regional operators calibrate differentiation attempts.
| Leading Market Players |
|---|
| United Rentals |
| Sunbelt Rentals |
| Herc Rentals |
| BlueLine Rental |
| A-Plant |
| HSS Hire |
| Coates Hire |
| Kennards Hire |
| The Home Depot Rental |
| Others |
Pricing and Supply Chain Analysis
Performance-tier divergence between hydraulic commercial units and electric municipal-grade equipment manifests in both rental rate structures and procurement sourcing patterns. Premium hydraulic fleets command rate premiums through southeastern storm-response contracts, while electric inventory draws from battery supply chains tethered to Asian cell manufacturers and EPA compliance cost curves.
Pricing Analysis
Project-based duration pricing with weekly rate anchoring dominates contract structures across rental networks. Price differentiation hinges on force-capacity tier and OSHA certification bundle inclusion, with commercial forestry contractors absorbing premium rates for 30-plus ton hydraulic units. Cost compression in electric sub-20-ton categories is intensifying because battery platform commoditization accelerates manufacturer competition. DIY homeowners exhibit highest price sensitivity, while property managers with multi-site portfolios prioritize telematics value over per-day rates.
Supply Chain Analysis
Single-source vulnerability sits with Chinese lithium-ion cell suppliers feeding battery-electric splitter platforms. Equipment fabrication draws from Taiwanese hydraulic component specialists, German precision pump manufacturers, and domestic I-beam steel processors. Tariff exposure on battery cells and power electronics creates margin instability for electric fleet transitions. Distribution runs through national branch networks with regional parts depots, supplemented by manufacturer-direct service partnerships for specialized hydraulic repairs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Log splitter rentals constitute a late-cycle quality story as storm-response reliability and EPA compliance certification displace pure price competition. Demand is concentrating toward bundled service contracts with predictive maintenance guarantees.
For Market Incumbents: Anticipate margin compression from battery-electric platform commoditization by deepening captive maintenance capabilities and securing exclusive hydraulic component distribution rights. Fleet standardization around single manufacturer protocols reduces technician cross-training costs. Prioritize telematics integration that locks property managers into multi-year utilization tracking contracts. For New Entrants and Emerging Players: Capture unmet demand in rural electrical infrastructure gaps where gasoline-to-electric transition timelines lag regulatory pressure. Municipal decarbonization subsidy windows in California and New York metropolitan areas offer penetrable entry points. Lead with overnight staging logistics and noise-ordinance compliance as differentiated go-to-market positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where telematics-enabled utilization optimization separates premium-margin players from commodity rental operations. Long-term viability favors regional specialists with storm-response mobilization expertise and dense southeastern branch coverage. Monitor battery energy density improvement curves as the inflection signal for electric fleet transition economics.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Sensor-based utilization tracking enables predictive maintenance scheduling and contractor loyalty lock-in. |
| Electric Fleet Transition | EPA Phase 3 compliance redirects capital toward battery-electric inventory with municipal subsidy capture. |
| Attachment Bundling Expansion | Chipper and stump grinder packaging raises contract values and compresses single-item rental frequency. |
| Regional Storm-Response Capacity | Southeastern branch density secures revenue predictability through hurricane cleanup mobilization contracts. |
| OSHA Certification Program | Operator training bundling reduces liability exposure and extends transaction duration with professional accounts. |
Research Methodology
Multiple input streams — fleet manager interviews, landscaping contractor procurement surveys, and regulatory filing analysis — were reconciled to construct demand and supply estimates. Primary discussions with rental branch operators, equipment manufacturer product managers, municipal procurement officers, and commercial forestry contractors informed utilization pattern assumptions. Secondary validation drew from EPA enforcement databases, OSHA training certification records, utility rebate program filings, and steel commodity trade data. Bottom-up branch-level fleet counts and top-down industry revenue estimates were triangulated to anchor market sizing.
Historical rental transaction velocity was cross-referenced against panel input from fleet managers regarding replacement cycles and electrification timelines. Segmentation modeling spanned product type, application, end user, and rental duration dimensions across the projection horizon. CAGRs were derived from equipment replacement schedules, regulatory phase-in dates, and regional storm frequency baselines. Forecast inputs incorporated battery cost decline curves, hydraulic component lead time fluctuations, and municipal decarbonization commitment tracking.
Steel price volatility, battery supply contract renegotiations, and storm frequency variability are the dominant revision risks to modeled equipment deployment and rental rate assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
GCC Construction Machinery Market
Construction Equipment
Truck Crane Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Laser Cutting Machines Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Latin America Construction Equipment Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Bale Openers Market
Construction Equipment
Backhoe Loaders Market
Construction Equipment
Concrete Demolition Professional Equipment Market
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market