
 Global Construction Dumper Market | 2026-2036
Global Construction Dumper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Dumper Market Analysis
ISO 6165 earth-moving machinery classification is reorganizing competitive entry barriers for construction dumper manufacturers seeking cross-border tenders. Caterpillar Inc. leverages its integrated powertrain manufacturing to sustain margin control across articulated and rigid product lines. Komatsu Ltd. anchors its position through autonomous haulage system compatibility, while AB Volvo competes via modular chassis architectures that simplify regional customization.
Construction dumpers are heavy-duty material transport vehicles engineered with payload capacities from 20 to 400 metric tons, utilizing either rigid or articulated frame geometries to traverse unimproved terrain at mining and infrastructure sites. Articulated dumpers dominate volume in European quarrying applications where maneuverability offsets lower per-load efficiency, while rigid dumpers command the highest unit values in Australian and Chilean open-pit mining where electric drive technology is displacing mechanical transmissions. Diesel technology still occupies the majority of installed fleets, though hybrid configurations are gaining specification share in urban infrastructure projects subject to noise and emissions constraints.
EPA Tier 4 Final and EU Stage V emissions frameworks are forcing engine aftertreatment investments that raise base unit costs and narrow the supplier field to manufacturers with captive powertrain development. China's MIIT implements domestic emission tiers that diverge from Euro-equivalent test cycles, creating parallel certification burdens for multinational suppliers. India's CEA construction equipment registration requirements add another compliance layer for imported machinery. Stakeholders must monitor how battery-electric range specifications evolve against duty-cycle validation protocols before committing capital to next-generation platform development.
Market Dynamics
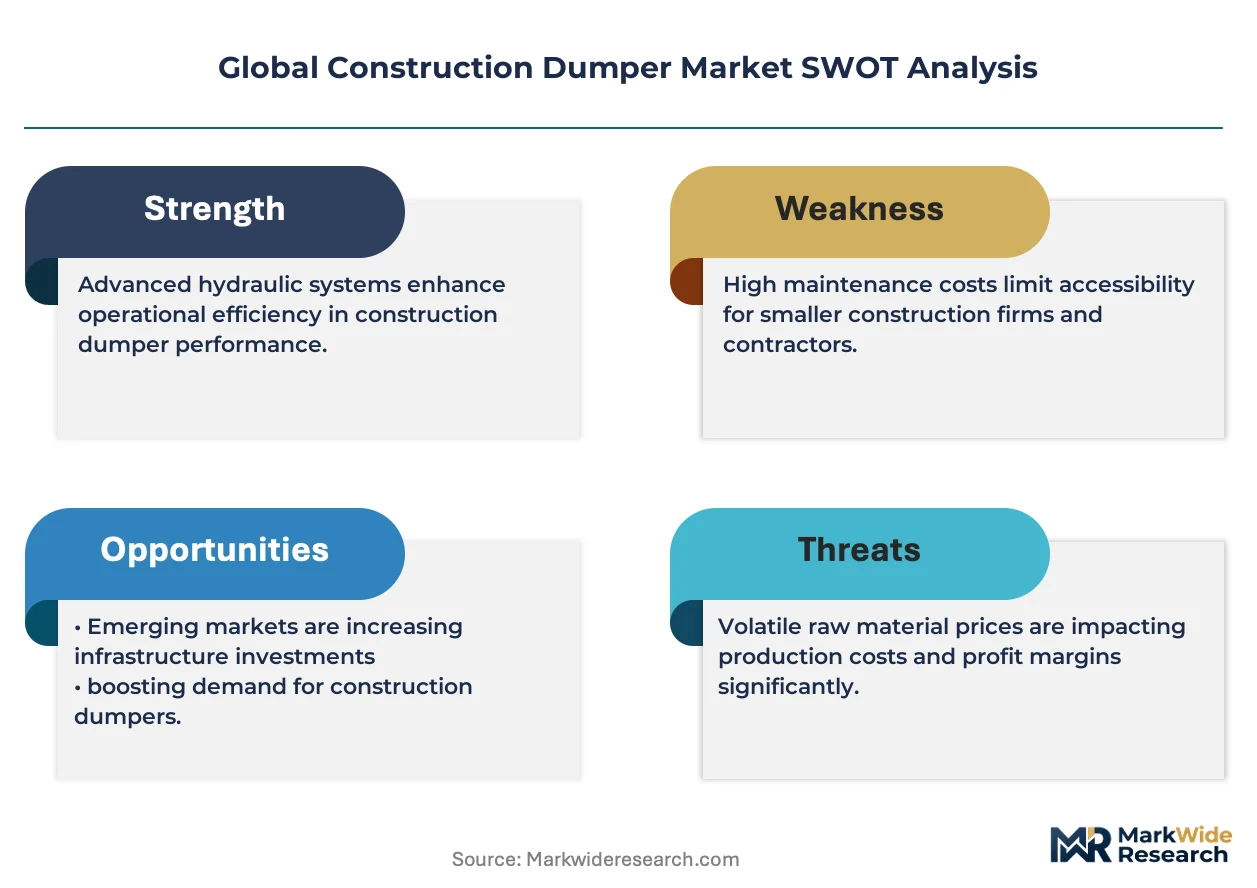
EPA Tier 4 Final and EU Stage V emissions standards are compressing the supplier field by forcing captive powertrain development and raising capital barriers for engine aftertreatment integration.
Growth Catalysts
- Australian and Chilean mining expansion:Open-pit operators in these markets are specifying autonomous-capable haulers for fleet renewal programs, pulling demand for rigid-frame dumpers with electric drive compatibility.
- China's western provincial infrastructure corridors:State-funded transport links through Sichuan, Yunnan, and Xinjiang are generating concentrated equipment procurement for articulated dumpers suited to high-altitude terrain.
- India's National Highway Development:CEA registration requirements are formalizing equipment traceability, creating compliant demand channels for imported construction dumpers in road-building segments.
Market Restraints
- Engine aftertreatment cost inflation:Diesel oxidation catalysts and selective catalytic reduction systems are raising base unit costs by 12-18% for Tier 4 Final compliance, squeezing mid-tier manufacturers without scale.
- Powertrain supply concentration:Captive engine development capabilities concentrate among integrated manufacturers, limiting sourcing options for independent dumper assemblers.
- Battery-electric range validation gaps:Duty-cycle testing protocols for electric dumpers remain underdeveloped, delaying specification confidence in mining applications.
Strategic Opportunities
- India's PLI scheme for construction equipment:Domestic manufacturing incentives are opening greenfield assembly opportunities for multinational suppliers seeking tariff advantages.
- Urban noise and emissions constraints:European city infrastructure projects are specifying hybrid dumper configurations, creating premium segments for low-decibel equipment.
- Autonomous haulage convergence:Integration of LiDAR perception systems with telematics platforms is enabling retrofit opportunities for existing fleet operators.
Industry Challenges
- Dual certification burdens:China's MIIT emission test cycles diverge from Euro-equivalent protocols, forcing parallel validation investments for multinational suppliers.
- ISO 6165 reclassification complexity:Updated earth-moving machinery standards are requiring technical documentation overhauls for cross-border tender eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Dumper Market |
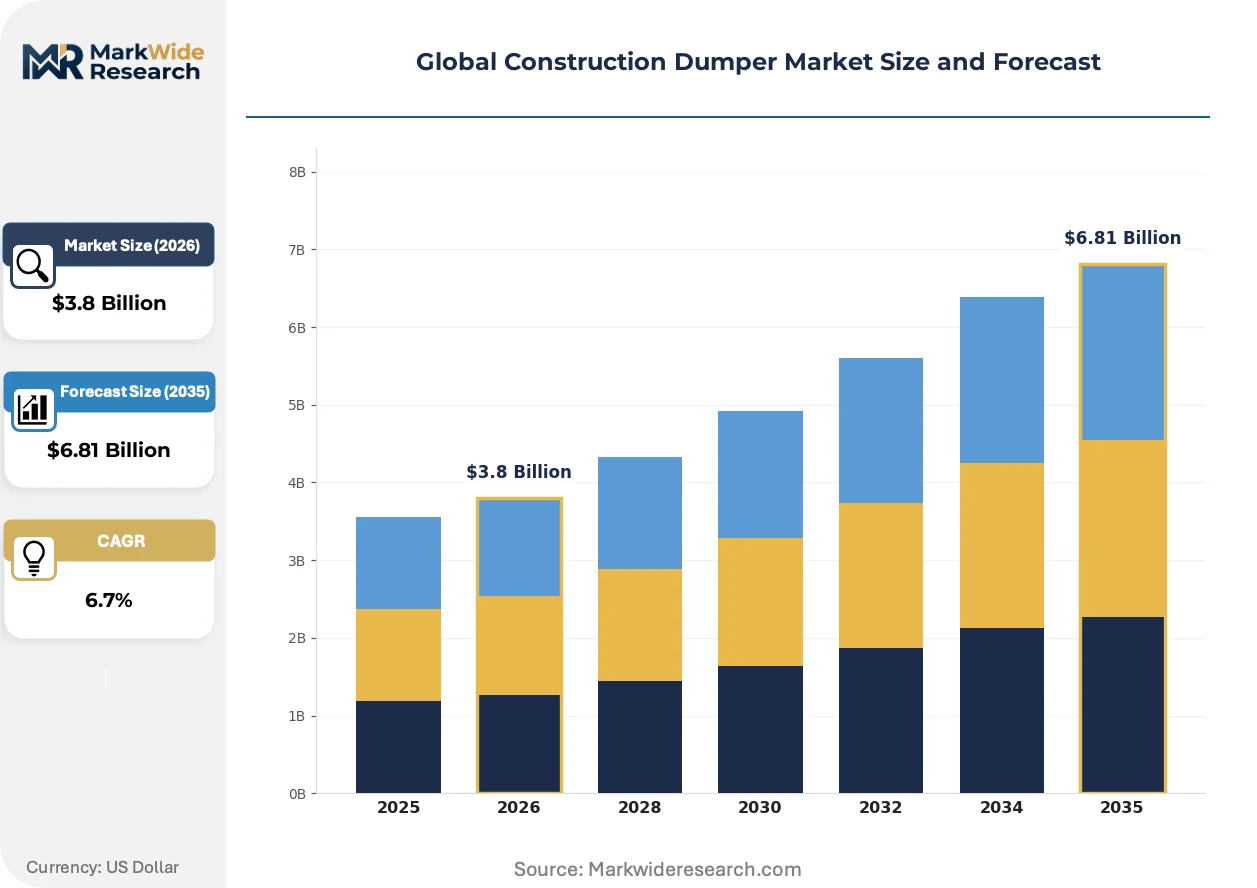
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Articulated Dumpers, Rigid Dumpers, Mini Dumpers, Track Dumpers End User: Residential, Commercial, Industrial, Infrastructure Service Type: Rental Services, Sales Services, Maintenance Services, Repair Services Technology: Hydraulic, Electric, Diesel, Hybrid |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., AB Volvo, J C Bamford Excavators Ltd., Liebherr, CNH Industrial N.V., Deere & Company, Hitachi Construction Machinery Co., Ltd., Doosan Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Dumper Market Emerging Trajectories
Electrification and automation are splitting equipment development paths, with mining-grade autonomy diverging from urban-focused hybridization while emissions compliance unifies engineering priorities across both tracks.
Electric drive technology is bifurcating the rigid dumper segment. AC induction and permanent magnet motor systems are replacing mechanical transmissions in Australian and Chilean open-pit operations. Komatsu and Caterpillar are accelerating electric platform deployment, compressing the competitive window for suppliers lacking integrated powertrain architectures.
EU Stage V and EPA Tier 4 Final frameworks are mandating particulate matter and nitrogen oxide reductions that exceed prior tier requirements. Engine manufacturers must integrate diesel particulate filters with selective catalytic reduction, raising development costs and consolidating the supplier base around vertically integrated producers. European quarrying applications face the steepest compliance timelines.
Equipment procurement is consolidating around lifecycle cost metrics rather than upfront capital expenditure. Mining operators in Australia are unbundling maintenance contracts from original equipment purchases, favoring suppliers with captive service networks. This shift is most pronounced in autonomous fleet deployments where uptime guarantees determine contract awards.
Global Construction Dumper Market Segmentation
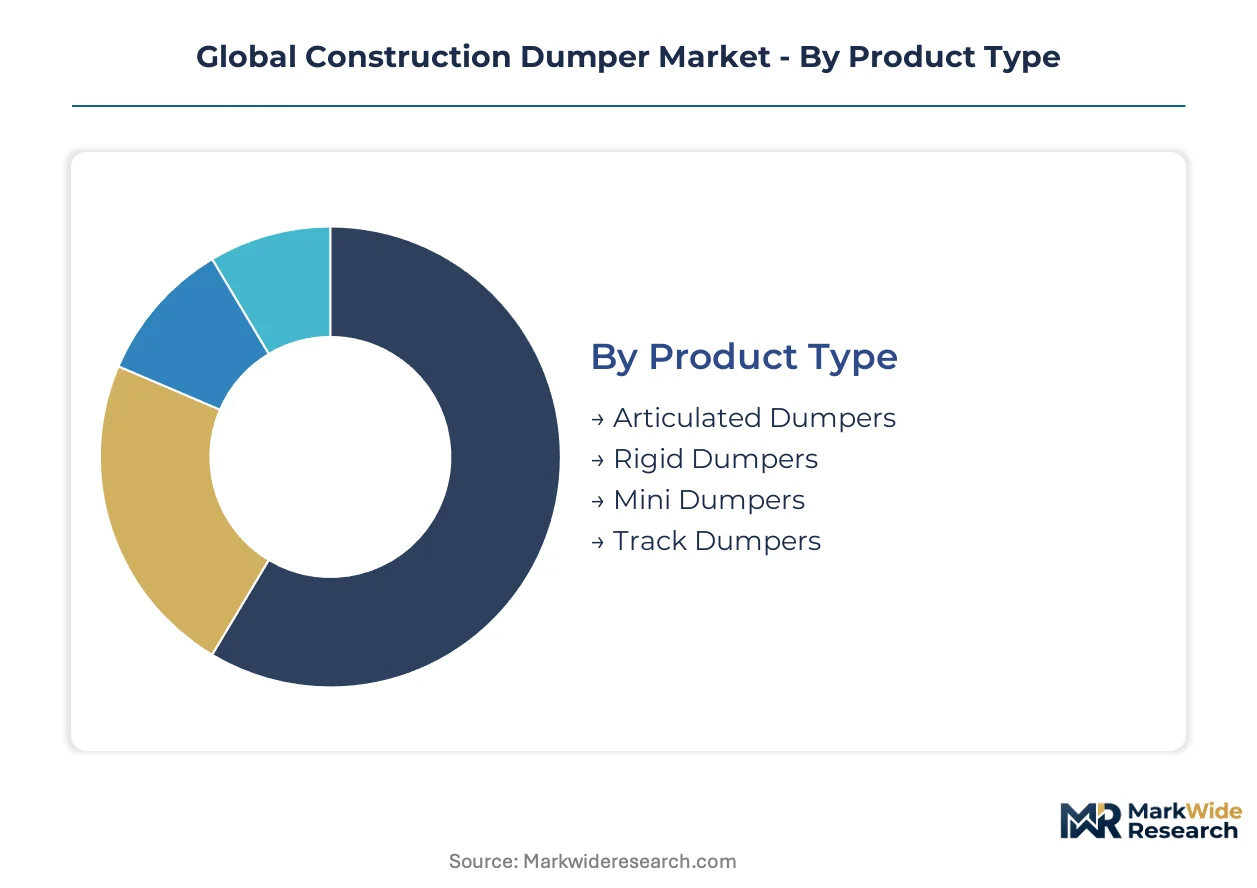
Construction dumper procurement patterns diverge sharply across operational contexts, with mining autonomy requirements, urban emissions constraints, and infrastructure scale each pulling specification toward distinct technical configurations. Understanding these segment boundaries enables suppliers to align powertrain investments with actual purchase decision criteria rather than assumed homogeneity.
Product Type:
EPA Tier 4 Final and EU Stage V emissions frameworks apply differential compliance burdens across frame geometries, with articulated designs facing tighter maneuverability packaging constraints for aftertreatment hardware.
- Articulated Dumpers:Hinged chassis designs with pivot steering enable operation on slopes exceeding rigid-frame limits. European quarrying operators in Germany and France specify these units for tight extraction sites where turning radius determines cycle efficiency. Stage V aftertreatment packaging challenges favor suppliers with integrated powertrain architectures.
- Rigid Dumpers:Fixed-frame construction supports payload ratings above 200 metric tons. Australian open-pit operators at Pilbara and Queensland sites are specifying electric drive variants for autonomous fleet integration, pulling demand toward AC motor systems with regenerative braking.
- Mini Dumpers:Compact units below 10-ton capacity serve urban renovation and landscaping contractors. Japanese metropolitan projects specify these for narrow street access where full-size equipment faces movement restrictions.
- Track Dumpers:Continuous track undercarriages distribute ground pressure for soft terrain. Canadian oil sands and Indonesian palm plantation applications favor these over wheeled alternatives during monsoon conditions.
Established volume favors articulated designs; emerging adoption favors rigid-frame electric configurations.
End User:
Customer scale determines maintenance infrastructure requirements and financing structures, with mining conglomerates unbundling service contracts while residential contractors prioritize rental flexibility.
- Residential:Single-family and low-rise developers utilize mini and small articulated units for site grading and material movement. India's urban housing schemes in Mumbai and Bangalore satellite townships generate concentrated procurement for 20-30 ton capacity equipment.
- Commercial:Office and retail construction demands mid-size articulated fleets with rapid site-to-site transportability. UAE commercial developments in Dubai South specify hybrid configurations to meet municipal noise ordinances.
- Industrial:Manufacturing facility and warehouse construction requires predictable uptime metrics. German industrial park developers favor rental arrangements with guaranteed availability clauses over capital purchase.
- Infrastructure:Highway, rail, and port projects represent the largest unit deployments. China's western provincial corridors through Sichuan and Xinjiang are generating fleet-scale orders for high-altitude-rated rigid dumpers.
Procurement scale concentrates in infrastructure; contract flexibility demands are climbing fastest in residential.
Service Type:
Lifecycle revenue models are displacing upfront equipment sales as mining operators prioritize uptime guarantees over asset ownership.
- Rental Services:Short-term equipment access without capital commitment. Brazilian construction SMEs in São Paulo state utilize rental for project-specific capacity matching.
- Sales Services:Direct purchase with financing arrangements. Australian mining majors prefer ownership with captive maintenance for autonomous fleet control.
- Maintenance Services:Scheduled and predictive upkeep contracts. South African platinum belt operators unbundle these from OEM agreements to utilize third-party specialists.
- Repair Services:Breakdown response and component replacement. Indonesian coal contractors face extended lead times for Tier 4 Final aftertreatment parts.
Revenue stability favors maintenance contracts; margin expansion favors rental fleet operators.
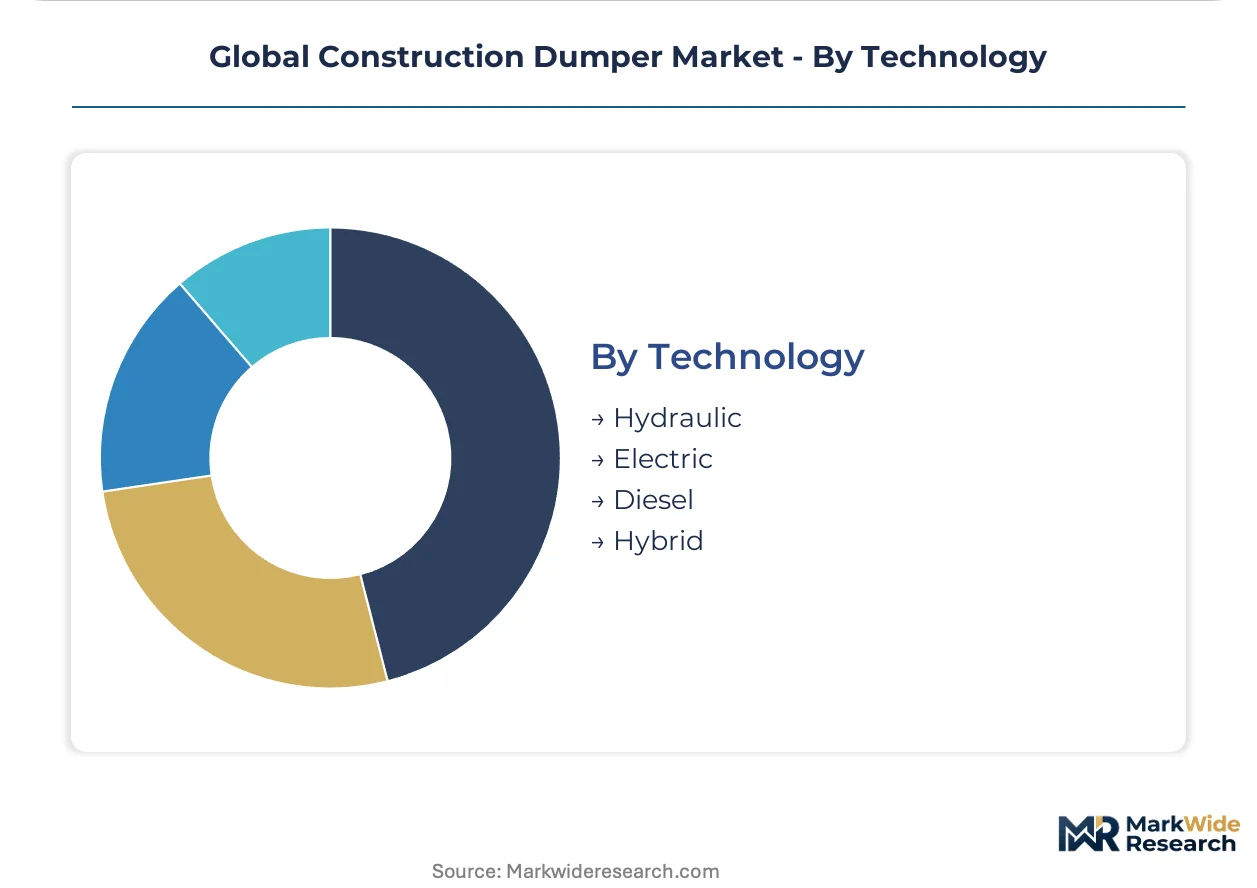
Technology:
Powertrain selection now hinges on duty-cycle validation protocols and charging infrastructure maturity as much as fuel cost economics.
- Hydraulic:Fluid power systems for lift and steering functions persist in legacy fleet bases. Russian and Central Asian contractors maintain substantial installed populations of mechanically actuated units.
- Electric:Battery and trolley-assist configurations for zero-emission operation. Norwegian tunneling projects specify these for underground ventilation compliance.
- Diesel:Compression-ignition engines dominate current fleet composition. EPA Tier 4 Final compliance costs have raised base unit pricing, consolidating procurement around manufacturers with captive engine development.
- Hybrid:Combined diesel-electric architectures with energy recovery. UK urban infrastructure schemes in London and Birmingham specify these for low-decibel operation near residential zones.
Installed base concentration favors diesel; specification momentum favors hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for construction equipment manufacturing is redirecting multinational assembly investments toward domestic production bases. Australia's autonomous mining fleet expansions are pulling demand for electric-drive rigid dumpers. China's MIIT emission tiers are forcing parallel certification investments from integrated powertrain suppliers.
Australia
Open-pit operators at Pilbara and Queensland sites are specifying autonomous-capable haulers for fleet renewal programs. The country's emission standards align with EPA Tier 4 Final frameworks, raising aftertreatment compliance costs for imported machinery. Perth-based mining contractors are unbundling maintenance contracts from equipment purchases to prioritize uptime guarantees.
China
State-funded transport corridors through Sichuan, Yunnan, and Xinjiang are generating concentrated procurement for high-altitude-rated articulated dumpers. MIIT implements domestic emission test cycles that diverge from Euro-equivalent protocols, creating dual certification burdens. Chengdu and Xi'an industrial clusters are emerging as assembly hubs for western provincial infrastructure deployment.
India
National Highway Development segments are formalizing equipment traceability through CEA registration requirements. The PLI scheme offers domestic manufacturing incentives for multinational suppliers seeking tariff advantages. Mumbai and Bangalore satellite townships are generating concentrated demand for 20-30 ton capacity mini and small articulated units.
Germany
Quarrying operators in North Rhine-Westphalia and Bavaria specify articulated dumpers for tight extraction sites where turning radius determines cycle efficiency. EU Stage V mandates diesel particulate filters with selective catalytic reduction, consolidating procurement around vertically integrated manufacturers. Industrial park developers in Baden-Württemberg favor rental arrangements with guaranteed availability clauses.
Chile
Copper belt mining operations are expanding electric-drive rigid dumper fleets for autonomous haulage integration. The country's emission regulations track EPA Tier 4 Final standards, raising base unit costs for Tier 4 Final aftertreatment hardware. Antofagasta and Calama mining clusters are pulling specification toward AC motor systems with regenerative braking.
Global Construction Dumper Market Vendor Landscape
Player mix skews toward integrated powertrain manufacturers with captive engine development capabilities. The supplier base compresses around manufacturers possessing in-house aftertreatment integration expertise, while independent assemblers face sourcing constraints. Three archetypes dominate: vertically integrated global OEMs, regional specialists with modular chassis platforms, and autonomous technology integrators. Competitive moves concentrate on strategic partnerships for electric drive technology and geographic expansion through local assembly joint ventures.
Among integrated global OEMs, Caterpillar Inc., Komatsu Ltd., and AB Volvo anchor the premium tier through differentiated technical positioning. Caterpillar exemplifies the powertrain-integrated archetype with manufacturing depth across articulated and rigid product lines. Komatsu occupies a position within the autonomous-systems vector, while AB Volvo represents modular chassis architecture approaches that simplify regional customization requirements.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| AB Volvo |
| J C Bamford Excavators Ltd. |
| Liebherr |
| CNH Industrial N.V. |
| Deere & Company |
| Hitachi Construction Machinery Co., Ltd. |
| Doosan Corporation |
| Others |
Supply Flow & Price Mechanics
Ninety-to-one-hundred-twenty-day lead times for EPA Tier 4 Final aftertreatment modules concentrate pricing power among integrated manufacturers with captive engine development, while independent assemblers absorb cost pass-throughs from concentrated powertrain suppliers. Inventory cycles for electric drive components stretch longer than mechanical transmission equivalents, compressing margins for buyers lacking forward procurement contracts.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with EPA Tier 4 Final and EU Stage V compliance adding 12-18% to base unit costs over prior tier equivalents. Pricing stratifies across integrated powertrain manufacturers, modular chassis specialists, and autonomous technology integrators based on after-sales service bundling and regional customization capabilities. Cost compression in mid-tier articulated dumpers is intensifying because captive engine development capabilities consolidate among vertically integrated producers. Residential contractors in India exhibit highest price sensitivity due to rental market alternatives, while Australian mining majors prioritize lifecycle cost metrics over upfront capital expenditure.
Supply Chain Analysis
Germany, Japan, and the United States anchor precision engine component and aftertreatment system manufacturing for construction dumper powertrains. The supply chain draws from rare earth magnet suppliers for electric drive motors, high-strength steel producers for rigid frame fabrication, and semiconductor foundries for autonomous haulage control modules. Single-source vulnerability concentrates in selective catalytic reduction substrate production, where three suppliers dominate global capacity. Distribution runs through OEM-owned dealer networks for mining fleet contracts and independent rental channels for residential and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat structure where regulatory entrenchment through EPA Tier 4 Final and EU Stage V certification creates switching costs that lock in fleet operators with established service networks.
For Market Incumbents: Fortify captive powertrain development capabilities through backward integration into aftertreatment substrate production, eliminating single-source vulnerability in selective catalytic reduction supply. Expand maintenance service contract penetration among Australian autonomous fleet operators to capture lifecycle revenue streams. Prioritize certification investment for China's MIIT emission test cycles to defend position against regional specialists with domestic assembly advantages. For New Entrants and Emerging Players: Anchor in India's PLI scheme construction equipment incentives to establish tariff-advantaged assembly operations serving National Highway Development procurement channels. Target European urban infrastructure hybrid dumper specifications where noise ordinance compliance creates premium positioning opportunities. Pursue autonomous technology licensing partnerships with established chassis manufacturers rather than ground-up platform development. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized construction equipment divisions lacking integrated powertrain depth. Long-term viability favors manufacturers with demonstrated electric drive platform deployment and autonomous haulage system compatibility. Monitor battery-electric range validation protocol development as the critical inflection signal for specification confidence in mining applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aftertreatment Manufacturing | Captive selective catalytic reduction production eliminates Tier 4 Final supply bottlenecks for Komatsu and Caterpillar. |
| Autonomous Haulage System Licensing | LiDAR perception integration with telematics platforms enables retrofit revenue from existing Pilbara fleet operators. |
| PLI Scheme Domestic Assembly | Greenfield manufacturing in Chennai or Pune secures tariff advantages for CEA-registered highway construction equipment. |
| Hybrid Configuration Premium Tier Launch | Low-decibel specifications for London and Birmingham urban infrastructure command margin expansion over diesel equivalents. |
| Lifecycle Service Contract Unbundling | Predictive maintenance agreements with Australian mining majors displace upfront equipment sales with recurring uptime guarantees. |
Methodological Framework
The analysis maps articulated dumpers, rigid dumpers, mini dumpers, and track dumpers, each validated through maintenance directors at mining operations, OEM procurement teams, aftermarket service heads, and plant engineers at infrastructure contractors. Primary interviews with fleet managers in Australia's Pilbara region, CEA registration officials in India, and quarrying operators in Germany's North Rhine-Westphalia combined with secondary validation from EPA certification databases, EU Stage V type-approval records, MIIT emission test cycle documentation, and customs trade data for construction equipment imports. Bottom-up unit deployment estimates triangulated against top-down infrastructure investment flows across the analysis window.
Consistency checks validated volume and value outputs against autonomous fleet deployment announcements, state-funded corridor procurement tenders in Sichuan and Xinjiang, and rental fleet expansion disclosures. Segmentation modeling spanned frame geometry, end-use application, service type, and powertrain technology across the projection horizon. CAGRs derived from equipment replacement cycles, emission regulation phase-in timelines, and infrastructure investment trajectories without year-specific anchoring. Electric drive adoption curves incorporated duty-cycle validation protocol development status and charging infrastructure maturity assessments.
Decision-makers should treat outputs as directional under assumptions of sustained mining capital expenditure, continued state infrastructure funding in China and India, and stable emission regulatory phase-in schedules; material deviation would warrant model refresh. Specific risk factors include battery-electric range validation delays, MIIT emission test cycle divergence expansion, and autonomous haulage system integration setbacks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Thailand Construction Equipment Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Oxy-Fuel Welding Equipment Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Dozer Tire Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Asia-Pacific Completion Equipment Market
Construction Equipment
Snow Pushers Market
Construction Equipment
GCC Crane Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
LAMEA Water Pump Market