
 Global Welding Market | 2026-2036
Global Welding Market Size, Share, and Industry Trends Forecast 2026-2036
Global Welding Market Outlook
ASME-grade welding qualification standards is unwinding older process tiers across heavy fabrication. Lincoln Electric sustains dominance in North American pipeline construction through captive wire production. Fronius International GmbH positions itself in European automotive battery welding with adaptive arc control systems. ESAB Corporation leverages its consumables portfolio to anchor share in offshore energy projects.
Welding encompasses metallurgical joining processes that fuse base metals using thermal energy, filler material, and shielding gas to achieve specified tensile strength and fatigue resistance for structural integrity. Arc welding equipment retains the largest installed base across shipyards and infrastructure projects, while laser welding captures premium margins in aerospace turbine blade repair where heat-affected zone minimization determines airworthiness certification. Resistance welding dominates automotive body-in-white throughput for uncoated and coated steel stack-ups.
OSHA governs US workplace exposure limits for hexavalent chromium and manganese fumes, compelling investment in extraction-integrated welding stations. The EU F-Gas Regulation and REACH restrict shielding gas blends and electrode coatings, reshaping consumables formulation across European fabricators. China's MEE enforces emissions controls on welding fume discharge from coastal manufacturing zones. Stakeholders must monitor how carbon border adjustments and evolving hydrogen infrastructure standards redirect procurement toward low-emission joining technologies.
Market Dynamics
Robotic welding lines for electric vehicle battery enclosures are restructuring capital deployment across automotive supply chains, forcing tier-one fabricators to recalibrate qualification protocols and equipment procurement cycles.
Growth Catalysts
- EU F-Gas Regulation:Tightened shielding gas certification requirements in Europe are accelerating equipment replacement cycles among fabricators seeking compliant arc systems.
- Yangtze River Delta cluster:Concentrated shipyard and infrastructure investment in this Chinese manufacturing corridor sustains demand for heavy-gauge arc welding platforms.
- Aluminum laser welding:Heat-affected zone minimization capabilities are unlocking penetration into aerospace turbine blade repair applications previously dominated by electron beam processes.
Market Restraints
- Helium supply concentration:Reliance on Qatar and US federal reserve releases for shielding gas blends creates input cost volatility for precision welding operations.
- ASME Section IX qualification timelines:Extended welder certification periods delay workforce scaling for pressure vessel fabricators in North American energy projects.
- Adhesive bonding substitution:Structural adhesives are capturing share in automotive body-in-white applications below 2mm stack thickness, compressing resistance welding volumes.
Strategic Opportunities
- India's Gujarat industrial belt:Petrochemical and renewable energy fabrication hubs remain undersupplied with automated welding stations relative to projected capacity additions.
- EU Green Deal hydrogen infrastructure:Pipeline construction mandates for hydrogen transport networks are generating demand for low-hydrogen consumables and specialized qualification protocols.
- Remote welding monitoring:IoT-enabled arc data analytics are creating service revenue streams independent of equipment sales through predictive maintenance contracts.
Industry Challenges
- Certified welding engineer scarcity:Pipeline construction and nuclear fabrication sectors face 18-24 month backlogs for ASME-qualified inspection personnel.
- Legacy equipment integration:Retrofitting analog power sources with digital waveform control requires custom interface development that fragments vendor support ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Welding Market |
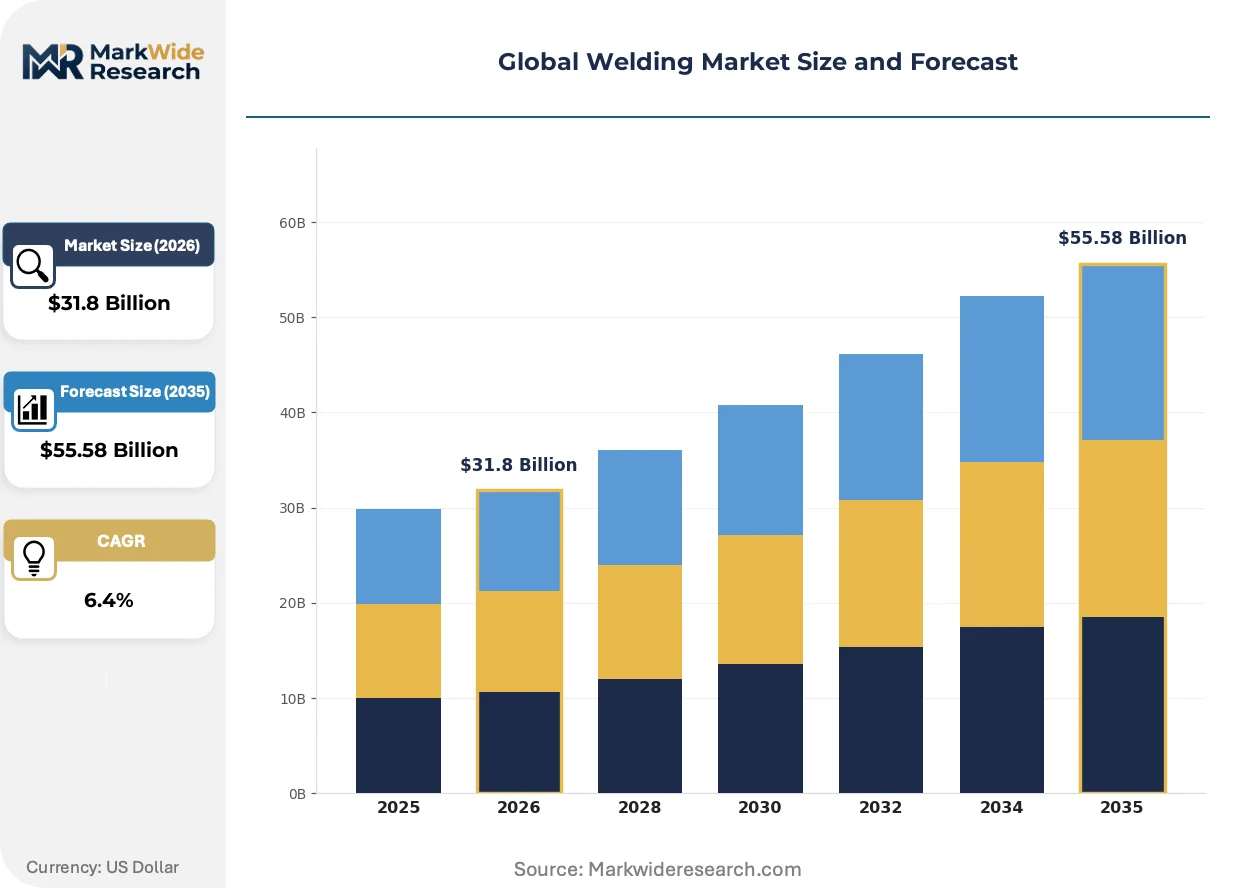
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $55.58 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Arc Welding, Resistance Welding, Laser Welding, TIG Welding End User: Aerospace, Automotive, Construction, Shipbuilding Product Type: Welding Equipment, Welding Consumables, Automation Technology, Safety Gear Installation: On-site, Off-site, Mobile Units, Workshop |
| Companies Covered | Emerson Electric Co. (Branson Ultrasonics), Miller Electric Manufacturing, Lincoln Electric, MS Ultraschall Technologie GmbH, Dukane Corporation, ESAB Corporation, Fronius International GmbH, Sonics & Materials, Inc., Illinois Tool Works (ITW) Welding, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Welding Market Strategic Shifts
Adaptive arc control systems and emissions-compliant consumables are converging to redefine process economics across high-mix, low-volume fabrication environments previously resistant to automation.
Hybrid laser-arc welding is displacing conventional multi-pass submerged arc processes in heavy plate applications. Offshore wind tower manufacturers in Northern Europe are adopting these systems to compress cycle times on 80mm+ thickness joints. The structural consequence is a compression in welder-hour requirements per ton of steel installed, reshaping labor cost models for marine fabrication.
China's GB welding standards revision is mandating fume extraction integration for all new stationary welding stations in coastal manufacturing zones. The industrial consequence is a forced obsolescence of legacy equipment without integrated ventilation. Japanese automotive battery enclosure fabricators are responding fastest, specifying adaptive arc systems that automatically modulate parameters to minimize fume generation.
Buyers are consolidating supplier relationships around full-process qualification capabilities rather than discrete equipment purchases. Automotive OEMs in Germany now require welding integrators to certify complete cell-to-pack joining sequences under single-source accountability. This pattern is most visible in European electric vehicle supply chains, where battery enclosure welding represents the highest-consequence quality gate in vehicle assembly.
Global Welding Market Segmentation
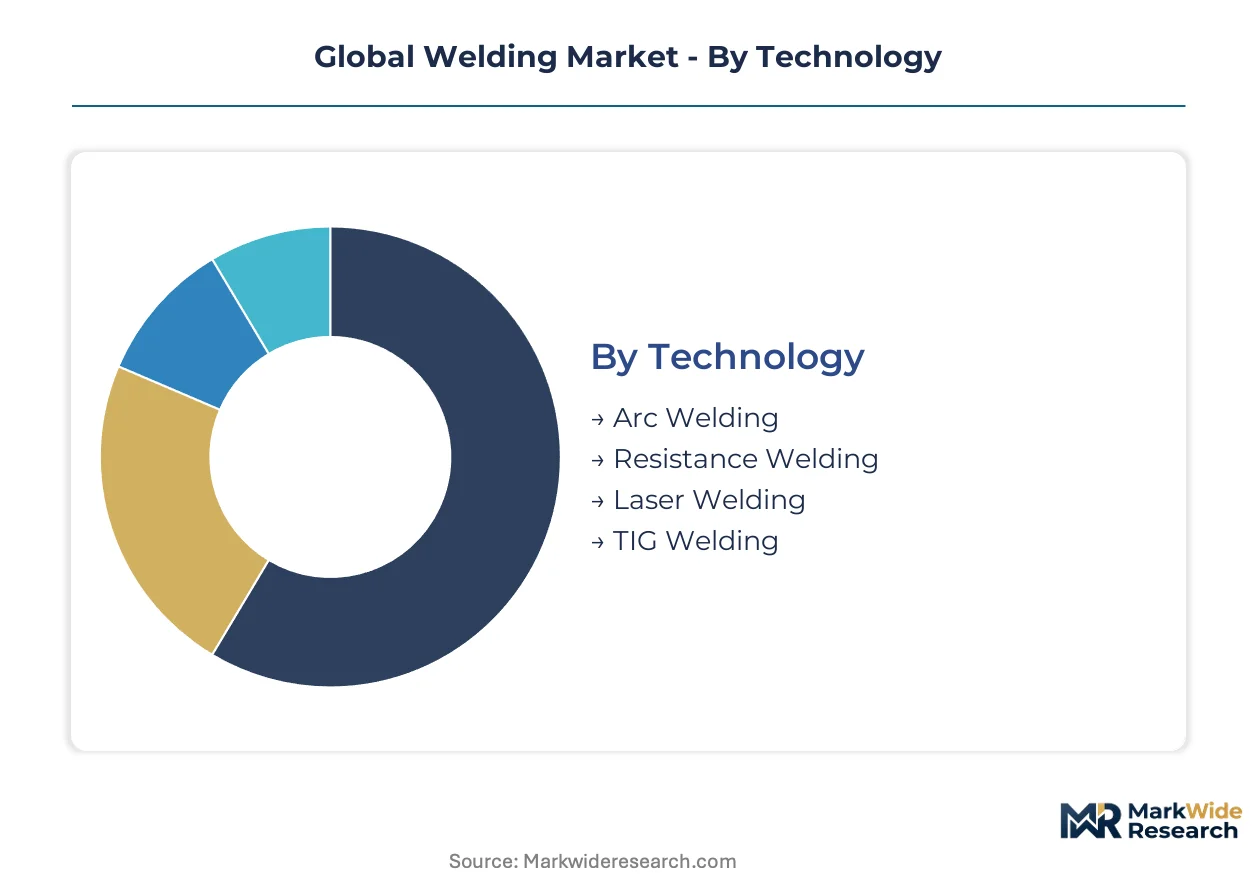
Welding market segmentation reveals distinct margin architectures across technology platforms and procurement modes. Equipment suppliers and consumables manufacturers face divergent capital intensity and replacement cycle dynamics that reshape competitive positioning.
Technology:
Margin pools concentrate in precision-controlled processes where specification certification creates pricing power.
- Arc Welding:Shielded metal and flux-cored processes dominate heavy fabrication through deep penetration capabilities and field portability. Shipyards in China's Yangtze River Delta and infrastructure contractors across India's Gujarat industrial belt sustain demand for 500-amp industrial platforms. ASME Section IX qualification requirements lock in consumables pull-through.
- Laser Welding:Solid-state fiber lasers deliver sub-millimeter heat-affected zones critical for aerospace turbine blade repair and battery tab joining. German automotive OEMs specify these systems for aluminum battery enclosure welding where electron beam alternatives face vacuum chamber constraints.
- Resistance Welding:Capacitive discharge and AC transformer systems serve high-throughput automotive body-in-white lines.
- TIG Welding:Tungsten inert gas processes retain share in precision pipe welding and nuclear qualification environments.
Arc Welding holds installed capacity. Laser Welding is rotating up the share rankings.
End User:
Application concentration determines equipment specification tiers and service attach rates.
- Automotive:Battery enclosure welding lines command premium system integration as OEMs consolidate qualification accountability under single-source vendors. German and Japanese manufacturers are expanding robotic capacity for electric vehicle platforms.
- Aerospace:Turbine blade repair and airframe joining require Nadcap-certified processes where heat-affected zone documentation determines airworthiness. Laser and electron beam systems capture margin through specification lock-in.
- Construction:Infrastructure and commercial building fabrication drives demand for portable arc equipment and flux-cored wire.
- Shipbuilding:Korean and Chinese yards consume heavy-gauge submerged arc systems for hull panel assembly.
Automotive commands specification leadership. Aerospace carries the steepest expansion trajectory in value per weld.
Product Type:
Recurring revenue intensity separates consumables from capital equipment business models.
- Welding Consumables:Solid wire, flux-cored electrodes, and specialty alloys generate repeat purchase velocity tied to fabrication hours. REACH and EU F-Gas Regulation are reformulating coating chemistries across European supply chains.
- Welding Equipment:Power sources and wire feeders represent installed base platforms where waveform control digitization is displacing analog systems. Retrofit complexity fragments vendor support ecosystems.
- Automation Technology:Robotic cells and seam tracking systems compress labor content per ton of steel installed.
- Safety Gear:Fume extraction-integrated helmets and respiratory systems face OSHA hexavalent chromium exposure mandates.
Consumables anchor recurring revenue. Automation Technology is gaining share fastest in new capital deployment.
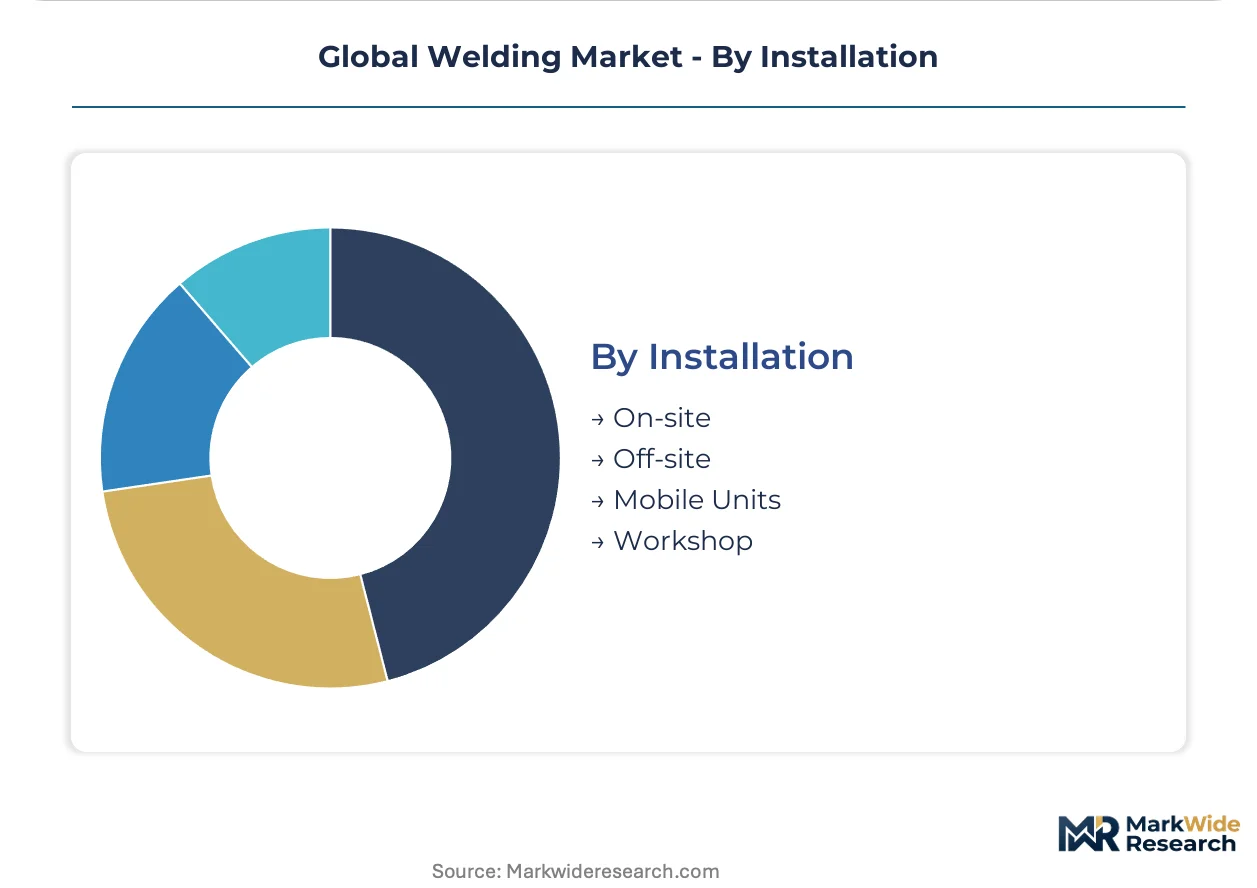
Installation:
Site constraints dictate equipment mobility requirements and service response models.
- Workshop:Fixed-position stationary systems with integrated fume extraction dominate qualification-critical fabrication. China's GB standards revision is mandating ventilation integration for all new coastal manufacturing zone installations.
- On-site:Engine-driven portable generators and suitcase wire feeders serve pipeline construction and infrastructure repair. Helium supply concentration from Qatar and US federal reserves creates input cost volatility for precision field welding.
- Off-site:Prefabrication yards near petrochemical hubs consolidate production for modular construction.
- Mobile Units:Containerized welding stations serve remote wind tower and offshore platform installation.
Workshop retains qualification density. On-site is climbing the fastest in project-scale deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal divergent welding equipment trade balances across major fabrication economies. China's Yangtze River Delta manufacturing corridor generates surplus arc system shipments to Southeast Asian shipyards. Germany and Japan maintain welding technology trade surpluses through precision laser and robotic system exports. The United States imports specialized consumables while exporting heavy-industrial power sources to Latin American energy projects.
China
Shipyard expansion along the Yangtze River Delta and Pearl River Delta sustains demand for submerged arc and flux-cored welding platforms. MEE emissions controls on welding fume discharge from coastal manufacturing zones are forcing ventilation-integrated equipment upgrades. The Ningbo-Zhoushan port cluster consumes heavy-gauge systems for hull panel assembly serving container vessel export contracts.
Germany
Automotive battery enclosure fabrication for electric vehicle platforms drives robotic welding line deployment across Bavaria and Baden-Württemberg. EU F-Gas Regulation certification requirements are accelerating replacement cycles for shielding gas-dependent arc systems. Stuttgart's automotive engineering corridor concentrates adaptive arc control system integration for aluminum battery tray welding sequences.
United States
Gulf Coast petrochemical construction and Permian Basin pipeline projects sustain demand for portable engine-driven welding generators. OSHA hexavalent chromium exposure limits compel investment in extraction-integrated welding stations across Texas and Louisiana fabrication yards. Houston's energy corridor anchors modular construction prefabrication serving offshore platform installation contracts.
Japan
Automotive OEMs in Aichi Prefecture and Kanagawa Prefecture are expanding robotic capacity for battery enclosure welding on electric vehicle platforms. METI industrial efficiency standards are promoting waveform-controlled power sources in precision fabrication environments. Toyota City's automotive supply chain exemplifies single-source accountability requirements for complete cell-to-pack joining sequence certification.
India
Gujarat's petrochemical and renewable energy fabrication hubs remain undersupplied with automated welding stations relative to projected capacity additions. BIS welding equipment certification protocols are tightening import compliance requirements for European and East Asian suppliers. Hazira's industrial belt concentrates demand for heavy-gauge arc platforms serving refinery and LNG terminal construction.
Global Welding Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and qualification depth dimensions. The market exhibits tiered concentration where multinational corporations control premium certification-driven segments while regional fabricators capture price-sensitive workshop equipment procurement. Three archetypes dominate: full-process integrators bundling equipment-consumables-service, precision technology specialists in laser and electron beam systems, and volume-driven consumables manufacturers. Consolidation through consumables portfolio acquisition and geographic expansion into undersupplied industrial belts represent the dominant competitive vectors.
Among North American-listed manufacturers, Lincoln Electric and ESAB Corporation exemplify full-process integrators with captive consumables production and qualification protocol bundling. Fronius International GmbH occupies a position within the European precision technology tier, representing adaptive arc control specialization for automotive battery fabrication. Illinois Tool Works anchors diversified industrial portfolio positioning across multiple welding technology segments. These three entities collectively illustrate how competitive positioning stratifies between recurring revenue intensity through consumables pull-through and premium system pricing through specification certification lock-in.
| Leading Market Players |
|---|
| Emerson Electric Co. (Branson Ultrasonics) |
| Miller Electric Manufacturing |
| Lincoln Electric |
| MS Ultraschall Technologie GmbH |
| Dukane Corporation |
| ESAB Corporation |
| Fronius International GmbH |
| Sonics & Materials, Inc. |
| Illinois Tool Works (ITW) Welding |
| Others |
Value Chain & Pricing Dynamics
Helium-to-argon substitution in precision shielding gas blends is redrawing procurement geography while compressing margins for high-specification welding operations across European and North American fabricators.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on ASME certification grade and captive consumables integration, with German automotive OEMs least sensitive due to single-source accountability requirements. Cost compression in economy-tier arc equipment is intensifying because Chinese manufacturers are scaling flux-cored wire production. Contract fabricators in India's Gujarat industrial belt exhibit highest price sensitivity, prioritizing per-unit equipment costs over lifecycle service bundling.
Supply Chain Analysis
Inventory cycles for tungsten electrodes and specialty alloys stretch 8-14 weeks, constraining just-in-time procurement for aerospace turbine repair shops. Manufacturing concentrates in China, Germany, and Japan, with raw material flows drawing from Chilean copper concentrate, Chinese rare earth processing, and Qatari helium reserves. Single-source vulnerability around Qatar's helium supply creates input cost volatility for laser welding operations. Distribution runs through authorized integrator networks that bundle qualification protocol support with equipment deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across battery enclosure welding specifications is creating specialist niches as automotive OEMs abandon multi-vendor qualification models.
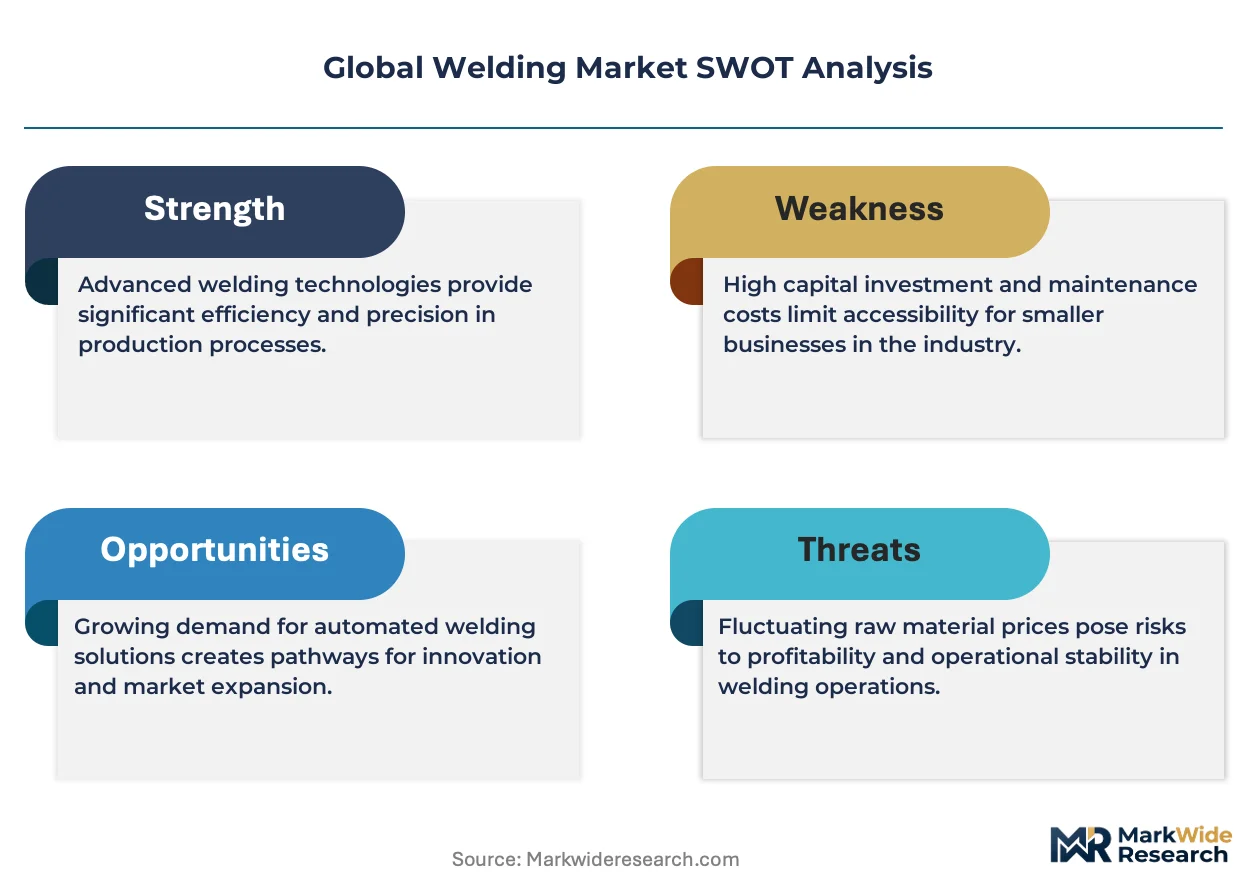
For Market Incumbents: Consolidate consumables portfolios through captive wire production investments to defend against Chinese flux-cored electrode imports. Deepen backward integration into aluminum alloy feedstock to secure margin pools in automotive battery tray fabrication. Lock in ASME Section IX qualification bundling to raise switching costs for pipeline construction contractors. For New Entrants and Emerging Players: Differentiate on adaptive arc control software for high-mix, low-volume job shops underserved by robotic system vendors. Target India's Hazira industrial belt with automated station leasing models that bypass capital-constrained fabricator procurement cycles. Pursue EU F-Gas Regulation compliance certification as the primary go-to-market credential. For Investors and Strategic Acquirers: The market sits at an equipment replacement phase that favors consumables-anchored business models over pure-play power source manufacturers. Five-to-ten year viability hinges on fume extraction integration mandates spreading beyond China's coastal zones. Acquire welding integrators with complete cell-to-pack certification capabilities for European automotive supply chains. Monitor EU Green Deal hydrogen pipeline construction contract awards as inflection signal for low-hydrogen consumables demand.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Consumables Integration | Lincoln Electric's wire production locks in recurring revenue across North American pipeline projects. |
| Adaptive Arc Control Development | Fronius International GmbH positions for German automotive battery enclosure specification leadership. |
| Fume Extraction Mandate Compliance | China's MEE standards force equipment replacement cycles in Yangtze River Delta shipyards. |
| Hydrogen Infrastructure Qualification | EU Green Deal pipelines require specialized low-hydrogen consumables certification protocols. |
| Remote Monitoring Service Launch | IoT-enabled arc analytics create predictive maintenance revenue independent of equipment sales. |
Study Parameters
The analysis maps arc welding equipment, laser systems, consumables, and automation technology segments, each validated through fabrication engineers, OEM procurement directors, and aftermarket service heads. Primary interviews with plant managers at Yangtze River Delta shipyards, technical R&D directors at European automotive battery suppliers, and maintenance directors at Gulf Coast petrochemical facilities combined with secondary validation from customs/trade data, SEC 10-K filings, and welding equipment certification databases. Bottom-up equipment shipment tallies and top-down fabrication hour estimates were triangulated against consumables pull-through rates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology platform, end-use industry, product type, and installation mode segmentation dimensions. CAGRs were derived from equipment replacement cycle analysis and consumables intensity per fabrication hour. Forecast inputs incorporated EU F-Gas Regulation compliance timelines and China's GB standards revision implementation patterns.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle battery enclosure investment levels or helium supply stability would require recalibration. Forecasts reflect documented assumptions regarding qualification protocol standardization and emissions regulation enforcement intensity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Boom Cranes Market
Construction Equipment
Rotary Trommel Market
Construction Equipment
Rotary Dryers Market
Construction Equipment
Yard Crane Market
Construction Equipment
Global Portable Sawmills Market
Construction Equipment
Gear Shaping Machine Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Global Crane and Hoist Market
Construction Equipment
Induction Furnace Market
Construction Equipment
Static Crane Market
Construction Equipment
Spray Washer Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
Cement Consistency Meter Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Bucket Teeth and Tips Market