
 Rockbreakers Market | 2026-2036
Rockbreakers Market Size, Share, and Industry Trends Forecast 2026-2036
Rockbreakers Market Analytics
The rockbreakers market is restructuring around a sharp split between premium hydraulic systems built for continuous mining duty and commodity-grade pneumatic units serving intermittent construction sites. Sandvik leverages its integrated drill-and-break automation platform to command premium positioning in underground hard-rock environments. Atlas Copco sustains broad geographic coverage through rental-service networks that reduce customer capital burdens. Komatsu differentiates by embedding breaker controls within its unified machine operating systems.
Rockbreakers are percussive attachments or standalone machines that deliver repeated high-energy impacts through hardened tool steel moil points or chisels, typically operating at blow frequencies between 300 and 1,500 strikes per minute to fracture consolidated rock and reinforced concrete. Their primary industrial purpose centers on primary ore fragmentation in open-pit and underground mines, secondary breaking of oversize material, and controlled demolition of structural concrete. Hydraulic breakers command the dominant share of mining revenue due to their power-to-weight ratios and compatibility with carrier excavators across tonnage classes, while electric breakers represent the fastest-growing product category as tunneling contractors and urban demolition firms confront emissions restrictions and noise limits. The rental service segment is expanding faster than equipment sales in mature European and North American markets, reflecting contractor preferences for operational flexibility and reduced maintenance exposure.
The US Mine Safety and Health Administration enforces operator protection standards that shape cabin design and remote-control adoption for breaker-mounted carriers, while the EU Machinery Directive and CE marking requirements govern structural integrity and acoustic emissions for units sold across member states. ISO 10243 and ISO 28927 establish baseline testing protocols for vibration emission and operator hand-arm exposure that manufacturers must certify against for market access. Stakeholders should monitor how battery-electric carrier platforms from mining OEMs reshape power-interface standards for breaker attachments, as interoperability decisions made in the next equipment replacement cycle will lock in supplier relationships for a decade or more.
Market Dynamics
Underground mining contractors in Australia are accelerating fleet utilization of hydraulic breakers to access deeper ore bodies, while municipal noise ordinances in Germany force manufacturers toward quieter electric designs. This tension between extraction depth requirements and urban environmental compliance is restructuring product development priorities across the sector.
Growth Catalysts
- Hard-Rock Extraction Intensification:Iron ore producers in Western Australia's Pilbara region face accelerating fragmentation requirements as surface deposits deplete and operations descend into harder formations.
- CE Marking Acoustic Standards:The EU Machinery Directive's tightened noise emission thresholds are compelling manufacturers to redesign breaker housings and damping systems for European tunneling contracts.
- Battery-Electric Carrier Proliferation:Mining OEMs are rolling out electric excavator platforms that demand compatible electric breaker attachments, creating synchronized replacement cycles across equipment fleets.
Market Restraints
- Specialized Steel Input Volatility:Tool steel moil points require premium-grade chromium-molybdenum alloys whose pricing fluctuates with mining commodity cycles, compressing attachment manufacturer margins.
- Component Supply Concentration:High-pressure hydraulic seals and accumulator systems rely on a concentrated supplier base in Central Europe, exposing breaker assemblers to single-source risk.
- Pneumatic Substitution Ceiling:Compressed-air breakers retain cost advantages for intermittent construction duty, limiting hydraulic unit penetration in developing infrastructure markets.
Strategic Opportunities
- Remote Control Integration:Breaker-mounted carriers with teleoperation capability address MSHA operator proximity standards while opening automated breaking workflows in hazardous stoping environments.
- Rental-Service Channel Expansion:Equipment-as-a-service models reduce contractor capital exposure and maintenance burden, particularly in mature European and North American construction markets.
- ISO 10243 Certification Arbitrage:Manufacturers achieving verified low-vibration ratings gain preferential positioning with unionized mining contractors facing hand-arm syndrome liability concerns.
Industry Challenges
- Automation Integration Complexity:Embedding breaker controls within unified machine operating systems requires software engineering capabilities that traditional attachment manufacturers lack.
- Interoperability Lock-In Risk:Power-interface decisions made during the current battery-electric carrier replacement cycle will freeze supplier relationships for extended periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rockbreakers Market |
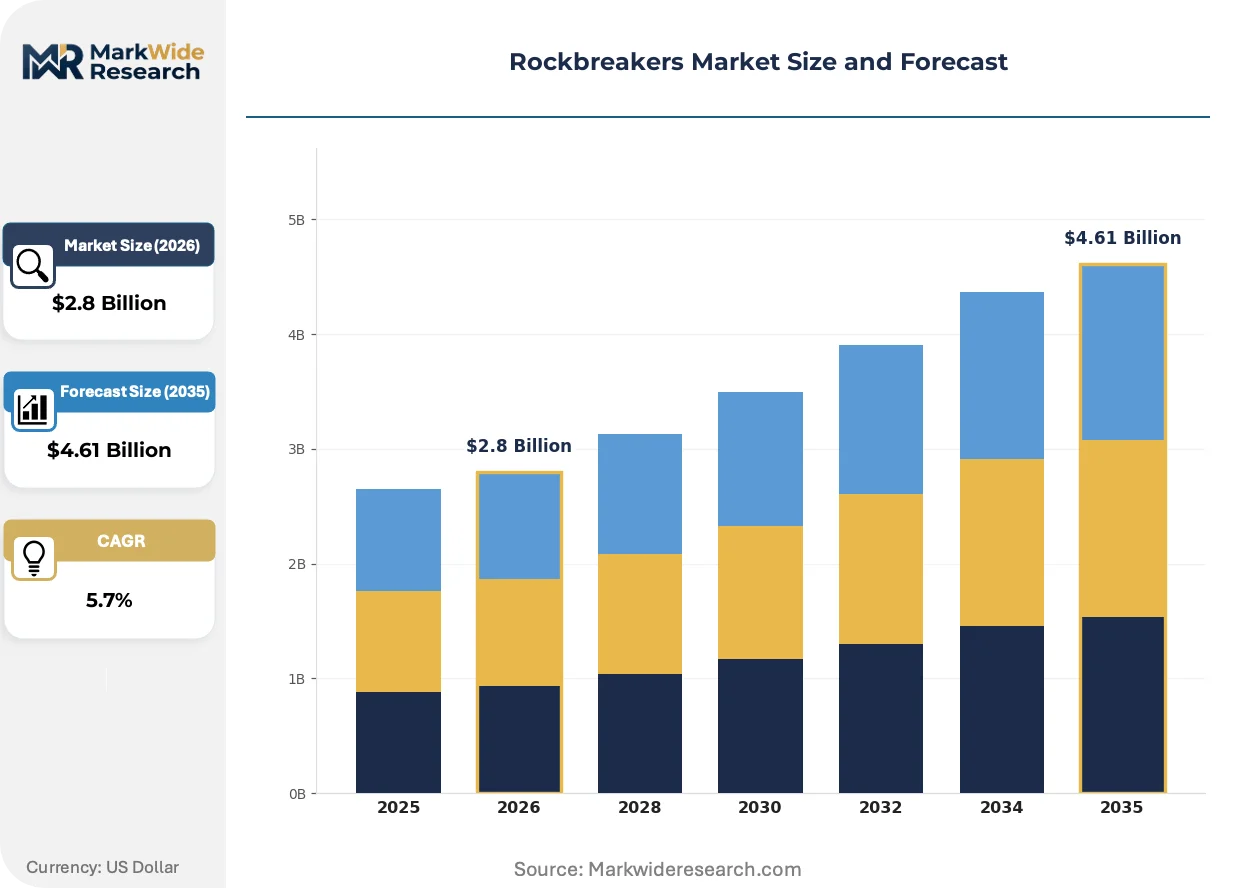
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Breakers, Pneumatic Breakers, Electric Breakers, Handheld Breakers Application: Construction, Mining, Demolition, Road Works End User: Contractors, Mining Companies, Infrastructure Developers, Builders Service Type: Sales, Rental, Maintenance, Repair |
| Companies Covered | Sandvik, Atlas Copco, Epiroc, Komatsu, Caterpillar, Furukawa Rock Drill, Indeco Ind. SpA, Montabert, NPK Construction, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rockbreakers Market Evolving Landscape
Breaker technology is converging around three vectors: powertrain electrification, control system integration, and service model restructuring. These shifts are compressing the traditional separation between attachment manufacturers and carrier OEMs.
Electric breaker architectures are modularizing around standardized battery pack interfaces and swappable power electronics modules. Tunneling contractors in urban environments are adopting these units to comply with emissions restrictions and noise limits. This modularization is enabling manufacturers to offer performance upgrades through firmware and component swaps rather than complete unit replacement.
German municipal regulators are enforcing stricter noise and vibration ordinances that exceed baseline EU Machinery Directive requirements. These local standards are pushing manufacturers to develop active damping systems and encapsulated breaker housings. Urban demolition firms in Stuttgart, Munich, and Hamburg are now specifying certified low-emission units as mandatory bid prerequisites.
Contractor preferences are gravitating toward operational flexibility over equipment ownership. Rental-service networks are displacing direct sales in mature markets, with customers prioritizing uptime guarantees and maintenance absorption. Western Australia's mining contractors are piloting subscription models that bundle breaker attachments with carrier excavators under single fleet management contracts.
Rockbreakers Market Segmentation
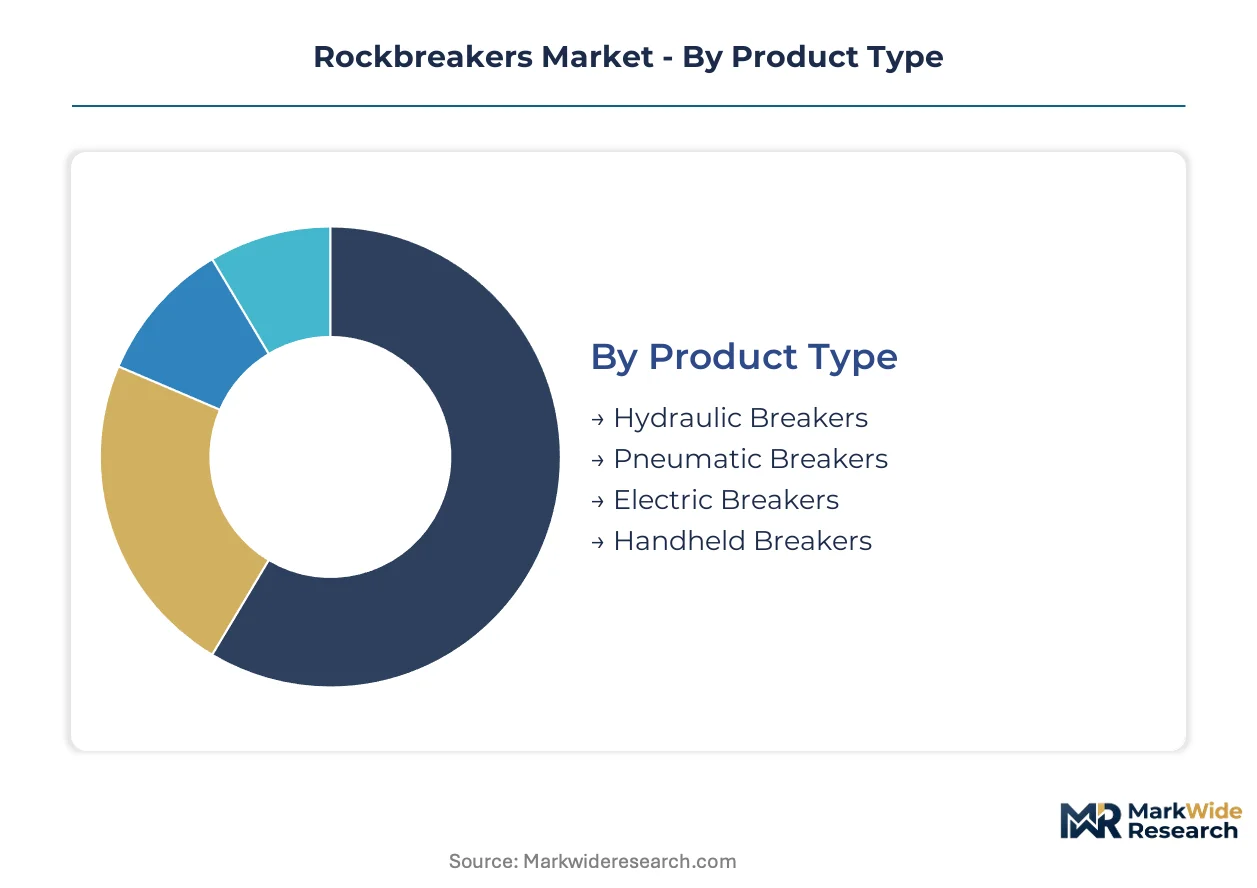
Equipment replacement cycles in mining and construction dictate how rockbreaker demand fragments across product architectures and service models. Fleet managers prioritize interoperability with carrier platforms over standalone performance metrics, reshaping how manufacturers configure their segment portfolios.
Product Type:
Upgrade decisions hinge on powertrain compatibility with emerging battery-electric carrier fleets and the torque requirements of descending ore bodies.
- Hydraulic Breakers:These units deploy high-pressure oil circuits to deliver percussive force through hardened tool steel moil points, with power-to-weight ratios optimized for continuous mining duty. Demand concentrates in Western Australia's Pilbara iron ore operations where hard-rock fragmentation requirements intensify as surface deposits deplete. Underground contractors specify these for compatibility with existing excavator fleets.
- Electric Breakers:Battery-powered architectures with modular power electronics and swappable battery pack interfaces eliminate hydraulic fluid contamination risks. Urban demolition contractors in Stuttgart, Munich, and Hamburg specify these to comply with municipal noise ordinances exceeding baseline EU Machinery Directive thresholds. Tunneling firms facing emissions restrictions drive specification.
- Pneumatic Breakers:Compressed-air units retain cost advantages for intermittent construction duty in developing infrastructure markets.
- Handheld Breakers:Portable units serve specialized concrete removal and confined-space applications where carrier-mounted systems cannot access.
Hydraulic breakers sit at the top of the volume ranking, with electric breakers climbing the fastest.
Application:
Cost tier differentiation separates premium continuous-duty specifications from intermittent-use commodity configurations.
- Mining:Primary ore fragmentation in open-pit and underground operations demands blow frequencies between 300 and 1,500 strikes per minute through consolidated formations. Australian underground contractors accelerate fleet utilization to access deeper ore bodies. Automation integration with drill-and-break platforms commands premium positioning.
- Construction:Secondary breaking of oversize material and foundation work requires compatibility across excavator tonnage classes. European and North American contractors increasingly favor rental-service models to reduce capital exposure and maintenance burden.
- Demolition:Controlled structural concrete removal in urban environments faces strict acoustic emission limits from municipal regulators.
- Road Works:Pavement breaking and utility trenching applications prioritize portability and rapid deployment.
Mining commands the highest revenue per unit installed, with demolition gaining share fastest on urban infrastructure renewal cycles.
End User:
Customer type determines procurement structure, with capital-intensive owners favoring direct purchase and project-based operators prioritizing operational flexibility.
- Mining Companies:Integrated ore producers specify breakers as part of unified fleet management contracts, locking in supplier relationships through synchronized replacement cycles with carrier platforms. Western Australian iron ore producers drive hard-rock extraction intensification requirements. Battery-electric carrier proliferation demands compatible attachment power interfaces.
- Contractors:Project-based operators in European and North American construction markets gravitate toward equipment-as-a-service models. Uptime guarantees and maintenance absorption outweigh ownership considerations. Subscription pilots bundling breaker attachments with carrier excavators are expanding in Western Australia.
- Infrastructure Developers:Long-horizon public works projects specify through tender processes with certified low-vibration and low-emission prerequisites.
- Builders:Smaller-scale construction firms favor rental channels for intermittent breaking requirements.
Mining companies anchor premium segment revenue, with contractors expanding most quickly through rental channel migration.
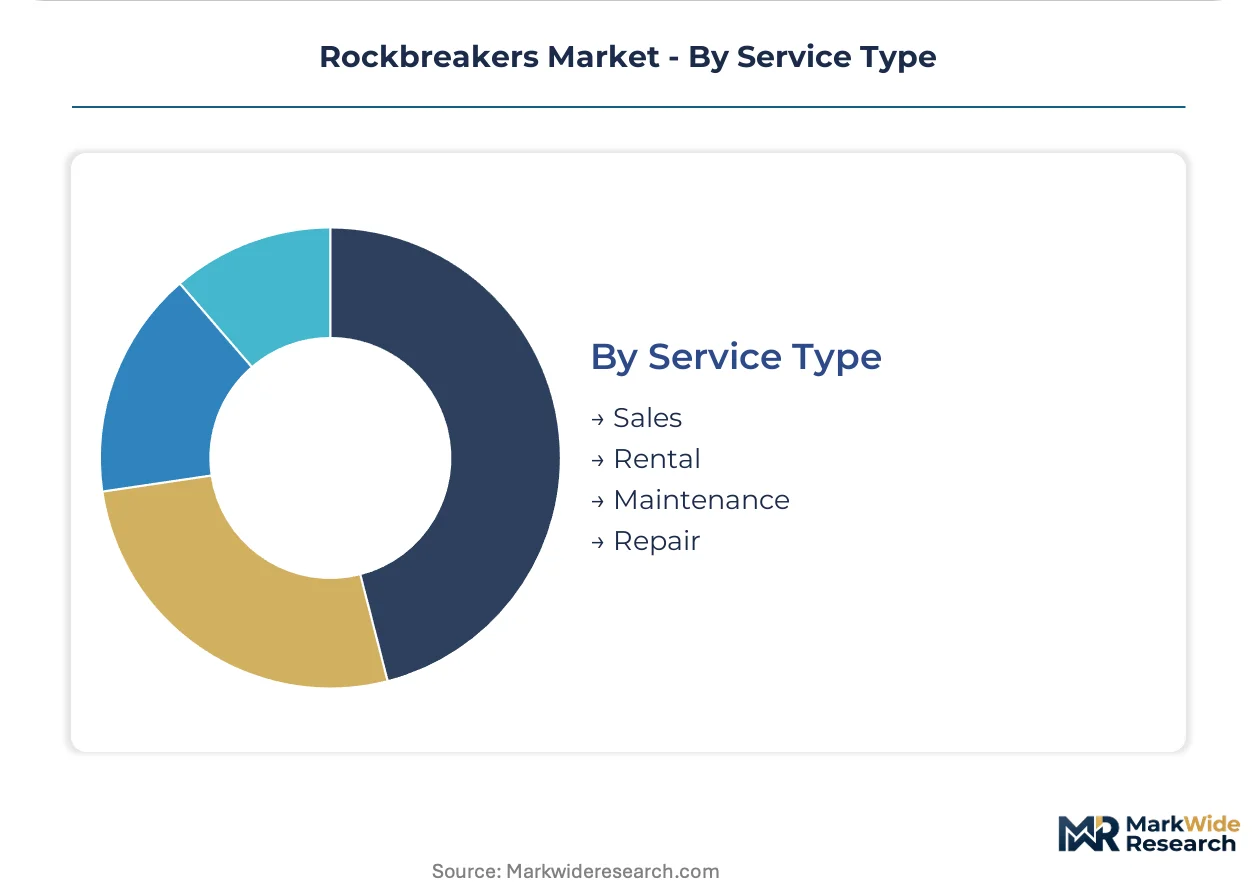
Service Type:
Margin structure varies sharply between one-time equipment sales and recurring service revenue streams.
- Rental:Equipment-as-a-service models absorb maintenance burden and guarantee uptime, displacing direct sales in mature European and North American markets. Contractors prioritize operational flexibility over capital deployment. Western Australian mining contractors pilot subscription bundling of breaker attachments with carrier excavators under single fleet management contracts.
- Sales:Direct equipment purchase retains dominance in mining operations with dedicated maintenance capabilities and long-horizon asset utilization.
- Maintenance:Preventive service contracts on hydraulic seal and accumulator systems generate recurring revenue concentrated with Central European component suppliers.
- Repair:Break-fix services for tool steel moil point replacement respond to wear rates in abrasive ore formations.
Sales still dominate absolute transaction value, with rental climbing fastest on contractor preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mining equipment operators in Western Australia anchor the largest concentration of hydraulic breaker demand, while German engineering talent drives electric breaker innovation for urban compliance.
Australia
Underground contractors accelerate fleet utilization to access deeper ore bodies in the Pilbara iron ore belt. The country's national mining safety regulator enforces operator proximity standards that shape remote-control adoption. Perth-based equipment distributors pilot subscription bundling of breaker attachments with carrier excavators under unified fleet contracts.
Germany
Municipal regulators in Stuttgart, Munich, and Hamburg enforce noise ordinances exceeding baseline EU Machinery Directive thresholds. The KBA and regional environmental agencies mandate active damping systems for urban demolition contracts. Engineering clusters in Baden-Württemberg develop encapsulated breaker housings for tunneling firms facing emissions restrictions.
United States
Iron ore producers in Minnesota's Mesabi Range and copper operators in Arizona deploy hydraulic breakers for hard-rock fragmentation. The Mine Safety and Health Administration enforces cabin design standards for breaker-mounted carriers. Equipment rental networks in Texas and the Mountain West expand maintenance-absorption service models.
China
Infrastructure developers in the Yangtze River Delta and Pearl River Delta specify pneumatic and hydraulic units for foundation work. The Ministry of Industry and Information Technology oversees GB standards for construction machinery emissions. State-owned mining enterprises in Inner Mongolia and Shanxi Province drive demand for continuous-duty hydraulic systems.
Brazil
Iron ore majors in Minas Gerais and copper developers in Pará deploy breakers for primary ore fragmentation. The national mining regulator ANM aligns equipment certification with ISO vibration emission protocols. Equipment distributors in São Paulo state expand rental-service channels to reduce contractor capital exposure.
Rockbreakers Market Competitive Landscape
Top-tier vendors anchor premium hydraulic systems for continuous mining duty, while commodity-grade specialists serve intermittent construction applications. The competitive field separates into three strategic archetypes: integrated mining equipment OEMs with unified operating systems, dedicated attachment manufacturers with rental-service networks, and regional fabricators with cost-optimized pneumatic offerings. Dominant competitive moves include strategic partnerships between breaker assemblers and battery-electric carrier OEMs, plus vertical integration into high-pressure hydraulic seal production.
Within the integrated-systems tier, Sandvik and Atlas Copco exemplify premium positioning through automation platforms and geographic coverage networks. Komatsu occupies a position bridging attachment manufacturing with unified machine operating systems. Epiroc represents the specialized mining equipment archetype with deep underground hard-rock expertise. These three anchors demonstrate how power-interface standardization decisions in the current equipment replacement cycle will freeze supplier relationships for extended periods.
| Leading Market Players |
|---|
| Sandvik |
| Atlas Copco |
| Epiroc |
| Komatsu |
| Caterpillar |
| Furukawa Rock Drill |
| Indeco Ind. SpA |
| Montabert |
| NPK Construction |
| Others |
Value Network & Pricing Analysis
Skilled welders and hydraulic technicians in Baden-Württemberg anchor premium-tier production costs, with labor-rate differentials between German engineering clusters and Central European assembly plants driving spreads between certified mining-grade units and commodity construction breakers.
Pricing Analysis
Bundled subscription models for fleet-as-a-service offerings diverge sharply from unbundled equipment-only transactions. Three-tier pricing structure across premium automation-integrated, standard hydraulic, and economy pneumatic levels stratifies by certification grade and after-sales service absorption. Cost compression in the standard tier is intensifying because tool steel alloy volatility compresses attachment manufacturer margins. Project-based contractors in European construction markets exhibit highest price sensitivity, while integrated mining companies with unified fleet contracts show least.
Supply Chain Analysis
Refurbishment flows for hydraulic seal and accumulator systems concentrate remanufacturing value in Germany and Austria, with worn moil points cycling back through Central European service depots. High-pressure hydraulic components draw from concentrated supplier bases in Germany, Italy, and Sweden. Single-source vulnerability for premium-grade chromium-molybdenum tool steel exposes breaker assemblers to mining commodity cycle swings. Distribution runs through OEM-authorized service networks for mining accounts and independent rental channels for construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in rockbreakers rests on rental-service model penetration absorbing maintenance burden and shifting revenue to recurring streams, plus premium-tier capture through automation integration with battery-electric carrier fleets.
For Market Incumbents: Extend automation platform control by embedding breaker controls within unified machine operating systems before interoperability decisions freeze supplier relationships. Capture backward integration into high-pressure hydraulic seal production to reduce single-source exposure from Central European component suppliers. Defend against emerging electric breaker specialists by accelerating ISO 10243 low-vibration certification across product lines.
For New Entrants and Emerging Players: Urban demolition contractors in German cities with municipal noise ordinances exceeding EU Machinery Directive thresholds represent an underserved buyer archetype with mandatory certified low-emission bid prerequisites. Tunneling firms facing emissions restrictions in Stuttgart, Munich, and Hamburg offer penetrable entry points. Subscription bundling pilots with Perth-based equipment distributors provide a proven go-to-market angle for fleet-as-a-service expansion.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional pneumatic breaker fabricators with cost-optimized offerings for developing infrastructure markets. Long-term viability over the analysis window favors targets with electric breaker architectures and modular power electronics capabilities. Monitor battery-electric carrier rollout announcements from mining OEMs as the inflection indicator for synchronized replacement cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Automation Platform Integration | Embedding breaker controls within Sandvik and Komatsu unified operating systems locks in supplier relationships for extended replacement cycles. |
| Rental-Service Channel Expansion | Equipment-as-a-service models with uptime guarantees absorb maintenance burden and displace direct sales in European and North American markets. |
| Electric Breaker Architecture Development | Modular battery pack interfaces and swappable power electronics enable firmware-based performance upgrades for urban compliance requirements. |
| Backward Integration into Seals | In-house production of high-pressure hydraulic seals reduces single-source vulnerability from concentrated Central European supplier bases. |
| ISO 10243 Certification Investment | Verified low-vibration ratings command preferential positioning with unionized mining contractors facing hand-arm syndrome liability exposure. |
Research Methodology
Coverage spans Australia, Germany, the United States, China, and Brazil, with primary inputs from each market combining structured interviews with mine maintenance directors, OEM procurement teams, aftermarket service heads, and tunneling contractors with secondary validation. Regulatory filings from MSHA, KBA, and ANM, equipment customs and trade data, SEC filings from listed mining equipment OEMs, and ISO certification databases inform bottom-up and top-down triangulation.
Granularity-level modeling disaggregates volume and value outputs by powertrain architecture, application intensity tier, service model structure, and regional regulatory cluster across the projection horizon. CAGRs derive from equipment replacement cycle timing, carrier fleet electrification trajectories, and ore body depth progression curves specific to Pilbara iron ore and Mesabi Range operations.
Inputs from mine operators and equipment distributors were available through the study window; gaps in battery-electric carrier platform specification timing introduce uncertainty bands around attachment power-interface adoption curves. Forecasts reflect assumptions on municipal noise ordinance enforcement intensity and tool steel alloy pricing stability. Practitioners should monitor battery-electric excavator rollout schedules and German municipal ordinance amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Electric Excavators Market
Construction Equipment
Australia Concrete Pump Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Cutting and Bending Machine Market
Construction Equipment
France Construction Equipment Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Europe Road Marking Machine Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Part Feeder Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Casting Equipment Market
Construction Equipment
Heavy Construction Equipment Rental Market