
 Mobile Crushers and Screeners Market | 2026-2036
Mobile Crushers and Screeners Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Crushers and Screeners Market Intelligence
The bundling of equipment with long-term service and telematics packages is shifting procurement decisions for large contractors. Metso Corporation leverages its extensive service network to support these integrated offerings. Sandvik AB competes through its focus on automation and remote control technologies integrated into its machines. McCloskey International specializes in high-throughput, robust equipment for the quarrying and recycling sectors.
Mobile crushers and screeners are self-contained, track-mounted or wheeled plants for on-site material size reduction and separation. Performance is defined by throughput capacity in tons per hour and the ability to handle abrasive materials. Jaw crushers lead in primary crushing applications, while cone crushers are essential for secondary stages in mining operations. Road construction and demolition projects represent the fastest-growing applications, a result of new infrastructure investments.
Engine emission standards, such as those from the US EPA and the European Union's CE marking requirements, dictate powertrain design. Worker safety regulations from bodies like OSHA in the United States influence machine guarding, noise reduction, and dust suppression features. Stakeholders must now evaluate the total cost of ownership between diesel, hybrid, and fully electric drive systems.
Market Dynamics
The global push towards a circular economy, codified in regulations like the EU Green Deal, is the central force shaping the market. This mandate compels the use of recycled aggregates in construction, directly driving demand for on-site crushing and screening capabilities.
Growth Catalysts
- Infrastructure Investment:Government-led infrastructure programs, particularly large-scale road and highway construction projects in India, require massive volumes of aggregates, creating sustained demand for high-capacity mobile crushing plants.
- Circular Economy Mandates:European Union policies promoting material circularity are accelerating the adoption of mobile screeners within the waste management sector to process construction and demolition waste into reusable materials.
- Recycling Sector Expansion:A broader industrial shift towards resource recovery is expanding the application of mobile crushers beyond traditional quarrying into scrap metal processing and industrial slag recycling.
Market Restraints
- High Capital Cost:The significant upfront investment required for hybrid and fully electric mobile crushers presents a substantial barrier for small to mid-sized contractors, slowing the transition away from diesel-powered equipment.
- Regulatory Fragmentation:Navigating disparate engine emission standards from the US EPA and differing CE marking requirements in the European Union complicates equipment design and increases compliance costs for manufacturers.
- Infrastructure Gaps:The lack of reliable charging infrastructure at remote quarrying and mining sites limits the practical deployment of fully electric crushers, which depend on a consistent power supply for operation.
Strategic Opportunities
- Service-Based Models:The integration of telematics and remote diagnostics creates opportunities for manufacturers to offer predictive maintenance and fleet management as a subscription service, generating recurring revenue.
- Urban Mining Applications:Developing specialized, compact mobile crushers for use in dense urban environments allows for the on-site recycling of demolition debris, a largely untapped application segment.
- Electrification of Ancillary Equipment:Expanding electric and hybrid powertrain technology from primary crushers to mobile screeners, stackers, and conveyors offers a path to providing fully electric processing trains.
Industry Challenges
- Skilled Operator Scarcity:A persistent shortage of technicians and operators qualified to manage and maintain equipment featuring advanced automation, telematics, and remote-control systems hinders productivity gains.
- Fleet Retrofitting Complexity:Upgrading existing diesel-powered fleets to comply with new occupational safety rules from bodies like OSHA regarding dust suppression and noise levels requires significant capital and downtime.
- Component Supply Chain Constraints:Securing a stable supply of high-power electric motors, battery packs, and advanced control systems poses a challenge for manufacturers scaling up production of next-generation equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Crushers and Screeners Market |
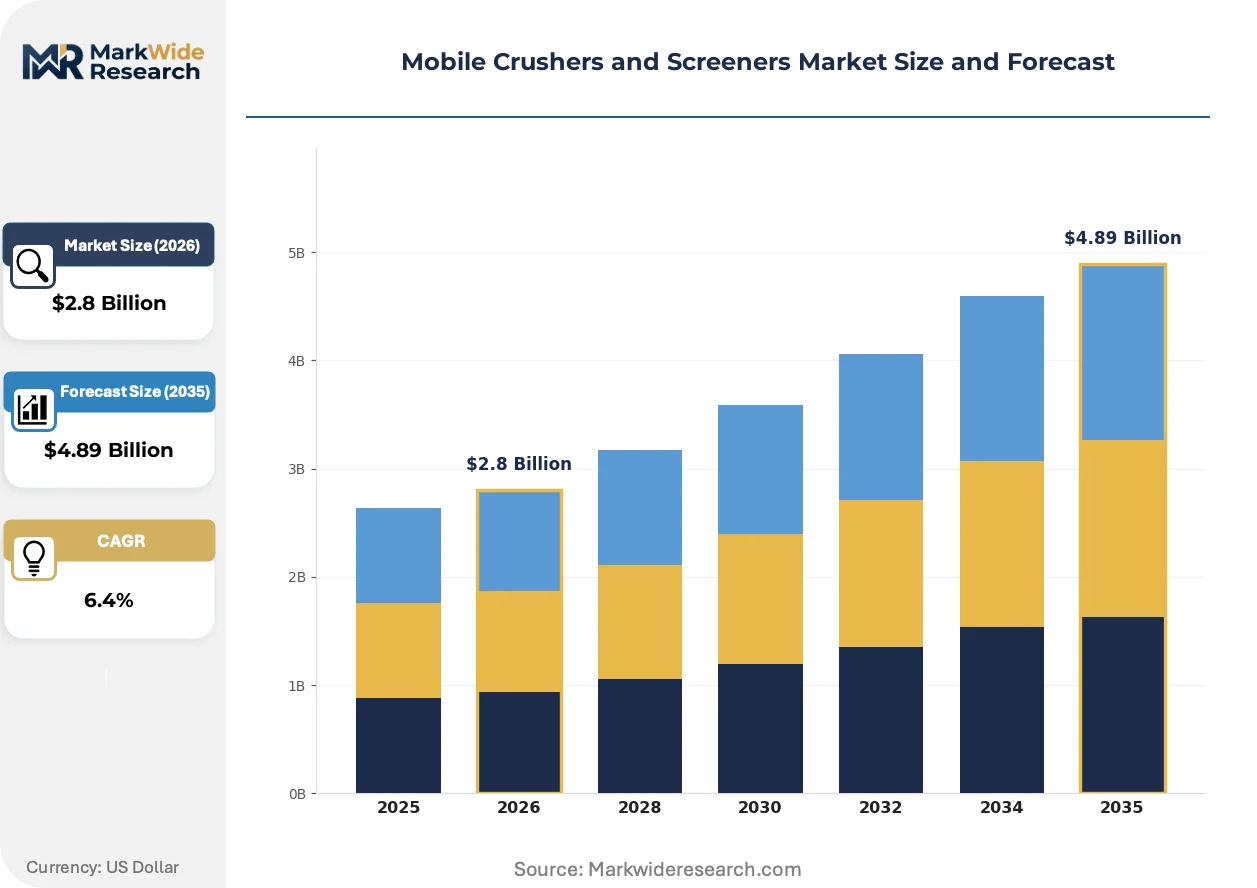
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jaw Crushers, Cone Crushers, Impact Crushers, Vibrating Screeners, Trommel Screeners Technology: Hydraulic System, Electric Drive, Diesel Engine, Remote Control, Automatic Monitoring Application: Mining Operations, Demolition Projects, Quarrying Sites, Road Construction, Waste Recycling End User: Contractors, Mining Corporations, Infrastructure Developers, Recycling Companies |
| Companies Covered | Metso Corporation, McCloskey International, Komatsu Ltd, Astec Industries Inc., RUBBLE MASTER HMH GmbH, Sandvik AB, Kleemann GmbH, SBM Mineral Processing GmbH, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Crushers and Screeners Market Strategic Shifts & Innovations
Electrification and digitalization are transforming mobile crushers from standalone capital assets into integrated components of a data-driven worksite. This evolution prioritizes operational efficiency, uptime, and total cost of ownership over the initial purchase price, altering competitive dynamics.
Technology or Product Evolution
On-board telematics and remote monitoring systems provide real-time data on fuel consumption, throughput, and equipment health. Large contractors and equipment rental companies are adopting this technology to optimize fleet utilization and schedule preventative maintenance. This capability is decentralizing operational oversight from the individual machine operator to a centralized, remote command center, enabling more effective fleet-wide management.
Regulatory or Policy Shift
European Union CE marking requirements, enforced through directives like the Machinery Directive, impose stringent standards for operational safety. These rules mandate advanced machine guarding, emergency stops, and integrated dust and noise suppression systems on all new equipment. Consequently, manufacturers targeting the EU market must engineer these features directly into the powertrain and chassis design, impacting production costs and development timelines.
Demand-Side or Behavioral Shift
Large-scale contractors are moving away from outright equipment purchases in favor of long-term leasing agreements that include comprehensive maintenance and service guarantees. This procurement model transfers the risk of downtime and maintenance to the equipment provider, with buyers prioritizing guaranteed operational availability. The trend is most visible in the highly developed construction and quarrying markets of North America and Western Europe.
Mobile Crushers and Screeners Market Segmentation
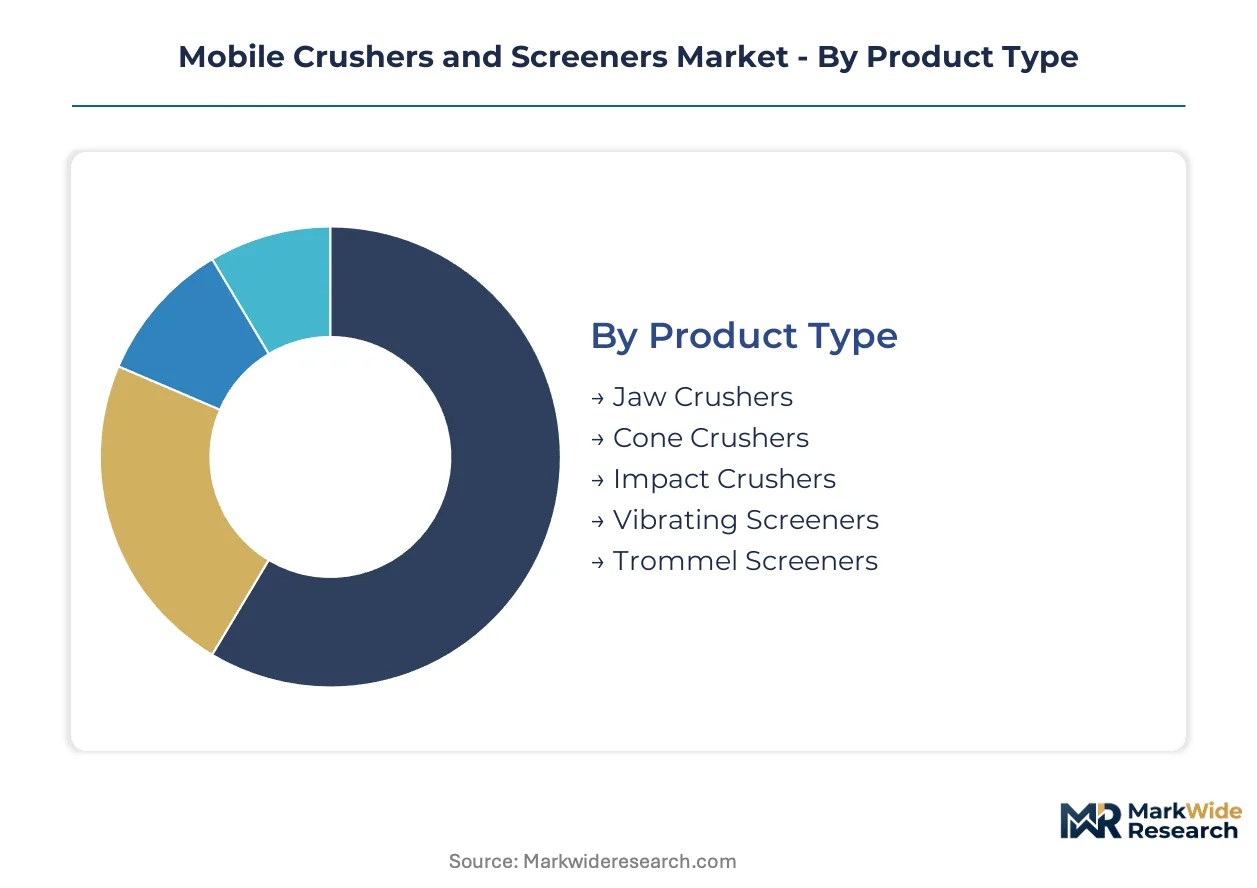
Understanding the distinct segments within the mobile crushers and screeners market illuminates the varied demands and operational priorities influencing equipment design and procurement. This segmentation provides clarity on where technological advancements and regulatory pressures are most acutely felt by manufacturers and end-users.
Product Type:
Equipment selection is primarily driven by the material characteristics and the desired final product size, dictating the crushing mechanism required.
- Jaw Crushers:These primary crushers feature two plates, one fixed and one movable, that compress material through a powerful force. Demand concentrates in quarrying operations across India for large-scale road construction projects.
- Cone Crushers:These secondary crushers employ a rotating crushing head within a concave mantle, providing excellent product shape and consistent output. Mining operations in Australia increasingly deploy these for fine aggregate production.
- Impact Crushers:These machines use high-speed rotors to break material through impact, suitable for processing softer aggregates and recycling applications.
- Vibrating Screeners:These units separate materials by size using vibrating decks, essential for precise aggregate classification and quality control.
- Trommel Screeners:Rotating cylindrical screens classify materials effectively, particularly for processing construction and demolition waste and topsoil.
Volume sits with Jaw Crushers; growth tilts toward Cone Crushers.
Technology:
Investment decisions in technology hinge on balancing operational efficiency, environmental compliance, and the total cost of ownership over the equipment's lifespan.
- Electric Drive:These powertrains use electric motors for propulsion and crushing functions, significantly reducing local emissions and noise. Adoption is accelerating in Europe due to stringent EU Green Deal mandates for cleaner operations.
- Diesel Engine:These conventional powertrains rely on internal combustion for power, offering robust performance and independence from grid infrastructure in remote locations. Their adoption remains strong in emerging markets lacking reliable charging infrastructure.
- Hydraulic System:This technology powers crushing mechanisms and track movements, offering precise control and high force for heavy-duty applications.
- Remote Control:This feature allows operators to manage equipment from a safe distance, improving worksite safety and enhancing operational flexibility.
- Automatic Monitoring:These systems collect real-time performance data on fuel consumption and throughput, enabling predictive maintenance and operational optimization.
Efficiency gains are concentrated in Electric Drive, while Diesel Engine offers immediate operational flexibility.
Application:
The specific project requirements and material sources dictate the type and scale of mobile crushing and screening equipment deployed.
- Road Construction:This segment involves crushing and screening aggregates for new highway and road infrastructure, demanding high-capacity and reliable plants. New infrastructure investments globally, particularly in India, drive significant demand.
- Waste Recycling:This application processes construction and demolition waste into reusable aggregates, supporting circular economy initiatives. European Union policies promoting material circularity are accelerating equipment adoption in this area.
- Mining Operations:This use case involves reducing ore size for further processing, requiring durable and high-capacity crushers capable of handling abrasive materials.
- Demolition Projects:These projects utilize mobile crushers for on-site processing of concrete and masonry debris, minimizing transport costs and environmental impact.
- Quarrying Sites:This traditional application extracts and processes virgin aggregates from rock formations, requiring robust primary and secondary crushing solutions.
Traditional demand stems from Quarrying Sites, but Waste Recycling is expanding rapidly.
End User:
Procurement strategies and service expectations vary significantly among different end-user groups, influencing market offerings.
- Contractors:These firms operate mobile crushers for various projects, often preferring long-term leasing agreements that include comprehensive maintenance. Large contractors in North America are shifting procurement towards service-based models.
- Recycling Companies:These businesses process waste materials into new products, utilizing mobile screeners for construction and demolition waste. EU mandates for recycled aggregates are expanding their operational scope.
- Mining Corporations:These large entities deploy extensive fleets for ore extraction and processing, prioritizing throughput capacity and equipment reliability.
- Infrastructure Developers:These organizations manage large-scale construction projects, frequently subcontracting crushing and screening tasks to specialized providers.
Operational scale defines the needs of Mining Corporations, whereas Recycling Companies focus on specialized processing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global market exhibits a production-consumption divide, with significant demand centers for mobile crushers and screeners emerging in developing economies while advanced manufacturing capabilities reside in established industrial nations. Infrastructure investments and circular economy initiatives drive regional equipment adoption. Regulatory frameworks and resource availability influence technological preferences across different geographies.
India
Massive government-led infrastructure programs, particularly for road and highway construction, create substantial demand for high-capacity mobile crushing plants. The country's national infrastructure policy supports these large-scale projects, requiring significant aggregate volumes. Cities like Mumbai and Delhi experience high demand for crushing and screening equipment to support urban development.
Germany
Stringent EU Green Deal mandates for circularity and reduced emissions accelerate the adoption of electric drive and hybrid mobile crushers. Germany's national waste management regulations prioritize recycling construction and demolition waste, driving equipment usage. The Rhine-Ruhr region, with its extensive industrial base, sees continuous demand for advanced mobile processing solutions.
Australia
Mining operations, especially for iron ore and coal, require durable and high-capacity cone crushers for efficient material reduction. The country's robust mining safety standards influence machine guarding and dust suppression features in equipment design. Western Australia, a major mining hub, consistently procures advanced crushing and screening technology.
United States
New infrastructure investments and the need for on-site recycling of demolition debris create consistent demand for mobile crushing and screening equipment. US EPA emission standards dictate powertrain design, pushing manufacturers towards cleaner engine technologies. Major metropolitan areas like New York and Los Angeles utilize compact mobile units for urban demolition projects.
China
Extensive road and railway construction projects generate significant demand for mobile crushers and screeners to produce aggregates. The country's dual carbon goals and MEE regulations are increasingly influencing the adoption of more energy-efficient and lower-emission equipment. The Yangtze River Delta region, a major manufacturing and construction center, drives substantial equipment procurement.
Mobile Crushers and Screeners Market Key Industry Players
The competitive structure tilts toward specialized manufacturers offering integrated solutions that combine equipment with advanced services. The market features a tiered landscape, with global conglomerates providing comprehensive portfolios alongside regional specialists focusing on niche applications. Companies pursue competitive differentiation through technological innovation, particularly in automation and electrification, and by expanding service networks.
Within the premium equipment segment, Metso Corporation and Sandvik AB exemplify manufacturers leveraging extensive service networks and advanced automation to offer integrated packages. McCloskey International, known for its robust and high-throughput machinery, anchors the market for specialized equipment in quarrying and recycling. These companies represent key archetypes in a market increasingly focused on total cost of ownership and operational efficiency.
| Leading Market Players |
|---|
| Metso Corporation |
| McCloskey International |
| Komatsu Ltd |
| Astec Industries Inc. |
| RUBBLE MASTER HMH GmbH |
| Sandvik AB |
| Kleemann GmbH |
| SBM Mineral Processing GmbH |
| Terex Corporation |
| Others |
Cost & Logistics Intelligence
Energy costs, particularly for diesel fuel and electricity, influence operational expenses for mobile crushers, directly impacting pricing for contractors evaluating total cost of ownership across different drive systems. This upstream cost component traces through the equipment's operational efficiency to affect downstream service and leasing package pricing.
Pricing Analysis
Cost-down pressure on mobile crushing equipment accelerates because contractors increasingly evaluate total cost of ownership over initial purchase price. Procurement often shifts towards long-term leasing agreements, bundling equipment with comprehensive maintenance and telematics services. Price differentiation stems from advanced automation, electrification, and guaranteed operational uptime, moving beyond basic machine cost. This pressure is most acutely felt by small to mid-sized contractors, who prioritize upfront capital expenditure, while large contractors prioritize long-term operational efficiency and service packages.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of high-power electric motors and advanced control systems, primarily located in China and Germany. The supply chain for mobile crushers depends heavily on critical components sourced from manufacturing hubs in Germany, Japan, and China. Key dependencies include battery packs for electric models and sophisticated hydraulic systems for heavy-duty applications. Component supply chain constraints pose a structural risk, impacting production timelines and equipment availability for manufacturers. Distribution typically runs through established regional dealer networks and direct sales channels to large contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mobile crushers and screeners market is increasingly defined by the cost of regulatory compliance. EU Green Deal mandates for circularity and emissions create a significant barrier-to-entry moat for manufacturers able to meet these standards.
For Market Incumbents:Lock in long-term service contracts and telematics subscriptions with large contractors to secure recurring revenue streams. Invest in R&D for hybrid and electric powertrains to preempt regulatory shifts and counter emerging competition from specialized electric equipment providers. The shift towards total cost of ownership models and stringent emission standards threatens traditional diesel-centric sales. Vertical integration into advanced component manufacturing or strategic partnerships can mitigate supply chain risks for critical electric components.
For New Entrants and Emerging Players:The EU Green Deal in Europe opens a window for specialized manufacturers of compact, fully electric mobile crushers designed for urban mining applications. Focus on developing modular, easily deployable electric units for demolition projects in dense urban environments, a largely untapped application segment. Urban demolition and small-scale recycling operations represent the most penetrable segments. Offer flexible rental and lease-to-own models that include comprehensive charging solutions and maintenance.
For Investors and Strategic Acquirers:The widespread adoption of electric ancillary equipment at quarrying sites is the leading indicator that full electrification of mobile processing trains is viable. The market demonstrates strong long-term viability driven by global infrastructure investments and circular economy mandates over the next decade. Seek out specialized mid-cap manufacturers with proven expertise in battery technology integration, advanced telematics, or compact urban recycling equipment. Monitor the expansion of reliable charging infrastructure at remote construction and mining sites as a key inflection point.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increase production capabilities for hybrid and electric models to meet evolving regulatory compliance. |
| Green Manufacturing Transition | Implement sustainable production processes to align with global environmental mandates and reduce operational footprint. |
| Long-term Supply Agreement | Secure critical components like battery packs and electric motors to stabilize production and mitigate supply chain risks. |
| Acquisition of Specialist Firm | Acquire companies with expertise in telematics or urban mining equipment to enhance integrated offerings. |
| Software-Defined Machine Investment | Develop advanced control software for remote operation and predictive maintenance, improving operational efficiency. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing foundational market insights. This analysis combined insights from extensive primary interviews with detailed secondary research. Primary data involved conversations with equipment manufacturers' R&D directors, large contractor procurement leads, recycling company operations managers, and infrastructure developer project managers. Secondary sources included US EPA reports, EU Green Deal policy documents, national infrastructure project databases, and industry white papers. Bottom-up and top-down triangulation validated market size and growth projections.
Market volume and value were modeled at a granular level across product type, technology, application, end-user, and key country segments. The analytical framework integrated historical data with future growth drivers over the projection horizon. Compound annual growth rates were derived by assessing demand-side shifts and supply-side capacity expansions. Key forecast inputs included infrastructure investment budgets and the pace of circular economy policy implementation across major geographies.
The model assumes a particular technology adoption path for electrification; alternative pathways for hydrogen fuel cell integration would alter the outlook significantly. Forecasts reflect assumptions regarding global economic stability and consistent regulatory enforcement. Geopolitical events or unforeseen supply chain disruptions represent specific risk factors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Compact Power Equipment Rental Market
Construction Equipment
Global Light Towers Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Derinding Machines Market
Construction Equipment
Hydraulic Press Machine Market
Construction Equipment
Indonesia Construction Equipment Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Europe Stud Welding Machine Market
Construction Equipment
Separation Machinery Market
Construction Equipment
Construction Equipment Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Portable Chamfering Machines Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
Cementing Accessories Market