
 Low-E Construction Glass Market | 2026-2036
Low-E Construction Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Low-E Construction Glass Market Intelligence
China is reconfiguring regional supply dynamics through expanded float glass and coating capacity additions. Saint-Gobain leverages integrated manufacturing platforms across multiple continents to sustain cost advantages in solar control coatings. AGC Inc. anchors its position through deep R&D investment in sputtered low-emissivity layer technologies. Guardian Glass competes via captive raw material access and vertical control over silica sourcing.
Low-E construction glass incorporates microscopic metallic oxide coatings—typically silver-based layers between 10 and 20 nanometers thick—deposited through magnetron sputtering onto float glass substrates to reduce thermal emissivity below 0.15 while maintaining visible light transmission above 70 percent. Triple glazed products command premium positioning as net-zero building standards tighten across temperate climates. Solar control technology leads volume deployment in commercial facade design, where architects balance daylight harvesting with cooling load reduction. Double glazed configurations occupy the broadest addressable base in residential renovation projects where retrofit compatibility constrains installation depth.
EPA Energy Star certification and the EU Green Deal building renovation requirements shape product specifications and market access thresholds across their respective jurisdictions. China's GB standards for building energy efficiency, administered by SAMR, mandate low-E glazing in new public construction above specified floor areas. Stakeholders must monitor evolving code harmonization between national energy performance frameworks and local enforcement capacity as retrofit mandates expand.
Market Dynamics
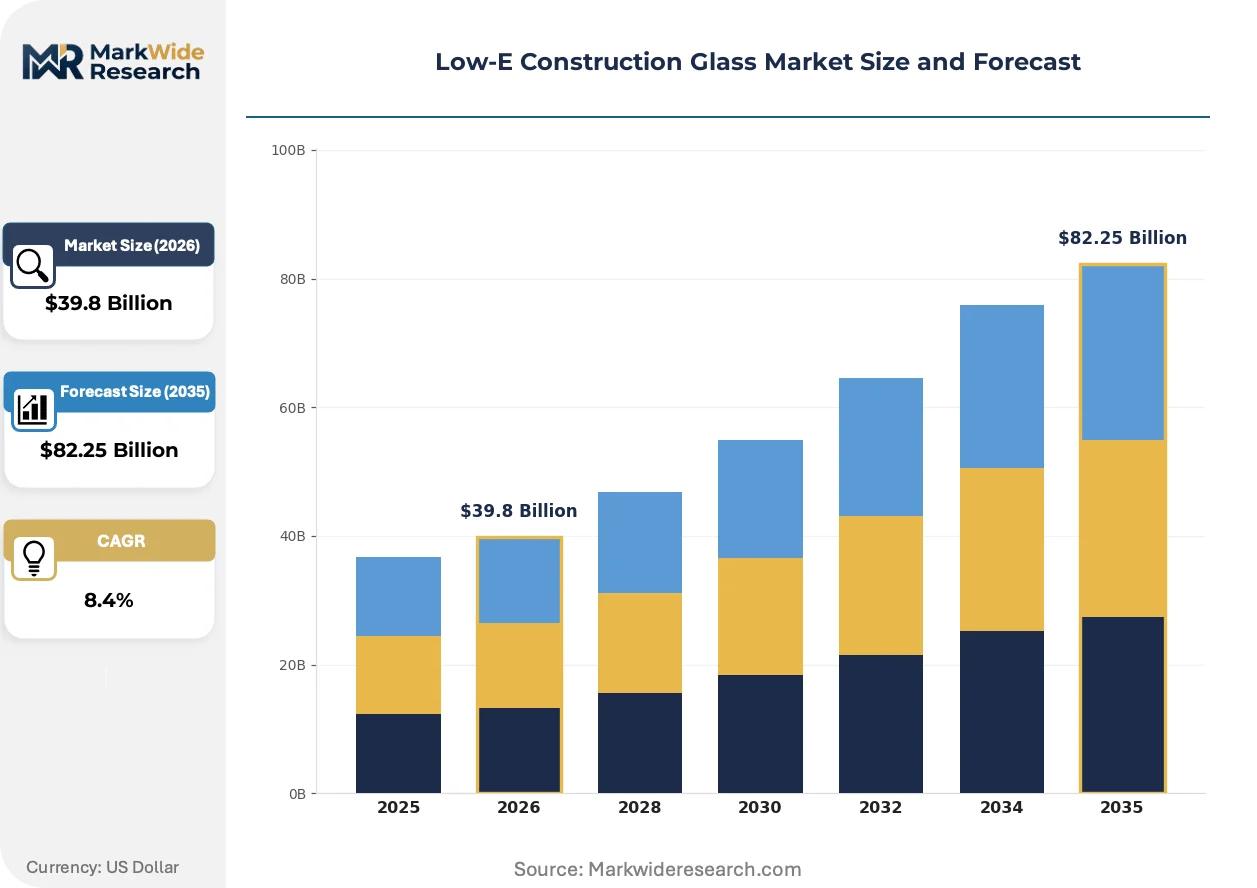
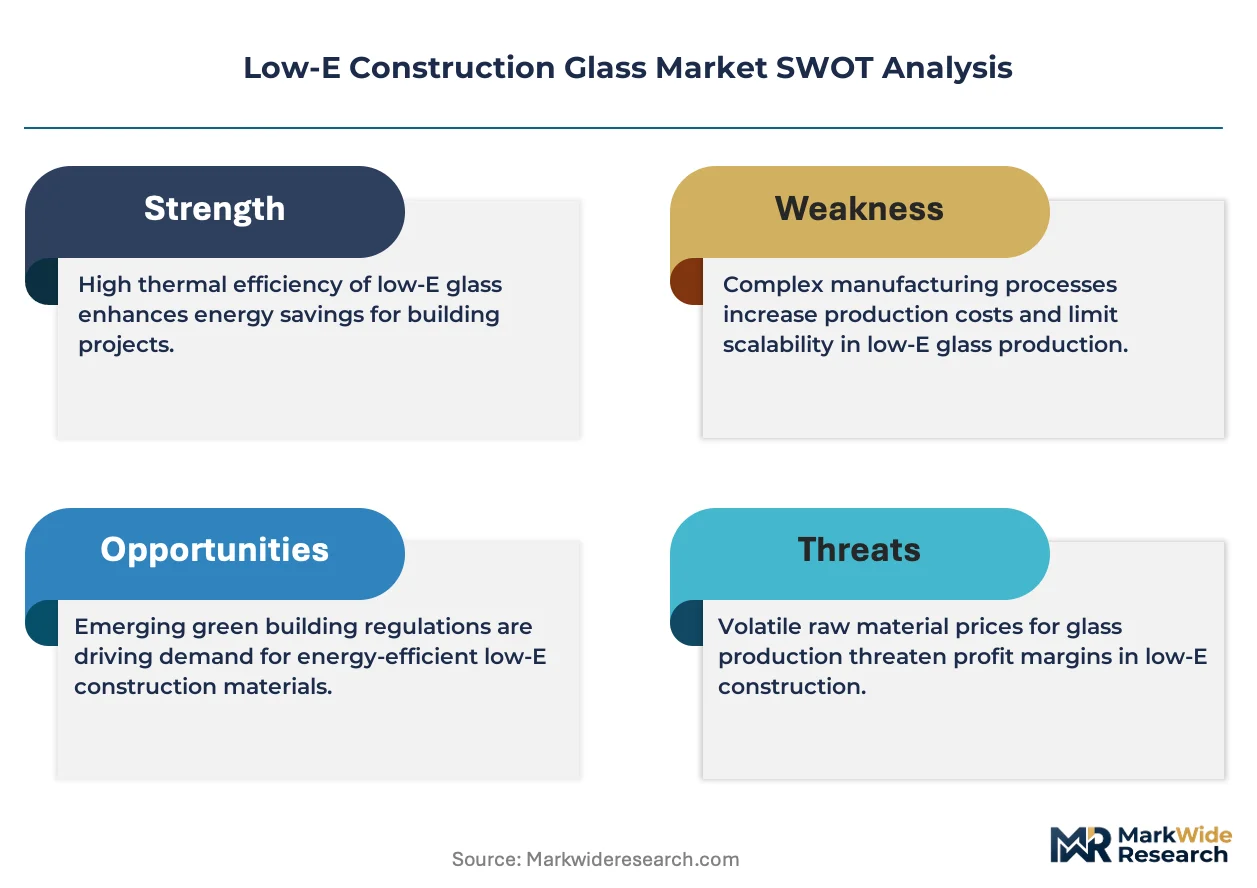
Building energy codes in China, the EU, and the US are compressing thermal performance thresholds faster than coating technology costs can decline, forcing manufacturers to absorb margin pressure while scaling capacity for triple-glazed and dynamic glazing systems.
Growth Catalysts
- China's GB Standards:SAMR mandates low-E glazing in new public construction above specified floor areas, pulling volume through state-backed urban retrofit programs and green building certification schemes.
- EU Green Deal Renovation Wave:The building renovation requirements are retrofitting millions of square meters of commercial and residential facade stock across Germany, France, and Poland.
- Magnetron Sputtering Advances:Thinner silver-based coatings below 15 nanometers are maintaining emissivity targets while reducing precious metal load and coating cycle time.
Market Restraints
- Silver Price Volatility:The silver-based metallic oxide layers expose coating operations to London Bullion Market Association spot price swings that compress gross margins unpredictably.
- Float Glass Supply Concentration:China controls over half of global flat glass melting capacity, creating geographic dependency risk for coating plants in Southeast Asia and Europe.
- Installation Depth Constraints:Retrofit compatibility limits residential renovation to double-glazed configurations, blocking premium triple-glazed penetration in the largest addressable segment.
Strategic Opportunities
- India's Underpenetrated Market:BIS energy efficiency codes are tightening for commercial high-rises in Mumbai, Bangalore, and Delhi NCR where low-E penetration remains below 15 percent.
- Dynamic Glazing Convergence:Electrochromic and thermochromic technologies are integrating with sputtered low-E substrates to enable responsive solar control in net-zero commercial towers.
- Direct Contractor Channels:Large glazing contractors in Texas, Florida, and California are bypassing traditional distribution to source coated glass directly from manufacturers for multi-family residential projects.
Industry Challenges
- Magnetron Sputtering Technician Shortage:The specialized vacuum deposition skill set required for uniform nanometer-scale coating application faces limited vocational training pipeline capacity.
- EPA Energy Star Certification Timelines:The verification and labeling process for thermal performance claims creates 8-14 month product launch delays that mismatch construction bidding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-E Construction Glass Market |
| Market Size in 2026 | $39.8 Billion |
| Market Size in 2035 | $82.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double Glazed, Triple Glazed, Laminated, Tempered Application: Commercial Buildings, Residential Buildings, Renovation Projects, Facade Design Technology: Solar Control, Low-Emissivity, Insulated, Energy Efficient End User: Architects, Contractors, Homeowners, Builders |
| Companies Covered | Taiwan Glass Ind. Corp., Saint-Gobain, AGC Inc., PPG Industries, Inc., Guardian Glass, Central Glass Co., Ltd., Nippon Sheet Glass Co., Ltd., Xinyi Glass Holdings Limited, CSG Holding Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-E Construction Glass Market Strategic Shifts & Innovations
Digital process control and spectroscopic inline monitoring are compressing coating variance and enabling mass customization of emissivity specifications at production speed.
Advanced process control software is digitizing magnetron sputtering operations through real-time plasma emission monitoring and automated cathode power adjustment. Coating plants in Ohio, Bavaria, and Jiangsu are retrofitting legacy lines with these systems to reduce silver waste and thickness variation. The digitization is compressing quality control labor costs while enabling single-run production of multiple emissivity grades without line changeover delays.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in insulating glass unit manufacturing, forcing spacer bar and sealant suppliers to reformulate with thermoplastic or silicone alternatives. German and Austrian IGU fabricators are retooling warm-edge spacer production lines to eliminate butyl-based primary seals. Commercial facade projects in Paris, Milan, and Stockholm now specify F-Gas-compliant assembly methods in tender documents, disqualifying legacy supply chains.
Architects and developers are unbundling glazing specification from general contractor procurement, engaging facade consultants directly for thermal modeling and coating selection. This disintermediation concentrates buying power with specialized envelope engineering firms in London, Singapore, and Sydney that specify performance criteria rather than manufacturer brands. The shift compresses distributor margins while rewarding coating plants with in-house technical service capabilities and WUFI or THERM simulation support.
Low-E Construction Glass Market Segmentation
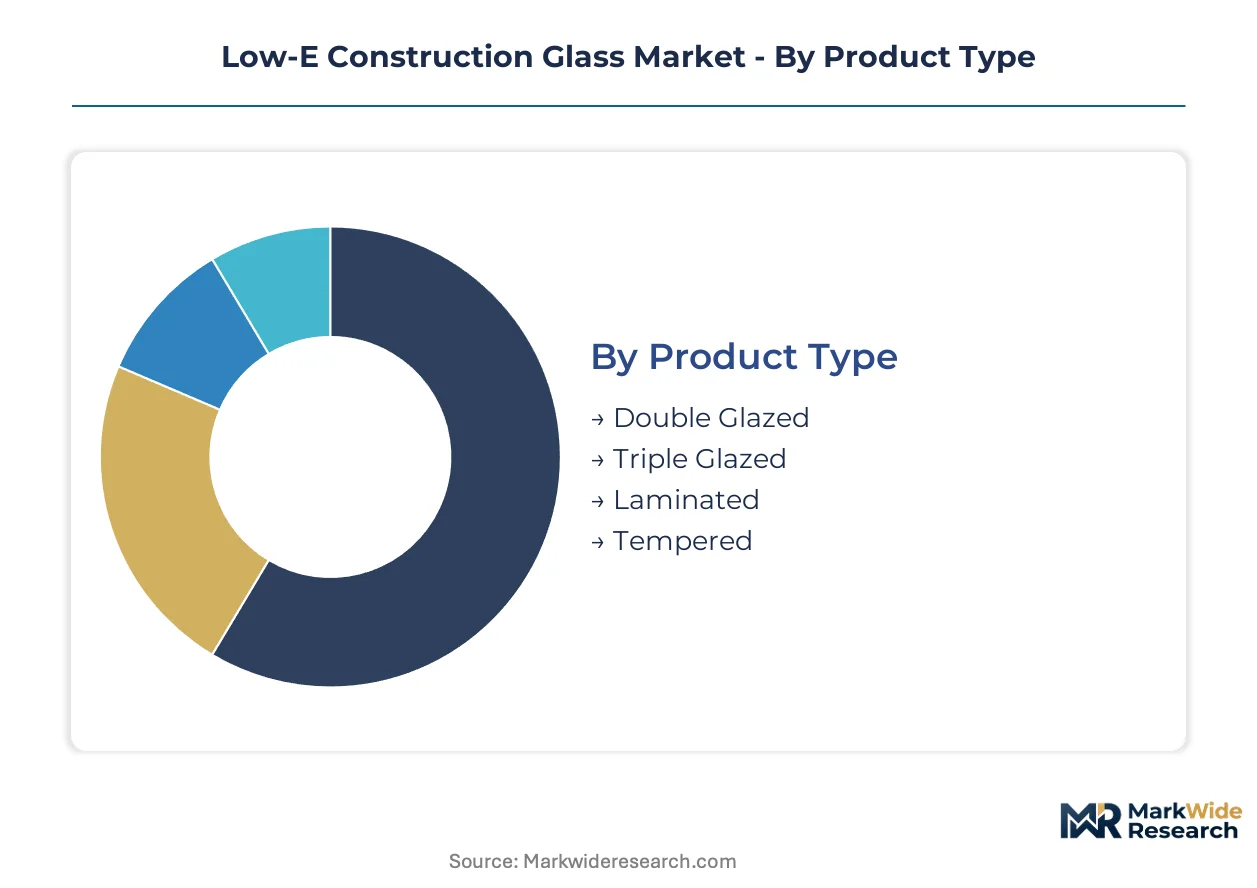
Low-E construction glass demand fragments across thermal performance tiers, installation contexts, and professional procurement channels. Each segmentation dimension reveals distinct margin structures and technical specification requirements that shape manufacturer portfolio strategy.
Product Type:
Cost tier differentiation separates retrofit-accessible configurations from premium thermal performance systems.
- Double Glazed:Two glass lites with a single low-E coated surface and air or argon-filled cavity. Residential renovation in Germany, France, and Poland absorbs volume as EU Green Deal renovation mandates compress payback thresholds for thermal upgrades.
- Triple Glazed:Three glass lites with multiple low-E surfaces and dual cavities, achieving U-values below 0.8 W/m²K. Net-zero commercial towers in Stockholm, Copenhagen, and Vancouver specify these units where thermal bridging constraints are minimal.
- Laminated:Polyvinyl butyral interlayers bond glass plies for acoustic dampening and post-breakage retention. High-rise residential in Mumbai and Singapore deploys laminated low-E combinations for safety-critical facade applications.
- Tempered:Thermal or chemical strengthening creates fourfold mechanical resistance. Spandrel panels and point-fixed glazing systems in commercial atriums require tempered substrates to meet ASTM E1300 load requirements.
Double glazed commands the established base. The steepest expansion runs through triple glazed.
Application:
Volume concentration varies by construction cycle phase and regulatory enforcement intensity.
- Commercial Buildings:Curtain wall and storefront systems specifying solar control low-E for cooling load management. Class A office construction in Texas, Florida, and California drives specification through direct contractor channels.
- Residential Buildings:New single-family and multi-family construction integrating low-E as code-mandated baseline. China's GB standards enforcement in public housing above specified floor areas pulls volume through state-backed programs.
- Renovation Projects:Existing stock retrofit constrained by installation depth and frame compatibility. Double-glazed units dominate as sash replacement limits cavity expansion in pre-1990 building stock across Germany and Poland.
- Facade Design:Architect-led specification unbundled from general contractor procurement. Envelope engineering firms in London, Singapore, and Sydney concentrate buying power through performance-based tendering.
Commercial buildings anchor current volume. Renovation projects are climbing the fastest as retrofit mandates widen.
Technology:
Coating functionality determines thermal emissivity targets and solar heat gain coefficients.
- Solar Control:Spectrally selective coatings reflecting near-infrared while transmitting visible light. Commercial facade design in temperate climates balances daylight harvesting with mechanical cooling reduction.
- Low-Emissivity:Silver-based sputtered layers reducing thermal emissivity below 0.15. Magnetron sputtering advances below 15 nanometers are compressing precious metal load while maintaining performance.
- Insulated:Gas-filled cavities and warm-edge spacers reducing conductive heat transfer. EU F-Gas Regulation compliance is forcing butyl-based primary seal reformulation across German and Austrian IGU fabricators.
- Energy Efficient:Integrated systems combining low-E coatings, inert gas fill, and thermally broken framing. EPA Energy Star certification timelines create 8-14 month product launch delays that mismatch construction bidding cycles.
Low-emissivity coatings command the established base. Solar control is gaining share fastest in commercial specification.
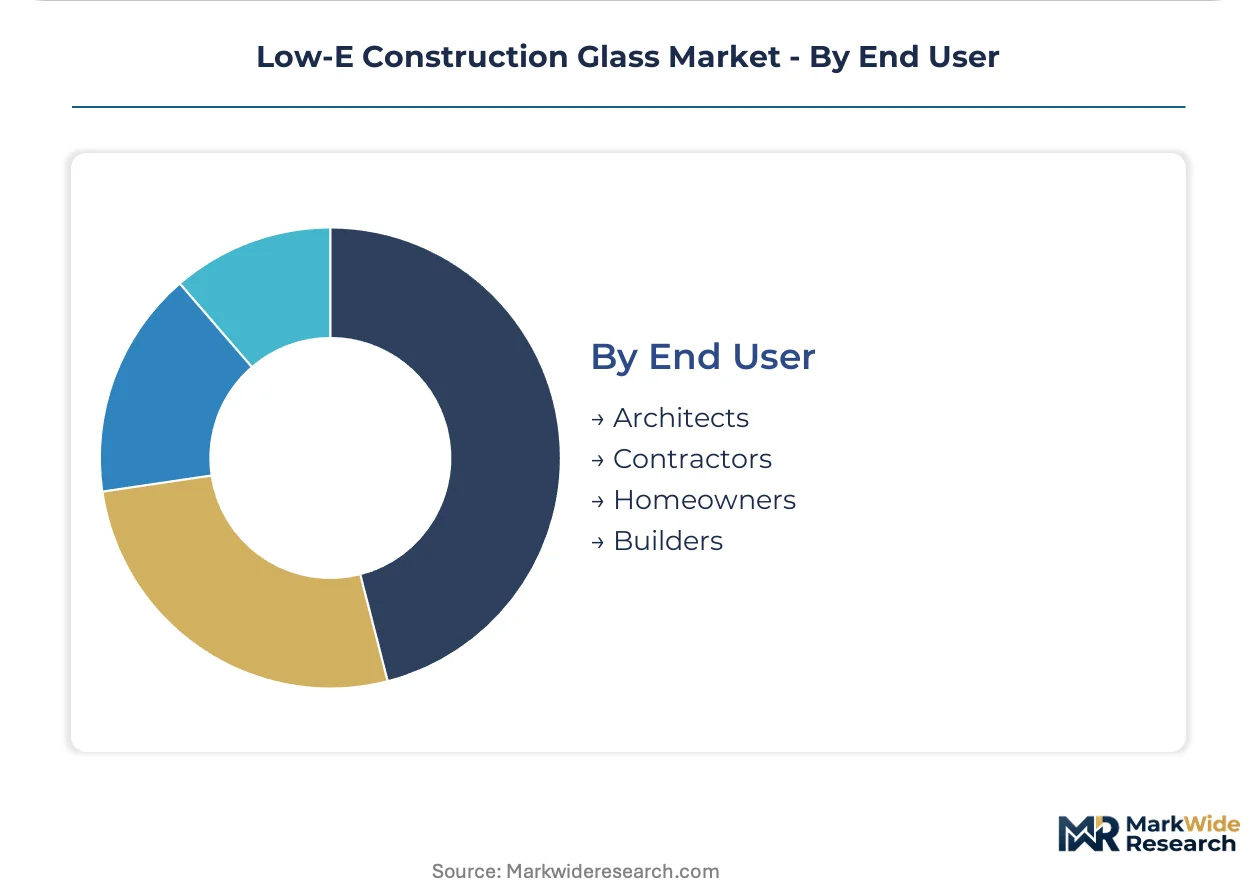
End User:
Procurement authority concentrates with technical decision-makers rather than price-sensitive owners.
- Architects:Design-phase specification of thermal performance criteria and coating selection. Facade consultants in Sydney and Singapore now specify performance metrics rather than manufacturer brands.
- Contractors:Execution-phase procurement with growing direct sourcing from coating plants. Large glazing contractors in Texas, Florida, and California bypass distribution for multi-family residential projects.
- Homeowners:Retrofit demand constrained by awareness gaps and upfront cost sensitivity. India's underpenetrated market shows below 15 percent low-E adoption despite BIS code tightening.
- Builders:Production home construction integrating low-E as standard specification. Volume procurement agreements with coating plants lock in emissivity grades across development portfolios.
Contractors command the established base. Architects are expanding influence fastest through performance-based specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands over half of global flat glass melting capacity, concentrating upstream supply while coating operations distribute across manufacturing clusters in Germany, the United States, and Southeast Asia. This geographic asymmetry shapes procurement risk profiles and investment patterns for low-E construction glass.
China
State-backed urban retrofit programs and green building certification schemes drive volume absorption. SAMR-administered GB standards mandate low-E glazing in new public construction above specified floor areas. Coating capacity expansions in Jiangsu province serve both domestic demand and export markets across Southeast Asia.
Germany
Commercial facade renovation and residential energy efficiency retrofits absorb significant volume. EU F-Gas Regulation compliance forces IGU fabricators in Bavaria to reformulate spacer bar and sealant systems. Warm-edge spacer production lines in Bavaria and Austria retool to eliminate butyl-based primary seals.
United States
Multi-family residential construction in Texas, Florida, and California pulls volume through direct contractor channels. EPA Energy Star certification timelines create product launch delays that mismatch construction bidding cycles. Coating plants in Ohio retrofit legacy lines with digital process control systems.
India
Commercial high-rise construction in Mumbai, Bangalore, and Delhi NCR drives specification despite low-E penetration remaining below 15 percent. BIS energy efficiency codes tighten for new construction. Fabrication capacity concentrates in Gujarat and Maharashtra to serve western and southern markets.
Japan
Seismic-resistant high-rise residential and commercial towers specify laminated low-E combinations for safety-critical applications. METI building energy standards drive thermal performance upgrades in Tokyo and Osaka. Nippon Sheet Glass anchors domestic coating capacity serving Kanto and Kansai regions.
Low-E Construction Glass Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in coating and substrate supply. The vendor base concentrates around integrated glass manufacturers with captive float capacity and independent coating specialists serving regional fabrication markets. Three archetypes dominate: vertically integrated multinationals with global float networks, regional coating specialists leveraging technical service capabilities, and emerging Asian producers scaling capacity for export markets. Competitive dynamics center on magnetron sputtering technology licensing and warm-edge spacer supply chain reconfiguration under EU F-Gas phase-down mandates.
Among Asia-Pacific-based producers, Taiwan Glass Ind. Corp. and Xinyi Glass Holdings Limited exemplify the scale-driven expansion archetype, while Saint-Gobain occupies a position representing integrated multinational platform strategy across multiple continents. These anchors illustrate how geographic origin and corporate structure shape competitive positioning within thermal performance tier differentiation.
| Leading Market Players |
|---|
| Taiwan Glass Ind. Corp. |
| Saint-Gobain |
| AGC Inc. |
| PPG Industries, Inc. |
| Guardian Glass |
| Central Glass Co., Ltd. |
| Nippon Sheet Glass Co., Ltd. |
| Xinyi Glass Holdings Limited |
| CSG Holding Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Jiangsu province's coating capacity expansions are compressing regional pricing power for European and North American fabricators. Float glass concentration in China creates asymmetric cost structures that downstream sputtering operations must absorb through efficiency gains or pass through to project developers.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across European markets, separating F-Gas-compliant warm-edge spacer assemblies from legacy butyl-based configurations. Pricing stratifies across triple-glazed premium systems, double-glazed standard units, and retrofit-constrained economy configurations. Cost compression in residential renovation tiers is intensifying because GB standards enforcement in Chinese public construction pulls volume toward state-backed procurement at negotiated rates. Homeowners in India's underpenetrated markets exhibit highest price sensitivity, while facade consultants in London and Sydney demonstrate lowest sensitivity due to performance-specification procurement authority.
Supply Chain Analysis
Independent coating specialists and integrated glass manufacturers hold magnetron sputtering capacity across Germany, the United States, and China. Silver bullion, argon gas, and float glass substrates anchor raw material dependencies. Supply chain risk centers on London Bullion Market Association spot price volatility for silver-based metallic oxide layers. Distribution runs through direct contractor channels in Texas, Florida, and California, bypassing traditional distributor networks for multi-family residential volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Low-E construction glass sits at an inflection where magnetron sputtering advances below 15 nanometers and EU F-Gas phase-down mandates are simultaneously reshaping cost structures and compliance requirements.
For Market Incumbents: Insulate margin position through captive float glass access and backward integration into silica sourcing. Saint-Gobain's integrated manufacturing platforms across multiple continents demonstrate how geographic diversification absorbs silver price volatility. Priority defensive moves include digital process control retrofitting to reduce coating variance and technical service capability expansion for facade consultant direct engagement. For New Entrants and Emerging Players: India's commercial high-rise markets in Mumbai, Bangalore, and Delhi NCR offer white-space expansion below 15 percent current penetration despite BIS code tightening. Dynamic glazing convergence with electrochromic and thermochromic technologies presents second entry vector for net-zero commercial tower specification. Go-to-market positioning should emphasize WUFI thermal simulation support and performance-based tendering alignment with envelope engineering firms. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because building energy codes across China, the EU, and the US are tightening thermal performance thresholds faster than technology costs can decline. Acquisition targets should display regional coating capacity with in-house magnetron sputtering technician training pipelines. Signal to monitor: EPA Energy Star certification timeline compression or acceleration as indicator of product launch velocity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetron Sputtering Line Digitalization | Ohio and Bavaria plants retrofit legacy equipment with real-time plasma emission monitoring to reduce silver waste. |
| Warm-Edge Spacer Retooling | German and Austrian IGU fabricators eliminate butyl-based primary seals to achieve EU F-Gas Regulation compliance. |
| Direct Contractor Channel Development | Large glazing contractors in Texas and California bypass distribution for multi-family residential project sourcing. |
| Facade Consultant Technical Service Expansion | Coating plants build WUFI and THERM simulation capabilities to align with Sydney and London specification authority. |
| Silver Load Reduction R&D | Thinner coatings below 15 nanometers maintain emissivity targets while compressing precious metal exposure to LBMA volatility. |
Research Approach
A spread of perspectives from magnetron sputtering plant managers, facade engineering consultants, glazing contractor procurement leads, and building code enforcement officers converged on the working assumptions. Primary fieldwork combined with secondary validation from SAMR GB standards documentation, EU F-Gas Regulation filings, EPA Energy Star certification databases, and customs trade data for float glass and silver bullion flows. Bottom-up project pipeline analysis and top-down construction spend triangulation anchored volume estimates.
Demand-supply balance modeling across the projection horizon integrated coating capacity utilization rates, retrofit mandate enforcement timelines, and green building certification scheme adoption curves. Segmentation dimensions included glazing configuration tier, application context, coating technology functionality, and procurement channel authority. CAGRs derived from regression against historical construction cycle patterns and regulatory compression trajectories. Key forecast inputs incorporated silver price volatility scenarios and magnetron sputtering technician pipeline constraints.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by emerging Asian producers or rapid electrochromic technology cost declines would shift outcomes. Specific risk factors include SAMR enforcement variability across Chinese provincial jurisdictions and F-Gas Regulation phase-down acceleration. Quarterly review of coating plant utilization rates, facade consultant specification trends, and BIS code adoption in Indian metropolitan markets is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Foam Bricks Market
Building Materials
Roofing and Insulation Market
Building Materials
HDG Steel Pipe Market
Building Materials
Asia-Pacific Facade Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Aluminum Door and Window Market
Building Materials
Timber Frames Market
Building Materials
Building and Construction Plastics Market
Building Materials
Rubbing Bricks Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Fly Ash Bricks Market
Building Materials
Concrete Market
Building Materials
Cement Tiles Market
Building Materials
Bio-Based Structural Wood Adhesives for Modular Construction Market
Building Materials
Global White Cement Market
Building Materials
China Cement Market