
 Shield Machines Market | 2026-2036
Shield Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Shield Machines Market Analysis
Municipal transit authorities are bifurcating from traditional road agencies as the dominant procurement class for shield machines. Herrenknecht AG dominates European urban tunneling with deep specialization in slurry shield technology. China Railway Construction Heavy Industry anchors domestic supply through in-house production of earth pressure balance systems for subway megaprojects. Komatsu Ltd leverages its construction equipment distribution network to compete in Southeast Asian infrastructure tenders.
A shield machine is a mechanized tunnel excavation system comprising a rotating cutterhead, thrust cylinders, and segment erection equipment designed to install precast concrete lining rings while simultaneously controlling ground pressure and groundwater ingress. Earth pressure balance machines lead volume in soft-ground urban applications where settlement control proves critical, while hard rock tunnel boring machines command premium margins in mountainous hydroelectric and mining access tunnels. Hybrid drive systems represent the fastest-growing technology segment as contractors demand operational flexibility across variable geology without machine replacement.
The EU Machinery Directive and CE marking requirements enforce rigorous safety protocols for cutterhead access, emergency shutdown systems, and operator visibility standards that elevate engineering costs for European deployments. China's GB standards and MIIT technical regulations mandate domestic content ratios and localization thresholds that shape procurement eligibility for foreign manufacturers. Stakeholders must monitor how evolving carbon accounting rules under the EU Green Deal and China's dual carbon goals will reshape energy efficiency benchmarks and steel sourcing requirements for new machine orders.
Market Dynamics
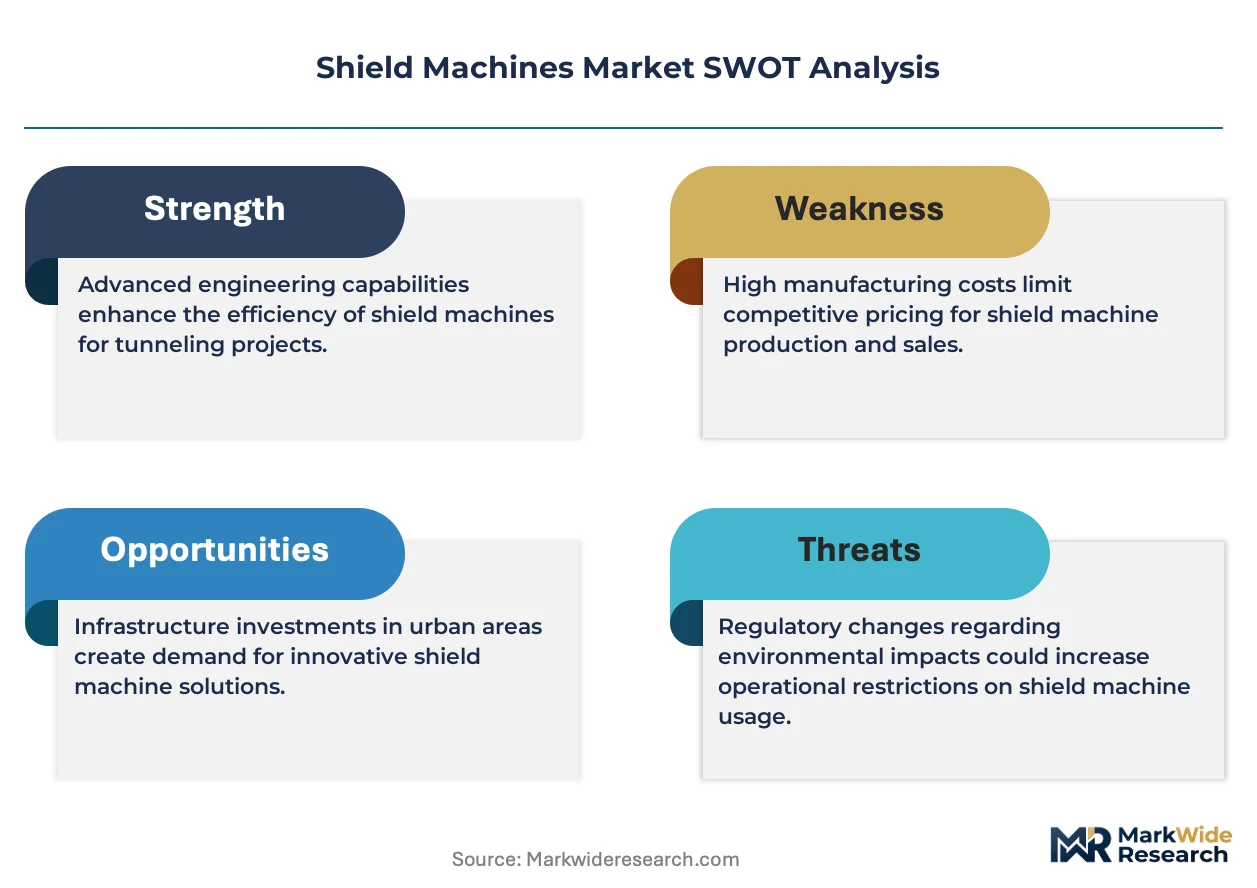
The EU Machinery Directive's cutterhead safety mandates and China's MIIT localization thresholds are bifurcating certification pathways, forcing manufacturers to maintain dual engineering tracks for European and Chinese deployments.
Growth Catalysts
- Urban subway expansion:Asian megacity transit authorities are procuring earth pressure balance systems for soft-ground corridors beneath dense metropolitan cores.
- EU Green Deal carbon accounting:Energy efficiency benchmarks for steel sourcing and hydraulic power systems are accelerating demand for electrified drive configurations.
- Hybrid drive adoption:Contractors operating across variable geology are specifying convertible machines that switch between EPB and slurry modes without site replacement.
Market Restraints
- Specialized steel alloy volatility:Cutterhead ring forgings require high-manganese wear-resistant grades subject to mining supply concentration in select jurisdictions.
- CE marking compliance costs:The EU Machinery Directive's emergency shutdown and visibility standards add engineering overhead that compresses margins on European tenders.
- Slurry shield technical limitations:Bentonite conditioning systems face groundwater pressure constraints in deep subaqueous tunnels exceeding specific hydrostatic thresholds.
Strategic Opportunities
- Southeast Asian infrastructure gaps:Vietnam and Indonesia lack domestic production capacity, creating import windows for established manufacturers with regional service networks.
- Retrofit and rebuild services:Extending machine lifecycles through cutterhead refurbishment and control system upgrades offers recurring revenue as installed base ages.
- MIIT localization incentives:Joint ventures with Chinese state-owned equipment groups satisfy domestic content ratios for subway megaproject eligibility.
Industry Challenges
- Tunneling engineer scarcity:Specialized operators capable of managing face pressure and settlement monitoring in real-time command premium wages across contracting firms.
- Extended type-approval timelines:CE marking and GB standard certification cycles delay revenue recognition by quarters for new machine configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shield Machines Market |
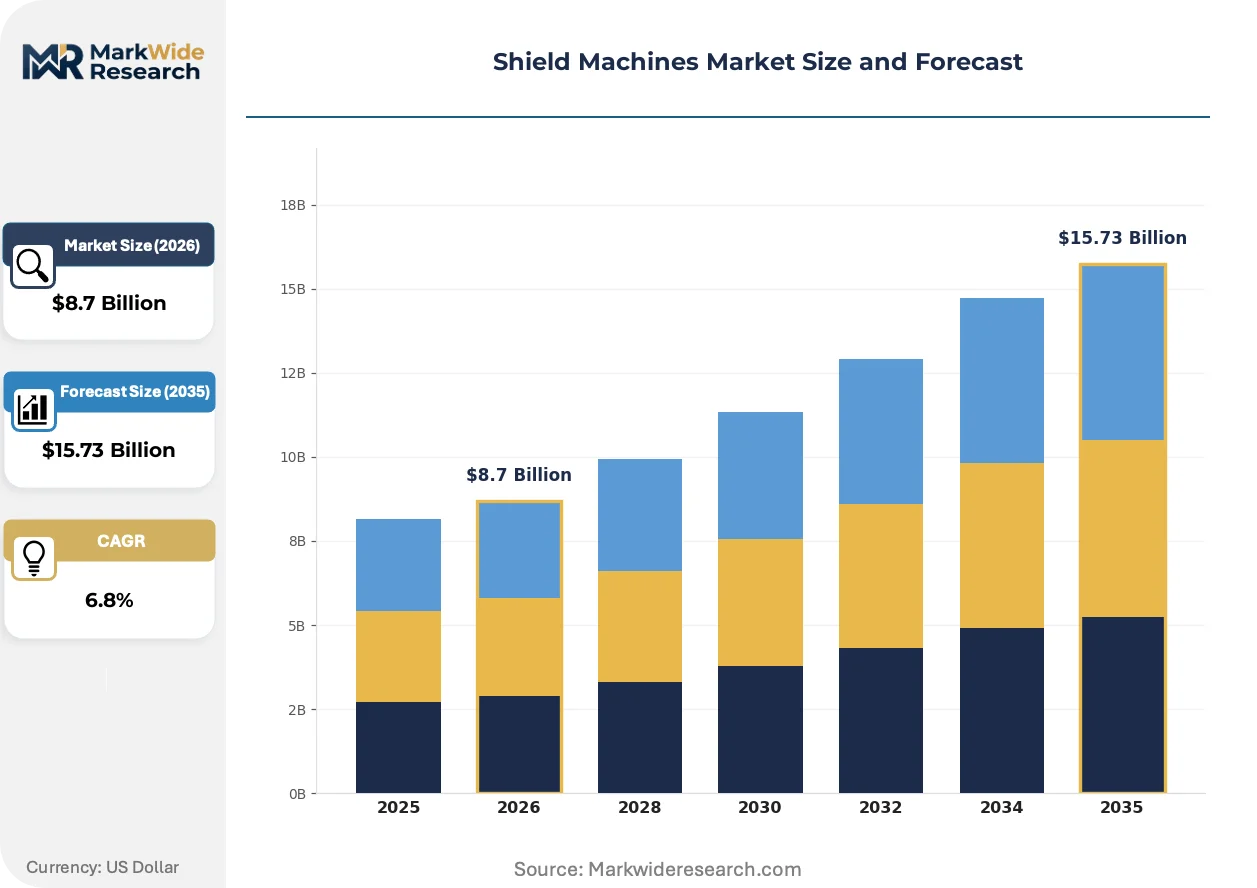
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Earth Pressure Balance Machines, Slurry Shield Machines, Hard Rock Tunnel Boring Machines, Mixed Shield Machines End User: Transportation, Water Supply, Wastewater Treatment, Utility Tunneling Application: Subway Construction, Road Tunneling, Dam Projects, Pipeline Installation Technology: Automated Monitoring Systems, Hybrid Drive Systems, Real-time Processing Technology, Advanced Cutting Techniques |
| Companies Covered | Komatsu Ltd, Hitachi Zosen Corporation, The Robbins Company, Kawasaki Heavy Industries, Mitsubishi Heavy Industries, Herrenknecht AG, Caterpillar Inc, China Tunnel Engineering Equipment Group, China Railway Construction Heavy Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shield Machines Market Emerging Trajectories
Automation of cutterhead steering and segment erection is compressing labor requirements while predictive maintenance algorithms reduce unplanned downtime in continuous tunneling operations.
Condition-based monitoring through embedded vibration and temperature sensors is decomposing the traditional fixed-interval maintenance model. Metro authorities in Germany and Japan are specifying these systems in tender documents. The shift is compressing aftermarket parts revenue streams while elevating software and analytics contracts.
The EU Machinery Directive's 2023 amendments to cutterhead access guarding and emergency stop response times are forcing redesigns of operator platforms and hydraulic lockout systems. Manufacturers serving European urban transit markets are absorbing these costs into base pricing. Hard rock TBM configurations face the steepest redesign burden due to confined cutterhead volumes.
Service contract unbundling is fragmenting the traditional machine-plus-maintenance bundle. Contractors in China's Pearl River Delta are separately sourcing cutterhead tooling, segment supply, and slurry treatment from specialist providers. This disaggregation pressures OEM margin capture while opening entry points for component specialists.
Shield Machines Market Segmentation
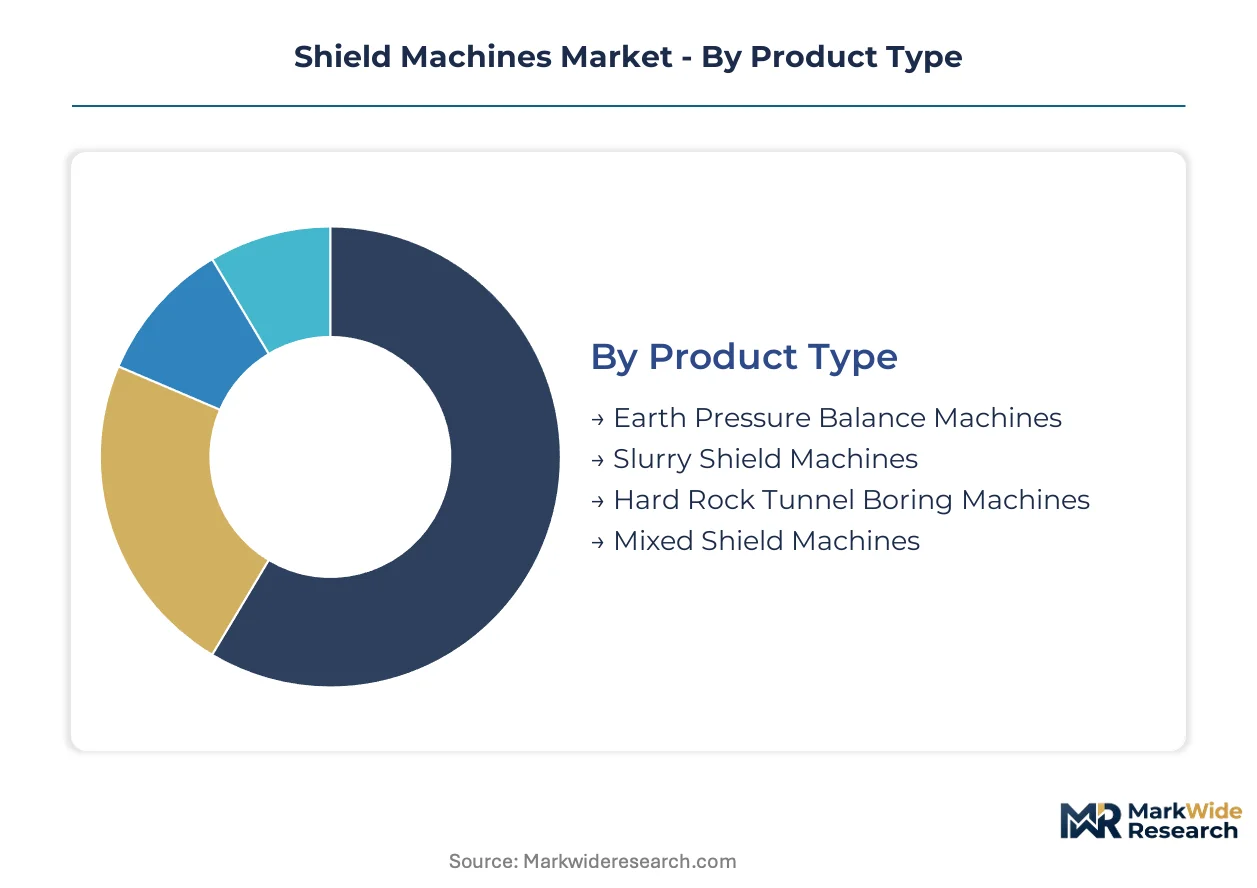
Segmentation in the shield machines market determines procurement specifications, certification pathways, and aftermarket service bundling. Contractors select configurations based on geology, tunnel diameter, and groundwater conditions rather than brand preference alone.
Product Type:
Channel distribution varies sharply by product complexity, with earth pressure balance and slurry shield systems flowing through specialized tunneling contractors while hard rock TBMs often move through mining equipment distributors.
- Earth Pressure Balance Machines:These systems maintain face pressure through controlled spoil extraction in soft ground conditions. China's subway megaprojects in Guangzhou and Chengdu anchor procurement volumes for urban corridors beneath dense metropolitan cores where settlement tolerances are tight.
- Slurry Shield Machines:Bentonite slurry stabilizes the excavation face and transports cuttings through pressurized pipelines. European urban transit authorities in Germany and France specify these for subaqueous crossings and high-water-pressure zones beneath riverbeds.
- Hard Rock Tunnel Boring Machines:Disc cutter arrays fracture competent rock at high torque for hydroelectric penstocks and mining access tunnels.
- Mixed Shield Machines:Convertible configurations switch between EPB and slurry modes without site replacement.
By volume, earth pressure balance machines lead. By growth pace, mixed shield machines are ahead.
End User:
Cost tier stratification separates premium-specification transportation projects from standardized utility deployments with narrower performance envelopes.
- Transportation:Subway authorities and road agencies demand continuous boring capability with sub-millimeter alignment precision. Japan's metro operators specify automated steering systems for congested urban corridors where surface disruption is prohibited.
- Water Supply:Municipal water boards prioritize corrosion-resistant segment erection systems for potable water conveyance tunnels.
- Wastewater Treatment:Deep interceptor sewers in coastal cities require slurry shield configurations for saturated ground conditions.
- Utility Tunneling:Power cable and district heating corridors specify smaller-diameter machines with rapid mobilization cycles.
Transportation commands the highest unit values. Utility tunneling shows the steepest expansion trajectory as cities bury infrastructure networks.
Application:
Volume concentration follows public infrastructure investment cycles, with subway construction absorbing multiple machines per corridor while dam projects deploy single units over extended timelines.
- Subway Construction:Sequential station-to-station drives demand high availability and rapid segment installation cycles. South Korea's Seoul Metro and India's Delhi Metro procure earth pressure balance fleets for alluvial soil conditions.
- Road Tunneling:Mountain highway crossings require hard rock TBMs with cutterhead designs optimized for abrasive quartzite and granite formations.
- Dam Projects:Diversion and headrace tunnels in the Himalayas and Andes command premium specifications for high-altitude operation.
- Pipeline Installation:Oil, gas, and water transmission corridors favor smaller-diameter machines with simplified logistics for remote linear routes.
Subway construction dominates unit shipments. Road tunneling generates the highest revenue per machine.
Technology:
Margin capture concentrates in automated and hybrid systems where software content elevates pricing power beyond mechanical specifications.
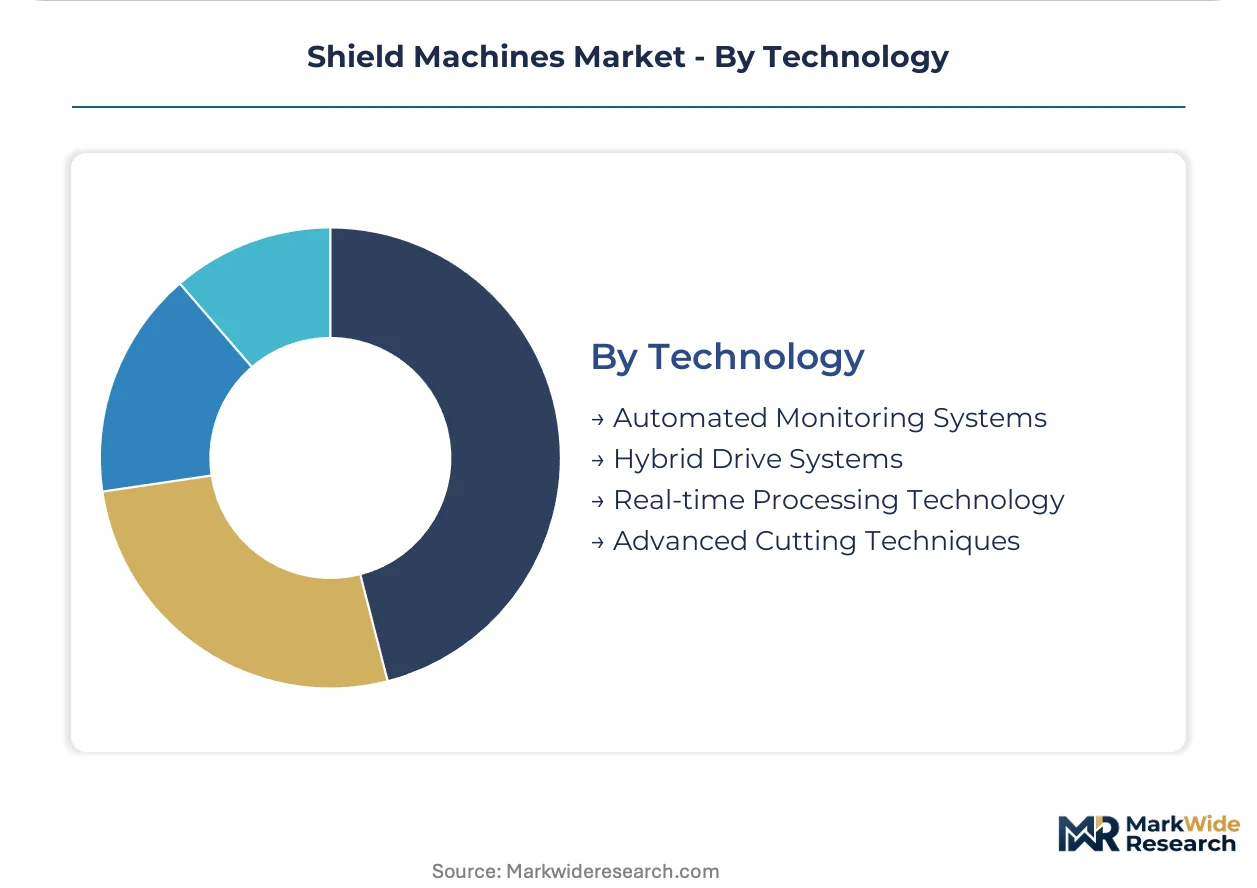
- Automated Monitoring Systems:Embedded sensors track cutterhead vibration, thrust cylinder pressure, and segment alignment in real time. Germany's Ruhr region metro authorities mandate these for continuous settlement monitoring beneath sensitive surface structures.
- Hybrid Drive Systems:Dual-mode electric-hydraulic powertrains switch between high-torque rock cutting and precision soft-ground control. Contractors in variable geology zones from Italy to Malaysia specify these to avoid machine replacement costs.
- Real-time Processing Technology:Edge computing platforms analyze face conditions and autonomously adjust advance rates.
- Advanced Cutting Techniques:Disc cutter metallurgy and spacing optimization extend tool life in abrasive ground.
Hybrid drive systems lead on revenue contribution. Automated monitoring is gaining share fastest as authorities embed requirements in tender documents.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Guangzhou-Shenzhen-Hong Kong Express Rail Link and Chengdu's radial subway network anchor China's procurement dominance. Germany's Rastatt Base Tunnel and Stuttgart-Ulm rail corridor sustain European demand. India's Mumbai Metro and Delhi-Meerut RRTS drive South Asian expansion.
China
Guangzhou Metro's Phase IV expansion and Chengdu's 700-kilometer network anchor earth pressure balance procurement volumes. MIIT localization thresholds mandate 70% domestic content ratios for subway megaproject eligibility. The Pearl River Delta manufacturing cluster around Guangzhou and Shenzhen hosts captive forging capacity for cutterhead ring production.
Germany
The Rastatt Base Tunnel and Stuttgart-Ulm high-speed rail corridor sustain slurry shield deployment beneath the Rhine Valley. EU Machinery Directive cutterhead access mandates and emergency stop response requirements elevate engineering costs for domestic tenders. Herrenknecht's Schwantau headquarters anchors specialized slurry technology development for European urban transit authorities.
India
Mumbai Metro Line 3 and Delhi-Meerut Regional Rapid Transit System drives earth pressure balance adoption through alluvial Gangetic soils. The Ministry of Housing and Urban Affairs' Metro Rail Policy mandates 25% mandatory land value capture financing for new corridors. The Delhi-Mumbai Industrial Corridor clusters tunneling contractor capacity around Ahmedabad and Surat.
Japan
Osaka Metro's Nanko Port Town extension and Tokyo's Outer Ring Road tunneling sustain hybrid drive specification for congested urban corridors. METI's infrastructure export promotion program subsidizes technology transfer for Southeast Asian deployments. The Nagoya-Tokyo industrial belt concentrates disc cutter metallurgy specialists and precision forging capacity.
United States
The Los Angeles Metro Purple Line extension and Seattle's Sound Transit 3 program anchor hard rock TBM procurement for mountainous terrain. FTA Buy America requirements mandate 100% domestic steel content for federally funded transit projects. The Pacific Northwest corridor from Seattle to Portland hosts specialized tunneling contractor engineering offices.
Shield Machines Market Vendor Landscape
Concentration sits with diversified heavy industrial conglomerates and specialized tunneling equipment fabricators. European and Japanese manufacturers anchor premium-tier positioning through slurry shield specialization and hybrid drive integration. Chinese state-owned equipment groups dominate domestic volume through MIIT-compliant localization. Competitive moves center on joint venture formation for market access compliance and captive forging capacity expansion for cutterhead ring supply security.
Among German and Japanese industrial conglomerates, Herrenknecht AG, Komatsu Ltd, and Mitsubishi Heavy Industries occupy positions across the technology spectrum. Herrenknecht exemplifies deep specialization in slurry shield configurations for European subaqueous crossings. Komatsu leverages construction equipment distribution networks to compete in Southeast Asian infrastructure tenders. Mitsubishi Heavy Industries anchors hybrid drive development for variable geology corridors. Chinese state-owned groups including China Railway Construction Heavy Industry represent the localization-compliant tier serving domestic subway megaprojects. The Robbins Company sits within the North American hard rock specialist archetype for mining access and hydroelectric penstock applications.
| Leading Market Players |
|---|
| Komatsu Ltd |
| Hitachi Zosen Corporation |
| The Robbins Company |
| Kawasaki Heavy Industries |
| Mitsubishi Heavy Industries |
| Herrenknecht AG |
| Caterpillar Inc |
| China Tunnel Engineering Equipment Group |
| China Railway Construction Heavy Industry |
| Others |
Supply Flow & Price Mechanics
EU Machinery Directive certification gates both supply qualification and price differentiation, forcing manufacturers to absorb engineering overhead for CE-marked configurations while Chinese MIIT localization thresholds create parallel domestic pricing tiers that foreign suppliers cannot access without joint venture restructuring.
Pricing Analysis
Volume-discount tiering structures separate subway authority fleet procurements from single-machine utility contracts. Premium-mid-economy pricing differentiation tracks certification grade and after-sales service bundling, with CE-marked slurry shields commanding substantial premiums over GB-standard equivalents. Cost compression in the mid-tier is intensifying because contractors in Southeast Asia unbundle service contracts and source components separately. Municipal transit authorities with fleet-scale purchasing power exhibit lowest price sensitivity, while independent tunneling contractors in emerging markets negotiate hardest on upfront capital cost.
Supply Chain Analysis
China and Japan anchor cutterhead ring forging and disc cutter metallurgy supply respectively. High-manganese wear-resistant steel for cutterhead assemblies draws from concentrated mining jurisdictions, while hydraulic power units and thrust cylinder seals hinge on German and Japanese precision manufacturing. Single-source vulnerability runs through specialized steel alloy supply subject to mining concentration. Distribution runs through specialized tunneling contractors for complex EPB and slurry systems, with hard rock TBMs moving through mining equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized tunneling engineer scarcity constrains operational scaling across contracting fleets, with real-time face pressure management skills commanding premium wages that compress project margins and limit machine utilization rates.
For Market Incumbents: Secure captive forging capacity for cutterhead ring supply through backward integration into high-manganese steel sourcing, insulating margin erosion from alloy price volatility. Deepen software and analytics service contracts to offset declining aftermarket parts revenue from condition-based monitoring adoption. Defend against unbundling pressure by embedding control system architecture that locks in proprietary tooling specifications. For New Entrants and Emerging Players: CE marking fast-track pathways through notified body pre-submission consultations open European urban transit access for hybrid drive specialists lacking established track records. Southeast Asian infrastructure gaps in Vietnam and Indonesia present the most penetrable geography, where domestic production capacity absence creates import windows. Pursue joint venture structures with Chinese state-owned equipment groups to satisfy MIIT localization thresholds for subway megaproject eligibility. For Investors and Strategic Acquirers: EU Green Deal carbon accounting milestones reshape the acquisition landscape by elevating energy efficiency benchmarks and electrified drive configuration capabilities as valuation differentiators. Long-term viability favors manufacturers with integrated hybrid drive development and established regional service networks. Target acquisition archetypes include disc cutter metallurgy specialists and aftermarket refurbishment operators. Monitor MIIT localization threshold adjustments as the signal for joint venture restructuring requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Joint Venture Formation | MIIT-compliant localization satisfies domestic content ratios for Chinese subway megaproject eligibility. |
| Captive Forging Capacity Expansion | Backward integration into cutterhead ring production insulates supply security from steel alloy volatility. |
| Hybrid Drive Technology Investment | Dual-mode configurations capture contractor demand for operational flexibility across variable geology. |
| Aftermarket Service Unbundling Response | Software and analytics contracts offset declining parts revenue from condition-based monitoring shifts. |
| Southeast Asian Service Network Buildout | Regional presence captures infrastructure procurement in Vietnam and Indonesia lacking domestic capacity. |
Methodological Framework
Initial hypotheses were tested against primary input from tunneling contractors, metro authority procurement directors, and aftermarket service managers and refined through secondary validation against customs trade data, SEC filings of listed construction equipment manufacturers, EPC project databases, and national transit authority tender documents. Bottom-up machine shipment tracking triangulates with top-down infrastructure investment flow analysis.
Variance-decomposition framing isolates volume and price contributions across product type, end user, application, and technology segmentation dimensions. CAGRs derive from fitted growth curves applied to infrastructure pipeline data and equipment replacement cycles. Forecast inputs incorporate subway construction timelines, hydroelectric project development stages, and mining access tunnel commissioning schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained public infrastructure investment and stable regulatory certification pathways; material deviation in steel alloy supply concentration or MIIT localization threshold adjustments would warrant model refresh. Recalibration cycles align with material shifts in infrastructure procurement cycles and regulatory amendment schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Collating Machinery Market
Construction Equipment
Saudi Arabia Construction Equipment Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Global PDC Drill Bits Market
Construction Equipment
Manhole Housing Lifter Hook Market
Construction Equipment
Rotational Moulding Machines Market
Construction Equipment
Garage Equipment Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Walform Machines Market
Construction Equipment
Turkey Construction Equipment Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Inflatable Ramps Market
Construction Equipment
Grout Bags Market