
 Saudi Arabia Construction Equipment Market | 2026-2036
Saudi Arabia Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Construction Equipment Market Insights
Saudi Arabia is rewriting construction equipment demand patterns through giga-project execution at NEOM, the Red Sea Project, and Qiddiya. Caterpillar leverages its established dealer network across the Eastern Province to sustain parts availability and service density. Komatsu Ltd anchors earthmoving supply through localized support centers in Riyadh and Jeddah. Volvo Construction Equipment differentiates via connected fleet telematics tailored to Saudi temperature extremes and dust conditions.
Construction equipment encompasses heavy machinery designed for earthmoving, material handling, and vertical lifting in built-environment projects, typically powered by diesel engines rated above 75 kW and built to ISO 6165 dimensional classifications for hydraulic excavators and wheel loaders. Excavators dominate procurement volumes across Saudi giga-projects due to their versatility in desert terrain preparation and foundation excavation. Hydraulic technology still occupies the majority of installed fleet value, though electric drivetrains are gaining specification share in indoor and tunneling applications where emission restrictions apply. Mining end-user demand concentrates in the phosphate and bauxite belts of the Northern Borders region, creating a distinct equipment specification tier from general construction.
SFDA and SASO govern equipment safety certification and energy-efficiency labeling for imported machinery, while the Saudi Building Code mandates operator certification standards that shape training and aftermarket service demand. The Ministry of Municipal and Rural Affairs enforces noise and emission thresholds for urban construction zones, pushing rental fleets toward newer Tier-compliant engine specifications. Stakeholders must monitor how local content requirements evolve under Vision 2030 industrialization targets to determine whether to expand Saudi assembly operations or deepen distributor partnerships.
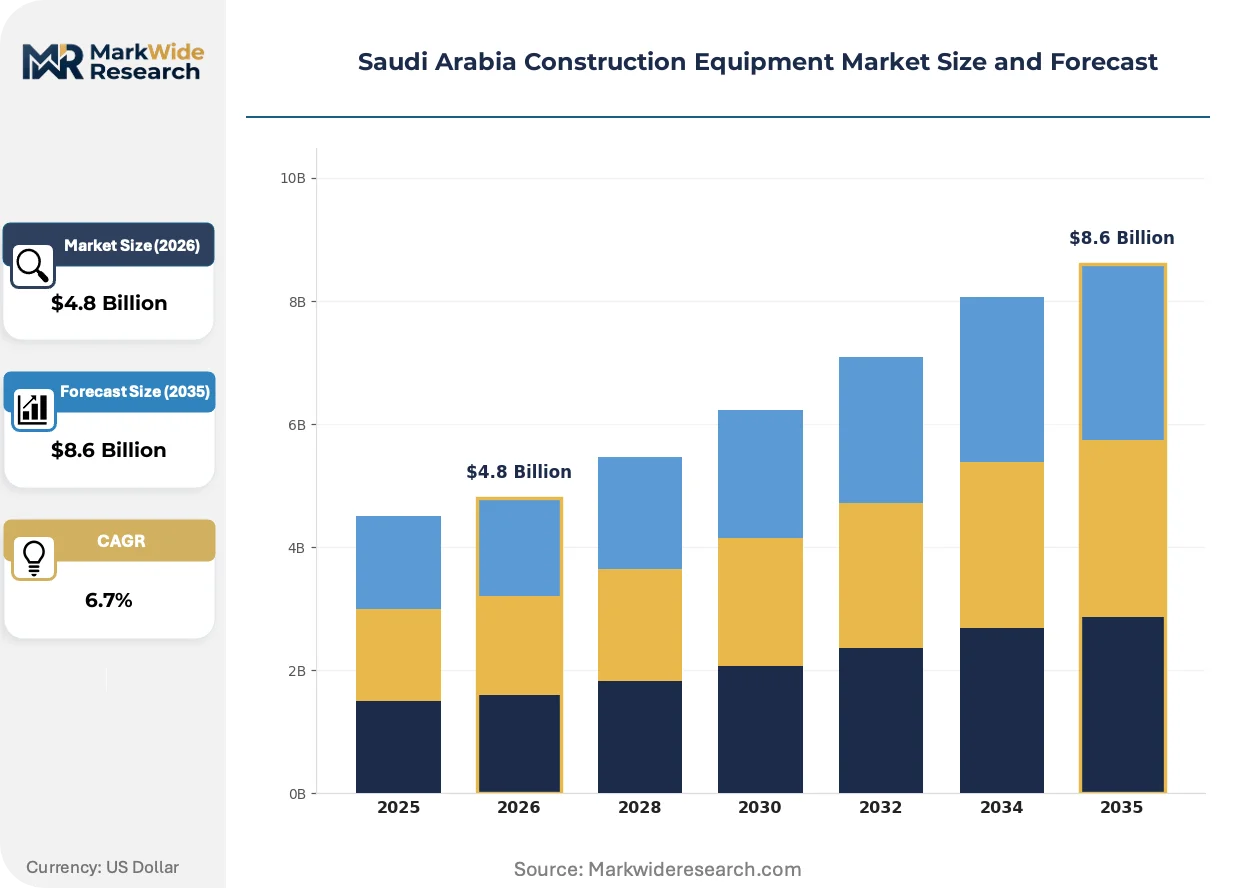
Market Dynamics
Giga-project execution timelines under Vision 2030 are compressing equipment procurement cycles and forcing rental fleet operators to pre-position assets years ahead of construction mobilization.
Growth Catalysts
- Vision 2030 infrastructure pipeline:NEOM, the Red Sea Project, and Qiddiya are generating sustained demand for earthmoving and lifting equipment across multiple simultaneous sites.
- SASO energy-efficiency mandates:Tier-compliant engine specifications are accelerating fleet replacement cycles among rental operators serving urban construction zones.
- Phosphate and bauxite belt expansion:Mining operations in the Northern Borders region are creating specialized equipment demand distinct from general construction applications.
Market Restraints
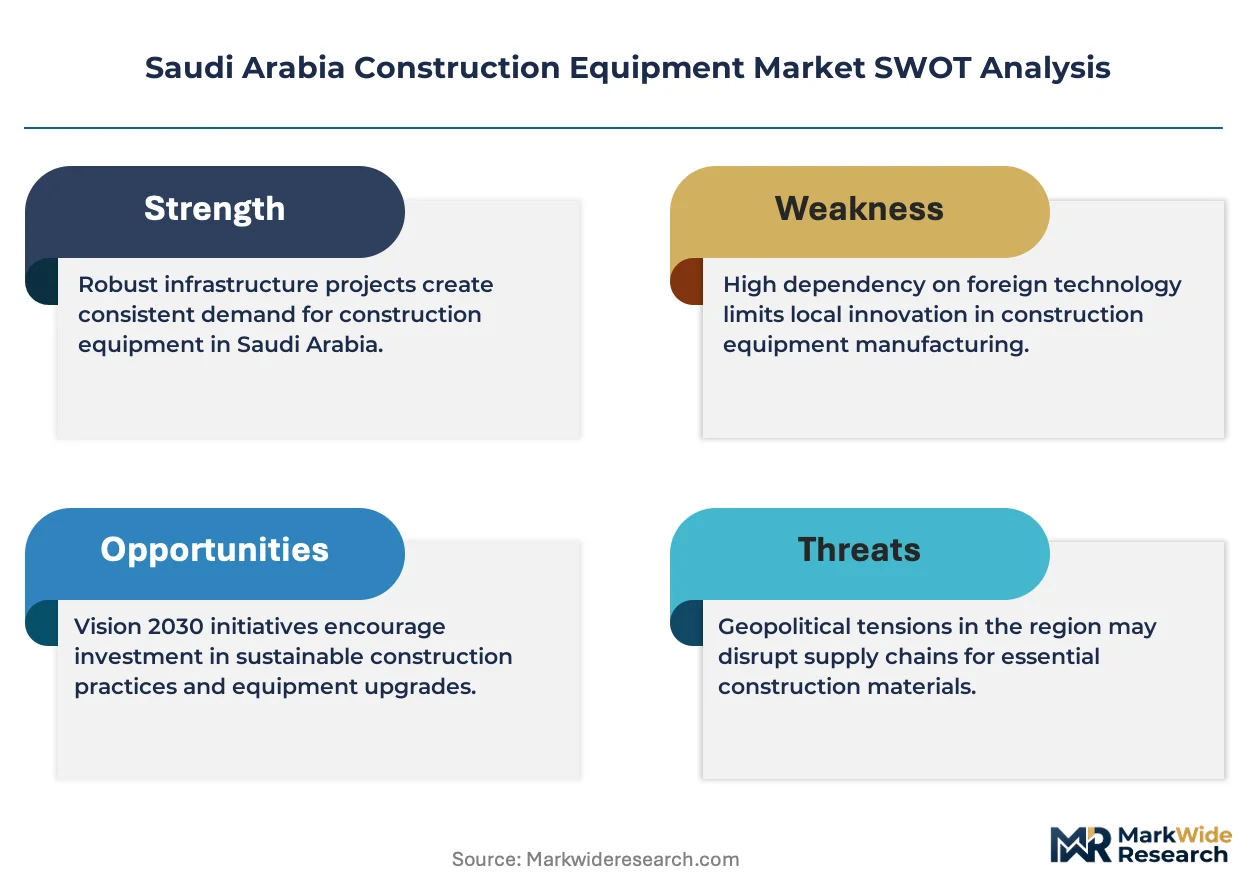
- Import dependency for hydraulic components:Core drivetrain and control systems concentrate among East Asian suppliers, exposing procurement to shipping bottlenecks.
- SFDA certification timelines:Equipment safety validation protocols add months to delivery schedules for non-established suppliers.
- Skilled operator scarcity:Saudi Building Code certification requirements outpace local training program output, constraining fleet utilization rates.
Strategic Opportunities
- Local assembly expansion:Industrialization targets under Vision 2030 incentivize joint ventures for domestic manufacturing of excavators and wheel loaders.
- Electric drivetrain niche penetration:Tunneling and indoor applications in Riyadh metro extensions favor zero-emission equipment specifications.
- Connected fleet telematics:Integration of dust-resistant sensors and temperature-hardened diagnostics opens premium service contract revenue streams.
Industry Challenges
- Aftermarket parts availability:Desert operating conditions accelerate component wear, stretching distributor inventory networks across vast project corridors.
- Multi-jurisdiction coordination:Equipment deployed across NEOM, the Red Sea coast, and Riyadh simultaneously faces fragmented municipal permitting regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Construction Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Loaders, Cranes, Bulldozers Technology: Electric, Hydraulic, Pneumatic, Mechanical End User: Commercial, Residential, Infrastructure, Mining Deployment: On-site, Off-site, Rental, Sale |
| Companies Covered | Caterpillar, Komatsu Ltd, Volvo Construction Equipment, Hitachi Construction Machinery, Liebherr, SANY, XCMG, JCB, Kobelco Construction Machinery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Construction Equipment Market Trends and Innovations
Equipment specification standards are pivoting from diesel-centric performance metrics to hybrid-ready platforms and predictive maintenance architectures. This shift redefines competitive differentiation among suppliers serving Saudi giga-projects.
Telematics-integrated hydraulic control systems are rendering obsolete manual fleet management practices reliant on periodic site inspections. Major rental operators in the Eastern Province are adopting real-time fuel consumption and idle-time monitoring. This compression of information asymmetry between asset owners and operators is rendering obsolete traditional time-based maintenance contracts.
SFDA equipment safety protocols and SASO energy-efficiency labeling requirements are tightening import compliance burdens. Machinery without pre-certified component traceability faces extended customs clearance procedures. Earthmoving equipment categories are most affected, with distributors accelerating pre-shipment documentation to avoid project timeline penalties.
Rental-versus-purchase decision calculus is shifting toward operational expenditure models among mid-tier contractors. Asset-light positioning allows smaller firms to bid on giga-project subcontracts without capital-intensive fleet ownership. This behavioral change is most visible in Jeddah and the Red Sea coastal corridor where project durations remain uncertain.
Saudi Arabia Construction Equipment Market Segmentation
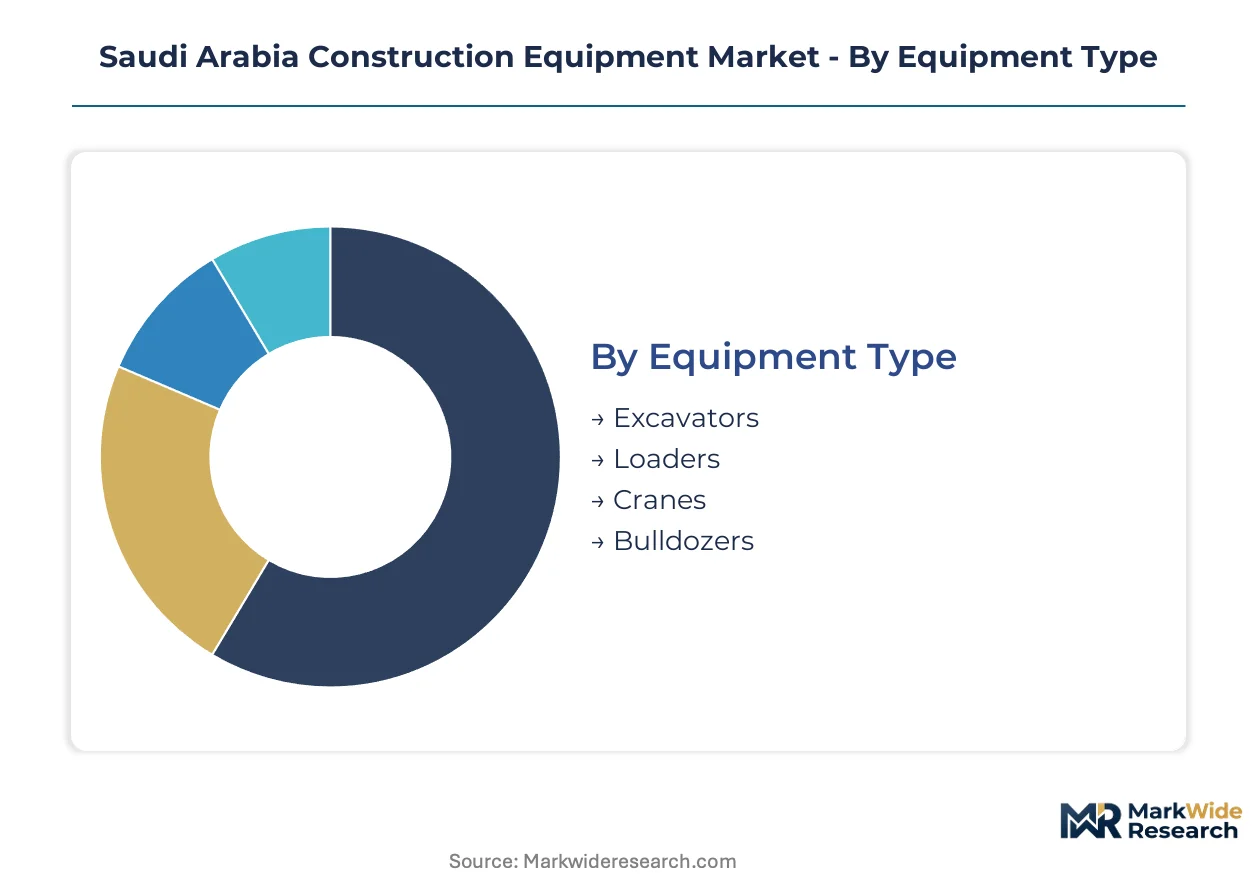
Equipment specification patterns across Saudi Arabia's construction sector diverge sharply between giga-project corridors and urban infill zones. Procurement cycles compress where Vision 2030 timelines demand simultaneous mobilization across NEOM, Qiddiya, and Red Sea coastal sites.
Equipment Type:
Earthmoving and lifting machinery spans a functional range from precision excavation to heavy material displacement, with specification tiers calibrated to desert operating conditions and foundation engineering requirements.
- Excavators:Hydraulic machines rated above 20 metric tons dominate fleet procurement for foundation work and terrain preparation across NEOM's linear city footprint. Demand concentrates in the Red Sea coastal corridor where marine-influenced soil conditions require extended-reach configurations and reinforced undercarriages.
- Loaders:Wheel loaders with high-lift arms and desert-rated cooling systems handle aggregate movement and site logistics across Qiddiya entertainment district earthworks. Procurement volumes track phosphate belt expansion in the Northern Borders region where mining contractors specify larger bucket capacities for bulk material handling.
- Cranes:Tower and mobile configurations serve vertical construction phases across Riyadh's commercial high-rise cluster.
- Bulldozers:Track-type tractors with blade attachments clear and grade vast desert parcels for linear infrastructure corridors.
The dominant share belongs to excavators, while loaders are closing the gap fastest.
Technology:
Power transmission architectures range from established diesel-hydraulic platforms to emerging electric drivetrains, with specification decisions shaped by emission zone restrictions and operating environment constraints.
- Hydraulic:Fluid-power systems with piston pumps and valve manifolds remain the installed base standard across Saudi rental fleets. SFDA certification requirements and SASO energy-efficiency labeling apply most stringently to hydraulic component traceability for imported machinery.
- Electric:Battery-electric and tethered configurations penetrate tunneling applications and enclosed structures where Ministry of Municipal and Rural Affairs emission thresholds apply. Riyadh metro extension contracts specify zero-emission equipment for underground segments, creating a distinct procurement tier from surface construction.
- Pneumatic:Compressed-air systems serve specialized drilling and breaking attachments in quarry operations.
- Mechanical:Direct mechanical linkages persist in legacy fleet segments and simplified utility applications.
Hydraulic systems retain the dominant share, though electric configurations are expanding most quickly in restricted-emission zones.
End User:
Demand concentration varies across project scales from sovereign wealth-funded megadevelopments to private commercial construction and resource extraction operations.
- Infrastructure:State-backed giga-projects under Vision 2030 generate sustained procurement volumes across simultaneous sites. NEOM, the Red Sea Project, and Qiddiya operate on compressed timelines that pre-position equipment years ahead of mobilization.
- Mining:Phosphate and bauxite extraction in the Northern Borders region creates specialized equipment demand with distinct durability specifications from general construction. Ma'aden expansion contracts require desert-hardened undercarriages and enhanced filtration systems for abrasive operating conditions.
- Commercial:Private sector development across Riyadh and Jeddah follows conventional procurement cycles with greater rental penetration.
- Residential:Smaller-scale housing construction favors compact equipment configurations and shorter-term rental arrangements.
Infrastructure commands the dominant share, while mining is gaining share fastest on resource sector expansion.
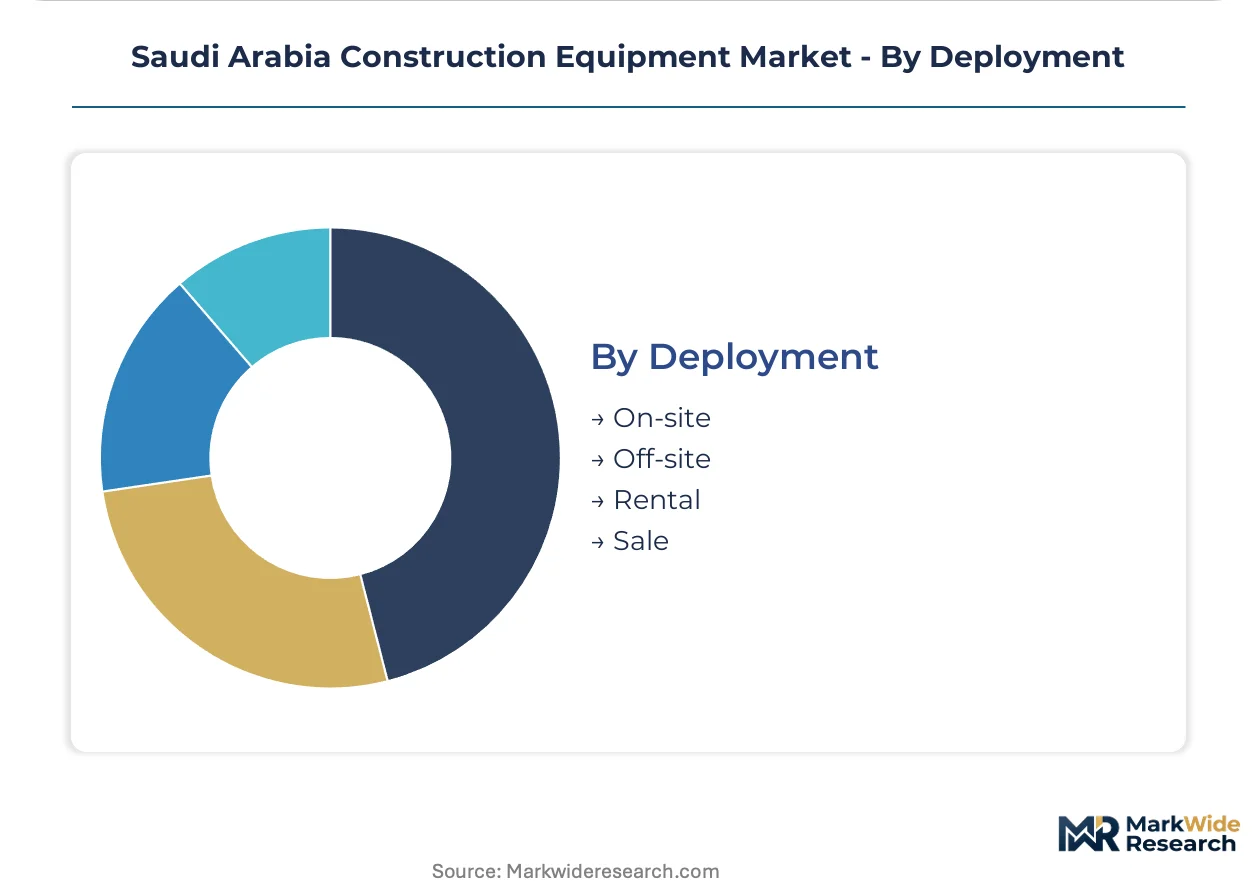
Deployment:
Asset ownership models range from capital-intensive fleet purchases to operational expenditure structures that align equipment access with project duration uncertainty.
- Rental:Operational lease arrangements allow mid-tier contractors to bid on giga-project subcontracts without balance-sheet commitment. Rental penetration is highest in Jeddah and the Red Sea coastal corridor where project timelines remain fluid and asset-light positioning reduces stranded equipment risk.
- Sale:Direct equipment purchases concentrate among established contractors with multi-year backlog visibility across Eastern Province oil and gas infrastructure. Caterpillar and Komatsu dealer networks in Riyadh and Dammam anchor aftermarket service density for owned fleets.
- On-site:Dedicated equipment deployment accompanies long-duration contracts with guaranteed utilization rates.
- Off-site:Yard-based asset pooling serves intermittent demand patterns across fragmented municipal jurisdictions.
Rental models hold the dominant share, while direct sales are climbing the fastest among contractors securing multi-year sovereign contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA equipment safety protocols and SASO energy-efficiency mandates anchor regulatory frameworks across Saudi Arabia's construction corridors, with demand concentrating in four distinct sub-regions executing Vision 2030 infrastructure timelines.
Riyadh
Commercial high-rise development and metro extension projects drive excavator and crane procurement across the capital region. The Saudi Building Code enforces operator certification standards that shape training infrastructure investments. Riyadh's central business district hosts dense rental fleet operations serving simultaneous giga-project mobilizations.
Eastern Province
Oil and gas infrastructure maintenance sustains multi-year equipment backlogs among established contractors. Ministry of Municipal and Rural Affairs noise thresholds push rental operators toward newer Tier-compliant engine specifications. Dammam anchors Caterpillar and Komatsu dealer networks with concentrated aftermarket service density.
Western Region
Jeddah's Red Sea coastal corridor exhibits highest rental penetration where project timelines remain fluid. SASO import compliance burdens concentrate at King Abdulaziz Port, stretching customs clearance for earthmoving equipment. The Jeddah Islamic Port logistics cluster handles bulk excavator shipments for Red Sea Project mobilization.
NEOM Northwest
The linear city footprint generates specialized demand for extended-reach excavators and desert-hardened undercarriages. SFDA certification timelines compress procurement cycles as foreign suppliers pre-position documentation. Oxagon and THE LINE construction zones operate equipment at full deployment across simultaneous earthmoving phases.
Saudi Arabia Construction Equipment Market Competitive Landscape
Capability concentration sits with established multinational manufacturers holding certified dealer networks; scale advantage sits with emerging Asian producers expanding through direct import channels. The market structures around three tiers: premium OEMs with full-service distribution, mid-tier specialists in specific equipment categories, and value-positioned challengers penetrating rental fleet replacement cycles. Dominant competitive moves include strategic partnerships for local assembly joint ventures and technology licensing agreements that bypass SFDA certification bottlenecks.
Among the premium-tier manufacturers, Caterpillar leverages its Eastern Province dealer infrastructure to sustain parts availability across vast project corridors. Komatsu Ltd anchors earthmoving supply through localized support centers in Riyadh and Jeddah. Volvo Construction Equipment occupies a differentiated position via connected fleet telematics adapted to Saudi temperature extremes and dust conditions.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu Ltd |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| Liebherr |
| SANY |
| XCMG |
| JCB |
| Kobelco Construction Machinery |
| Others |
Pricing and Supply Chain Analysis
Dammam's Eastern Province dealer infrastructure anchors aftermarket parts availability across Saudi Arabia's vast project corridors, translating concentrated service density into pricing power for premium-tier OEMs serving multi-year oil and gas contracts. Tier-compliant engine specifications mandated by SASO and the Ministry of Municipal and Rural Affairs compress replacement cycles, forcing rental operators to absorb accelerated depreciation costs that ripple through equipment lease rates.
Pricing Analysis
Riyadh commands premium positioning over Jeddah and the Red Sea coastal corridor, where fluid project timelines and higher rental penetration intensify rate competition among mid-tier fleet operators. Three-tier pricing structure across premium, standard, and economy levels separates Caterpillar and Komatsu dealer-supported fleets from direct-import Asian challengers and used-equipment brokers. Pricing pressure stems from SFDA certification delays that strand capital in customs, squeezing margins for non-established suppliers. Mid-tier contractors exhibit highest price sensitivity, while sovereign-backed giga-project developers prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Hyundai Heavy Industries and Doosan Infracore hold concentrated capacity for hydraulic component production serving Saudi-bound excavator assemblies. Core drivetrain systems draw from South Korea, Japan, and China, with engine blocks and control electronics resting on East Asian manufacturing clusters. Single-source vulnerability in precision hydraulic valve manufacturing exposes procurement to shipping bottlenecks through the Strait of Hormuz. Distribution runs through Jeddah Islamic Port and King Abdulaziz Port, where SASO pre-certification documentation determines customs clearance velocity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's construction equipment market fragments across giga-project scale tiers, with Vision 2030's compressed mobilization schedules creating distinct procurement niches for specialized desert-hardened configurations versus standard urban rental fleets.
For Market Incumbents: Harden aftermarket service density in the Northern Borders mining belt before phosphate and bauxite expansion accelerates. Deepen vertical integration of desert-rated filtration and cooling component production within Saudi industrial zones to satisfy evolving local content requirements. Lock multi-year service contracts with NEOM development authorities to preempt Asian challenger penetration in extended-reach excavator categories. For New Entrants and Emerging Players: Pursue electric drivetrain specifications for Riyadh metro tunneling segments where Ministry of Municipal and Rural Affairs emission thresholds exclude diesel alternatives. Target Jeddah's Red Sea coastal corridor rental market, where asset-light contractors favor operational expenditure models over fleet ownership. Partner with established Saudi logistics providers to bypass SFDA certification bottlenecks through pre-positioned documentation and local assembly joint ventures. For Investors and Strategic Acquirers: Long-term, this sits as a local-content arbitrage play because Vision 2030 industrialization targets progressively tighten import restrictions while sovereign capital guarantees project pipeline visibility. Acquisition candidates include mid-tier rental operators with established municipal permitting relationships across fragmented jurisdictions. Monitor SASO energy-efficiency mandate enforcement cadence as the inflection signal for fleet replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Joint Venture | Positions OEMs to satisfy Vision 2030 local content thresholds for NEOM procurement preferences. |
| Desert-Hardened Component Sourcing | Secures proprietary filtration and cooling specifications that differentiate fleet performance in abrasive conditions. |
| Connected Fleet Telematics Deployment | Enables predictive maintenance contracts that capture recurring revenue from giga-project operators. |
| SFDA Pre-Certification Investment | Compresses delivery timelines for Asian challengers seeking to bypass established dealer networks. |
| Operator Training Infrastructure | Addresses Saudi Building Code certification gaps that constrain fleet utilization across project corridors. |
Research Methodology
Operator-level perspectives from fleet managers at rental companies, procurement leads at giga-project joint ventures, aftermarket service directors at Caterpillar and Komatsu dealer networks, and mining contractors in the Northern Borders region anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through SASO technical regulation filings, Ministry of Municipal and Rural Affairs permitting databases, customs import records at King Abdulaziz Port, and SEC filings from listed construction equipment manufacturers. Bottom-up equipment deployment tallies across NEOM, Qiddiya, and Red Sea Project sites were triangulated against top-down market sizing from sovereign contract award announcements.
Scenario-bracketing framed the analytical approach, with projection horizons tested against Vision 2030 infrastructure commitment trajectories and mining sector expansion plans. Segmentation dimensions modeled include equipment type, power transmission architecture, end-user application, and deployment model across the analysis window. CAGRs were derived from equipment procurement cycle compression rates observed in giga-project mobilizations and rental fleet replacement patterns tied to SASO Tier compliance deadlines. Forecast inputs incorporated phosphate and bauxite belt expansion timelines and Riyadh metro extension phase commitments.
Macroeconomic conditions sit as an overlay; deviation in oil revenue flows, sovereign wealth fund allocation priorities, or construction labor import policies would shift the trajectory. Forecasts reflect assumptions around sustained Vision 2030 execution commitment and stable East Asian component supply chains. Quarterly review of giga-project mobilization schedules, SASO regulatory amendment notices, and dealer inventory build rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Mini Cranes Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
US Aerial Work Platform Market
Construction Equipment
Philippines Construction Equipment Market
Construction Equipment
Vibratory Rammer Market
Construction Equipment
Porter Cable Air Compressor Market
Construction Equipment
Fixed Crane Market
Construction Equipment
Brazil Construction Equipment Market
Construction Equipment
Self-Driving Dumpers Machine Market
Construction Equipment
Malaysia Plastic Injection Molding Machine Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
CNC Lathe Machine Market
Construction Equipment
Backhoes Market