
 Boring-Milling Machines Market | 2026-2036
Boring-Milling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Boring-Milling Machines Market Analysis
High-strength cast iron is consolidating its position as the dominant bed and column material in large-capacity boring-milling machines, displacing welded steel fabrications that require more extensive vibration-damping treatments. PAMA leverages in-house foundry operations to control material quality and thermal stability across its horizontal boring mill portfolio. DANOBATGROUP anchors its competitive stance through deep specialization in energy-sector applications, particularly wind turbine component machining. Doosan Machine Tools competes aggressively on manufacturing scale, operating one of the largest dedicated production facilities for CNC boring equipment in Asia.
A boring-milling machine combines rotary cutting with linear axis movement to enlarge existing holes and machine precise flat surfaces on large workpieces, typically handling components exceeding two meters in diameter and requiring spindle power above 50 kW for heavy roughing operations. CNC Boring Machines command the dominant share of new order value due to their integration with five-axis contouring and real-time tool condition monitoring. Horizontal Boring Mills represent the fastest-growing product configuration as energy and aerospace customers prioritize access to four-sided workpiece machining in a single setup. The Technology dimension shows Computer Numerical Control systems capturing margin pools through software-enabled productivity guarantees and remote diagnostics subscriptions.
The EU Machinery Directive and CE marking framework mandate comprehensive risk assessments and electromagnetic compatibility validation for machine tools sold across Europe, elevating compliance costs for non-European builders. The EPA and OSHA in the United States enforce metalworking fluid exposure limits and machine guarding standards that shape equipment specification sheets for domestic automotive and construction buyers. Stakeholders must monitor how evolving cybersecurity requirements for connected CNC systems will reshape supplier qualification criteria and aftermarket service contracts.
Market Dynamics
Horizontal boring mills are capturing disproportionate capital allocation as energy and aerospace OEMs prioritize four-sided machining access in single setups, compressing fixture changeover cycles and floor space requirements.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking and electromagnetic compatibility validation requirements are filtering non-compliant Asian builders from European tender pools, creating protected margin zones for certified manufacturers.
- High-strength cast iron thermal stability:PAMA's foundry-integrated supply chain demonstrates how in-house material control reduces bed distortion during heavy roughing cycles, attracting precision-critical aerospace contracts.
- German automotive supplier density:OEMs in Stuttgart and Munich maintain dense ecosystems for heavy-duty metalworking equipment, generating localized demand pull for large-capacity spindle configurations above 50 kW.
Market Restraints
- Scrap steel and ferroalloy input volatility:Foundry-dependent builders face margin compression when nickel and molybdenum prices spike, forcing selective hedging or surcharge passthrough clauses.
- Asian production concentration risk:Doosan's dominance in dedicated CNC boring facilities creates single-source vulnerability for buyers seeking geographic diversification of supply.
- Welded steel fabrication displacement lag:Legacy machine parks with steel-frame beds require expensive vibration-damping retrofits to match cast-iron performance, slowing replacement cycles.
Strategic Opportunities
- Wind turbine component machining specialization:DANOBATGROUP's energy-sector focus reveals unmet demand for nacelle housing and main bearing bore finishing in emerging offshore wind clusters.
- Remote diagnostics subscription models:CNC system vendors can capture recurring revenue streams by packaging real-time tool condition monitoring with predictive maintenance algorithms.
- Five-axis contouring capability gaps:Mid-tier job shops lack capital for full five-axis integration, creating white space for retrofittable contouring heads and software-enabled productivity guarantees.
Industry Challenges
- CNC programming and mechatronics skill scarcity:Machine tool builders struggle to staff application engineering teams capable of configuring complex multi-axis interpolation for aerospace turbine casings.
- Cybersecurity certification timelines:Connected CNC systems face prolonged validation against evolving IEC 62443 industrial security standards, delaying product launches and service contract rollouts.
- Legacy FANUC and Siemens control integration friction:Proprietary communication protocols complicate third-party sensor integration for tool monitoring and adaptive feedrate systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boring-Milling Machines Market |
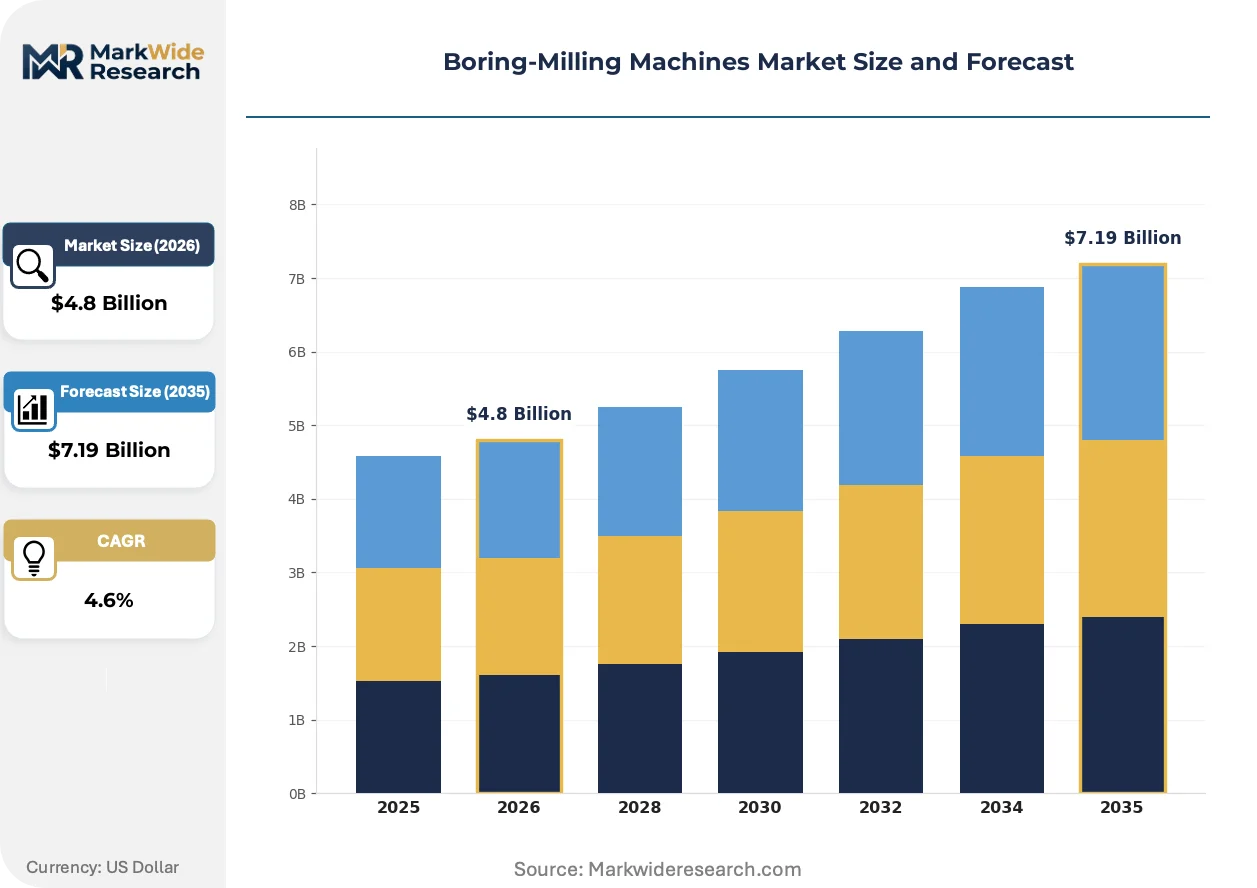
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Boring Machines, Vertical Boring Mills, Horizontal Boring Mills, Bridge Type Boring Machines End User: Aerospace, Automotive, Construction, Energy Capacity: Small Capacity, Medium Capacity, Large Capacity, Customized Capacity Technology: Conventional, Computer Numerical Control, Hybrid, Automation |
| Companies Covered | AZ spa, FPT Industrie, PAMA, Doosan Machine Tools, Juaristi, DANOBATGROUP, LAZZATI, Shibaura Machine, MHI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boring-Milling Machines Market Emerging Trajectories
Software-enabled productivity guarantees and real-time process monitoring are restructuring how machine tool value is captured, shifting revenue from hardware margins to subscription-based uptime commitments.
Direct-drive torque motor rotary tables are expanding into high-precision contouring applications by eliminating backlash and gear wear. Aerospace turbine casing manufacturers in Germany and Japan are specifying these tables for five-axis bore finishing where conventional worm-drive systems introduce unacceptable circularity errors. This technology is expanding into mid-size job shops through modular retrofit kits, compressing the performance gap between premium and standard machine configurations.
REACH chemical restrictions and RoHS substance limitations are forcing reformulation of metalworking fluids and electrical insulation materials used in spindle motors and cable harnesses. European builders face elevated compliance costs for material certification and supply chain documentation, particularly for machines exported to German automotive clusters. Asian manufacturers are responding by establishing EU-based fluid blending partnerships to preempt border rejection risks.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into discrete modules for spindle rebuild, ballscrew replacement, and control software updates. Energy sector buyers in Denmark and the Netherlands now negotiate à la carte coverage based on seasonal utilization patterns rather than fixed annual fees. This shift is most visible in offshore wind supply chains where machining intensity fluctuates with installation vessel availability and weather windows.
Boring-Milling Machines Market Segmentation
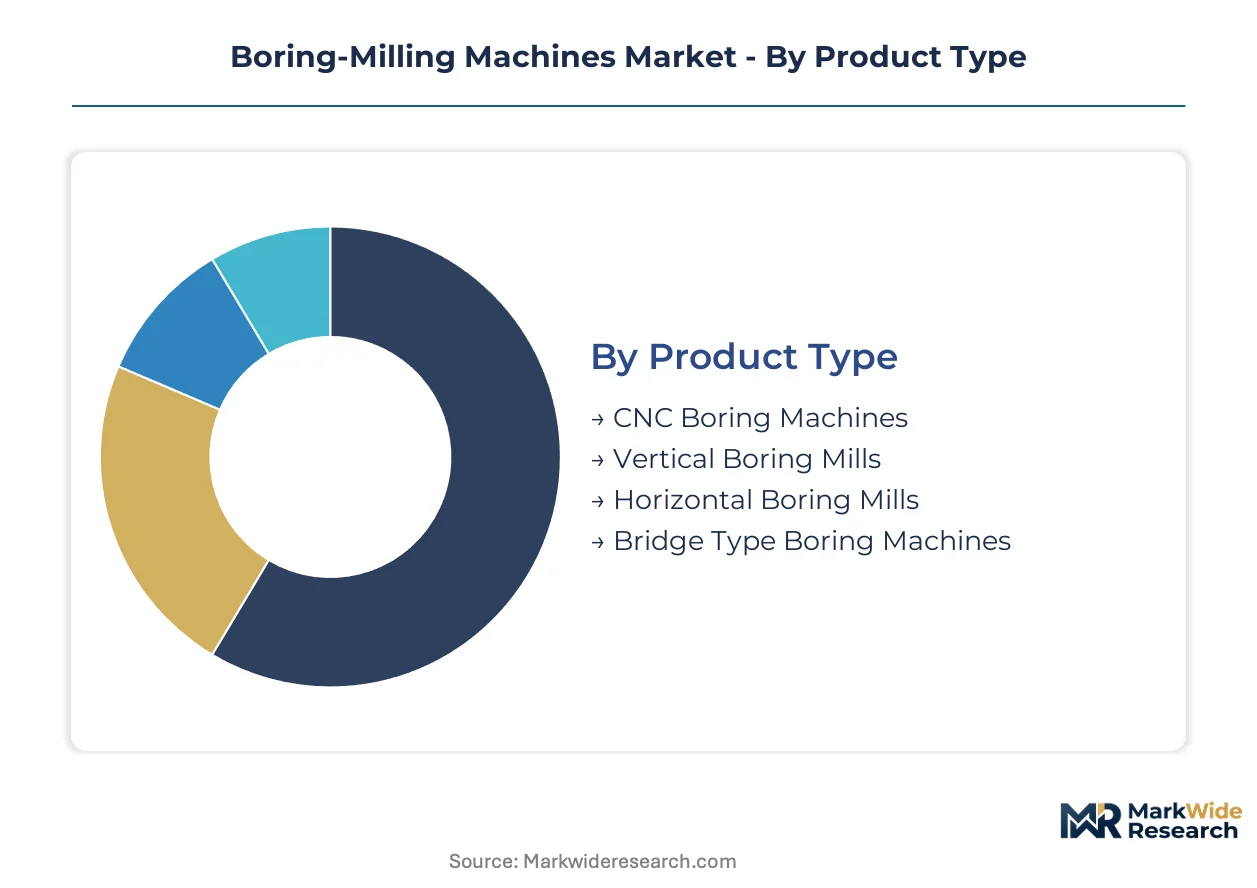
Boring-milling machine procurement follows distinct specification hierarchies that separate precision-critical aerospace contracts from heavy roughing applications in energy and construction. Segmentation reveals how spindle power, axis configuration, and control architecture align with specific capital equipment budgets and operational intensity profiles.
Product Type:
Spindle orientation and structural rigidity define the machining envelope and fixture complexity for each configuration.
- CNC Boring Machines:Integration with five-axis contouring and real-time tool condition monitoring enables complex bore finishing on turbine casings and transmission housings. German automotive OEMs in Stuttgart specify these systems for powertrain component families requiring sub-10-micron positional accuracy.
- Horizontal Boring Mills:Four-sided workpiece access in single setups compresses fixture changeover cycles for energy sector nacelle housings and main bearing bores. Offshore wind clusters in Denmark and the Netherlands prioritize this configuration for seasonal installation windows.
- Vertical Boring Mills:Gravity-assisted chip evacuation suits heavy roughing of large-diameter flanges and pump casings in construction equipment manufacturing.
- Bridge Type Boring Machines:Spanning gantries accommodate workpieces exceeding five meters for shipbuilding and heavy machinery structural components.
Mature deployment sits with vertical boring mills in legacy automotive foundries. Newer deployment is concentrated in horizontal configurations serving renewable energy supply chains.
End User:
Capital intensity and precision requirements create divergent specification patterns across industrial verticals.
- Aerospace:Turbine casing manufacturers demand thermal stability and circularity control for nickel-alloy bore finishing, driving specification of direct-drive rotary tables and cast-iron bed structures.
- Automotive:Powertrain machining lines in Germany balance throughput against changeover flexibility, favoring pallet-based horizontal mills with 50 kW-plus spindle power for cast iron engine blocks.
- Construction:Hydraulic cylinder and frame component producers prioritize purchase price over contouring sophistication, accepting conventional controls for standardized bore families.
- Energy:Wind turbine main bearing bores and nacelle housings require extended Z-axis travel and custom fixture interfaces, with offshore project timelines dictating delivery reliability over unit cost.
Margin concentration aligns with aerospace precision specifications. Volume concentration clusters in automotive serial production.
Capacity:
Workpiece envelope dimensions determine bed construction, spindle power scaling, and transportation logistics.
- Large Capacity:Machines handling components above two meters diameter require segmented cast-iron beds and thermal compensation systems. PAMA's foundry-integrated supply chain targets this tier for aerospace and energy contracts.
- Medium Capacity:Flexible machining centers serving job shops balance floor space constraints against multi-axis capability, representing the primary retrofit and upgrade opportunity.
- Small Capacity:Compact configurations serve subcontract precision engineers and medical device component specialists with limited capital budgets.
- Customized Capacity:Project-specific builds for ship propulsion shafts and industrial press frames involve extended lead times and application engineering intensity.
Specification standardization dominates small and medium tiers. Engineering customization concentrates in large and bespoke configurations.
Technology:
Control architecture and automation integration separate productivity tiers and aftermarket revenue potential.
- Computer Numerical Control:Software-enabled productivity guarantees and remote diagnostics subscriptions restructure vendor revenue toward recurring service streams. FANUC and Siemens control ecosystems dominate this tier.
- Automation:Pallet pools, robotic workpiece handling, and in-process probing reduce operator intervention for high-volume automotive lines. Cybersecurity certification against IEC 62443 standards delays rollout timelines.
- Conventional:Manual and semi-automatic configurations persist in emerging market job shops and maintenance departments with limited programming capability.
- Hybrid:Additive-manufacturing integration for bore repair and cladding applications remains experimental, with material deposition head compatibility constraining adoption.
Installed base concentration remains with conventional systems. Capability investment flows toward CNC and automation tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for boring-milling machines concentrates in industrial clusters with dense automotive and energy equipment supply chains. Germany anchors procurement volume through its precision engineering ecosystem. Regulatory frameworks in the EU, United States, and Asia-Pacific shape equipment specifications and compliance costs.
Germany
Automotive OEMs in Stuttgart and Munich drive specification of 50 kW-plus spindle configurations for powertrain machining. The EU Machinery Directive mandates CE marking and electromagnetic compatibility validation for all imported machine tools. Bavaria's supplier ecosystem generates localized demand pull for large-capacity cast-iron bed structures.
United States
Aerospace manufacturers in the Pacific Northwest and Southeast are expanding capital equipment budgets for precision turbine casing machining. The EPA enforces metalworking fluid exposure limits that shape equipment specification sheets for domestic buyers. Seattle-area clusters prioritize thermal stability for nickel-alloy bore finishing operations.
Japan
Precision engineering traditions sustain demand for direct-drive torque motor rotary tables in turbine casing applications. METI industrial standards govern machine tool safety and electromagnetic compatibility certification. Nagoya-area automotive suppliers specify sub-10-micron positional accuracy for transmission housing production lines.
China
Domestic wind turbine manufacturers are scaling nacelle housing production for offshore installation projects. GB standards and MIIT regulations establish safety and performance benchmarks for CNC equipment. Yangtze River Delta machine tool builders are expanding dedicated production facilities for heavy-duty boring equipment.
Denmark
Offshore wind project developers prioritize delivery reliability for main bearing bore machining equipment. REACH chemical restrictions force reformulation of metalworking fluids used in spindle systems. Esbjerg-area suppliers negotiate à la carte service contracts based on seasonal installation vessel availability.
Boring-Milling Machines Market Vendor Landscape
Capacity expansion dominates the current landscape as builders scale dedicated production facilities for CNC boring equipment. The vendor base organizes around three tiers: foundry-integrated specialists controlling material quality, scale-driven Asian manufacturers operating large production footprints, and precision-focused European engineering houses. Two strategic archetypes have emerged: backward-integrated builders with captive casting operations, and automation-focused vendors bundling remote diagnostics subscriptions. Geographic expansion into offshore wind clusters and technology licensing for five-axis contouring heads represent the dominant competitive moves.
Within the foundry-integrated tier, PAMA exemplifies material control strategies through its in-house casting operations. DANOBATGROUP occupies a position as an energy-sector specialist with particular emphasis on wind turbine component machining. Doosan Machine Tools anchors the scale-driven archetype through its large dedicated production facility in Asia. These three companies represent distinct competitive vectors: material quality assurance, vertical application focus, and manufacturing scale.
| Leading Market Players |
|---|
| AZ spa |
| FPT Industrie |
| PAMA |
| Doosan Machine Tools |
| Juaristi |
| DANOBATGROUP |
| LAZZATI |
| Shibaura Machine |
| MHI |
| Others |
Supply Flow & Price Mechanics
Family-owned Italian machine tool specialists with multi-generational foundry operations anchor supply-side discipline, translating captive casting capacity into pricing power for thermal-stability-critical aerospace contracts while forcing project-based pricing on custom-engineered large-capacity configurations.
Pricing Analysis
Volume concentration in automotive serial production runs against margin concentration in aerospace precision specifications. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified European builders from Asian scale manufacturers and emerging local assemblers. Price differentiation hinges on thermal compensation systems and spindle power ratings above 50 kW. Cost compression in mid-tier CNC configurations is intensifying because Yangtze River Delta builders are expanding dedicated production footprints. Construction equipment buyers exhibit highest price sensitivity, accepting conventional controls for standardized bore families, while energy sector procurement prioritizes delivery reliability over unit cost for offshore wind installation windows.
Supply Chain Analysis
Freight costs for segmented cast-iron bed structures and thermal compensation systems constrain geographic sourcing flexibility for large-capacity machines. Supply concentrates in Germany, Italy, and South Korea, with foundry-integrated builders in Piacenza and Seoul controlling material quality for precision-critical applications. Component sourcing draws from nickel and molybdenum ferroalloy suppliers, direct-drive torque motor manufacturers, and FANUC or Siemens control ecosystems. Single-source vulnerability persists in Asian production concentration for dedicated CNC boring facilities. Distribution runs through OEM procurement teams in Stuttgart and Munich, aftermarket service heads in Esbjerg, and EPC contractors managing offshore wind installation timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Foundry ownership and in-house casting operations represent the decisive upstream lever separating margin-capturing specialists from assembly-dependent competitors.
For Market Incumbents: Cement foundry-integrated supply chain advantages by expanding thermal stability testing protocols for nickel-alloy aerospace contracts. Add spindle rebuild and ballscrew replacement capacity in Denmark and the Netherlands to capture unbundled service contract demand from offshore wind developers. The threat of REACH chemical restrictions forcing metalworking fluid reformulation demands preemptive EU-based fluid blending partnerships. For New Entrants and Emerging Players: Retrofittable five-axis contouring heads for mid-tier job shops lacking capital for full integration represent the most penetrable white space. Target German automotive supplier ecosystems with software-enabled productivity guarantees bundled with remote diagnostics subscriptions. A technology-licensing go-to-market angle with established control vendors bypasses proprietary FANUC and Siemens protocol friction. For Investors and Strategic Acquirers: DANOBATGROUP-style energy-sector specialization announcements are the leading indicator that offshore wind clusters are entering capital equipment procurement cycles. Long-term viability favors builders with captive casting operations and established CE marking compliance infrastructure. The signal to monitor is cybersecurity certification timelines against IEC 62443 standards delaying connected CNC system rollouts.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Integration Expansion | PAMA's in-house casting operations demonstrate how thermal stability control wins aerospace turbine casing contracts. |
| Remote Diagnostics Subscription Launch | Real-time tool condition monitoring packages restructure vendor revenue toward recurring service streams with German automotive OEMs. |
| Five-Axis Contouring Head Licensing | Modular retrofit kits compress the performance gap between premium and standard configurations for mid-size job shops. |
| EU-Based Fluid Blending Partnership | REACH compliance partnerships preempt border rejection risks for Asian manufacturers exporting to German automotive clusters. |
| Offshore Wind Cluster Geographic Expansion | Esbjerg-area service contract unbundling responds to seasonal installation vessel availability and weather window fluctuations. |
Methodological Framework
Multi-period observation of capital equipment order backlogs, foundry capacity utilization, and CE marking certification timelines anchored the trend analysis, supplemented by interviews with maintenance directors at German automotive OEMs, plant engineers in Danish offshore wind supply chains, aftermarket service heads at Italian machine tool builders, and OEM procurement teams in Stuttgart. Secondary validation drew from EU Machinery Directive compliance databases, EPA metalworking fluid exposure filings, customs records for cast-iron bed imports, and SEC disclosures from publicly traded control system vendors. Bottom-up equipment shipment tallies triangulated against top-down industrial production indices for precision engineering sectors.
Segment-weighting approaches modeled spindle power tiers, axis configuration categories, and control architecture generations alongside end-use verticals spanning aerospace turbine casing manufacturers, automotive powertrain machining lines, and wind turbine nacelle housing producers. CAGRs were derived from equipment replacement cycle analysis and capital expenditure intensity ratios across the projection horizon. Industry-specific forecast inputs included direct-drive torque motor adoption curves and cybersecurity certification lag times against evolving IEC 62443 standards.
Several conditions sit outside the modeled scope, including unannounced tariff modifications on machine tool imports, abrupt nickel or molybdenum price spikes beyond historical volatility bands, and force majeure disruptions to Asian production concentration. Forecasts reflect assumptions about sustained aerospace capital expenditure expansion and continued German automotive supplier ecosystem density. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
2D Laser Cutting Machine Market
Tools
Machine Vise Market
Tools
Europe Machine Tools Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Diamond Hole Saw Market
Tools
Ripper Market
Tools
Rivet Busters Market
Tools
Impact Sockets Market
Tools
Floor Polishing Machine Market
Tools
Screw Fastener Market
Tools
Key Cutting Machine Market
Tools
Leather Embossing Machine Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Construction Anchors Market
Tools
Drill Presses Market
Tools
Nail Gun Market