
 Screw Compressor Rental Market | 2026-2036
Screw Compressor Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Screw Compressor Rental Market Outlook
Midstream energy operators is rotating toward rental screw compressors as capital discipline overrides equipment ownership preferences across North American shale plays. Atlas Copco dominates portable compression technology leadership through its oil-free and diesel-electric hybrid portfolios. United Rentals sustains North American channel control via the industry's densest branch network and same-day deployment capability. Kaeser Kompressoren anchors European rental density with factory-maintained fleets and energy-efficiency guarantees.
A screw compressor rental delivers positive-displacement gas compression through intermeshing helical rotors, typically achieving discharge pressures from 100 to 250 psig in industrial process and temporary plant service applications. Oil and gas applications command the largest current revenue pool due to continuous demand for gas gathering and processing redundancy, while emergency service type segments represent the fastest-expanding margin opportunity as weather-driven grid instability and unplanned outage events intensify. Medium power rating units occupy the structural center of rental fleets, balancing transportability against the coverage threshold for most construction and manufacturing temporary air demands.
EPA New Source Performance Standards and OSHA respiratory air quality regulations jointly compel fleet renewal toward low-emission prime movers and instrument-grade output certification across US rental operations. In Europe, CE machinery directives and the EU F-Gas Regulation restrict refrigerant-lubricant chemistries and mandate leak detection protocols for portable compression equipment. Stakeholders must weigh fleet decarbonization pathways against utilization economics as regulatory compliance timelines compress and customer sustainability scorecards harden into contract prerequisites.
Market Dynamics
Capital discipline among shale operators is compressing equipment ownership cycles and accelerating rental adoption for temporary compression needs. This structural preference for operational flexibility over fixed asset exposure now governs fleet procurement decisions across upstream and midstream energy segments.
Growth Catalysts
- EPA New Source Performance Standards:Emissions mandates in the United States are forcing fleet turnover toward Tier 4 Final and electric-hybrid prime movers, expanding addressable rental demand for compliant units.
- Permian Basin drilling volatility:Well completion timing uncertainty in West Texas and southeastern New Mexico makes rental compression the preferred hedge against capital commitment risk.
- Instrument air certification:Food processing and pharmaceutical end-users require oil-free screw compressor output meeting ISO 8573-1 Class 0 standards, pulling specialized rental fleet investment.
Market Restraints
- Diesel engine supply concentration:Dependence on a limited supplier base for EPA-certified prime movers creates procurement bottlenecks and extended lead times for rental fleet expansion.
- Steel alloy input volatility:Rotor machining requires specialized nickel-chromium-molybdenum steel grades subject to commodity price swings that compress rental margin predictability.
- Pipeline quality specification friction:Variability in gas gathering pipeline inlet pressure requirements across shale plays forces redundant fleet configuration and underutilization risk.
Strategic Opportunities
- Carbon capture retrofit demand:Post-combustion capture projects in the US Gulf Coast require temporary CO2 compression, opening rental penetration into power generation and cement manufacturing.
- EU F-Gas Regulation phase-down:Refrigerant restrictions are accelerating demand for air-cooled screw compressors in European process cooling applications previously served by refrigerant-based systems.
- Telematics-enabled predictive maintenance:Integration of vibration monitoring and oil analysis sensors allows rental providers to guarantee uptime and command premium pricing against traditional time-based service models.
Industry Challenges
- Rotor profile grinding specialization:Precision machining of asymmetric screw profiles requires skilled technicians with five-plus years of apprenticeship, constraining in-house maintenance capacity expansion.
- Multi-jurisdictional transport permitting:Oversized load classification for units above 500 horsepower triggers state-by-state variance in escort requirements and route restrictions, complicating rapid deployment logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screw Compressor Rental Market |
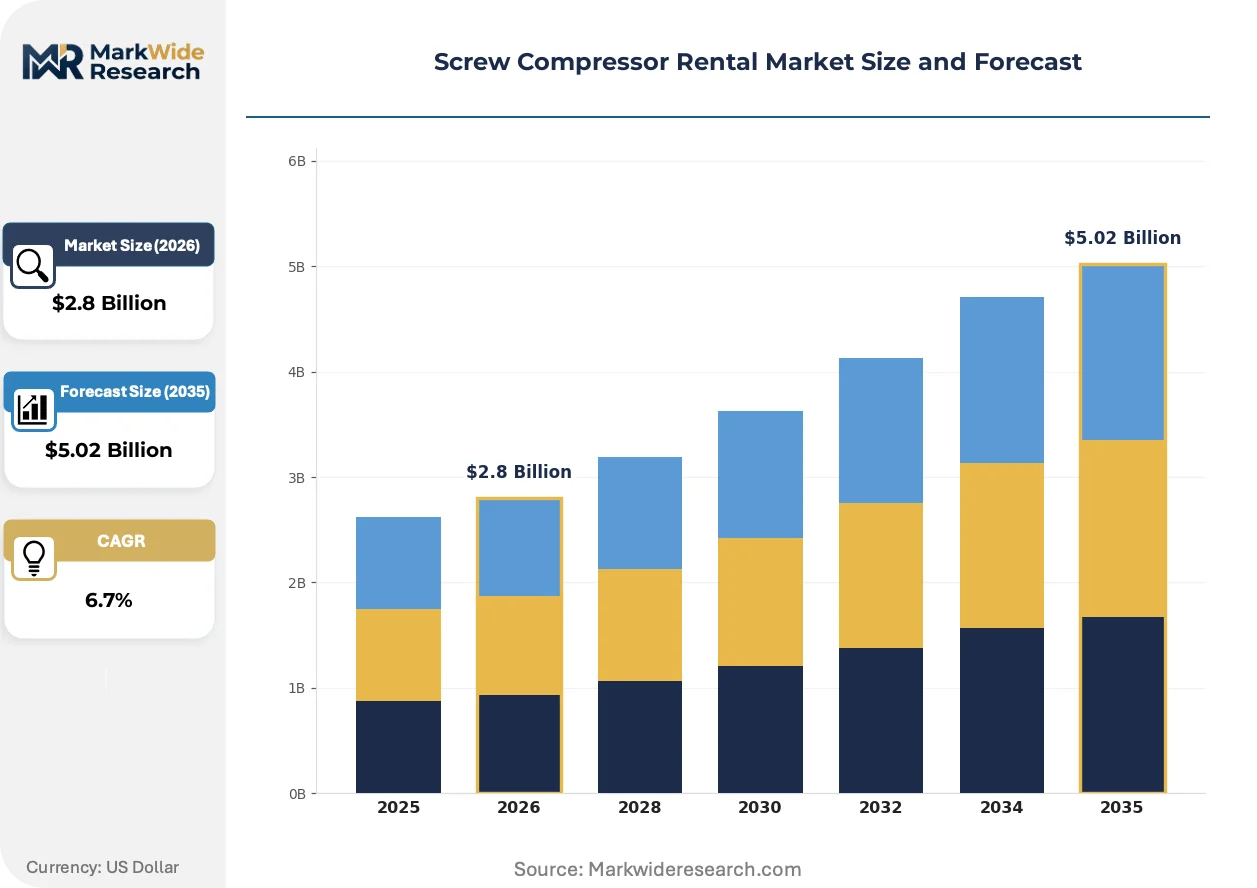
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Construction, Oil & Gas, Mining, Manufacturing End User: Industrial, Commercial, Residential, Government Service Type: Short-Term, Long-Term, Emergency, Seasonal Power Rating: Low, Medium, High, Ultra-High |
| Companies Covered | Atlas Copco, United Rentals, Ingersoll Rand, Caterpillar, Kaeser Kompressoren, Aggreko, Sullair, Gardner Denver, Ashtead Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screw Compressor Rental Market Strategic Shifts
Diesel-electric hybrid architecture is rewriting the economics of portable compression, enabling variable-speed operation that cuts fuel consumption during partial-load conditions. This technological pivot is compressing the total cost gap between rental and ownership models.
Permanent magnet motor integration with variable frequency drives is supplanting traditional fixed-speed induction motor configurations in medium-duty rental fleets. Midstream operators in the Marcellus and Utica shale corridors are specifying these packages for gas gathering redundancy. The technology is supplanting conventional load-unload control strategies and extending maintenance intervals by reducing mechanical contact wear.
EPA greenhouse gas reporting requirements for stationary combustion sources are tightening monitoring obligations for rental compressors deployed beyond ninety days. Operators must now install continuous emissions monitoring systems or conduct quarterly stack testing, adding compliance overhead that favors newer fleet vintages. The Permian Basin and Bakken formation see the highest enforcement density, pushing rental customers toward 2020-model-year or newer equipment.
Equipment-as-a-service contracting is replacing traditional dry-hire arrangements in manufacturing and construction verticals. Rental providers now bundle compressed air audits, energy optimization, and guaranteed output specifications into multi-year agreements. Germany and the Netherlands show the deepest penetration of this model, driven by industrial customer preferences for converting capital expenditures to operational line items.
Screw Compressor Rental Market Segmentation
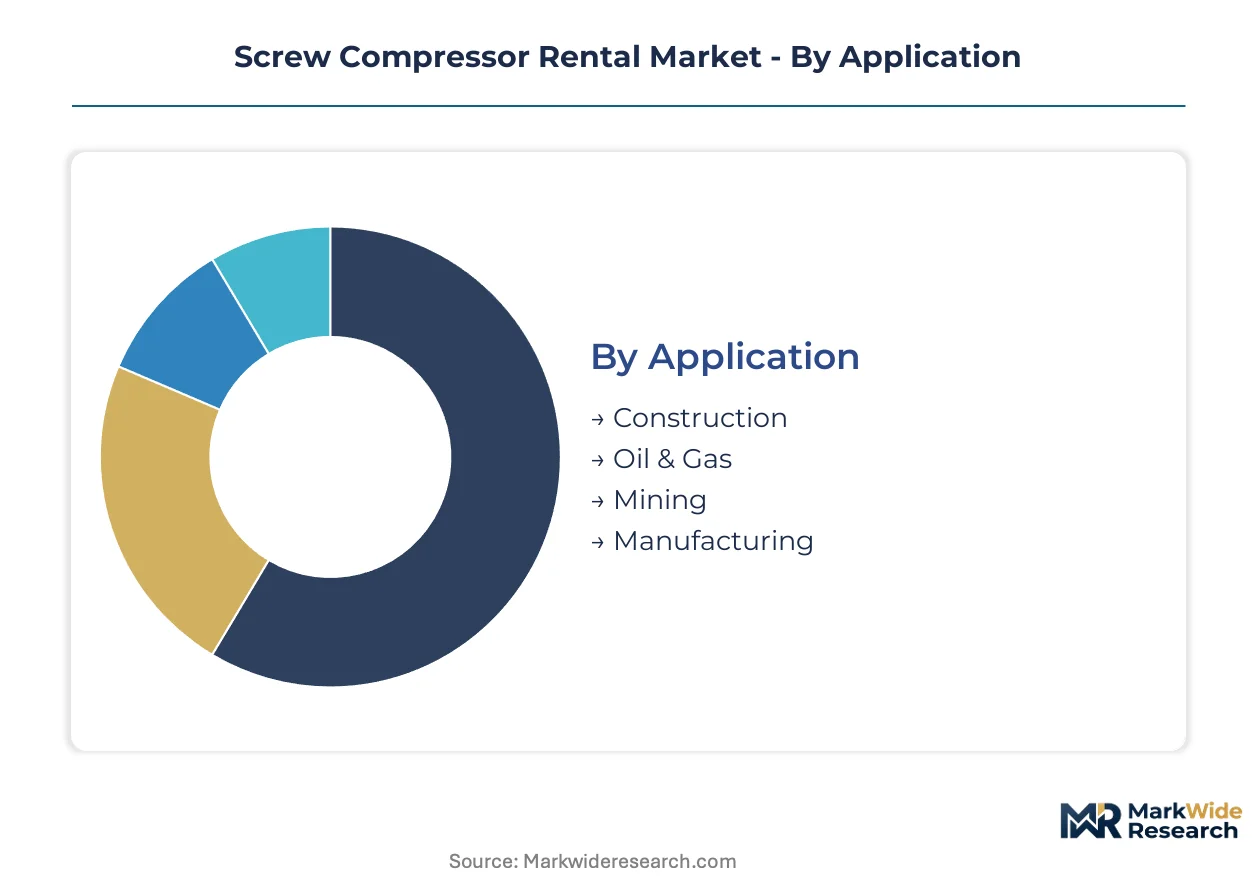
Screw compressor rental demand fragments across application intensity, customer sophistication, service urgency, and unit scale. Each dimension shapes fleet configuration, pricing architecture, and deployment logistics differently.
Application:
Substitute pressure concentrates in construction and manufacturing, where portable diesel units face displacement from electric-hybrid alternatives and fixed installation economics.
- Oil & Gas:Continuous-duty gas gathering and processing redundancy commands the deepest rental penetration. Permian Basin operators deploy medium-to-high power units for well maintenance and pipeline integrity projects where capital avoidance outweighs ownership returns.
- Construction:Pneumatic tool air supply and shotcrete operations drive short-cycle demand. Diesel-electric hybrid units are compressing total cost gaps against ownership as EPA Tier 4 Final compliance costs escalate.
- Mining:Underground ventilation and refuge chamber air systems require explosion-proof configurations. Australian and South African hard-rock operations specify these for regulatory compliance.
- Manufacturing:Temporary plant expansion and outage coverage pull oil-free units for instrument air. Food processing and pharmaceutical end-users mandate ISO 8573-1 Class 0 certification.
Oil & Gas retains volume leadership; Manufacturing holds the steepest expansion curve.
End User:
Cost tier stratification separates industrial procurement sophistication from commercial price sensitivity and residential fragmentation.
- Industrial:Multi-year equipment-as-a-service contracts predominate. German and Dutch manufacturing customers bundle compressed air audits and energy optimization into operational expenditure conversions.
- Commercial:HVAC contractors and facility managers prioritize same-day deployment over specification depth. United Rentals' branch density captures this segment through logistics superiority.
- Residential:Limited to specialty applications like geothermal drilling and pool construction. Seasonal demand spikes concentrate in Florida and California construction corridors.
- Government:Infrastructure stimulus and emergency response procurement favor certified small-business vendors. FEMA disaster relief specifications drive oil-free requirements for temporary medical facilities.
Industrial customers anchor fleet utilization; Government procurement is expanding most quickly through infrastructure appropriations.
Service Type:
Margin concentration follows urgency gradient, with emergency and seasonal premiums offsetting utilization volatility.
- Emergency:Unplanned outage response commands 40-60% rate premiums. Weather-driven grid instability in Texas and California intensifies demand for guaranteed uptime contracts with telematics monitoring.
- Short-Term:Project-based deployment for construction and maintenance windows. Atlas Copco's portable diesel-electric hybrids dominate this segment through fuel efficiency at partial load.
- Long-Term:Multi-year agreements for manufacturing and midstream gas processing. Kaeser Kompressoren's factory-maintained fleets with energy-efficiency guarantees secure European share.
- Seasonal:Agricultural harvest compression and summer cooling peak demand. Revenue predictability challenges require geographic diversification across hemispheres.
Long-Term contracts stabilize fleet economics; Emergency service claims the highest margin expansion trajectory.
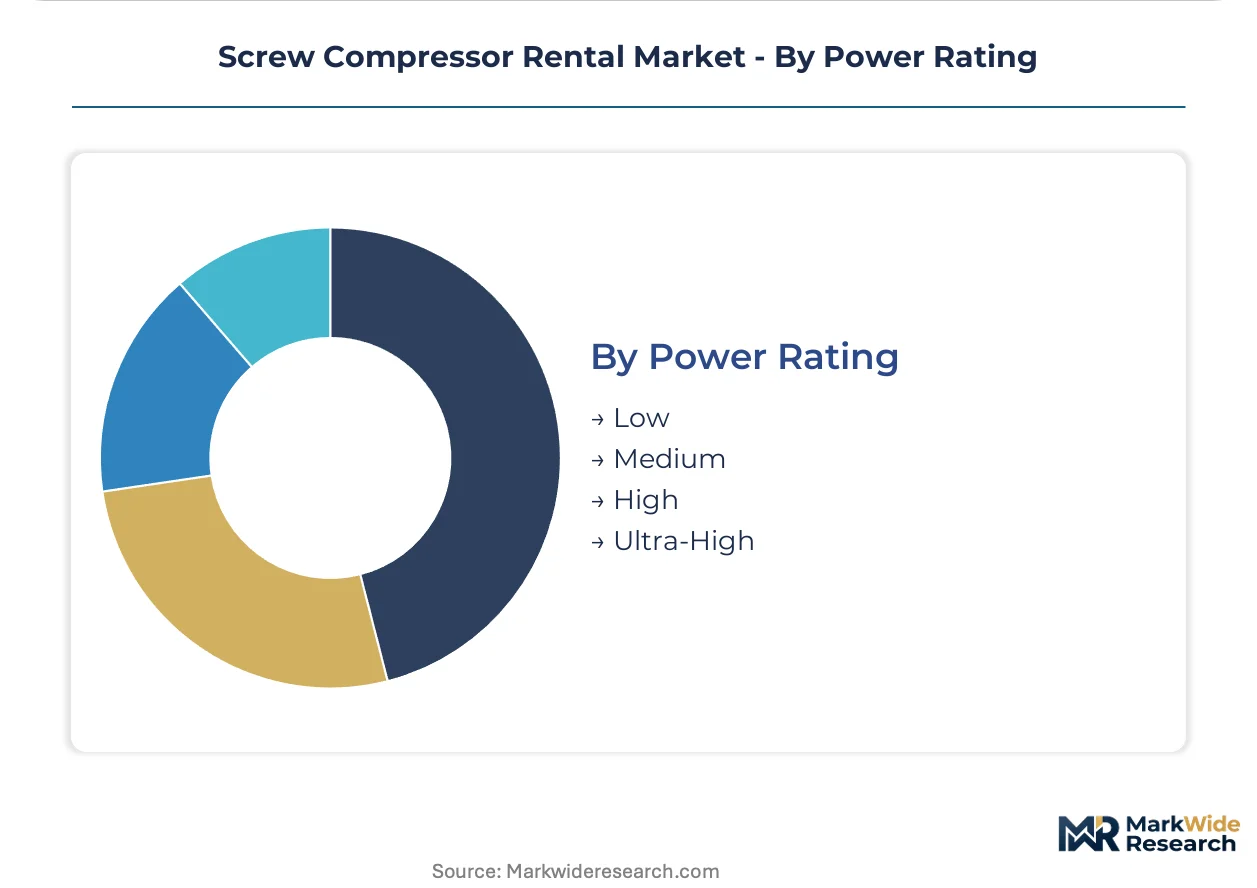
Power Rating:
Supply concentration in medium-duty units creates bottleneck risk as demand polarizes toward efficiency-optimized ends of the spectrum.
- Medium:Structural center of rental fleets balancing transportability against coverage threshold. Marcellus and Utica shale operators specify permanent magnet motor with variable frequency drive configurations for gas gathering redundancy.
- High:Pipeline compression and carbon capture retrofit applications. Post-combustion CO2 compression in US Gulf Coast power generation requires these units for temporary project phases.
- Low:Light construction and municipal maintenance. Electric portability and noise restrictions govern specification in European urban environments.
- Ultra-High:Specialized industrial process and offshore platform service. Multi-jurisdictional transport permitting for units above 500 horsepower complicates rapid deployment logistics.
Medium power rating retains fleet dominance; High power rating is gaining share fastest through energy transition infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German rental fleets export oil-free compression packages to Dutch process manufacturers under long-term equipment-as-a-service contracts. This trade corridor exemplifies how regulatory harmonization under EU machinery directives accelerates cross-border fleet standardization.
United States
Permian Basin shale operators deploy medium-to-high power units for well maintenance and pipeline integrity projects where capital avoidance outweighs ownership returns. EPA New Source Performance Standards force fleet turnover toward Tier 4 Final and electric-hybrid prime movers. West Texas drilling corridors concentrate rental demand volatility.
Germany
Industrial manufacturing customers bundle compressed air audits and energy optimization into operational expenditure conversions. CE machinery directives and EU F-Gas Regulation restrict refrigerant-lubricant chemistries for portable compression equipment. Ruhr industrial clusters anchor factory-maintained fleet density with efficiency guarantees.
China
Construction and manufacturing expansion drives short-cycle demand for portable diesel-electric hybrid units. National dual carbon goals and GB standards tighten emissions monitoring for stationary combustion sources deployed beyond ninety days. Yangtze River Delta manufacturing corridors specify permanent magnet motor configurations.
Netherlands
Process cooling applications accelerate demand for air-cooled screw compressors previously served by refrigerant-based systems. EU F-Gas Regulation phase-down mandates leak detection protocols for portable equipment. Rotterdam industrial zones convert capital expenditures to operational line items through multi-year service agreements.
Australia
Hard-rock mining operations specify explosion-proof configurations for underground ventilation and refuge chamber air systems. National workplace safety regulators enforce respiratory air quality standards comparable to OSHA mandates. Western Australian mineral extraction corridors drive specialized fleet investment.
Screw Compressor Rental Market Competitive Environment
Listed leaders compete with private specialists across capital access and fleet flexibility dimensions. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates with captive rental divisions, pure-play equipment rental specialists with dense branch networks, and factory-anchored compressor manufacturers with vertically integrated service arms. Consolidation pressure intensifies as telematics-enabled predictive maintenance creates scale advantages in uptime guarantee pricing. Geographic expansion and portfolio diversification toward carbon capture and hydrogen infrastructure represent the dominant competitive moves.
Within the factory-anchored manufacturer tier, Atlas Copco and Kaeser Kompressoren exemplify European engineering heritage applied to rental fleet energy efficiency. United Rentals occupies a position as the North American channel archetype, with branch density enabling same-day deployment velocity that manufacturing and commercial customers prioritize. Ingersoll Rand represents the diversified industrial conglomerate model, where compression technology sits within broader mission-critical flow solutions.
| Leading Market Players |
|---|
| Atlas Copco |
| United Rentals |
| Ingersoll Rand |
| Caterpillar |
| Kaeser Kompressoren |
| Aggreko |
| Sullair |
| Gardner Denver |
| Ashtead Group |
| Others |
Value Chain & Pricing Dynamics
Long-term equipment-as-a-service contracts lock in supply access for industrial end-users while compressing price visibility into fixed operational expenditure line items. This contracting pattern concentrates pricing power with factory-anchored rental providers who bundle energy-efficiency guarantees and factory-maintained fleet commitments.
Pricing Analysis
Next-generation diesel-electric hybrid units command rental premiums against fixed-speed induction motor fleets nearing obsolescence. Three-tier pricing structure across premium, standard, and economy levels separates oil-free ISO 8573-1 Class 0 certified packages from general industrial instrument air and basic construction pneumatics. Cost compression in economy-tier diesel units is intensifying because EPA Tier 4 Final compliance escalates ownership economics. Commercial HVAC contractors and facility managers exhibit highest price sensitivity, prioritizing same-day deployment velocity over specification depth.
Supply Chain Analysis
Port congestion on Asia-North America trade lanes elevates inbound logistics costs for permanent magnet motor and variable frequency drive components sourced from East Asian manufacturing hubs. Precision rotor machining draws from specialized nickel-chromium-molybdenum steel grades concentrated in Germany, Japan, and South Korea. Single-source vulnerability for EPA-certified prime mover engines creates procurement bottlenecks extending fleet expansion timelines. Distribution runs through dense branch networks for rapid deployment velocity and factory-direct service arms for uptime guarantee contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Screw compressor rental demand tracks upstream drilling cycle recovery, with Permian Basin completion volatility creating counter-cyclical rental preference during capital discipline phases.
For Market Incumbents: Secure factory-maintained fleet density in Marcellus and Utica shale corridors where permanent magnet motor configurations are displacing conventional load-unload control strategies. Anchor channel control through telematics-enabled predictive maintenance capabilities that guarantee uptime against emerging equipment-as-a-service competitors. Deepen backward integration into rotor profile grinding specialization to constrain in-house maintenance capacity expansion by rivals. For New Entrants and Emerging Players: EPA New Source Performance Standards certification fast-track opens white-space penetration in carbon capture retrofit demand across US Gulf Coast power generation and cement manufacturing. Target government infrastructure stimulus procurement where certified small-business vendor status and FEMA disaster relief specifications favor oil-free requirements for temporary medical facilities. Deploy telematics bundling as primary go-to-market angle against established time-based service models. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among factory-anchored compressor manufacturers with vertically integrated service arms and energy-efficiency guarantee contracts. Long-term viability across the projection horizon favors acquisition targets with dense European rental fleet positions under EU F-Gas Regulation compliance and leak detection protocol mandates. Monitor diesel engine supply concentration as inflection indicator for rental fleet expansion capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics-Enabled Predictive Maintenance | Vibration monitoring and oil analysis sensors allow uptime guarantees commanding premium pricing against traditional service models. |
| Permanent Magnet Motor Fleet Conversion | Variable frequency drive integration extends maintenance intervals by reducing mechanical contact wear in Marcellus gas gathering. |
| Carbon Capture Retrofit Rental Positioning | Post-combustion CO2 compression projects in US Gulf Coast power generation open rental penetration beyond traditional oil and gas. |
| Equipment-as-a-Service Contract Expansion | Compressed air audits and energy optimization bundling converts capital expenditures to operational line items in German manufacturing. |
| Factory-Maintained Fleet Density Buildout | Ruhr industrial clusters anchor efficiency-guaranteed rental share against diversified conglomerate competitors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of EPA enforcement databases, OSHA regulatory filings, and EU machinery directive implementation records. Primary interviews engaged rental fleet managers at oil and gas operators, maintenance directors at midstream energy companies, plant engineers at food processing facilities, and aftermarket service heads at compressor OEMs. Secondary validation drew from SEC 10-K equipment rental disclosures, customs trade data on compressor component imports, and FERC filings for pipeline integrity project timelines. Bottom-up unit deployment estimates triangulate against top-down addressable market sizing across application segments.
Segmentation dimensions modeled include power rating tier, service type urgency gradient, end-user procurement sophistication, and application intensity across oil and gas, construction, mining, and manufacturing verticals. CAGRs derive from regression analysis of fleet utilization rates, rental penetration trends by customer archetype, and regulatory compliance-driven replacement cycles. Industry-specific forecast inputs incorporate Permian Basin drilling volatility indices and EPA greenhouse gas reporting threshold triggers for stationary combustion sources.
Underlying assumptions cover sustained capital discipline among shale operators and phased implementation of EU F-Gas Regulation restrictions, with deviation risk concentrated in diesel engine supply chain disruptions and nickel-chromium-molybdenum alloy price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Construction Pump Market
Construction Equipment
Crossover Ladder Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Hand Push Trencher Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Japan Waterjet Cutting Machines Market
Construction Equipment
Baler Market
Construction Equipment
Industrial and Commercial Floor Scrubbers Market
Construction Equipment
Plasma Cutting Machine Market
Construction Equipment
Bale Openers Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
Bucket Elevator Market
Construction Equipment
UK Heavy Construction Equipment Rental Market
Construction Equipment
Hose End Sprayers Market