
 Computer-Aided Oral and Maxillofacial Surgery Market | 2026-2036
Computer-Aided Oral and Maxillofacial Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Computer-Aided Oral and Maxillofacial Surgery Market Analysis
The capability gap between high-R&D platform developers and hardware-assembly competitors is unwinding competitive stability in computer-aided oral and maxillofacial surgery. Stryker Corporation leverages its orthopedic robotics heritage to anchor integrated navigation-to-implant workflows. Dentsply Sirona sustains dominance in digital dentistry channels that feed surgical planning software adoption. Zimmer Biomet Holdings competes through specialized maxillofacial reconstruction portfolios that bridge preoperative simulation with intraoperative guidance.
Computer-aided oral and maxillofacial surgery encompasses image-guided planning, robotic-assisted execution, and patient-specific implant fabrication for craniofacial procedures, relying on submillimeter registration accuracy between CT/CBCT datasets and surgical instruments. Its primary purpose is to reduce operative time, minimize iatrogenic nerve injury, and improve occlusal outcomes in complex jaw reconstructions. Surgical navigation systems occupy the largest revenue pool due to capital equipment replacement cycles in tertiary hospitals, while 3D printing solutions represent the fastest-expanding segment as point-of-care titanium implant manufacturing gains regulatory traction. Artificial Intelligence applications in automated nerve canal segmentation are displacing manual radiologist annotation, compressing preoperative planning timelines.
FDA 510(k) pathways govern surgical navigation software and patient-specific instrumentation in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for AI-assisted planning algorithms entering European markets. Japan's PMDA evaluates robotic surgical assistants under accelerated review frameworks, shaping how manufacturers prioritize registration strategies. Stakeholders must monitor evolving software-as-a-medical-device classifications across jurisdictions to determine whether cloud-based surgical planning platforms trigger additional conformity assessment obligations.
Market Dynamics
AI-assisted nerve segmentation is compressing preoperative planning timelines from hours to minutes, forcing surgical navigation vendors to reengineer software architectures around automated anatomical recognition rather than manual radiologist annotation.
Growth Catalysts
- FDA 510(k) Acceleration:Streamlined clearance pathways for AI-assisted surgical planning software reduce time-to-market for navigation platform upgrades, incentivizing R&D investment in automated segmentation algorithms.
- Orthognathic Procedure Volume:Hospitals in the United States, Germany, and Japan are expanding surgical navigation system deployment for complex jaw reconstructions, creating sustained capital equipment demand.
- Point-of-Care Manufacturing:Tertiary medical centers are installing electron beam melting systems for titanium implant fabrication, collapsing lead times between preoperative simulation and intraoperative implant placement.
Market Restraints
- Capital Equipment Intensity:Surgical navigation systems require multimillion-dollar installation commitments, constraining adoption to academic medical centers and excluding community hospitals.
- EU MDR Compliance Burden:Stricter clinical evidence requirements for AI-assisted planning algorithms create registration friction and delay European market entry relative to FDA pathways.
- Specialized Surgeon Shortage:Limited fellowship-trained oral and maxillofacial surgeons capable of operating navigation platforms restricts addressable procedure volume despite hardware availability.
Strategic Opportunities
- Cloud-Based SaaS Platforms:Browser-based surgical planning tools bypass on-premise hardware requirements, opening community hospital and ambulatory surgery center segments previously excluded by capital constraints.
- Japan PMDA Fast-Track:Accelerated review frameworks for robotic surgical assistants enable earlier market positioning for manufacturers prioritizing Asian regulatory strategy.
- Bioresorbable Implant Convergence:Integration of patient-specific 3D printing with magnesium alloy materials creates differentiation in pediatric craniofacial reconstruction where permanent metal implants are contraindicated.
Industry Challenges
- Submillimeter Registration Accuracy:Maintaining precision between CBCT datasets and surgical instruments demands continuous calibration protocols that strain operating room workflow efficiency.
- Cross-Platform Interoperability:Proprietary data formats between imaging systems, planning software, and navigation hardware create integration friction requiring costly custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer-Aided Oral and Maxillofacial Surgery Market |
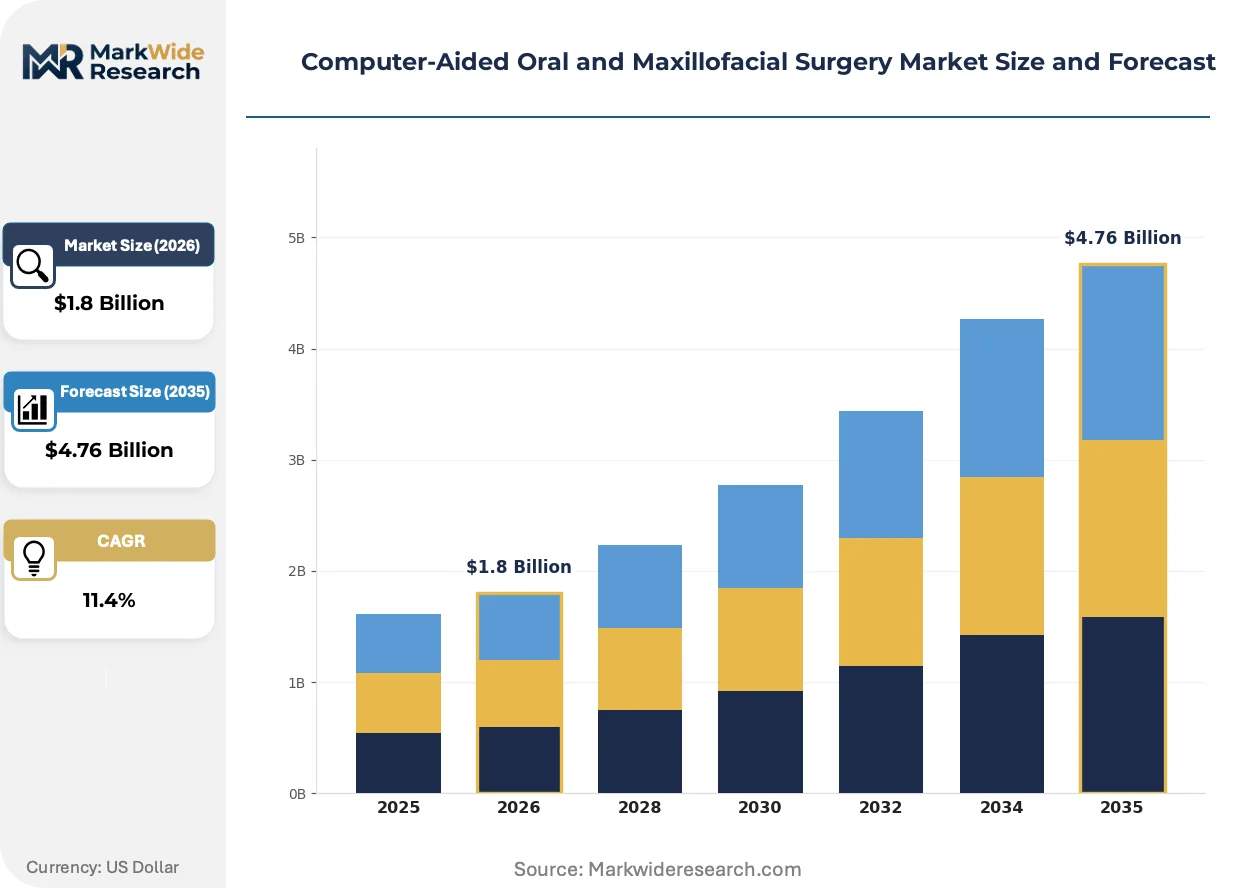
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Navigation Systems, Imaging Devices, 3D Printing Solutions, Simulation Software End User: Hospitals, Dental Clinics, Research Institutes, Ambulatory Surgical Centers Technology: Augmented Reality, Computer Vision, Artificial Intelligence, Robotics Application: Orthognathic Surgery, Trauma Surgery, Reconstructive Surgery, Tumor Resection |
| Companies Covered | Stryker Corporation, Dentsply Sirona, 3M Corporation, Straumann Group, Align Technology, Medtronic, Zimmer Biomet Holdings, Integra LifeSciences Corporation, Danaher Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer-Aided Oral and Maxillofacial Surgery Market Emerging Trajectories
Three converging forces are restructuring how surgical planning translates into operative execution: hardware miniaturization, regulatory recalibration for software-as-device, and procurement model fragmentation across hospital tiers.
Intraoperative optical tracking arrays are miniaturizing from room-mounted stereo cameras to headset-integrated sensors. Ambulatory surgery centers lacking dedicated navigation suites are adopting these compact systems for orthognathic procedures. The form factor reduction is miniaturizing the economic threshold for navigation adoption, compressing the historical hospital-only addressable market into outpatient settings.
EU MDR Article 10 clinical evaluation requirements are tightening evidentiary standards for AI-assisted segmentation algorithms. Manufacturers must now submit prospective clinical data rather than retrospective validation studies for software updates. European oral surgery departments are delaying procurement cycles until vendors complete MDR technical documentation, slowing replacement demand relative to FDA-cleared markets.
Service-based contracting is displacing capital purchase models for surgical navigation platforms. Health systems in Germany are unbundling hardware acquisition from per-procedure software licensing, transferring technology obsolescence risk to vendors. This consumption-pattern shift pressures platform developers to engineer modular architectures supporting continuous feature deployment without hardware replacement.
Computer-Aided Oral and Maxillofacial Surgery Market Segmentation
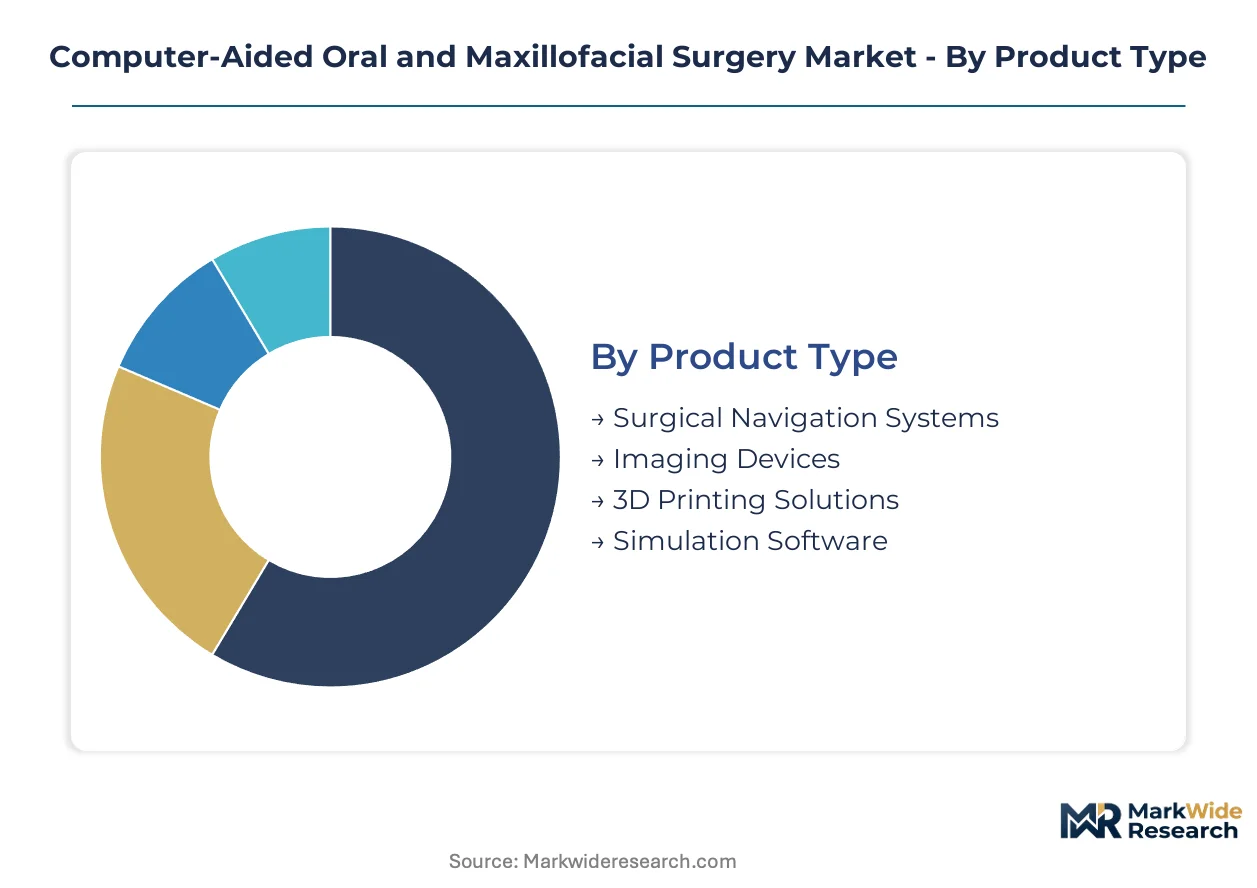
Computer-aided oral and maxillofacial surgery markets fragment across hardware, software, and service layers with distinct procurement cycles and customer concentration patterns. Understanding these divisions reveals where capital intensity blocks adoption versus where cloud delivery models unlock new customer tiers.
Product Type:
Surgical navigation systems concentrate demand in tertiary hospitals across the United States, Germany, and Japan, while 3D printing solutions attract export-led growth from European and Asian manufacturing hubs.
- Surgical Navigation Systems:Optical and electromagnetic tracking platforms requiring submillimeter registration accuracy between CBCT datasets and surgical instruments. Demand clusters in academic medical centers performing complex orthognathic reconstructions, constrained by multimillion-dollar capital commitments that exclude community hospitals.
- 3D Printing Solutions:Electron beam melting and selective laser sintering systems for patient-specific titanium implant fabrication. Point-of-care manufacturing at tertiary centers in Switzerland and South Korea is collapsing lead times between simulation and implant placement, driving fastest segment expansion.
- Imaging Devices:CBCT scanners and intraoral scanners supplying DICOM datasets to planning software.
- Simulation Software:Preoperative planning platforms with automated nerve segmentation capabilities.
Surgical Navigation Systems holds the largest share; momentum sits with 3D Printing Solutions.
End User:
Procurement authority and reimbursement pathways shape distinct technology requirements across facility types, with hospital systems dominating capital equipment decisions.
- Hospitals:Tertiary academic centers with dedicated oral and maxillofacial surgery departments. United States health systems leverage bundled payment models for orthognathic procedures to justify navigation system investments, while German hospitals adopt service-based contracting to transfer obsolescence risk.
- Ambulatory Surgical Centers:Outpatient facilities adopting miniaturized optical tracking arrays for jaw reconstruction procedures. Compact form factors and headset-integrated sensors in Japan and the Netherlands are compressing the economic threshold for navigation adoption outside traditional hospital settings.
- Dental Clinics:Private practices referring complex cases or acquiring simulation software for treatment planning.
- Research Institutes:University hospitals validating AI-assisted segmentation algorithms and bioresorbable implant materials.
Hospitals command the dominant revenue pool; Ambulatory Surgical Centers are expanding most quickly.
Technology:
Regulatory classification divergence across FDA, EU MDR, and Japan PMDA frameworks determines which technology categories face accelerated versus burdened market entry.
- Artificial Intelligence:Automated nerve canal segmentation and anatomical recognition algorithms displacing manual radiologist annotation. FDA 510(k) streamlined pathways enable rapid deployment in the United States, while EU MDR Article 10 clinical evaluation requirements impose prospective data submission obligations that delay European commercialization.
- Robotics:Surgical assistants for implant placement and bone resection procedures. Japan PMDA accelerated review frameworks prioritize registration for manufacturers targeting Asian markets, creating regulatory arbitrage opportunities against slower European pathways.
- Augmented Reality:Headset-based intraoperative visualization overlaying planning data onto the surgical field.
- Computer Vision:Optical tracking and pattern recognition enabling instrument navigation without mechanical guides.
Artificial Intelligence captures the steepest expansion trajectory; Robotics benefits from favorable Asian regulatory positioning.
Application:
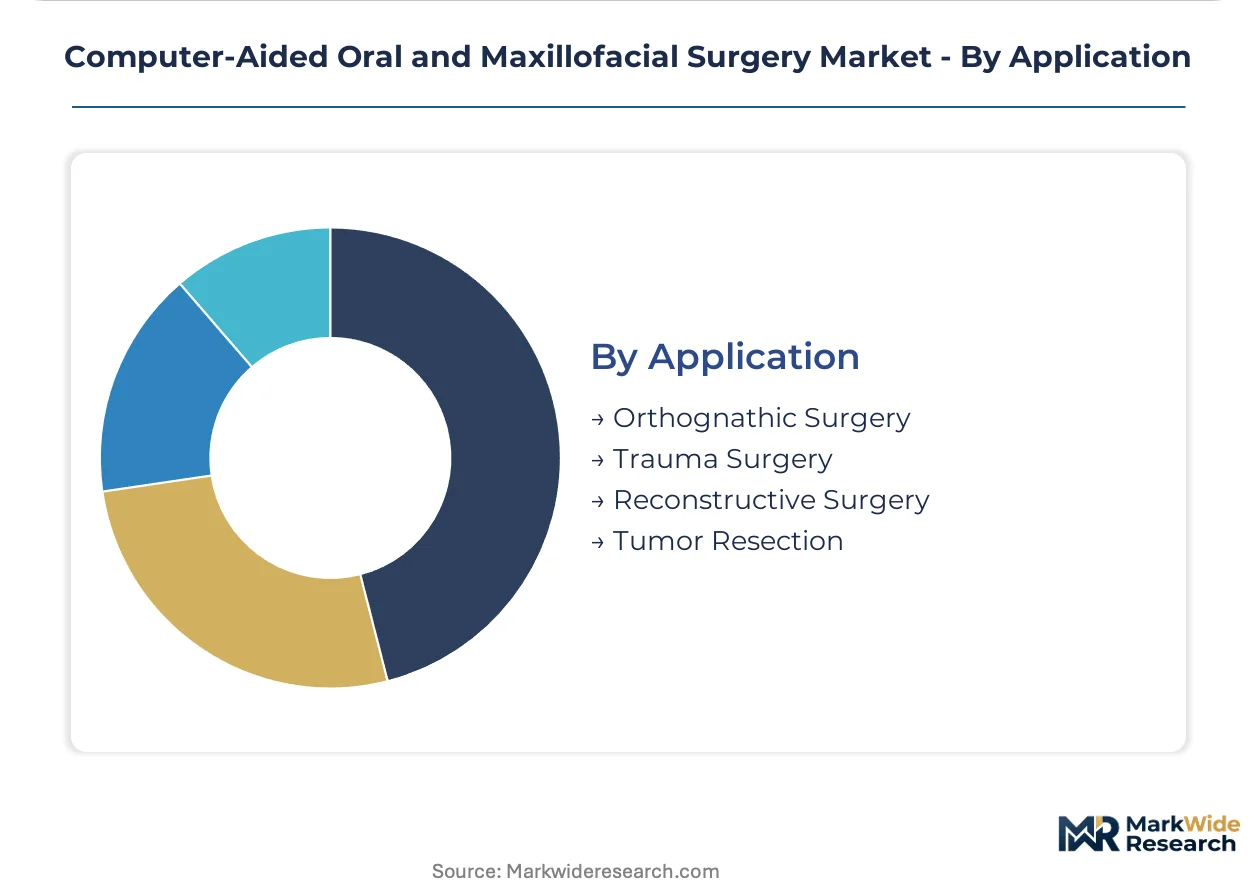
Procedure complexity and reimbursement generosity determine technology penetration rates, with elective reconstructions supporting premium system deployment over emergency interventions.
- Orthognathic Surgery:Corrective jaw procedures requiring precise occlusal outcomes and nerve preservation. German and Japanese hospitals are expanding navigation system deployment for these planned reconstructions, where preoperative simulation time justifies capital investment through reduced operative duration and complication rates.
- Reconstructive Surgery:Craniofacial restoration following trauma or congenital defects. Patient-specific 3D printed titanium implants from point-of-care manufacturing in Swiss and South Korean centers are displacing standard plate systems in complex orbital and mandibular reconstructions.
- Trauma Surgery:Emergency fracture repair with limited preoperative planning windows.
- Tumor Resection:Oncologic procedures requiring margin assessment and immediate reconstruction planning.
Orthognathic Surgery anchors current revenue concentration; Reconstructive Surgery is gaining share fastest through implant personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing hubs in Switzerland and South Korea shipping patient-specific titanium implants to deficit markets in North America and Western Europe. Capital equipment flows concentrate from German and Japanese precision engineering centers toward tertiary hospital systems in the United States and emerging Asian medical centers.
United States
FDA 510(k) streamlined pathways for AI-assisted surgical planning software attract navigation system vendors prioritizing rapid commercialization. Academic medical centers in Boston and New York Metro deploy bundled payment models for orthognathic procedures to justify multimillion-dollar capital investments. The Cleveland Clinic and Mayo Clinic anchor validation networks for automated nerve segmentation algorithms.
Germany
Service-based contracting for surgical navigation platforms transfers technology obsolescence risk from hospitals to vendors in Baden-Württemberg and Bavaria. EU MDR Article 10 clinical evaluation requirements delay procurement cycles until technical documentation completes. The Stuttgart medical technology cluster concentrates electron beam melting systems for point-of-care titanium implant manufacturing.
Japan
PMDA accelerated review frameworks for robotic surgical assistants enable earlier market positioning against slower European regulatory pathways. Tokyo and Osaka metropolitan hospitals expand navigation system deployment for planned orthognathic reconstructions. The Nagoya medical device corridor specializes in compact optical tracking arrays for ambulatory surgery center adoption.
Switzerland
Precision manufacturing heritage supports patient-specific 3D printed titanium implant exports to craniofacial reconstruction centers globally. Swissmedic maintains alignment with EU MDR standards while preserving faster conformity assessment timelines. The Lake Geneva region clusters electron beam melting facilities serving European and Middle Eastern hospital networks.
South Korea
Government-backed medical device innovation programs accelerate domestic navigation platform development for regional export. Seoul National University Hospital and Samsung Medical Center validate point-of-care manufacturing workflows for complex mandibular reconstructions. The Pangyo Techno Valley hosts specialized 3D printing service bureaus integrating with Asian hospital supply chains.
Computer-Aided Oral and Maxillofacial Surgery Market Vendor Landscape
Concentration sits with diversified medical technology conglomerates leveraging orthopedic and dental heritage to anchor integrated surgical workflows. Three to five global players capture the majority of surgical navigation system revenue through established hospital procurement relationships. The vendor base stratifies across capital equipment manufacturers, digital dentistry platform developers, and specialized maxillofacial reconstruction suppliers. Dominant competitive moves include strategic partnerships between imaging device makers and planning software developers, plus geographic expansion through distributor networks in Asian markets.
Among diversified technology conglomerates, Stryker Corporation and Zimmer Biomet Holdings exemplify archetypes leveraging orthopedic robotics heritage to bridge navigation hardware with implant portfolios. Dentsply Sirona occupies a position representing digital dentistry channel dominance that feeds surgical planning software adoption. These three anchors illustrate how competitive positioning depends on pre-existing clinical relationships and integrated workflow capabilities rather than standalone technology features.
| Leading Market Players |
|---|
| Stryker Corporation |
| Dentsply Sirona |
| 3M Corporation |
| Straumann Group |
| Align Technology |
| Medtronic |
| Zimmer Biomet Holdings |
| Integra LifeSciences Corporation |
| Danaher Corporation |
| Others |
Supply Flow & Price Mechanics
Electron beam melting systems replacing conventional CNC machining for titanium implant fabrication simultaneously concentrate supply geography around Swiss and South Korean precision manufacturing clusters and compress per-unit implant pricing through collapsed lead times and reduced tooling overhead. This substitution dynamic reshapes how tertiary hospitals negotiate procurement contracts for patient-specific instrumentation.
Pricing Analysis
Tertiary hospital procurement committees anchor pricing negotiations for surgical navigation platforms through service-based contracting models that unbundle hardware acquisition from per-procedure software licensing. Three-tier pricing structure across premium navigation suites, standard optical tracking systems, and economy-grade simulation software reflects FDA 510(k) clearance tier and after-sales calibration service bundling. Cost compression in the standard tier is intensifying because German health systems transfer technology obsolescence risk to vendors through consumption-pattern contracting. Community hospital segments exhibit highest price sensitivity due to capital equipment intensity, while academic medical centers prioritize registration accuracy and vendor validation networks over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and Busan trade lanes elevates inbound logistics costs for electron beam melting powder feedstock and optical tracking array components sourced from German precision engineering centers and Japanese sensor manufacturers. Supply concentration rests on Switzerland, South Korea, and Germany for patient-specific titanium implant fabrication systems, with raw material dependencies spanning medical-grade titanium powder, electromagnetic tracking coils, and CBCT detector arrays. Single-source vulnerability in optical sensor supply from the Nagoya medical device corridor creates exposure to Japan METI export licensing protocols. Distribution runs through hospital GPO contracts and specialized dental equipment distributors serving ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital equipment replacement cycles in tertiary hospitals signal cyclical recovery momentum as deferred navigation system upgrades from EU MDR compliance delays release into procurement pipelines.
For Market Incumbents: Consolidate software architecture control through backward integration into automated nerve segmentation algorithm development, neutralizing the threat from AI-native planning platform entrants. Prioritize CE marking technical documentation completion to capture delayed European replacement demand. Anchor hospital procurement relationships through bundled service contracts that transfer calibration protocol liability from clinical engineering departments. For New Entrants and Emerging Players: FDA 510(k) streamlined pathways for AI-assisted segmentation algorithms open white-space entry into community hospital and ambulatory surgery center segments previously excluded by capital constraints. Target Japanese metropolitan hospitals through PMDA accelerated review frameworks for compact optical tracking arrays. Pursue software-as-a-medical-device positioning to bypass multimillion-dollar hardware installation barriers. For Investors and Strategic Acquirers: EU MDR Article 10 clinical evaluation requirements reshape the acquisition landscape toward vendors with completed prospective validation studies rather than retrospective algorithm training datasets. Five-to-ten year viability hinges on regulatory documentation depth rather than feature velocity alone. Monitor FDA 510(k) submission volumes for automated segmentation platforms as inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Streamlined pathways accelerate AI-assisted planning software deployment in United States academic medical centers. |
| CE Marking Pathway | EU MDR Article 10 compliance unlocks delayed procurement cycles in German and Swiss hospital systems. |
| Hospital System Partnership | Service-based contracting with Baden-Württemberg health networks transfers technology obsolescence risk to vendors. |
| Software Companion Development | Cloud-based SaaS platforms bypass capital equipment barriers for Japanese ambulatory surgery centers. |
| Reimbursement Strategy | Bundled payment models for orthognathic procedures justify navigation system investments in United States tertiary hospitals. |
Methodological Framework
Operator-level perspectives from oral and maxillofacial surgeons, hospital biomedical engineers, GPO contracts managers, and dental equipment procurement directors anchored the qualitative base. Primary interview data combined with secondary validation from FDA 510(k) filings, PMDA review documentation, EU MDR technical file databases, and hospital procurement system records. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data from German and Japanese precision engineering clusters.
Sensitivity analysis across automated segmentation algorithm adoption curves, EU MDR compliance timeline scenarios, and point-of-care manufacturing penetration rates informed the analytical framework. Segmentation dimensions modeled span product type, end-user facility tier, technology regulatory classification, and application complexity across the projection horizon. CAGRs derived from installed base replacement cycles and new system adoption elasticities, with specific inputs from orthognathic procedure volume trends and titanium implant personalization demand curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway efficiency, EU MDR documentation completion timelines, and fellowship-trained surgeon supply expansion would require recalibration. Forecasts reflect documented assumptions regarding health system capital allocation priorities and regulatory review velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Medical Radiation Detectors Market
Medical Devices
Kirschner Wires Market
Medical Devices
US Anti-Snoring Devices and Snoring Surgery Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
IV Therapy and Vein Access Devices Market
Medical Devices
US Anti-Blue Ray Myopia Lenses Market
Medical Devices
Patellar Implant Market
Medical Devices
Global Prefilled Auto Injectors Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Knee Walkers Market
Medical Devices
Inhaled Corticosteroid Device Market
Medical Devices
Australia Contraceptive Devices Market
Medical Devices
Nanotechnology in Medical Devices Market
Medical Devices
Rectal Catheters Market