
 US Anti-Blue Ray Myopia Lenses Market | 2026-2036
US Anti-Blue Ray Myopia Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
US Anti-Blue Ray Myopia Lenses Market Insights
California's SB-1472 digital wellness mandate for schools is restructuring procurement criteria for protective eyewear across district-level health programs. EssilorLuxottica SA leverages its coastal distribution hubs to sustain rapid fulfillment for West Coast optometry chains. Hoya Corporation anchors its US position through specialized myopia management protocols developed with pediatric ophthalmology networks. Nikon Corporation differentiates via proprietary high-index substrate formulations that reduce chromatic aberration in blue-filtering designs.
Anti-blue ray myopia lenses incorporate selective wavelength-attenuating dyes or vacuum-deposited interference coatings that block or absorb electromagnetic radiation between 380 and 500 nanometers while preserving luminous transmittance for visual acuity correction. Polycarbonate substrates dominate volume production due to inherent impact resistance and compatibility with spin-coating application of multi-layer optical stacks. Progressive lens designs capture expanding margin pools as presbyopic myopes seek unified correction for near-work and distance viewing. Online retail channels are accelerating fastest among distribution pathways, though eye clinics retain premium positioning for initial fittings and myopia progression monitoring.
FDA Center for Devices and Radiological Health oversight governs blue light blocking claims as medical device labeling, while FTC advertising standards scrutinize unsubstantiated retinal protection assertions in consumer marketing. State-level optometry boards in Texas and Florida enforce continuing education requirements for myopia control credentialing that indirectly shapes lens recommendation patterns. Stakeholders must monitor evolving ANSI Z80 standards for blue light filtration metrics and prepare for potential CMS consideration of myopia management as a covered pediatric vision benefit.
Market Dynamics
FDA Center for Devices and Radiological Health oversight of blue light blocking claims as medical device labeling is forcing manufacturers to restructure product certification workflows and substantiation protocols before market entry.
Growth Catalysts
- Screen exposure epidemiology:K-12 students and remote workers now average 6+ hours of daily near-work, expanding pediatric and occupational buyer segments with documented myopia progression risk.
- California SB-1472:This digital wellness mandate for schools is restructuring procurement criteria for protective eyewear across district-level health programs statewide.
- Polycarbonate substrate dominance:Inherent impact resistance and spin-coating compatibility for multi-layer optical stacks is accelerating volume production scalability.
Market Restraints
- Monomer supply concentration:Optical-grade polycarbonate resin production concentrates among three global chemical suppliers, exposing lens fabricators to input cost volatility and allocation risk.
- FDA labeling friction:Medical device classification of blue light blocking claims extends certification timelines and elevates legal exposure for unsubstantiated retinal protection assertions.
- Contact lens substitution:Daily disposable silicone hydrogel lenses with integrated UV and selective blue filtration are capturing younger myopes seeking correction alternatives.
Strategic Opportunities
- Progressive lens white space:Presbyopic myopes seeking unified near-work and distance correction represent an underserved segment with premium margin potential.
- Online channel acceleration:Direct-to-consumer platforms are capturing replacement cycle volume from price-sensitive buyers outside managed vision care networks.
- ANSI Z80 standard evolution:Anticipated blue light filtration metrics will create first-mover certification advantages for laboratories pre-investing in compliant coating infrastructure.
Industry Challenges
- Myopia control credentialing:State optometry boards in Texas and Florida enforce continuing education requirements that fragment practitioner qualification and recommendation consistency.
- Coating equipment capex:Vacuum deposition chambers for interference stack application require seven-figure capital commitments that strain mid-scale laboratory balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Anti-Blue Ray Myopia Lenses Market |
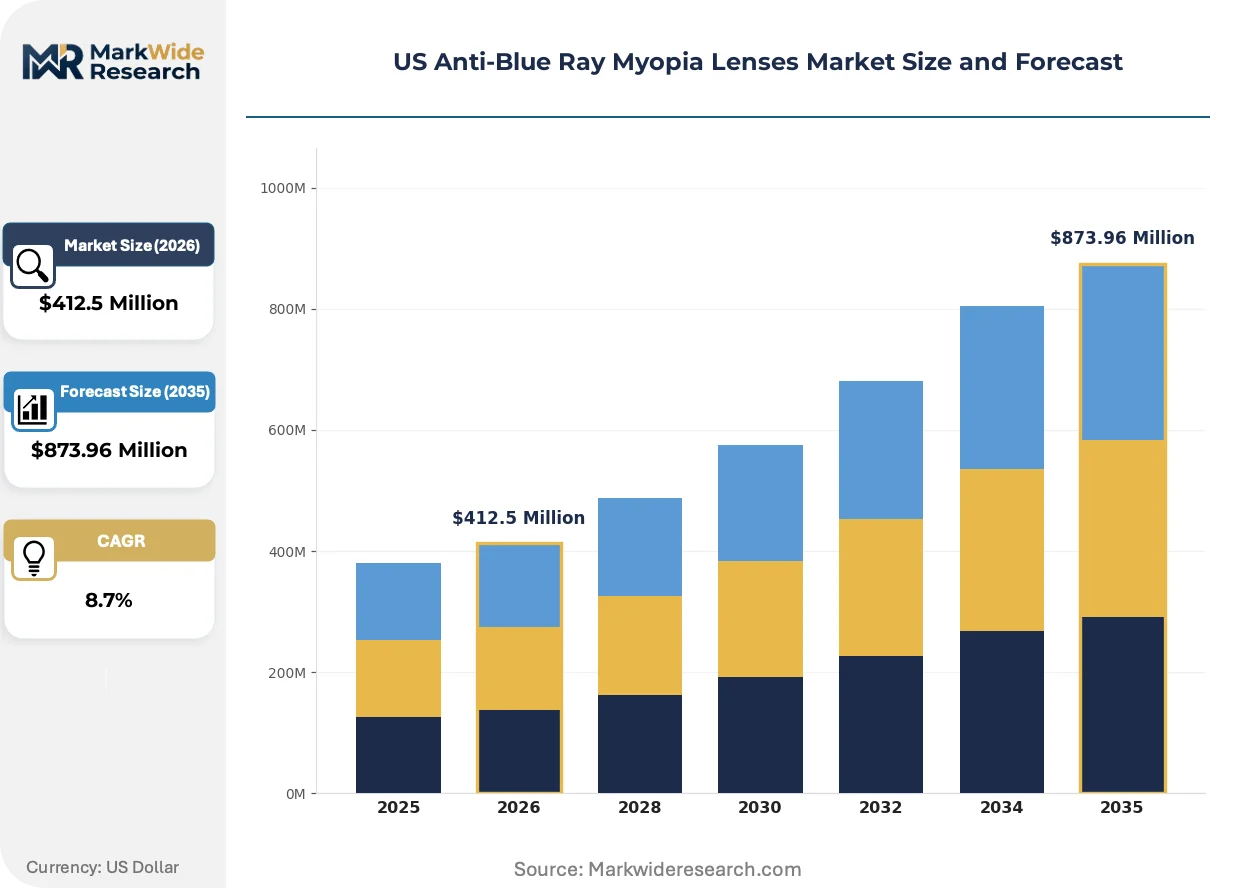
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lens Type: Single Vision, Multifocal, Progressive, Photochromic Material: Polycarbonate, Trivex, Glass, CR-39 Coating Type: Anti-Reflective, Scratch-Resistant, UV Protection, Hydrophobic Distribution Channel: Optical Stores, Online Retail, Supermarkets, Eye Clinics |
| Companies Covered | EssilorLuxottica SA, Carl Zeiss AG, Nikon Corporation, Hoya Corporation, Rodenstock GmbH, Seiko Vision, Shamir Optical Industry Ltd., Chemiglas Corp., Shanghai Conant Optics Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Anti-Blue Ray Myopia Lenses Market Trends and Innovations
Selective wavelength-attenuating dye chemistry and vacuum-deposited interference coatings are actively displacing legacy substrate tinting methods, compressing optical performance variance while elevating manufacturing precision requirements across the supply base.
High-index substrate formulations with integrated chromatic aberration reduction are rewriting performance benchmarks for blue-filtering designs. Pediatric ophthalmology networks are specifying these materials for progressive myopia management protocols. The technology is rewriting margin structures by enabling premium pricing for unified optical correction and protective filtration.
FDA oversight of blue light blocking claims as medical device labeling is tightening substantiation requirements for retinal protection assertions. Manufacturers must now compile clinical evidence packages before marketing deployment. Pediatric lens categories face the steepest compliance burden, with California and New York district health programs demanding FDA-acknowledged filtration metrics.
Managed vision care networks are unbundling myopia progression monitoring from initial lens dispensing, compressing traditional eye clinic capture rates. Online retailers are absorbing replacement volume through prescription verification APIs and virtual try-on tools. Texas and Florida show the most pronounced channel rotation, where optometry board credentialing requirements paradoxically drive price-sensitive buyers toward unregulated direct-to-consumer platforms.
US Anti-Blue Ray Myopia Lenses Market Segmentation
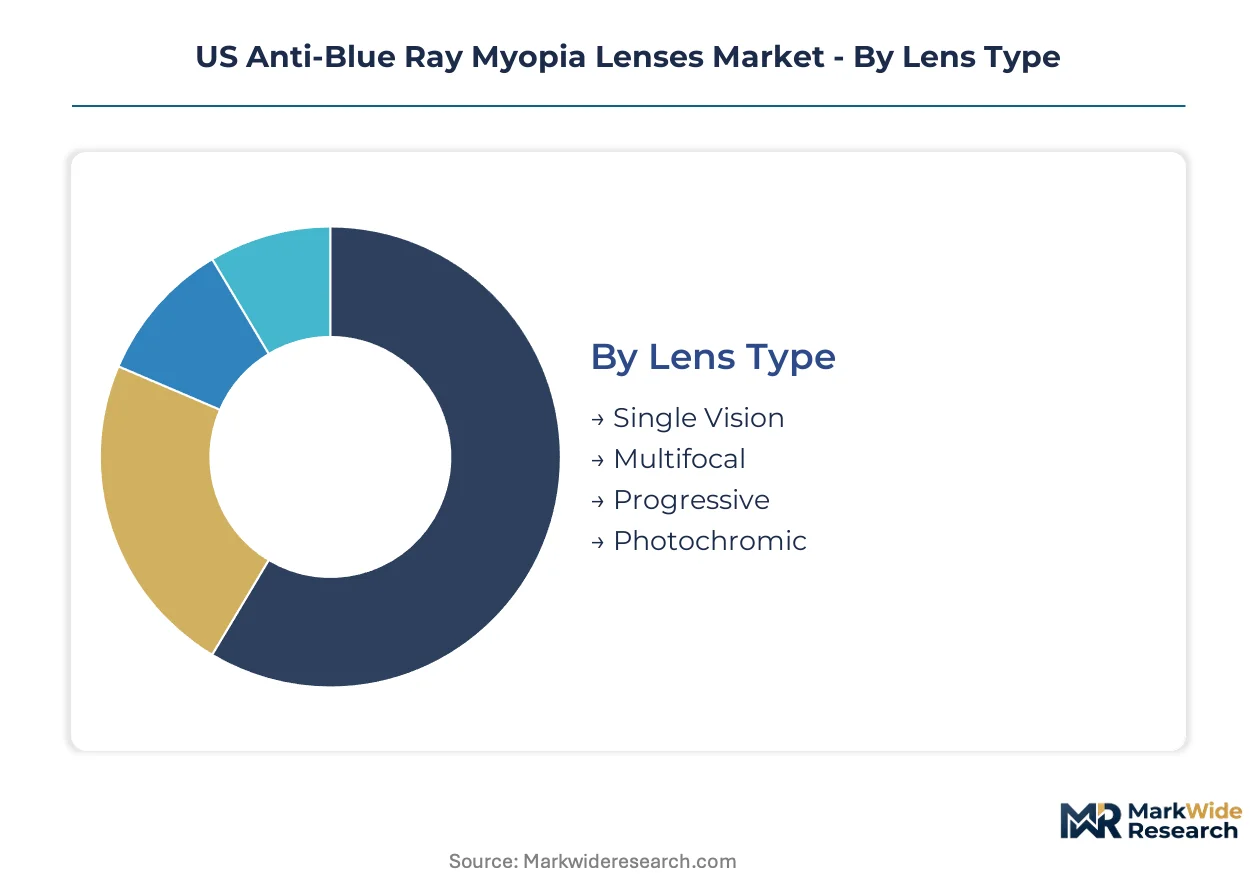
Segmentation in this market reveals how FDA certification burdens and state-level procurement mandates reshape competitive positioning across lens categories. Understanding these divides exposes where margin pools concentrate and which buyer segments drive replacement velocity.
Lens Type:
Single Vision lenses carry the heaviest FDA substantiation requirements for pediatric blue light claims, while Progressive designs face expanded clinical documentation for presbyopic myopia management protocols.
- Single Vision:Uniform diopter correction across the entire optical surface with integrated selective wavelength filtration. K-12 district health programs in California and Texas concentrate procurement volume here, driven by SB-1472 compliance mandates and documented screen exposure epidemiology.
- Progressive:Continuous power gradient enabling unified near-work and distance correction without visible segments. Presbyopic remote workers in New York and coastal metropolitan areas are expanding this segment fastest, seeking one-lens solutions for dual-focus demands.
- Multifocal:Discrete correction zones for near and distance vision with blue-attenuating substrate integration.
- Photochromic:Light-adaptive dye systems that darken under UV exposure while maintaining static blue filtration in indoor conditions.
Single Vision sits at the top of the volume ranking, with Progressive climbing the fastest.
Material:
Cost tier stratification separates impact-resistant synthetics from premium high-index formulations, with supply concentration among three global resin suppliers dictating availability patterns.
- Polycarbonate:Thermoplastic polymer with inherent shatter resistance and 1.586 refractive index, compatible with spin-coating multi-layer optical stacks. Volume production scales through California and Texas distribution hubs serving managed vision care networks.
- Trivex:Urethane-based monomer with superior optical clarity and lower density than polycarbonate, preferred for pediatric applications where impact standards exceed FDA minimums.
- Glass:Mineral substrate with exceptional scratch resistance but weight penalties limiting adoption to specialty prescriptions.
- CR-39:Allyl diglycol carbonate resin offering cost efficiency and coating compatibility for price-sensitive replacement cycles.
Polycarbonate dominates absolute volume, while Trivex gains share fastest among pediatric credentialing requirements.
Coating Type:
Application-specific layering determines whether vacuum deposition infrastructure or spin-coating lines capture fabrication economics, with ANSI Z80 pre-certification investments separating tier-1 laboratories from mid-scale competitors.
- Anti-Reflective:Multi-layer interference stack reducing surface glare and ghosting in high-illumination environments. Remote workers in dense urban markets prioritize this specification for sustained screen visibility.
- Scratch-Resistant:Hardcoat polymer overlay protecting underlying optical substrates from mechanical abrasion during daily handling.
- UV Protection:Organic absorber integration blocking sub-400nm radiation alongside blue filtration protocols.
- Hydrophobic:Fluorinated surface chemistry repelling moisture and particulate accumulation for reduced cleaning frequency.
Anti-Reflective coatings lead volume deployment, with Hydrophobic treatments expanding most quickly through premium channel positioning.
Distribution Channel:
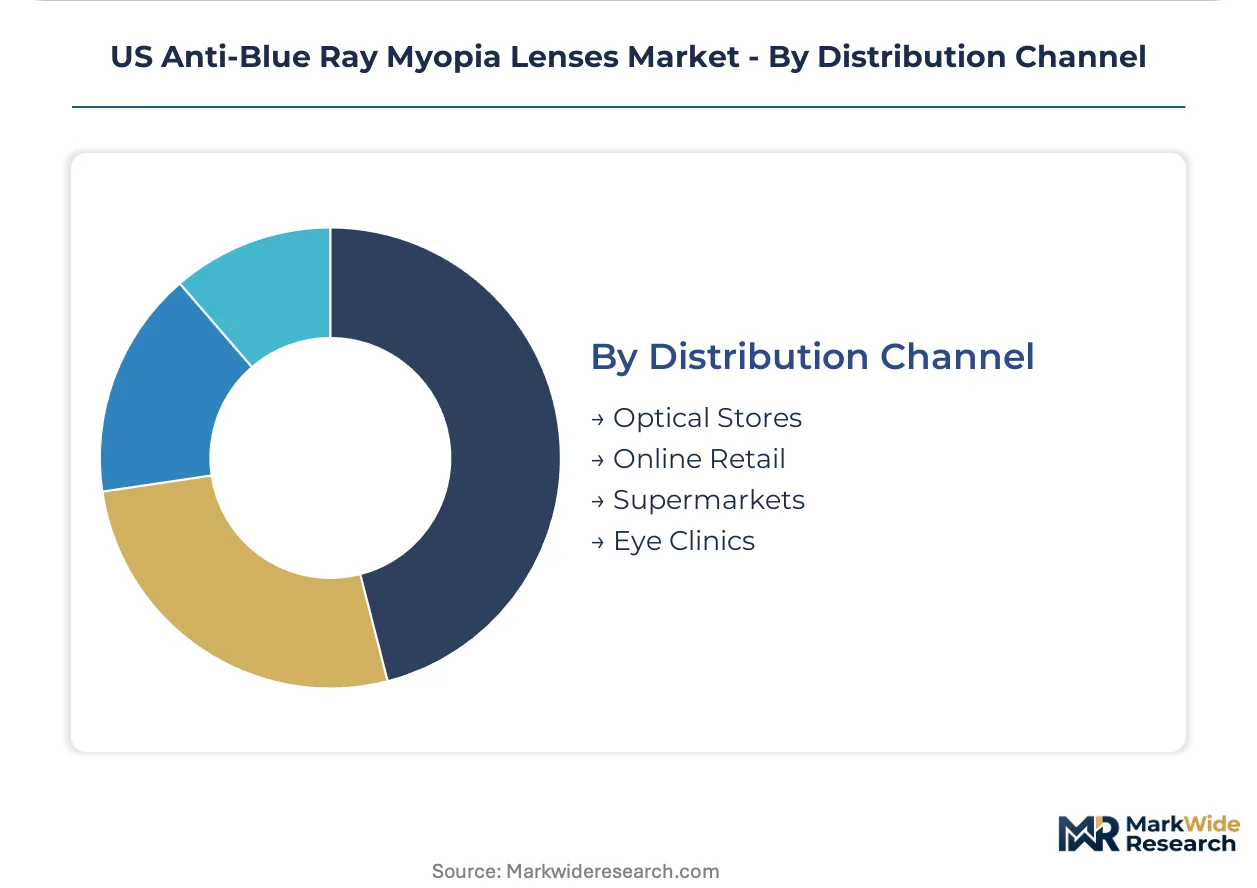
Customer type fragmentation separates managed care-integrated buyers from self-directed purchasers, with credentialing requirements in Texas and Florida paradoxically accelerating unregulated platform migration.
- Eye Clinics:Professional fitting services with myopia progression monitoring and ANSI-compliant prescription verification. Initial pediatric fittings concentrate here due to state board continuing education requirements.
- Online Retail:Direct-to-consumer platforms leveraging prescription APIs and virtual try-on tools for replacement cycle capture. Price-sensitive buyers outside managed networks drive steepest expansion in Texas and Florida.
- Optical Stores:Brick-and-mortar chains with in-house edging laboratories and rapid fulfillment networks.
- Supermarkets:Mass retail positioning for emergency replacement and budget-conscious single-vision procurement.
Eye Clinics retain the highest volume position, with Online Retail climbing the fastest through channel rotation dynamics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dense concentrations of pediatric ophthalmologists and optometry schools in California, Texas, and New York anchor US demand for anti-blue ray myopia lenses. Remote worker populations in coastal metros sustain occupational replacement cycles.
California
K-12 enrollment exceeding 6 million students and SB-1472 digital wellness mandates drive district-level procurement of protective eyewear. FDA substantiation requirements for pediatric blue light claims concentrate compliance burdens on Los Angeles and San Francisco Bay Area laboratories. EssilorLuxottica SA operates coastal distribution hubs serving West Coast optometry chains with rapid fulfillment networks.
Texas
Independent school districts in Dallas-Fort Worth and Houston metropolitan areas administer vision screening programs expanding pediatric lens demand. State optometry board continuing education requirements for myopia control credentialing shape practitioner recommendation patterns. Austin and San Antonio host emerging telehealth optometry platforms capturing replacement volume through prescription verification APIs.
New York
Presbyopic remote workers in Manhattan and Brooklyn seek unified near-work and distance correction solutions. Progressive lens designs capture premium positioning among financial and technology sector employees. State Department of Health oversight of managed vision care networks influences reimbursement structures for myopia progression monitoring services.
Florida
Retiree migration to Miami-Dade and Tampa Bay metros sustains demand for photochromic and progressive configurations. State optometry board credentialing requirements paradoxically accelerate price-sensitive buyer migration toward unregulated direct-to-consumer platforms. Orlando-area pediatric ophthalmology networks specify high-index substrate formulations for myopia management protocols.
Illinois
Chicago metropolitan concentration of corporate headquarters drives occupational lens procurement through employer-sponsored vision benefit programs. Midwest distribution infrastructure supports inventory positioning for managed care network fulfillment. University of Illinois College of Optometry research collaborations influence regional practitioner adoption of blue filtration technologies.
US Anti-Blue Ray Myopia Lenses Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across coating application and substrate formulation tiers. The market exhibits moderate consolidation among integrated optical conglomerates with vacuum deposition infrastructure, while mid-scale laboratories rely on outsourced spin-coating services. Two strategic archetypes dominate: vertically integrated multinational lens manufacturers with captive resin supply, and specialized coating laboratories serving regional optometry chains. Competitive moves center on ANSI Z80 pre-certification investments and strategic partnerships with pediatric ophthalmology networks for myopia management protocol development.
Among Japanese-origin multinationals, Hoya Corporation and Nikon Corporation occupy positions emphasizing specialized substrate chemistry and proprietary high-index formulations. EssilorLuxottica SA anchors the integrated conglomerate tier with distribution infrastructure spanning coastal population centers. These three exemplify divergent competitive vectors: coating technology specialization, material science integration, and supply chain scale respectively.
| Leading Market Players |
|---|
| EssilorLuxottica SA |
| Carl Zeiss AG |
| Nikon Corporation |
| Hoya Corporation |
| Rodenstock GmbH |
| Seiko Vision |
| Shamir Optical Industry Ltd. |
| Chemiglas Corp. |
| Shanghai Conant Optics Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Optical coating engineers concentrated in California and Texas drive labor-cost spreads that separate premium FDA-certified laboratories from mid-tier spin-coating operations, compressing margin structures at the standard tier while elevating pricing power among ANSI Z80 pre-certified facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the US market, with differentiation resting on FDA certification grade and coating infrastructure ownership. Premium tier laboratories command spreads through captive vacuum deposition chambers and pediatric ophthalmology network partnerships. Pricing pressure stems from online retail channel expansion compressing replacement cycle margins. Occupational remote workers in managed vision care networks show lowest price sensitivity, while K-12 district procurement programs exhibit highest budget constraint responsiveness.
Supply Chain Analysis
FDA medical device classification and ANSI Z80 pre-certification requirements gate supply chain participation, favoring laboratories with established clinical evidence packages. Optical-grade polycarbonate resin draws from Japan, Germany, and South Korea, with bisphenol-A monomer and specialty dye chemistries feeding coating application lines. Single-source vulnerability concentrates among three global resin suppliers exposed to petrochemical feedstock volatility. Distribution runs through EssilorLuxottica coastal hubs and regional optometry chain laboratories serving managed care networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US anti-blue ray myopia lens market reads as a late-cycle quality story, with presbyopic remote worker demand shifting toward progressive high-index formulations that command sustained premium positioning.
For Market Incumbents: Anticipate contact lens substitution threats from silicone hydrogel daily disposables with integrated blue filtration by deepening pediatric ophthalmology network partnerships. Prioritize ANSI Z80 certification pre-investment to capture first-mover positioning before metric finalization. Defensive consolidation through regional laboratory acquisition in Texas and Florida offsets online channel volume erosion.
For New Entrants and Emerging Players: Enter via direct-to-consumer platforms targeting price-sensitive replacement cycles in Texas and Florida, where state board credentialing paradoxically accelerates unregulated platform migration. White space concentrates in presbyopic progressive lens segments underserved by incumbent managed care focus. Go-to-market leverage rests on prescription verification API integration and virtual try-on tooling.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale coating laboratories lacking vacuum deposition infrastructure but holding established optometry chain relationships. Long-term viability favors assets with backward integration into resin sourcing or forward integration into telehealth optometry platforms. The signal to watch is CMS consideration of myopia management as a covered pediatric vision benefit, which would restructure reimbursement economics.
| Strategic Initiative | Industry Significance |
|---|---|
| ANSI Z80 Pre-Certification Investment | FDA-acknowledged filtration metrics create first-mover certification advantages for compliant laboratories. |
| Pediatric Ophthalmology Network Partnership | Myopia management protocol development secures high-margin prescription flows from K-12 district programs. |
| Vacuum Deposition Infrastructure Expansion | Captive interference coating capacity eliminates outsourced spin-coating dependencies and margin leakage. |
| Direct-to-Consumer Platform Launch | Prescription verification APIs capture replacement volume outside managed vision care network constraints. |
| High-Index Substrate Formulation R&D | Proprietary chromatic aberration reduction enables premium pricing for presbyopic progressive configurations. |
Research Methodology
Direct dialogue with optical laboratory managers, pediatric ophthalmologists, optometry chain procurement directors, and managed vision care network executives anchored qualitative grounding, cross-referenced with FDA 510(k) filings, ANSI Z80 draft standards, state optometry board continuing education records, and SEC 10-K optical segment disclosures. Bottom-up laboratory capacity estimates and top-down prescription volume modeling provided triangulation discipline across the analysis window.
Bottom-up modeling aggregated individual laboratory coating line throughput by substrate type and certification tier, while top-down analysis calibrated against national vision benefit enrollment and screen exposure epidemiology trends. Segmentation dimensions included lens type, material grade, coating stack configuration, and distribution channel density. CAGRs derived from replacement cycle velocity assumptions and pediatric myopia progression monitoring adoption curves, with FDA regulatory timeline uncertainty folded into scenario bands.
Inputs from laboratory operators and state regulatory filings were available through the study window; gaps in real-time inventory positioning data from polycarbonate resin suppliers introduce uncertainty bands around cost pass-through assumptions. Forecasts reflect documented assumptions about SB-1472 procurement mandate expansion and contact lens substitution elasticity. A model refresh is warranted upon material change in CMS pediatric vision benefit coverage determination or ANSI Z80 final standard publication.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Osmotic Pumps Market
Medical Devices
Balloon Inflation Devices Market
Medical Devices
Global Live Cell Encapsulation Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Needle-Free Injectors Market
Medical Devices
Neurotech Devices Market
Medical Devices
BFS Syringes Market
Medical Devices
Global Endotracheal Tubes Market
Medical Devices
Autotransfusion Devices Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Retinal Implant Market
Medical Devices
US Electrosurgical Generators Market
Medical Devices
Mucus Clearance Devices Market
Medical Devices
Elbow Fixators Market
Medical Devices
Pharma Robots Market