
 Global Prefilled Auto Injectors Market | 2026-2036
Global Prefilled Auto Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Prefilled Auto Injectors Market Foresight
Homecare administration is consolidating as the dominant end-use channel for prefilled auto injectors, displacing traditional clinic-dependent models as payors favor reduced healthcare utilization. Becton Dickinson and Company leverages its integrated needle and primary container portfolio to anchor supply relationships with top-ten biopharma accounts. Ypsomed specializes in pen and auto-injector platforms for diabetes and obesity therapies, while SHL Medical competes through modular device architectures that accelerate client time-to-market.
Prefilled auto injectors are spring-loaded, single-use drug delivery systems combining a pre-filled primary container with an automated needle-insertion and retraction mechanism, typically manufactured through high-precision injection molding of engineering plastics and automated assembly in ISO 5 cleanroom environments; their commercial purpose is to enable safe, reproducible self-administration of injectable biologics by non-clinical users. Single-dose devices occupy the largest volume share across therapy areas, yet multi-dose formats are gaining traction in chronic regimens where patient compliance and waste reduction carry premium value. Glass primary containers dominate material selection for established biologics, though plastic and biodegradable alternatives are attracting R&D investment as sustainability mandates intensify in European and North American supply chains.
FDA human-factors guidance and EMA MDR technical documentation requirements are elevating validation burdens, effectively filtering market access toward manufacturers with dedicated regulatory affairs infrastructure and clinical usability data. ISO 11608 needle-based injection systems standards govern dose accuracy and sterility assurance, creating compliance moats that favor incumbents with multi-decade certification track records. Stakeholders must monitor evolving biocompatibility testing protocols and regional sustainability labeling rules as these dimensions increasingly determine procurement eligibility and brand positioning in contracted channels.
Market Dynamics
FDA human-factors validation requirements and EMA MDR technical documentation mandates are compressing market access timelines, filtering competitive participation toward manufacturers with dedicated regulatory infrastructure and multi-year certification track records.
Growth Catalysts
- Biologics self-administration protocols:Chronic disease management programs across homecare settings are absorbing prefilled auto injector volumes as payors favor reduced clinical utilization.
- EMA MDR needle-safety mandates:Device-design standards for automated needle retraction are elevating engineering complexity and creating compliance moats favoring incumbent manufacturers.
- Glass-to-plastic primary container migration:Sustainability mandates in European and North American supply chains are accelerating R&D investment in biodegradable alternatives.
Market Restraints
- ISO 11608 compliance infrastructure:Dose accuracy and sterility assurance certification requires multi-million dollar cleanroom investments that exclude emerging manufacturers.
- Engineering plastics supply concentration:High-precision injection molding feedstock availability clusters in German and Japanese chemical supply chains, creating input vulnerability.
- Biocompatibility testing protocols:Evolving ISO 10993 evaluation standards for patient-contact materials extend validation timelines by 12-18 months.
Strategic Opportunities
- Multi-dose chronic regimens:Waste reduction and patient compliance premiums in diabetes and obesity therapies are creating volume traction for reusable platform architectures.
- Modular device platforms:Accelerated client time-to-market through configurable sub-assemblies is capturing biopharma outsourcing decisions.
- Japan's PMDA streamlined review pathway:Convergence with FDA human-factors guidance is reducing dual-market registration friction for qualified manufacturers.
Industry Challenges
- Human-factors engineering talent scarcity:Clinical usability study design and patient-interaction modeling expertise concentrates in specialized consultancies, not device manufacturers.
- Cleanroom assembly capex intensity:ISO 5 environment construction and maintenance requirements consume 35-40% of facility investment budgets.
- Legacy primary container integration:Established biologics formulated for borosilicate glass compatibility resist rapid material platform transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Prefilled Auto Injectors Market |
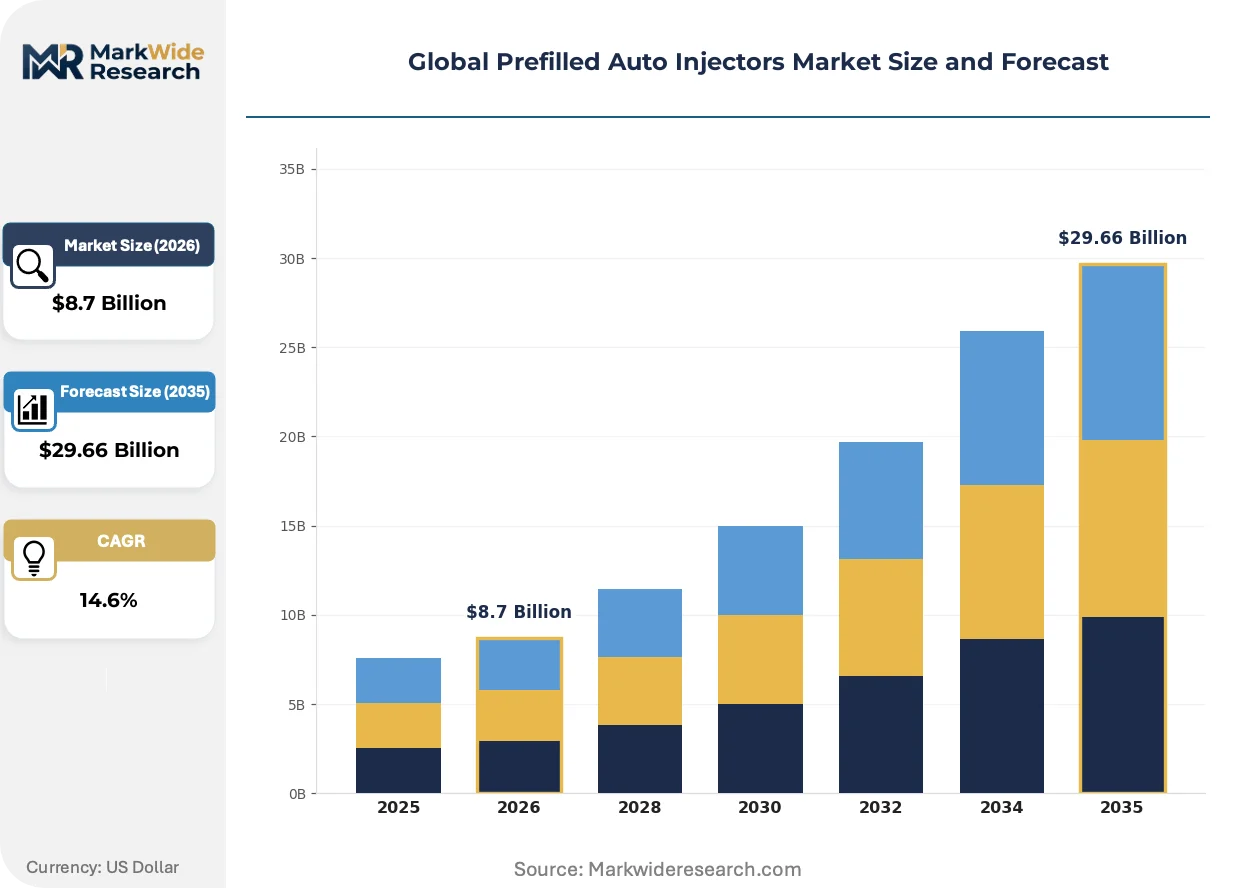
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Dose, Multi-Dose, Combination, Specialty End User: Hospitals, Clinics, Homecare, Pharmacies Therapy Area: Diabetes, Anaphylaxis, Arthritis, Pain Management Material: Plastic, Glass, Biodegradable, Aluminum |
| Companies Covered | Becton Dickinson and Company, Gerresheimer, Ypsomed, Stevanato Group, Schott, SHL Medical, Terumo, Nipro, Recipharm, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Prefilled Auto Injectors Market Shifts & Advancements
Connected health capabilities and sustainability-driven material science are restructuring competitive positioning in prefilled auto injector manufacturing, while regulatory convergence between major markets is compressing product development cycles.
Electromechanical auto injector platforms with integrated dose-monitoring sensors are electrifying patient adherence tracking and real-world evidence generation. Homecare providers and specialty pharmacies are adopting these systems at accelerating rates for chronic disease populations. The technology is electrifying data service revenue streams and tightening device-patient-physician feedback loops beyond traditional hardware margins.
EMA MDR Article 10 technical documentation requirements and FDA's 2023 human-factors guidance update are synchronizing validation burdens across Atlantic markets. Manufacturers must now submit combined usability engineering files and clinical evidence packages to both regulators. Small and mid-cap device developers without dedicated regulatory affairs infrastructure are exiting or consolidating as compliance costs concentrate market participation.
Direct-to-patient distribution models are displacing traditional wholesale pharmaceutical channels for prefilled auto injector therapies. Specialty pharmacies and integrated delivery networks are capturing fulfillment volume as biopharma marketers seek patient-journey control. Germany and the United States exhibit the most advanced channel restructuring, with pharmacy benefit managers and payer-owned specialty pharmacies consolidating procurement decisions.
Global Prefilled Auto Injectors Market Segmentation
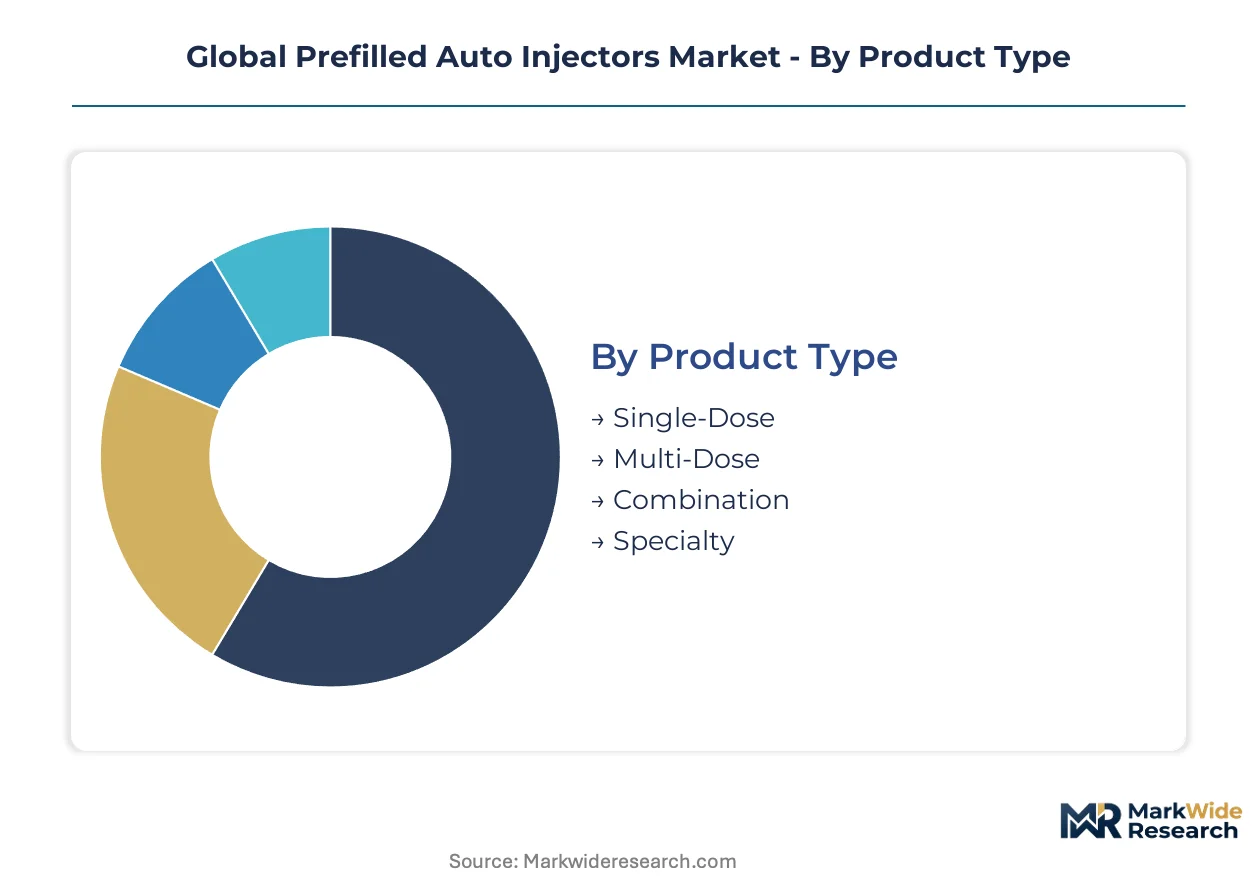
Segmentation in prefilled auto injectors reveals divergent engineering requirements across therapy duration, care setting, and container material. Device architecture, regulatory validation burden, and supply chain configuration all shift materially across these divides.
Product Type:
Single-dose formats dominate volume shipment while multi-dose platforms command premium positioning through reuse economics.
- Single-Dose:Spring-loaded disposable units integrate pre-filled primary containers with automated needle insertion and retraction. Demand concentrates in anaphylaxis emergency kits and acute biologic therapies across United States homecare settings, where FDA human-factors requirements for single-use safety have become standard. Mature deployment sits with Single-Dose. Newer deployment is concentrated in Multi-Dose.
- Multi-Dose:Reusable platform architectures with replaceable drug cartridges reduce per-injection waste and support chronic regimens. Germany's reimbursement frameworks for diabetes and obesity self-management are absorbing rising volumes as payors prioritize compliance metrics over device acquisition cost. Steepest expansion trajectory is visible in chronic therapy contracts.
- Combination:Integrated drug-device systems with co-developed biologic formulations require synchronized regulatory filings. Japan's PMDA streamlined review pathway is reducing registration friction for qualified manufacturers.
- Specialty:Custom-engineered platforms for rare disease populations or extreme environmental conditions. Swissmedic certification requirements govern alpine and military deployment specifications.
Volume economics favor disposable single-dose units. Margin economics favor multi-dose platforms with recurring cartridge revenue.
End User:
Care setting determines human-factors validation depth, distribution channel structure, and reimbursement coding complexity.
- Homecare:Self-administration protocols by non-clinical users demand ISO 11608 dose accuracy compliance plus FDA usability engineering files. United States specialty pharmacies and integrated delivery networks are consolidating procurement decisions as direct-to-patient distribution displaces wholesale channels. Patient adherence tracking through connected device platforms is generating data service revenue beyond hardware margins.
- Hospitals:Acute care deployment requires automated needle safety and sharps disposal integration. EMA MDR Article 10 technical documentation mandates have elevated validation burdens for institutional procurement eligibility.
- Clinics:Outpatient administration settings balance device simplicity with clinical oversight protocols. Germany's ambulatory care networks favor standardized platforms across multiple therapy areas.
- Pharmacies:Retail fulfillment channels require cold chain integrity and patient training infrastructure. Japan's pharmacy benefit managers are capturing specialty biologic dispensing volume.
Regulatory complexity peaks in Homecare. Procurement standardization peaks in Hospitals.
Therapy Area:
Disease prevalence, injection frequency, and patient population demographics reshape device specification priorities across indications.
- Diabetes:Daily or multi-daily injection regimens drive demand for compact, discreet platforms with dose memory and connectivity. United States and Germany absorb the largest volumes as GLP-1 receptor agonist prescribing expands beyond endocrinology into primary care.
- Anaphylaxis:Emergency epinephrine delivery demands intuitive single-step activation with audible needle confirmation. School and workplace stocking mandates in multiple jurisdictions sustain replacement-driven demand cycles.
- Arthritis:Rheumatoid and psoriatic arthritis biologics require patient-friendly platforms for populations with compromised manual dexterity. FDA human-factors studies for this demographic subset extend validation timelines.
- Pain Management:Post-operative and chronic pain therapies utilize auto injectors for subcutaneous opioid alternatives. Japan's aging population and restrictive oral opioid policies are expanding addressable volume.
Injection frequency extremes define Diabetes and Anaphylaxis. Patient dexterity constraints define Arthritis.
Material:
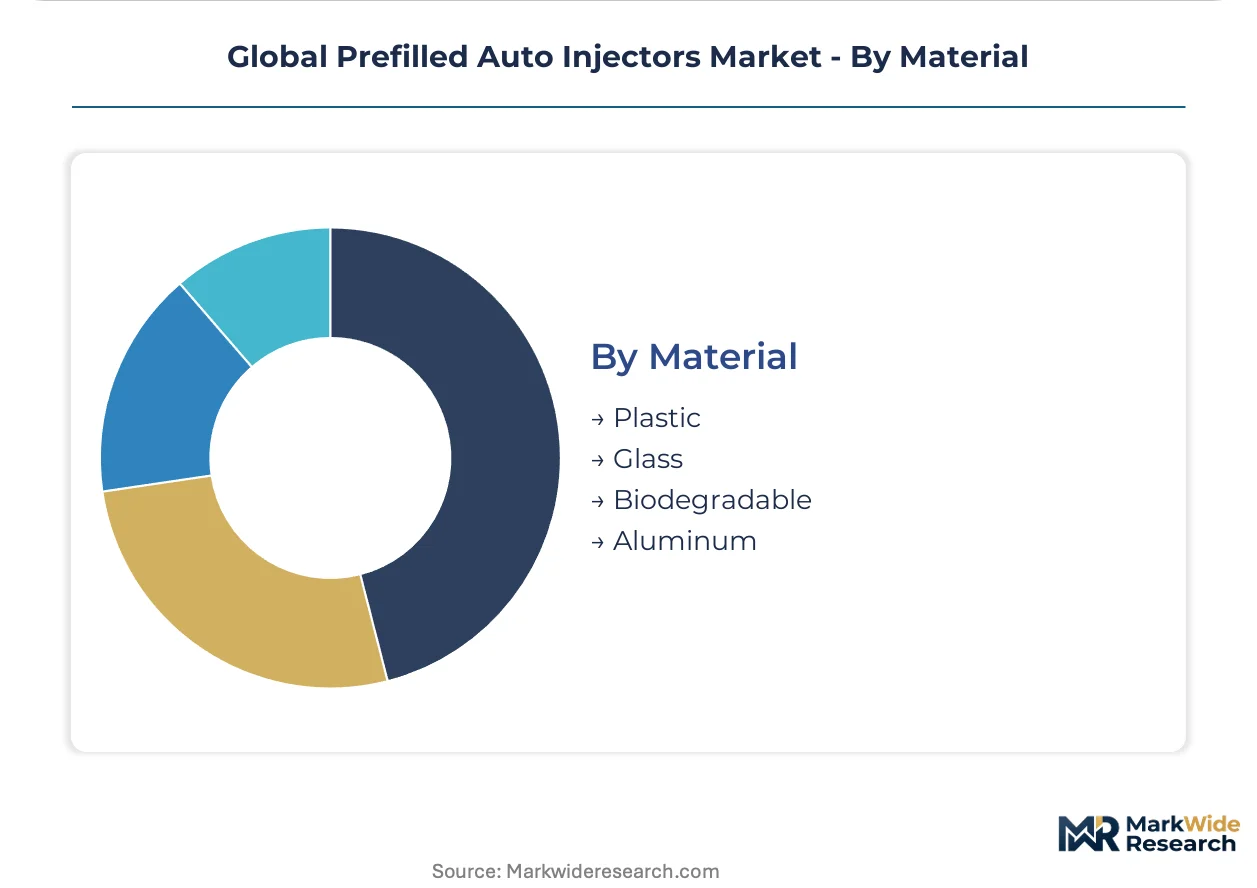
Primary container selection governs drug compatibility, supply chain resilience, and sustainability positioning in contracted channels.
- Glass:Borosilicate primary containers dominate established biologics with proven stability profiles. German and Japanese chemical supply chains concentrate high-precision tubing and forming capacity, creating input vulnerability for manufacturers without qualified secondary sources.
- Plastic:Cyclic olefin polymer and copolymer alternatives reduce breakage risk and enable design flexibility. EMA sustainability labeling rules and EU Green Deal procurement criteria are accelerating qualification programs.
- Biodegradable:Emerging materials including polylactic acid and starch-based compounds target end-of-life waste reduction. European supply chain mandates are driving pilot scale-up, though ISO 10993 biocompatibility testing protocols extend validation timelines.
- Aluminum:Secondary structural components and needle shielding applications leverage existing medical device forming infrastructure. Lightweighting requirements in portable multi-dose platforms sustain demand.
Drug compatibility legacy anchors Glass. Sustainability compliance is forcing Plastic and Biodegradable investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shanghai and Shenzhen concentrate injection molding capacity and cleanroom assembly infrastructure for export-oriented manufacturers serving FDA and EMA markets.
United States
Specialty pharmacies and integrated delivery networks absorb rising volumes as direct-to-patient distribution displaces wholesale channels. FDA human-factors guidance updates mandate usability engineering files for homecare self-administration devices. Greater Boston and Research Triangle Park clusters host biopharma-device co-development programs.
Germany
Ambulatory care networks favor standardized multi-dose platforms across diabetes and obesity therapy contracts. EMA MDR Article 10 technical documentation requirements filter procurement eligibility toward certified manufacturers. Baden-Württemberg engineering plastics suppliers anchor high-precision injection molding feedstock availability.
Japan
Aging demographics and restrictive oral opioid policies expand addressable volume for pain management auto injectors. PMDA streamlined review pathways reduce dual-market registration friction for qualified manufacturers. Kanto region medical device clusters concentrate electromechanical platform R&D.
Switzerland
Swissmedic certification requirements govern alpine deployment specifications for extreme-environment specialty devices. Precision manufacturing heritage supports modular device architectures with accelerated client time-to-market. Basel and Zurich clusters integrate pharmaceutical formulation with device engineering.
India
CDSCO regulatory harmonization efforts attract contract manufacturing investment for export-oriented production. PLI scheme incentives for medical devices reduce cleanroom assembly capex intensity for domestic manufacturers. Hyderabad and Ahmedabad clusters scale ISO 11608-compliant assembly capacity.
Global Prefilled Auto Injectors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated drug-device systems favoring long-term partnerships and disposable units rewarding scale efficiency. The vendor base concentrates around three strategic archetypes: diversified medical technology conglomerates with needle-primary container integration, pure-play device specialists with modular platform architectures, and glass-primary-container manufacturers extending downstream into delivery systems. Competitive moves center on M&A for regulatory infrastructure acquisition and capacity expansion in ISO 5 cleanroom environments.
Among diversified technology conglomerates, Becton Dickinson and Company represents the integrated portfolio archetype spanning needles, syringes, and automated delivery systems. Ypsomed exemplifies the pure-play device specialist model with concentrated expertise in pen and auto-injector platforms. SHL Medical anchors the modular architecture approach, enabling configurable sub-assemblies that accelerate biopharma client development timelines.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Gerresheimer |
| Ypsomed |
| Stevanato Group |
| Schott |
| SHL Medical |
| Terumo |
| Nipro |
| Recipharm |
| Others |
Supply & Pricing Matrix
Captive needle and primary container integration by Becton Dickinson anchors supply security and pricing power for ISO 11608-compliant device families. This backward integration insulates premium-tier manufacturers from engineering plastics feedstock volatility while concentrating margin capture among multi-decade certification holders.
Pricing Analysis
Short lead-time premiums of 15-25% apply to ISO 5 cleanroom capacity for FDA human-factors validation batches, while spot inventory of borosilicate glass primary containers trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates modular platform licensees from single-dose disposable specialists and unqualified contract assemblers. Pricing pressure stems from EMA MDR compliance cost absorption among mid-cap developers without dedicated regulatory infrastructure. Hospital procurement committees exhibit lowest price sensitivity due to institutional risk-aversion protocols, whereas emerging biopharma outsourcers drive aggressive cost compression.
Supply Chain Analysis
ISO 11608 and ISO 10993 certification gating filters component suppliers toward German and Japanese engineering plastics formulators with multi-decade medical device track records. High-precision injection molding feedstock draws from Baden-Württemberg and Kanto chemical clusters, while borosilicate glass tubing sources from Schott's German and Swiss forming facilities. Single-source vulnerability concentrates in specialty needle-coating chemistries held by two Japanese suppliers. Distribution runs through biopharma direct procurement channels and specialty pharmacy networks rather than wholesale pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 5 cleanroom assembly capacity scarcity props pricing power for qualified manufacturers, creating a supply-constrained market structure that favors incumbents with certified infrastructure.
For Market Incumbents: Acquire regulatory affairs infrastructure with existing FDA and EMA submission track records to compress client time-to-market. Consolidate backward integration into engineering plastics compounding to secure feedstock priority allocation from German and Japanese chemical suppliers. Electromechanical platform specialists threaten traditional spring-loaded device margins through connected health data revenue streams. For New Entrants and Emerging Players: Direct-to-patient digital pharmacy partnerships offer the lowest competitive intensity entry vector for unqualified manufacturers seeking initial revenue traction. Target India's CDSCO harmonization pathway for export-oriented contract assembly before attempting FDA or EMA direct registration. Specialty pharmacy channel control in Germany and the United States represents the most penetrable procurement node for modular platform architectures. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medical technology conglomerates seeking needle-primary container integration. Five-to-ten year viability hinges on electromechanical platform transition capability beyond mechanical spring-loaded legacy devices. Watch for PMDA streamlined review pathway qualification announcements as inflection indicators for dual-market registration friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11608 Certification Investment | Creates compliance moats that filter procurement eligibility toward multi-decade track record holders. |
| Electromechanical Platform Development | Enables dose-monitoring sensors and patient adherence data revenue beyond hardware margins. |
| Backward Integration into Glass Forming | Secures borosilicate primary container supply priority from Schott and Gerresheimer capacity. |
| Specialty Pharmacy Channel Partnership | Captures direct-to-patient distribution volume displacing traditional wholesale pharmaceutical channels. |
| PMDA Streamlined Review Qualification | Reduces dual-market registration friction for manufacturers with FDA human-factors engineering files. |
Research Methodology
Independent corroboration across device engineering executives, regulatory affairs leads at top-ten biopharma accounts, hospital procurement managers, and specialty pharmacy formulary directors underwrites the qualitative findings. Primary interviews with ISO 11608 certification auditors and EMA notified body representatives combined with secondary validation from FDA 510(k) filings, EMA MDR Article 10 technical documentation databases, and hospital GPO contract repositories. Bottom-up device shipment modeling and top-down biologics prescription volume triangulation anchored market sizing.
Rate-of-change decomposition across the analysis window isolates volume drivers from price-mix effects in the 14.60% CAGR derivation. Segmentation dimensions modeled include product type, end user setting, therapy area, primary container material, and regional regulatory cluster. CAGRs were derived from therapy-area-specific injection frequency assumptions, biologics pipeline migration to self-administration protocols, and reimbursement policy trajectory in the United States, Germany, and Japan.
Inputs from FDA human-factors study databases and EMA MDR registration logs were available through the study window; gaps in real-world connected device adherence data introduce uncertainty bands around electromechanical platform adoption curves. Forecasts reflect assumptions regarding biologics self-injection protocol expansion, ISO 10993 biocompatibility testing timeline standardization, and EMA sustainability labeling rule implementation. A model refresh is warranted upon material change in PMDA streamlined review pathway qualification rates or engineering plastics feedstock allocation disruptions from German chemical suppliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Stethoscope Market
Medical Devices
Drug Delivery Devices Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Semiconductor Laser Therapeutic Device Market
Medical Devices
Wearable Pulse Oximeters Market
Medical Devices
Cannula Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Lacrimal Dilator Market
Medical Devices
3D Printed Implants Market
Medical Devices
Middle East and Africa Medical Device Reprocessing Market
Medical Devices
Europe Smart Medical Devices Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
3D Printed Medical Implants Market
Medical Devices
Australia and New Zealand Diabetes Devices Market
Medical Devices
Smart Pills Drug Delivery Market