
 Single Lead ECG Equipment Market | 2026-2036
Single Lead ECG Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Single Lead ECG Equipment Market Analytics
A capital-intensity divergence between cloud-connected wearable specialists and legacy diagnostic equipment manufacturers is unwinding competitive stability in single lead ECG supply. AliveCor leverages its FDA-cleared AI algorithms to dominate direct-to-consumer cardiac screening channels. GE Healthcare anchors hospital procurement through integrated telemetry infrastructure that extends from bedside to ambulatory settings. Philips Healthcare sustains brand strength across European home care markets with CE-marked portable monitors.
Single lead ECG equipment captures cardiac electrical activity through one bipolar electrode pair, typically sampling at 250–500 Hz with bandwidth filtered to 0.05–40 Hz for arrhythmia detection in ambulatory or remote settings. Wearable devices and portable monitors are leading volume growth as lithium-polymer power miniaturization and Bluetooth Low Energy transmission enable multi-day continuous monitoring outside clinical walls. Telemetry systems occupy higher margin pools through subscription-linked remote patient monitoring platforms, while diagnostic equipment faces pricing pressure from commoditized hardware in saturated hospital markets.
FDA 510(k) pathways and EU MDR conformity assessments are elevating clinical validation burdens for algorithm-based arrhythmia classification, filtering out undercapitalized entrants. The EPA and FCC jointly shape device design through electromagnetic compatibility standards and wireless spectrum allocation for medical data transmission. Stakeholders must monitor evolving reimbursement codes for remote physiological monitoring as payors recalibrate coverage thresholds between episodic diagnostic use and longitudinal cardiac surveillance models.
Market Dynamics
Cloud-connected wearable ECG devices are compressing margins for legacy diagnostic equipment manufacturers by collapsing the distinction between consumer wellness and clinical-grade monitoring, forcing incumbents to rebuild their telemetry infrastructure around subscription-linked remote patient monitoring platforms.
Growth Catalysts
- FDA 510(k) clearance expansion:Streamlined pathways for algorithm-based arrhythmia detection are accelerating portable device commercialization in ambulatory care settings. The FDA's evolving digital health pre-certification framework reduces validation timelines for AI-enabled cardiac screening tools.
- Home care settings:Aging demographics in the United States, Germany, and Japan are driving concentrated procurement pull for lithium-polymer powered monitors with Bluetooth Low Energy transmission. Reimbursement expansion for remote physiological monitoring is shifting cardiac surveillance from episodic diagnostics to longitudinal models.
- EU MDR harmonization:CE marking convergence under the Medical Device Regulation is creating standardized performance benchmarks that reduce market fragmentation across European home care channels. The MDR's tightened clinical validation requirements are filtering out undercapitalized entrants and consolidating competitive positions.
Market Restraints
- Lithium-polymer supply concentration:Battery cell production clusters in East Asia create input cost volatility and geopolitical exposure for wearable device manufacturers dependent on multi-day continuous monitoring capabilities.
- EU MDR conformity assessment burden:Elevated clinical validation requirements for algorithm-based arrhythmia classification are extending time-to-market for portable detection systems and consuming R&D capital.
- Electromagnetic compatibility constraints:Joint EPA and FCC standards for wireless medical data transmission are limiting spectrum allocation options and increasing hardware design complexity for cloud-connected form factors.
Strategic Opportunities
- Rural cardiac surveillance gaps:Underpenetrated regions in India present white space for low-cost wearable monitors paired with telemedicine platforms. The country's PLI scheme for medical electronics manufacturing offers production incentives for localized assembly.
- AI-ECG convergence:Integration of deep learning classification with single lead hardware is enabling predictive arrhythmia detection that extends beyond reactive diagnostic models. This convergence opens subscription revenue streams in employer wellness programs.
- Direct-to-consumer channels:Pharmacy retail partnerships and telehealth platform integrations are bypassing traditional hospital procurement gatekeepers for preventive cardiac screening. Germany's Apotheken network provides established distribution infrastructure for CE-marked portable monitors.
Industry Challenges
- Algorithm validation talent scarcity:Clinical data science expertise for FDA-compliant arrhythmia classification pipelines is concentrated among a limited pool of specialists, inflating compensation and extending development cycles.
- Legacy telemetry integration friction:Hospital IT infrastructure built around bedside monitoring systems requires costly middleware development to ingest ambulatory wearable data streams into electronic health records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Lead ECG Equipment Market |
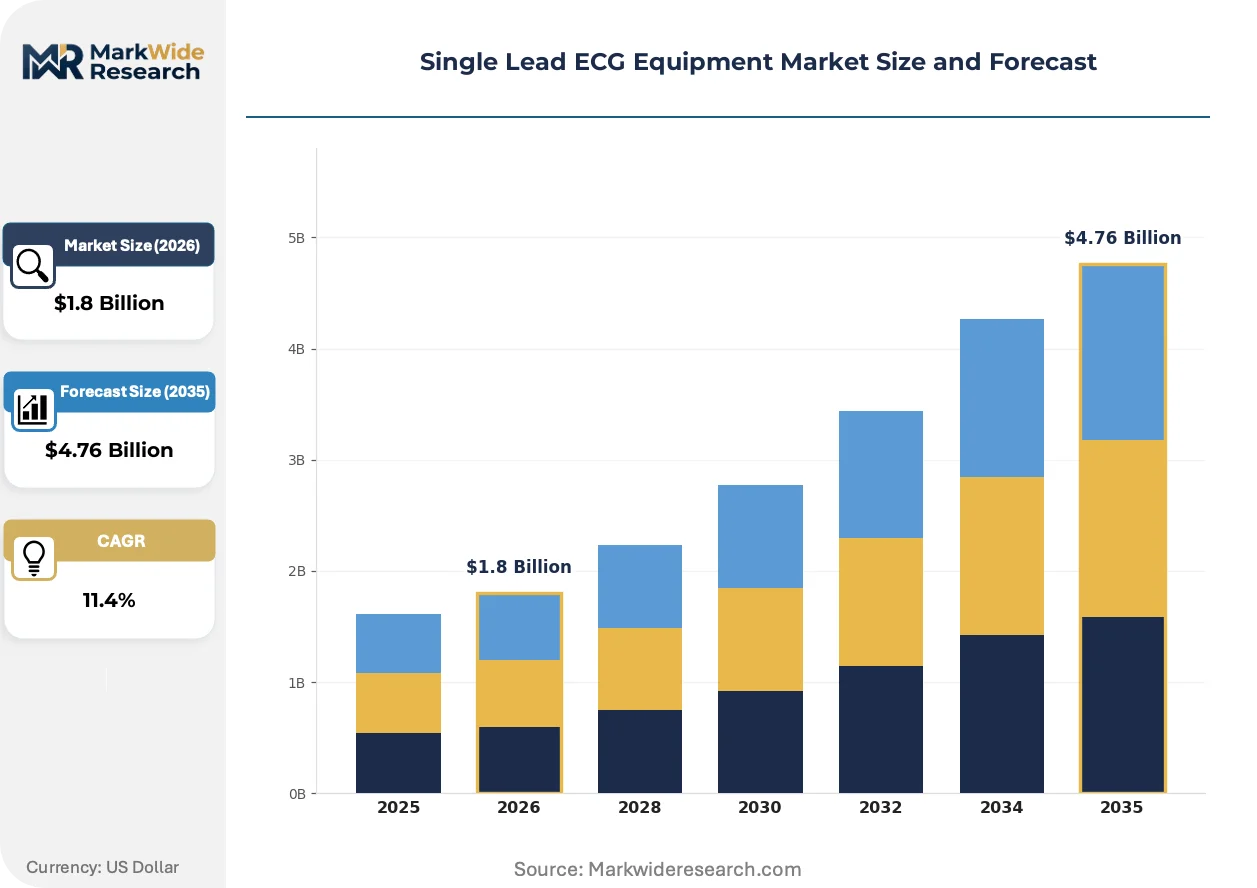
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Wearable Devices, Diagnostic Equipment, Telemetry Systems Technology: Wireless Transmission, Cloud Connectivity, Signal Processing, Data Analytics End User: Clinics, Hospitals, Home Care, Telehealth Services Application: Cardiac Monitoring, Remote Patient Monitoring, Fitness Tracking, Emergency Response |
| Companies Covered | AliveCor, Inc., GE Healthcare, OMRON Corporation, Philips Healthcare, Dimetek Digital Medical Technologies Ltd., Zenicor Medical Systems, iRhythm Technologies, Inc., Mindray Medical International Limited, Schiller AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Lead ECG Equipment Market Evolving Landscape
Artificial intelligence inference at the edge is collapsing the latency between cardiac event detection and clinical intervention, while regulatory frameworks on both sides of the Atlantic are hardening around algorithm transparency requirements.
Photoplethysmography-enhanced single lead ECG is supplanting pure electrical signal acquisition in consumer wearables by enabling continuous heart rate variability tracking without gel electrodes. Sports medicine clinics and employer wellness programs are adopting these hybrid sensors for stress monitoring and recovery optimization. This convergence is compressing the addressable market for standalone diagnostic holters by shifting preventive cardiac surveillance toward always-on wearable form factors.
The EU AI Act's risk classification system for medical device algorithms is mandating conformity assessments for arrhythmia detection software that were previously self-certified under general wellness exemptions. European manufacturers must now document training data provenance and algorithmic explainability to maintain CE marking validity. Portable monitor developers with cloud-based inference pipelines face the steepest compliance recalibration as the Act's high-risk system designations extend to cardiovascular diagnostic functions.
Hospital procurement committees are fragmenting their cardiac monitoring vendor portfolios to avoid single-source dependency in telemetry infrastructure. Integrated health systems in the United States are unbundling hardware acquisition from software subscriptions, forcing device manufacturers to compete on interoperability rather than captive platform lock-in. This unbundling is most visible in multi-hospital networks consolidating their remote patient monitoring contracts around API-first vendors with FHIR-compliant data exchange capabilities.
Single Lead ECG Equipment Market Segmentation
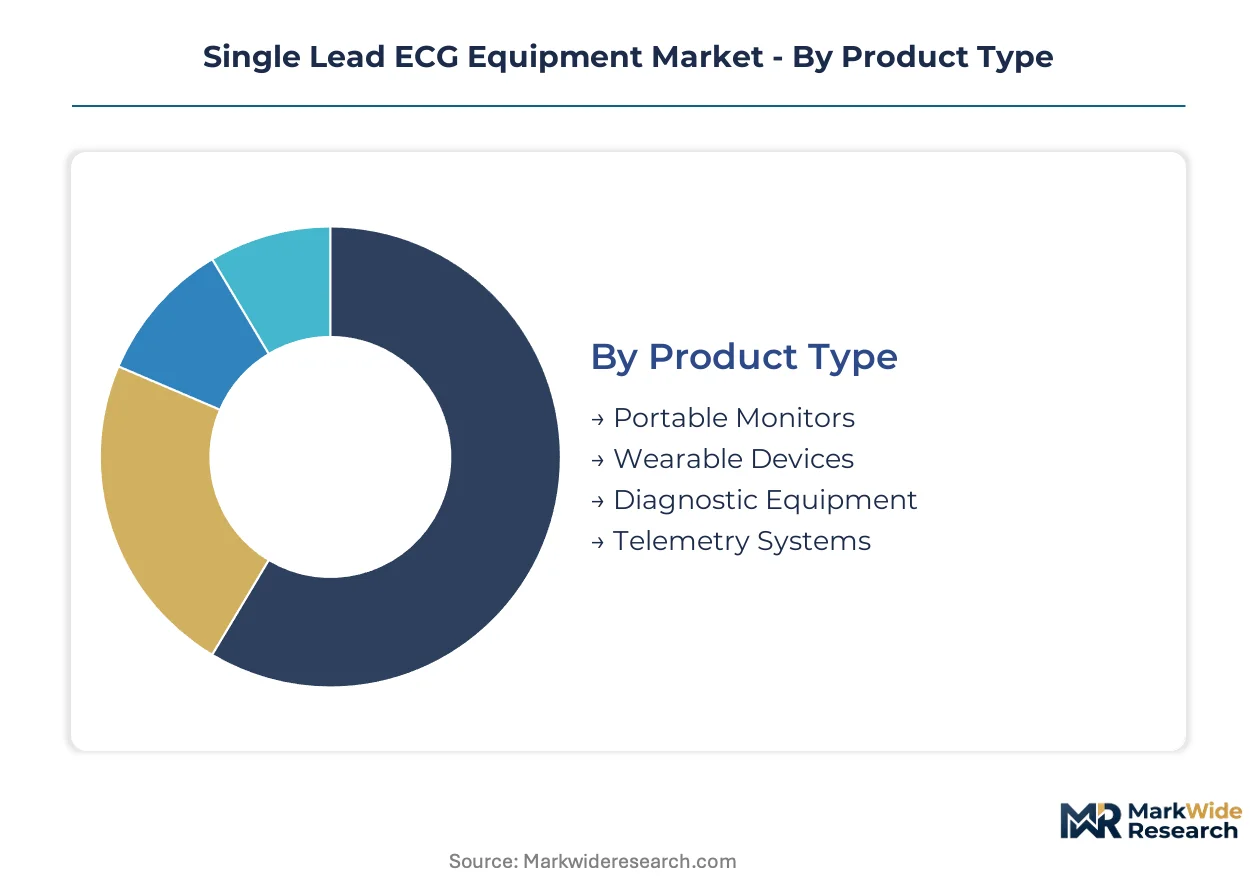
Segmentation in single lead ECG equipment reveals how margin pools migrate between hardware commoditization and software-enabled recurring revenue. Understanding these divisions exposes where capital is concentrating and which technology layers command pricing power.
Product Type:
Telemetry systems capture the highest recurring revenue through subscription-linked remote monitoring platforms, while portable monitors compete on lithium-polymer efficiency and Bluetooth transmission range.
- Portable Monitors:Handheld units sampling at 250–500 Hz with gel electrodes for episodic arrhythmia screening in ambulatory clinics. Demand clusters in United States cardiology practices where Medicare reimbursement for remote physiological monitoring has expanded coverage thresholds.
- Wearable Devices:Continuous-monitoring form factors powered by lithium-polymer cells with multi-day battery life, transmitting via Bluetooth Low Energy to cloud platforms. Germany's aging demographics and Apotheken retail network are driving concentrated procurement for CE-marked preventive screening tools.
- Diagnostic Equipment:Bedside systems with integrated thermal printers and lead-wire assemblies for hospital-based acute cardiac assessment.
- Telemetry Systems:Subscription-linked infrastructure extending from bedside monitors to ambulatory data aggregation, commanding annual recurring revenue through FDA-cleared remote patient monitoring platforms.
Telemetry systems hold installed capacity in United States hospital networks. Wearable devices are rotating up the share rankings through direct-to-consumer pharmacy channels.
Technology:
Cloud connectivity extracts premium pricing through AI-enabled arrhythmia classification, while signal processing hardware faces cost compression from commoditized analog front-end components.
- Wireless Transmission:Bluetooth Low Energy and proprietary RF protocols enabling real-time cardiac data streaming from ambulatory patients to clinical decision support systems. FCC spectrum allocation constraints and electromagnetic compatibility standards are shaping hardware design specifications for cloud-connected form factors.
- Cloud Connectivity:Centralized inference pipelines for algorithm-based arrhythmia detection with FHIR-compliant electronic health record integration. United States integrated health systems are unbundling hardware from software subscriptions, forcing API-first interoperability over captive platform lock-in.
- Signal Processing:Analog front-end amplification and digital filtering circuits for 0.05–40 Hz bandwidth cardiac signal acquisition.
- Data Analytics:Deep learning classification models for predictive arrhythmia detection, now requiring FDA 510(k) clearance and EU AI Act conformity assessments for high-risk medical device designation.
Signal processing holds installed capacity in legacy hospital telemetry infrastructure. Cloud connectivity is climbing the fastest as payors shift reimbursement toward longitudinal cardiac surveillance models.
End User:
Home care settings command volume growth through aging demographic procurement, while hospitals defend margin through integrated telemetry infrastructure that resists unbundling.
- Home Care:Direct-to-consumer and caregiver-administered cardiac monitoring for chronic disease management outside clinical walls. Japan's super-aged society and reimbursement expansion for remote patient monitoring are creating concentrated demand for lithium-polymer powered continuous wearables.
- Telehealth Services:Platform-integrated cardiac screening with asynchronous clinician review and automated arrhythmia alerts. India's underpenetrated rural regions present white space for low-cost wearable monitors paired with telemedicine infrastructure, supported by PLI scheme production incentives for localized medical electronics assembly.
- Hospitals:Acute care settings with bedside telemetry integration and electronic health record connectivity requirements.
- Clinics:Outpatient cardiology practices with episodic diagnostic workflows and limited IT infrastructure for wearable data ingestion.
Hospitals hold installed capacity in acute cardiac monitoring. Home care is gaining share fastest as reimbursement codes align with longitudinal surveillance over episodic diagnostics.
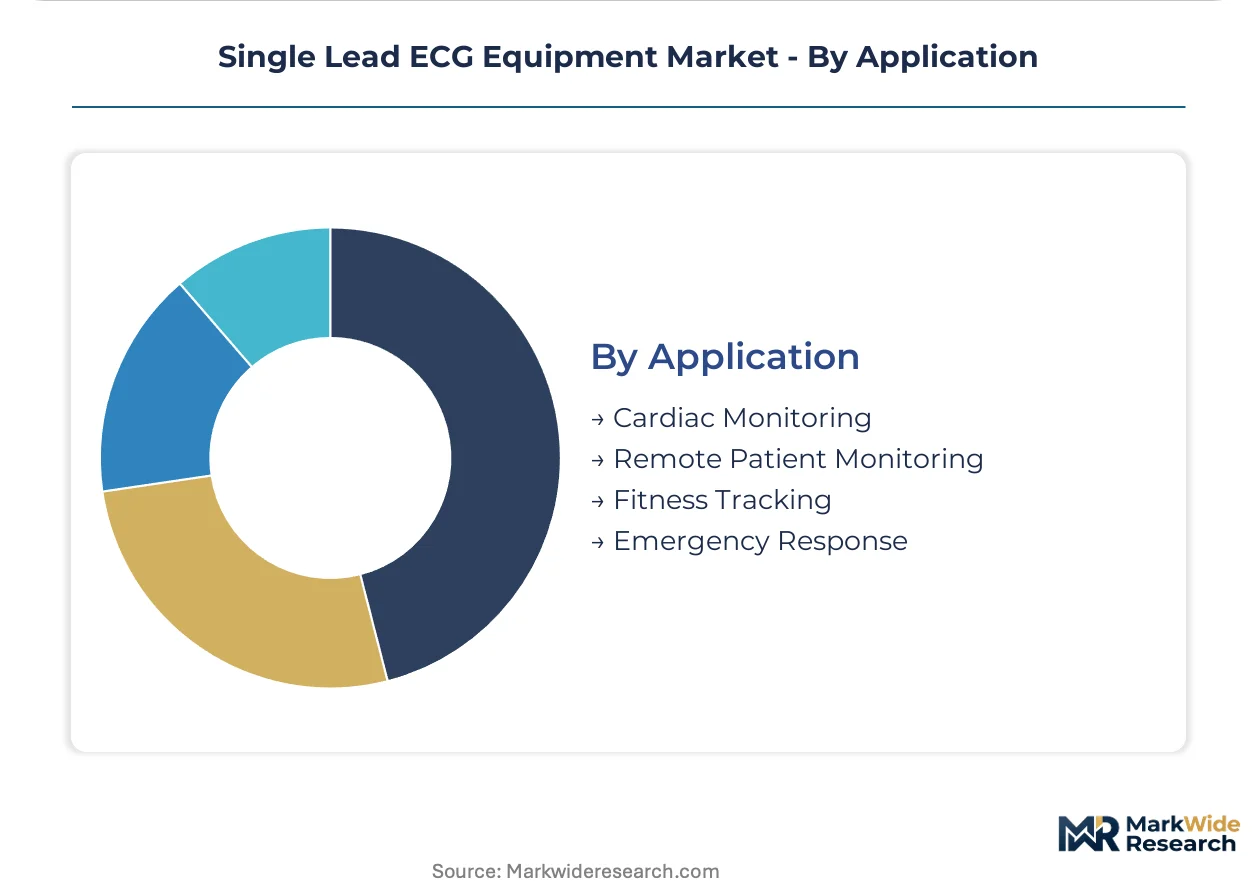
Application:
Remote patient monitoring aggregates subscription revenue across hardware and software layers, while fitness tracking competes in consumer wellness markets with lower clinical validation burdens.
- Remote Patient Monitoring:Longitudinal cardiac surveillance with clinician oversight, reimbursable under expanded Medicare CPT codes for physiological data review. United States payor recalibration of coverage thresholds between diagnostic and surveillance models is shifting procurement toward multi-day continuous monitoring capabilities.
- Cardiac Monitoring:Diagnostic-grade arrhythmia detection requiring FDA 510(k) clearance or EU MDR CE marking with tightened clinical validation for algorithm-based classification. EU MDR harmonization is filtering undercapitalized entrants and consolidating competitive positions across European home care channels.
- Fitness Tracking:Consumer wellness applications with photoplethysmography-enhanced sensors for heart rate variability and recovery optimization in sports medicine.
- Emergency Response:Automated alert systems for acute cardiac events with emergency services dispatch integration.
Cardiac monitoring holds installed capacity in clinical diagnostic workflows. Remote patient monitoring is rotating up the share rankings through unbundled subscription pricing and API-first vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement channels. United States hospital buyers prioritize FDA-cleared algorithm accuracy over hardware cost, while German home care consumers and Indian rural telehealth platforms demand lithium-polymer efficiency at aggressive price points.
United States
Medicare reimbursement expansion for remote physiological monitoring drives concentrated procurement of multi-day continuous wearables. FDA 510(k) clearance pathways for AI-enabled arrhythmia detection filter out undercapitalized entrants. Boston's medical device cluster anchors telemetry infrastructure development for integrated health systems unbundling hardware from software subscriptions.
Germany
Super-aged demographics and Apotheken retail network penetration create pull for CE-marked preventive screening tools. EU MDR harmonization tightens clinical validation requirements for algorithm-based classification. Baden-Württemberg's precision electronics manufacturing base supplies analog front-end components for portable monitor assembly.
Japan
World's oldest population sustains demand for caregiver-administered cardiac monitoring outside clinical walls. METI standards for medical device wireless transmission shape Bluetooth Low Energy hardware specifications. Tokyo-Osaka corridor concentrates PMDA consultation resources for accelerated approval of cloud-connected form factors.
India
Underpenetrated rural regions present white space for low-cost wearable monitors paired with telemedicine platforms. PLI scheme production incentives support localized lithium-polymer device assembly. Karnataka's medical electronics manufacturing zone attracts contract fabrication for export-oriented portable monitor producers.
China
Domestic aging demographics and hospital procurement centralization drive volume demand for bedside telemetry integration. NMPA regulatory harmonization with international standards accelerates approval timelines for algorithm-based detection systems. Shenzhen's consumer electronics cluster enables rapid prototyping of photoplethysmography-enhanced hybrid sensors.
Single Lead ECG Equipment Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in single lead ECG supply. Hospital procurement committees fragment vendor portfolios to avoid single-source dependency in telemetry infrastructure. Three archetypes dominate: FDA-cleared AI algorithm specialists, legacy diagnostic equipment manufacturers with bedside-to-ambulatory integration, and cloud-connected wearable pure-plays. Competitive moves concentrate on API-first interoperability capabilities and backward integration into lithium-polymer power management.
Within the AI-enabled tier, AliveCor exemplifies direct-to-consumer cardiac screening dominance through algorithm differentiation. GE Healthcare and Philips Healthcare anchor hospital procurement channels with integrated telemetry infrastructure spanning bedside to ambulatory settings. These three occupy positions across the pricing spectrum from premium subscription-linked platforms to standard diagnostic hardware, reflecting divergent capital intensity strategies between cloud-connected specialists and legacy equipment manufacturers.
| Leading Market Players |
|---|
| AliveCor, Inc. |
| GE Healthcare |
| OMRON Corporation |
| Philips Healthcare |
| Dimetek Digital Medical Technologies Ltd. |
| Zenicor Medical Systems |
| iRhythm Technologies, Inc. |
| Mindray Medical International Limited |
| Schiller AG |
| Others |
Value Network & Pricing Analysis
Multi-year lithium-polymer supply contracts in East Asia anchor scale economies that compress unit costs for wearable device manufacturers while simultaneously raising price floors for smaller entrants lacking procurement leverage. These scale dynamics concentrate supply chain power among incumbent battery cell producers, translating into tiered hardware pricing that separates FDA-cleared algorithm platforms from commoditized diagnostic equipment.
Pricing Analysis
After-sales service revenue through remote patient monitoring subscriptions drives lifetime value for telemetry system vendors. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared AI platforms from CE-marked portable monitors and unbranded consumer wearables. Cost compression in diagnostic equipment tiers is intensifying because hospital procurement committees unbundle hardware from software subscriptions. Home care buyers in Germany and Japan exhibit highest price sensitivity, while United States integrated health systems prioritize algorithm accuracy over hardware cost.
Supply Chain Analysis
China and South Korea anchor lithium-polymer cell production for multi-day continuous monitoring capabilities. Japan supplies precision analog front-end components for signal amplification circuits. Taiwan concentrates Bluetooth Low Energy chipset fabrication. The supply chain draws from cobalt and lithium raw material streams subject to commodity price volatility. Single-source vulnerability in East Asian battery cell production creates geopolitical exposure. Distribution runs through direct-to-consumer pharmacy channels and hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The single lead ECG equipment market sits in a reimbursement-driven cyclical upswing as Medicare CPT code expansion for remote physiological monitoring refreshes procurement budgets across United States health systems.
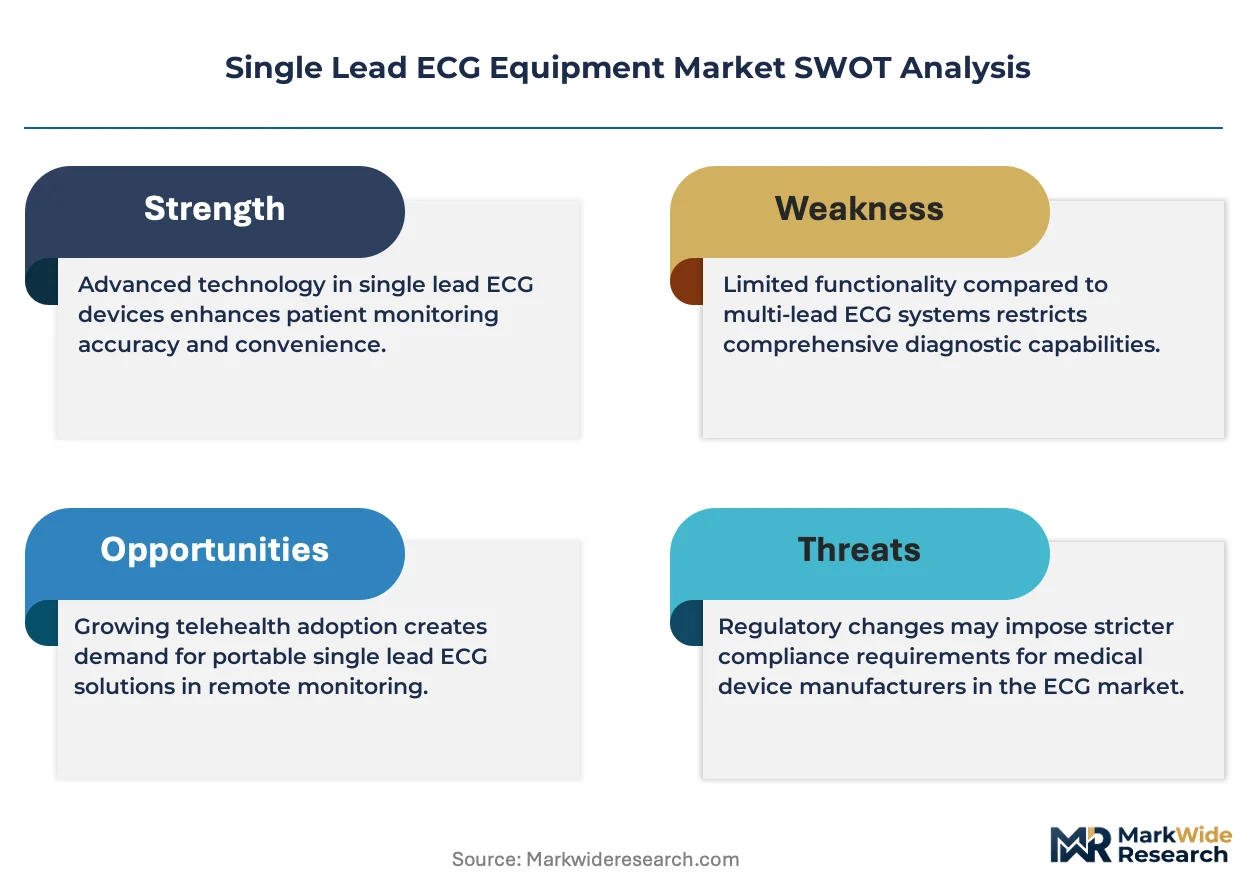
For Market Incumbents: Consolidate telemetry infrastructure positions through backward integration into lithium-polymer power management and API-first interoperability investments that resist unbundling by hospital procurement committees. Cloud-connected wearable pure-plays threaten legacy diagnostic equipment margins by collapsing wellness-clinical boundaries. Certification investment in FDA 510(k) algorithm clearance remains the priority defensive lever. For New Entrants and Emerging Players: Differentiate on AI-ECG convergence for predictive arrhythmia detection that extends beyond reactive diagnostic models. India's underpenetrated rural telehealth platforms and employer wellness programs in sports medicine clinics represent the most penetrable white-space targets. Pharmacy retail partnerships in Germany's Apotheken network offer established go-to-market infrastructure for CE-marked preventive screening tools. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-connected wearable specialists with FDA-cleared algorithm pipelines and FHIR-compliant data exchange capabilities over legacy hardware manufacturers facing commoditization pressure. Long-term viability across the 5-10 year window hinges on subscription revenue durability and regulatory moat maintenance. The signal to monitor is reimbursement code recalibration by United States payors between episodic diagnostic and longitudinal surveillance coverage thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined pre-certification for AI-enabled arrhythmia detection accelerates portable device commercialization timelines. |
| CE Marking Under EU MDR | Harmonized clinical validation requirements filter undercapitalized entrants and consolidate European competitive positions. |
| Hospital System Partnership | Integrated health network contracts anchor telemetry infrastructure revenue through subscription-linked remote monitoring platforms. |
| Software Companion Development | FHIR-compliant EHR integration capabilities satisfy procurement committee interoperability requirements for wearable data ingestion. |
| Reimbursement Strategy | Medicare CPT code alignment for remote physiological monitoring shifts procurement toward longitudinal cardiac surveillance models. |
Research Methodology
Desk research of FDA 510(k) clearance databases, EU MDR notified body decisions, and hospital procurement contract filings preceded structured interviews with biomedical engineers, GPO contracts managers, and remote patient monitoring platform executives. Secondary validation drew from CMS Medicare reimbursement data, PMDA consultation minutes, and METI wireless transmission standards documentation. Bottom-up unit economics modeling and top-down market sizing triangulated volume estimates across product type and end-user segments.
Variance decomposition across the projection horizon isolates volume drivers by portable monitor, wearable device, and telemetry system categories. Technology layer segmentation modeled cloud connectivity, wireless transmission, signal processing, and data analytics dimensions. CAGRs derived from installed base growth rates and replacement cycle analysis. Forecast inputs incorporated lithium-polymer battery efficiency curves and Bluetooth Low Energy penetration trajectories in ambulatory care settings.
Decision-makers should treat outputs as directional under assumptions of sustained Medicare reimbursement expansion and stable East Asian battery cell supply; material deviation in either would warrant model refresh. Specific risk factors include EU AI Act compliance recalibration for algorithm-based arrhythmia classification and electromagnetic compatibility standard revisions by the FCC. Recalibration cycles align with material shifts in payor coverage thresholds and MDR notified body guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Medical Manifolds Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Blood Warmers Market
Medical Devices
China Respiratory Devices Market
Medical Devices
Batteries for Skin Patches Market
Medical Devices
Neuromodulation Devices Market
Medical Devices
Medical Mobility Aid Market
Medical Devices
Global Doppler Ultrasound Systems Market
Medical Devices
APAC AMH Market
Medical Devices
Supraglottic Device Market
Medical Devices
Europe Breast Implant Market