
 Asia Pacific Portable X-Ray Devices Market | 2026-2036
Asia Pacific Portable X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Portable X-Ray Devices Market Outlook
Amorphous selenium is shifting toward amorphous silicon and cesium iodide scintillator combinations in flat-panel detector construction, lowering unit costs for mid-range portable systems. Fujifilm Holdings Corporation leverages its in-house sensor fabrication to control detector supply chains across Japan and Southeast Asia. Canon Inc. competes through vertical integration into tube and generator manufacturing, sustaining margin resilience against component volatility. Koninklijke Philips N.V. dominates wireless connectivity protocols, anchoring its position in premium mobile radiography suites.
Asia Pacific portable X-ray devices comprise self-contained, battery-powered or mains-connected imaging systems producing diagnostic radiographs outside fixed radiology departments, typically weighing under 150 kg with digital flat-panel detectors replacing film-screen cassettes. These systems enable point-of-care trauma assessment, bedside cardiac evaluation, and field emergency response where patient transport risks outweigh stationary imaging benefits. Digital X-Ray leads product type revenue due to replacement cycles in Japanese and Australian hospital networks, while wireless technology captures the fastest expansion as 5G infrastructure spreads across South Korean and Chinese diagnostic centers. Home Care remains nascent but carries outsized margin potential where regulatory clarity on remote supervision emerges.
Japan's PMDA and South Korea's MFDS enforce electromagnetic compatibility and radiation exposure standards that shape product registration timelines and design requirements for portable systems. China's NMPA implements distinct clinical trial obligations for novel digital detector architectures, filtering market access for non-domestic manufacturers. India's CDSCO and BIS coordinate on medical electrical safety certifications under evolving harmonization with IEC 60601-1-3. Stakeholders must monitor whether ASEAN medical device directive convergence accelerates or fragments approval pathways across Indonesia, Thailand, and Vietnam.
Market Dynamics
China's NMPA is compressing registration timelines for wireless-capable portable X-ray systems while India's PLI scheme for medical electronics forces local assembly commitments from foreign manufacturers seeking market access.
Growth Catalysts
- PLI Scheme for Medical Electronics:India's production-linked incentive scheme mandates domestic manufacturing thresholds, pulling assembly capacity into Gujarat and Tamil Nadu industrial corridors.
- 5G Infrastructure Deployment:South Korean and Chinese diagnostic centers are retrofitting mobile radiography suites with real-time image transmission capability.
- Rural Clinic Digitization:China's tier-two city hospital upgrades and village-level health station modernization programs are replacing film-screen systems with battery-powered digital units.
Market Restraints
- Detector Material Cost Volatility:Cesium iodide scintillator and amorphous silicon substrate prices fluctuate with semiconductor foundry capacity constraints.
- Supply Concentration in Japanese Sensor Fabrication:Flat-panel detector manufacturing clusters heavily in Kyushu and Tohoku regions, creating single-source vulnerability.
- Ionizing Radiation Exposure Limits:Japan's PMDA and South Korea's MFDS enforce strict electromagnetic compatibility testing that extends product validation cycles.
Strategic Opportunities
- Home Care Regulatory Clarity:Australia's TGA and Japan's PMDA are drafting remote supervision protocols for bedside imaging in residential settings.
- Emergency Services Expansion:Southeast Asian hospital networks are procuring wireless-capable units for field trauma response and disaster medical teams.
- AI-Assisted Image Interpretation:Machine learning integration with portable systems is creating new revenue streams in point-of-care diagnostic workflows.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Field service technicians trained in digital detector calibration and tube maintenance remain concentrated in Tokyo, Seoul, and Shanghai metropolitan areas.
- Legacy System Integration Complexity:Hospital information systems in Vietnam, Indonesia, and Philippines require custom DICOM middleware to connect new portable units with existing PACS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Portable X-Ray Devices Market |
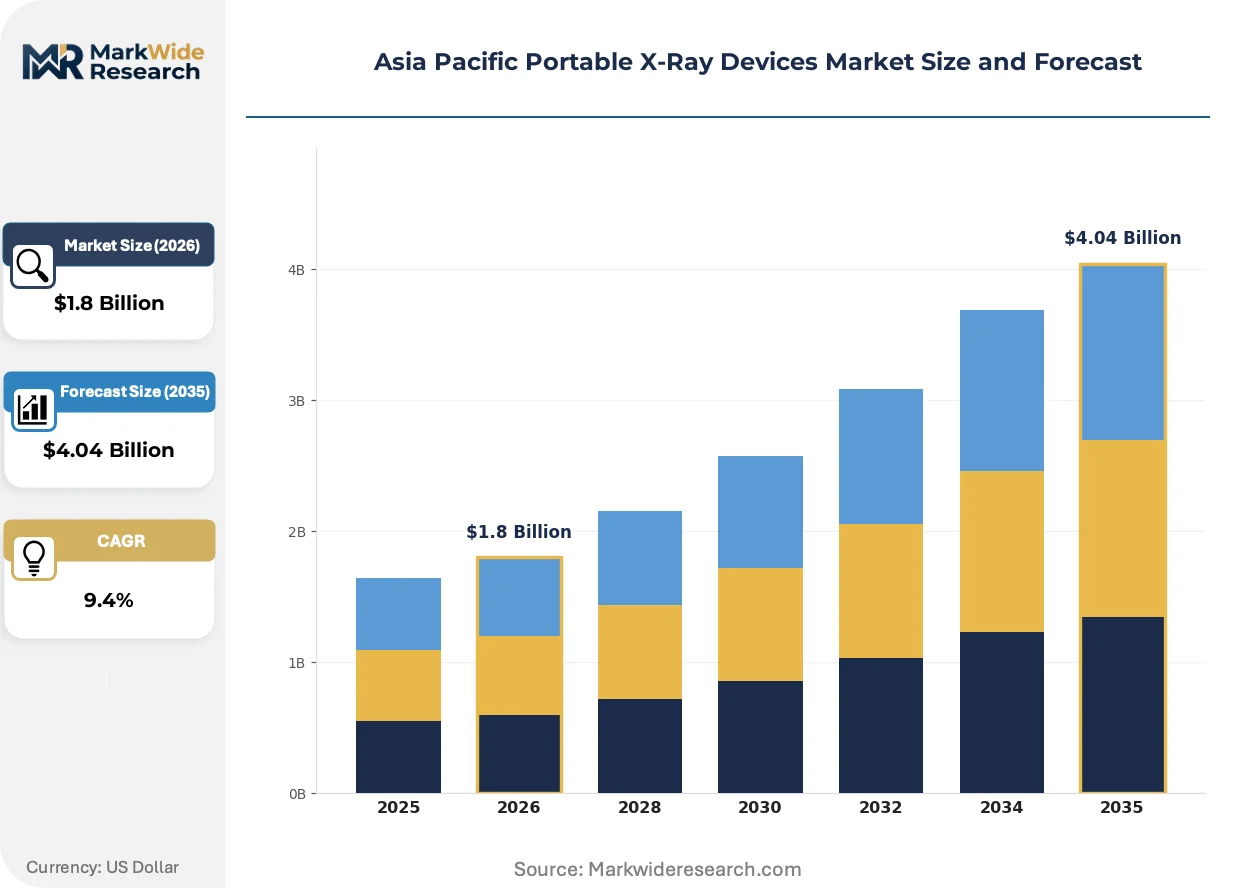
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital X-Ray, Analog X-Ray, Fluoroscopy, Others End User: Hospitals, Diagnostic Centers, Research Facilities, Home Care Technology: Portable, Stand-Alone, Wireless, Mobile Application: Emergency Services, Trauma Diagnosis, Cardiac Imaging, Preventive Care |
| Companies Covered | Canon Inc., Carestream Health Inc., Fujifilm Holdings Corporation, GE Healthcare, Hitachi Ltd, Koninklijke Philips N.V., Samsung, Shimadzu Corporation, Siemens Healthineers, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Portable X-Ray Devices Market Strategic Shifts
Wireless connectivity protocols and solid-state detector architectures are collapsing the distinction between fixed radiology departments and point-of-care imaging, enabling new deployment models across emergency medicine and rural health delivery.
Flat-panel detectors using amorphous silicon and cesium iodide scintillator combinations are decentralizing diagnostic radiography from centralized hospital radiology suites to bedside and field locations. Emergency departments across Australian and Japanese hospital networks are adopting these systems for trauma assessment where patient transport risks outweigh stationary imaging benefits. This shift is decentralizing capital equipment purchasing decisions from radiology department heads to emergency medicine chiefs and rural clinic administrators.
China's NMPA has implemented distinct clinical trial obligations for novel digital detector architectures, filtering market access for non-domestic manufacturers seeking approval for wireless-enabled systems. The regulation requires local electromagnetic compatibility testing and radiation safety verification that adds six to nine months to registration timelines. Foreign manufacturers are responding by establishing captive testing facilities in Suzhou and Shenzhen industrial parks to accelerate compliance documentation.
Equipment leasing and managed service contracts are displacing capital purchase models among mid-tier Chinese and Indian hospital networks facing working capital constraints. Distributors in Mumbai and Bangalore are bundling maintenance, detector replacement, and software upgrades into per-scan pricing structures. This shift is most visible in India's private hospital chains expanding into tier-three cities where upfront equipment costs previously blocked market entry.
Asia Pacific Portable X-Ray Devices Market Segmentation
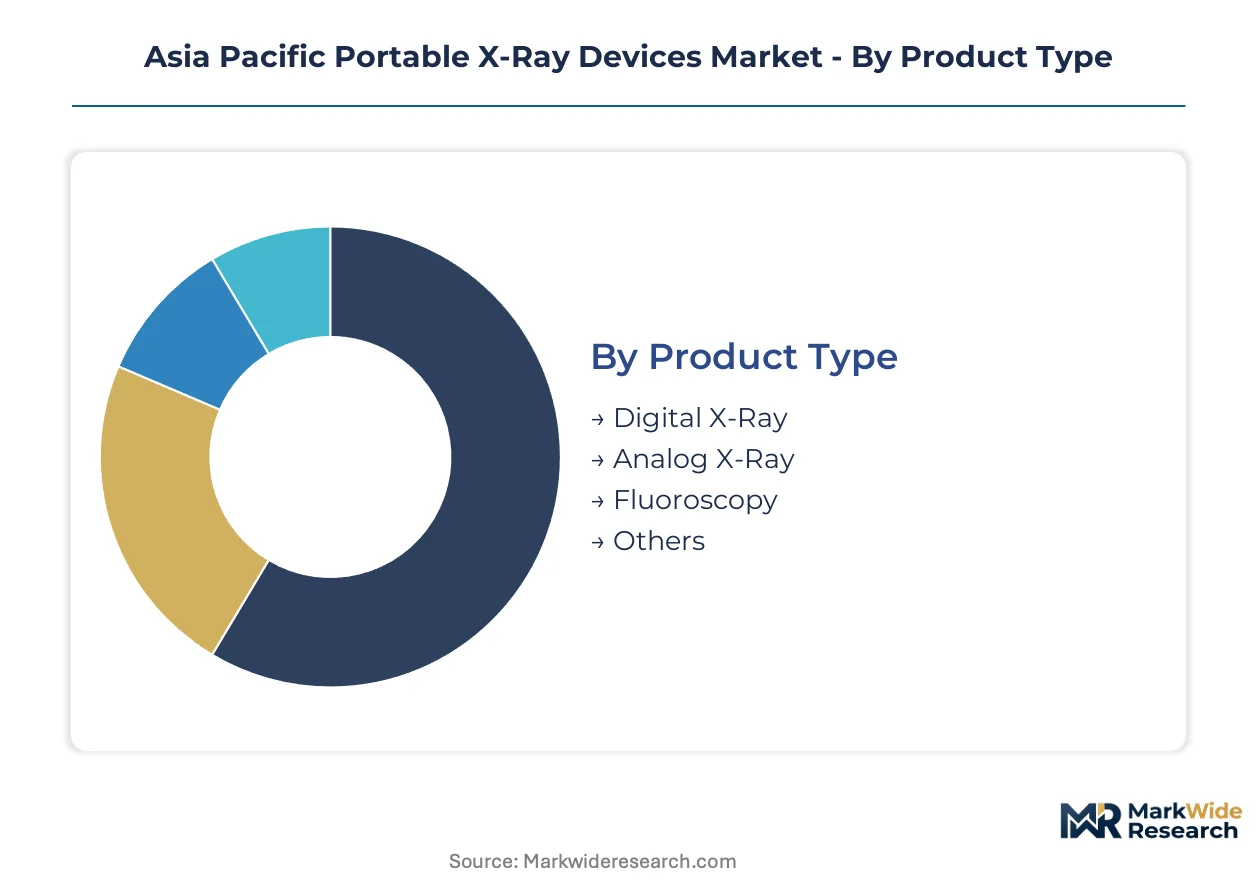
Portable X-ray segmentation in Asia Pacific reflects divergent equipment specifications across hospital procurement tiers, rural clinic budgets, and emergency response protocols. Understanding these divides clarifies where component suppliers, service networks, and regulatory compliance resources must concentrate.
Product Type:
Detector architecture and image processing capability separate premium digital systems from legacy analog alternatives across Japanese, Australian, and Chinese procurement channels.
- Digital X-Ray:Flat-panel detectors using amorphous silicon and cesium iodide scintillator combinations dominate replacement cycles in Japanese and Australian hospital networks. China's tier-two city hospital upgrades and rural clinic digitization programs are pulling battery-powered digital units into village-level health stations previously dependent on film-screen systems.
- Analog X-Ray:Film-screen cassette systems persist in cost-constrained segments of Vietnam, Indonesia, and Philippines where PACS infrastructure remains underdeveloped. Procurement concentrates in provincial government tenders with extended payment terms that favor established distributors with working capital depth.
- Fluoroscopy:Real-time imaging capability for cardiac catheterization guidance and interventional procedures. Demand clusters in South Korean and Chinese cardiac centers retrofitting mobile C-arm configurations.
- Others:Specialized veterinary and dental variants with modified collimation and exposure parameters. Niche procurement through Australian agricultural equipment channels and Japanese pet hospital networks.
Mature deployment sits with Digital X-Ray. Newer deployment is concentrated in Fluoroscopy as interventional cardiology expands across Chinese and South Korean metropolitan centers.
End User:
Capital availability and image throughput requirements stratify purchasing authority from radiology department heads to emergency medicine chiefs and rural clinic administrators.
- Hospitals:Emergency departments across Australian and Japanese networks are adopting wireless-capable systems for trauma assessment where patient transport risks outweigh stationary imaging benefits. India's private hospital chains expanding into tier-three cities are driving equipment leasing and managed service contract adoption.
- Diagnostic Centers:High-volume outpatient imaging operations in South Korean and Chinese urban centers prioritize throughput and DICOM connectivity. Procurement emphasizes detector replacement programs and software upgrade bundles.
- Research Facilities:Academic medical centers in Tokyo, Seoul, and Shanghai evaluating novel detector architectures for clinical trial endpoints. NMPA's distinct clinical trial obligations for wireless-enabled systems filter market access for foreign manufacturers in this segment.
- Home Care:Residential bedside imaging remains nascent pending regulatory clarity from Australia's TGA and Japan's PMDA on remote supervision protocols. Australia's aging-in-place policies and Japan's rural depopulation create latent demand structures.
Procurement authority concentrates in Hospitals. Margin expansion potential sits with Home Care as regulatory frameworks mature.
Technology:
Connectivity architecture and power autonomy determine deployment flexibility across fixed departments, bedside locations, and field emergency response.
- Wireless:5G infrastructure deployment across South Korean and Chinese diagnostic centers enables real-time image transmission to radiologist workstations. Southeast Asian hospital networks are procuring these units for field trauma response and disaster medical teams.
- Mobile:Motorized transport systems for intra-hospital relocation between emergency departments, operating theaters, and intensive care units. Standard configuration in Japanese and Australian tertiary facilities.
- Portable:Self-contained battery-powered or mains-connected systems under 150 kg for point-of-care deployment. China's rural clinic digitization programs favor this configuration for village health station electrification constraints.
- Stand-Alone:Fixed-position units for dedicated imaging rooms with hardwired power and network connections. Predominant in Indian diagnostic centers with stable infrastructure and high daily throughput requirements.
Established deployment sits with Portable. Steepest expansion trajectory belongs to Wireless as 5G network coverage extends across South Korean and Chinese diagnostic infrastructure.
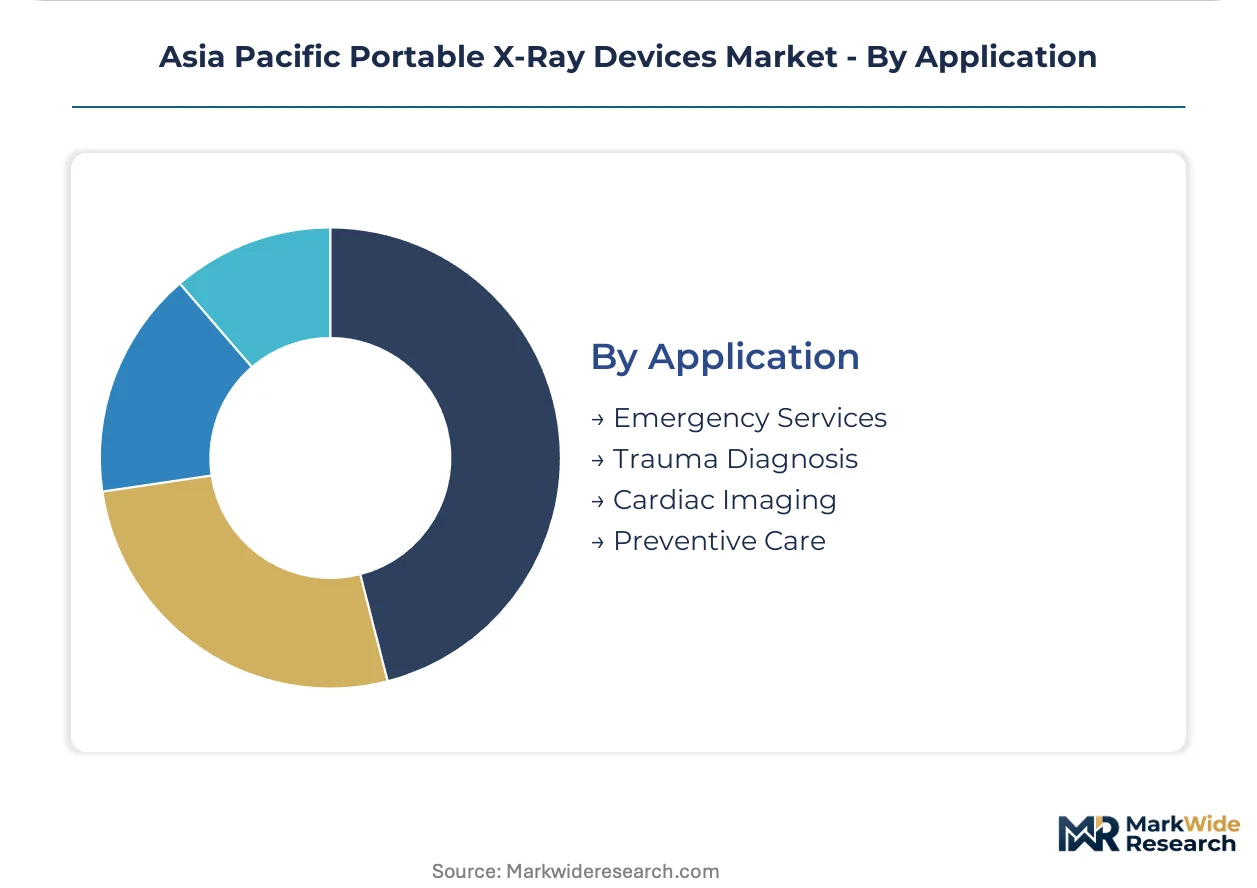
Application:
Clinical urgency and reimbursement structures shape equipment specification requirements from emergency response through preventive screening programs.
- Emergency Services:Field trauma assessment and disaster medical team deployment across Southeast Asian hospital networks. Equipment specifications prioritize rapid power-on, battery endurance, and ruggedized transport cases.
- Trauma Diagnosis:Bedside skeletal and thoracic imaging where patient transport risks outweigh stationary imaging benefits. Australian and Japanese emergency departments are retrofitting mobile radiography suites with these capabilities.
- Cardiac Imaging:Portable chest radiography for acute cardiac evaluation and post-interventional monitoring. Demand concentrates in Chinese tier-two city hospital cardiology department expansions.
- Preventive Care:Community screening programs for tuberculosis and occupational lung disease in Indian and Indonesian public health initiatives. Procurement emphasizes cost per scan and simplified operator training requirements.
Volume concentration sits with Trauma Diagnosis. Emerging deployment is accelerating in Preventive Care as national tuberculosis elimination programs expand across India and Indonesia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical electronics has concentrated assembly capacity in Gujarat and Tamil Nadu special economic zones, pulling foreign manufacturers into captive production commitments. China's NMPA registration reforms and South Korea's 5G infrastructure buildout are reshaping deployment patterns across the region.
China
Tier-two city hospital upgrades and rural clinic digitization programs drive procurement of battery-powered digital units for village health stations. NMPA mandates local electromagnetic compatibility testing and radiation safety verification, adding six to nine months to registration timelines for wireless-enabled systems. Suzhou and Shenzhen industrial parks host captive testing facilities established by foreign manufacturers seeking accelerated compliance documentation.
Japan
Emergency departments in Tokyo and Osaka metropolitan networks adopt wireless-capable systems for trauma assessment where patient transport risks outweigh stationary imaging benefits. PMDA enforces strict electromagnetic compatibility and radiation exposure standards that shape product registration timelines and detector design requirements. Kyushu and Tohoku regions concentrate flat-panel detector manufacturing clusters, creating single-source supply vulnerability for regional procurement.
India
Private hospital chains expanding into tier-three cities drive equipment leasing and managed service contract adoption to circumvent upfront capital constraints. CDSCO and BIS coordinate on medical electrical safety certifications under evolving harmonization with IEC 60601-1-3 standards. Gujarat and Tamil Nadu industrial corridors absorb PLI scheme-mandated domestic manufacturing thresholds for foreign assembly operations.
South Korea
Diagnostic centers in Seoul and Busan retrofit mobile radiography suites with real-time image transmission capability as 5G network coverage extends. MFDS enforces electromagnetic compatibility testing protocols that extend product validation cycles for portable system approvals. Daegu-Gyeongbuk region hosts cardiac center expansions driving demand for mobile C-arm fluoroscopy configurations.
Australia
Aging-in-place policies and rural depopulation create latent demand structures for residential bedside imaging pending regulatory clarity. TGA drafts remote supervision protocols for home care deployment where margin expansion potential exceeds hospital procurement channels. New South Wales and Victoria emergency services expand wireless-capable unit procurement for field trauma response and disaster medical team deployment.
Asia Pacific Portable X-Ray Devices Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium wireless systems consolidating around integrated technology providers while mid-range portable units fragment across regional assembly operations. The vendor base organizes into three strategic archetypes: diversified imaging conglomerates with captive detector fabrication, precision electronics specialists leveraging semiconductor supply chain proximity, and emerging domestic assemblers capitalizing on local content requirements. M&A activity concentrates on detector technology acquisitions and strategic partnerships for 5G connectivity integration.
Among Japan-based imaging conglomerates, Fujifilm Holdings Corporation and Canon Inc. exemplify divergent integration strategies—Fujifilm leverages in-house sensor fabrication for supply chain control while Canon anchors its position through backward integration into tube and generator manufacturing. Koninklijke Philips N.V. occupies the premium wireless connectivity tier across Southeast Asian hospital networks. These three represent distinct competitive positioning archetypes: materials-integrated fabrication, component-backward integration, and protocol-dominant system architecture.
| Leading Market Players |
|---|
| Canon Inc. |
| Carestream Health Inc. |
| Fujifilm Holdings Corporation |
| GE Healthcare |
| Hitachi Ltd |
| Koninklijke Philips N.V. |
| Samsung |
| Shimadzu Corporation |
| Siemens Healthineers |
| Others |
Value Chain & Pricing Dynamics
Cesium iodide scintillator spot pricing volatility cascades through Asia Pacific portable X-ray manufacturing tiers, compressing margins for mid-range system assemblers while amplifying pricing power for Japanese and South Korean detector fabricators with captive material sourcing.
Pricing Analysis
Lead-time-driven pricing separates procurement tiers across Asia Pacific hospital networks, with premium rates commanding six-week delivery guarantees for wireless-capable systems while spot inventory of analog units trades at discounted clearing levels. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution grade and NMPA registration status. Pricing pressure stems from India's PLI scheme forcing local assembly cost absorption. Tier-three city hospital chains exhibit highest price sensitivity, while Australian emergency services procurement shows lowest elasticity due to trauma response mandates.
Supply Chain Analysis
Single-source vulnerability sits with Kyushu and Tohoku flat-panel detector fabrication clusters, where seismic disruption or foundry allocation shifts would cascade through regional procurement channels. Manufacturing draws from Japan, South Korea, and China for amorphous silicon substrates, cesium iodide crystals, and tube generator assemblies. Tariff exposure concentrates in semiconductor component flows subject to export control classifications. Distribution runs through Mumbai, Singapore, and Shanghai medical device distributors with captive service technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific portable X-ray markets sit in active technology transition, with solid-state flat-panel detectors displacing legacy film-screen cassette systems across Chinese and Indian procurement channels.
For Market Incumbents: Hedge detector supply exposure through dual-sourcing arrangements with secondary amorphous silicon substrate vendors outside Kyushu manufacturing clusters. Prioritize NMPA electromagnetic compatibility pre-certification investments to compress registration timelines against emerging domestic Chinese competitors. Defensive positioning requires backward integration into tube generator manufacturing or captive cesium iodide scintillator supply agreements. For New Entrants and Emerging Players: India's PLI scheme for medical electronics opens a window for Gujarat and Tamil Nadu assembly operations targeting tier-three city hospital leasing contracts. White-space concentration sits with wireless-enabled systems for Southeast Asian emergency services expansion and home care regulatory clarity in Australia. Go-to-market execution should bundle per-scan pricing with field technician training to overcome biomedical engineering talent scarcity in provincial Indonesian and Vietnamese markets. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier digital system assemblers in India facing working capital constraints from PLI localization mandates. Long-term viability hinges on detector technology acquisition targets with NMPA registration pathways already established. Watch for TGA remote supervision protocol finalization as inflection signal for home care margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Registration Acceleration | Captive testing facilities in Suzhou and Shenzhen compress six-to-nine-month compliance timelines for wireless systems. |
| 5G Connectivity Integration | Real-time image transmission capability anchors premium positioning in South Korean and Chinese diagnostic centers. |
| Detector Technology Acquisition | Amorphous silicon and cesium iodide scintillator combinations lower unit costs for mid-range portable systems. |
| Managed Service Contract Expansion | Per-scan bundling in Indian tier-three cities circumvents upfront capital constraints blocking market entry. |
| AI-Assisted Image Interpretation | Machine learning integration creates new revenue streams in point-of-care diagnostic workflows across Japanese networks. |
Study Parameters
Document review covered NMPA registration filings, MFDS electromagnetic compatibility protocols, and Indian PLI scheme administrative guidelines, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and field service technicians. Secondary validation drew from customs trade databases, hospital procurement registries, and semiconductor foundry capacity disclosures. Bottom-up equipment shipment estimates triangulated against top-down healthcare infrastructure spending allocations.
Cross-referencing historical replacement cycle patterns with panel input from distributor inventory managers and OEM regional sales directors shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include detector architecture, connectivity protocol, end-user procurement tier, and application urgency level. CAGRs were derived from installed base evolution and average selling price trajectory assumptions, with specific weighting for 5G infrastructure deployment schedules and rural electrification program timelines.
The model assumes a particular technology adoption path; alternative pathways for wireless flat-panel detector architectures would alter the outlook if NMPA registration reforms accelerate or semiconductor substrate shortages persist. Forecasts reflect assumptions about PLI scheme compliance thresholds and ASEAN medical device directive convergence timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Corneal Surgery Devices Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Global Medical Footwear Market
Medical Devices
Nerve Ablation Devices Market
Medical Devices
Syringeless Injector Market
Medical Devices
Membrane Oxygenators Market
Medical Devices
Infant Oxygen Hoods Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
Accelerometers Medical Sensors Market