
 Europe Sinus Tissue Resection Market | 2026-2036
Europe Sinus Tissue Resection Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sinus Tissue Resection Market Intelligence
The capital-intensity divergence between integrated manufacturers and instrument-only suppliers is rotating competitive advantage toward firms with in-house energy-platform development. Medtronic leverages its broad electrosurgical portfolio to bundle sinus devices with capital equipment, sustaining pricing power across European hospital systems. Stryker Corporation anchors its position through specialized ENT visualization systems that complement tissue resection workflows. Karl Storz competes on optical precision, dominating rigid endoscope supply to academic medical centers in Germany and Switzerland.
Europe sinus tissue resection encompasses surgical removal of pathological nasal and paranasal sinus tissue using powered instrumentation, electrocautery, or laser ablation, typically performed under endoscopic visualization with irrigation suction systems maintaining operative field clarity. The primary purpose is restoring sinus ventilation and mucociliary clearance in patients with medically refractory inflammatory or neoplastic disease. Electrosurgical instruments command the largest revenue share within product type segmentation due to reusable generator compatibility and established reimbursement codes, while radiofrequency technology represents the fastest-expanding modality as cold ablation protocols reduce perioperative bleeding and accelerate recovery in ambulatory settings. Hospitals absorb the majority of procedure volume, though ambulatory surgical centers are capturing growing case migration as regional anesthesia protocols and same-day discharge pathways mature.
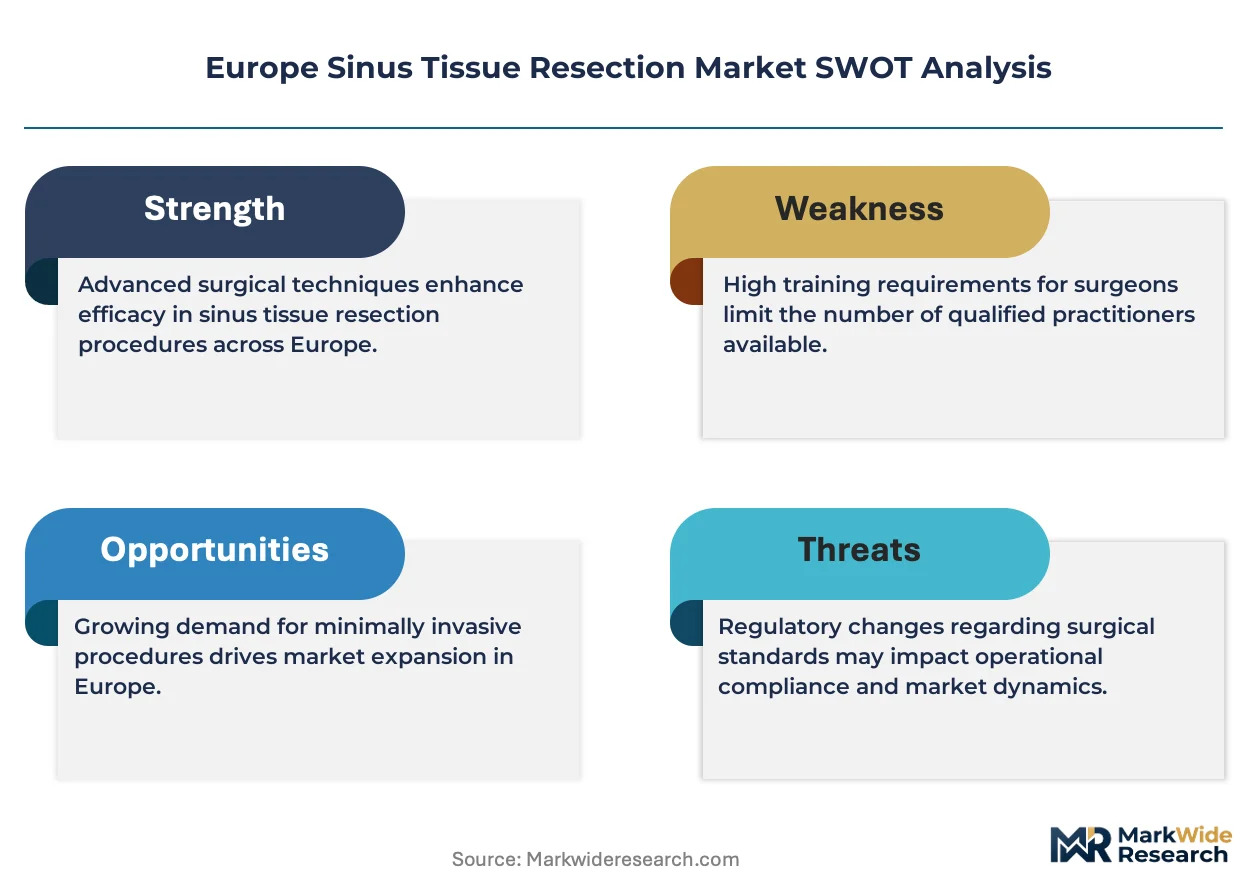
The EU Medical Device Regulation and CE marking framework administered by notified bodies in Germany, France, and the Netherlands are elevating clinical data requirements for novel sinus resection devices, extending time-to-market for innovators while consolidating advantage among established manufacturers with robust quality management systems. EMA guidance on biocompatibility testing and post-market surveillance obligations further shapes product development priorities, particularly for single-use electrosurgical tips and disposable tissue graspers. Stakeholders must monitor evolving HTA assessment methodologies across France's HAS, Germany's G-BA, and England's NICE to anticipate reimbursement thresholds that will determine commercial viability of next-generation energy platforms.
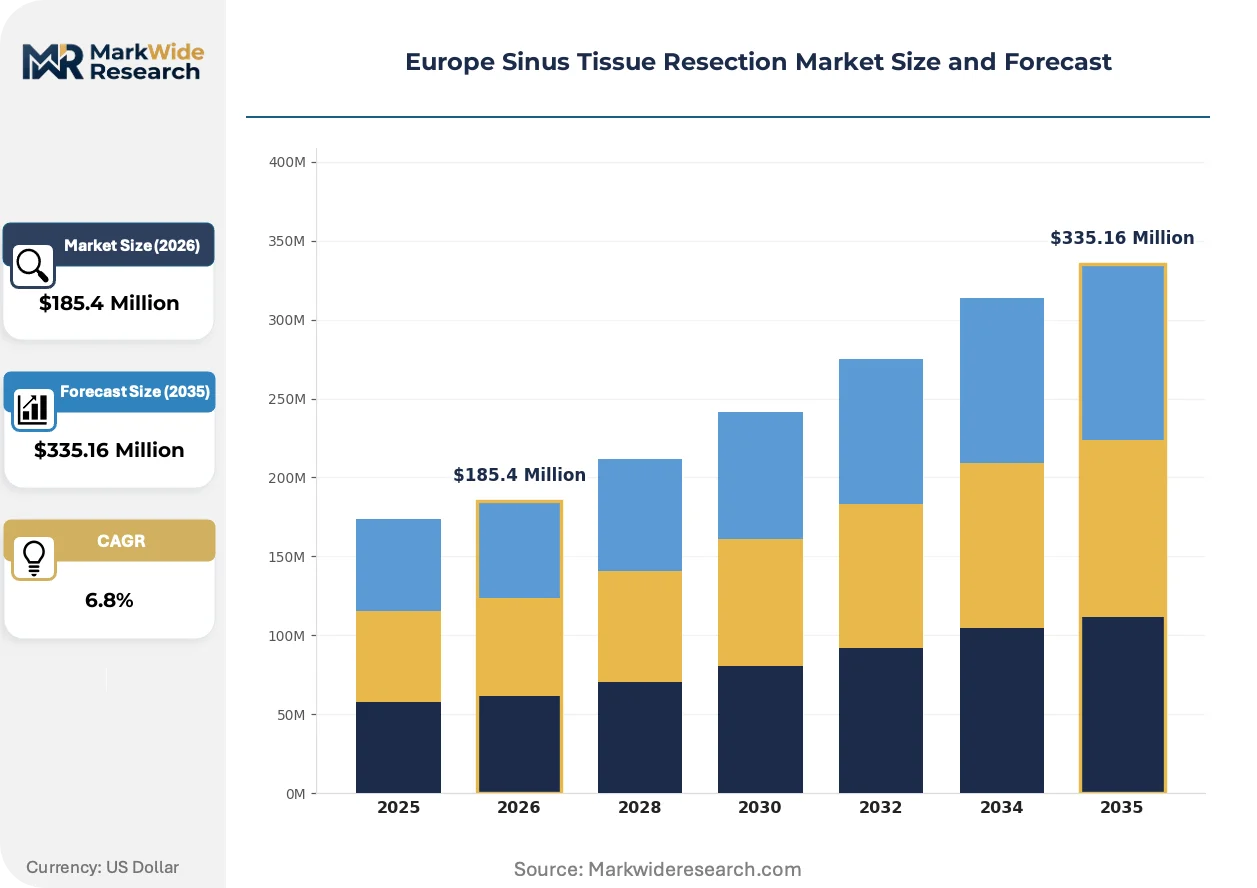
Market Dynamics
EU Medical Device Regulation clinical evidence requirements are compressing time-to-market for novel sinus resection platforms while advantaging manufacturers with established quality management systems and post-market surveillance infrastructure.
Growth Catalysts
- Ambulatory migration:Same-day discharge protocols across German and French outpatient ENT centers are expanding addressable procedure volume beyond traditional hospital settings.
- MDR transition completion:Stabilized CE marking pathways under the EU Medical Device Regulation are restoring predictable market access timelines for compliant device portfolios.
- Radiofrequency cold ablation:Reduced perioperative bleeding profiles are accelerating adoption in academic medical centers prioritizing enhanced recovery pathways.
Market Restraints
- Capital equipment concentration:Generator-tethered electrosurgical systems lock buyers into single-vendor consumable ecosystems, limiting instrument supplier switching.
- Notified body bottleneck:Capacity constraints at German and Dutch designated bodies extend technical documentation review cycles for novel energy platforms.
- Reimbursement heterogeneity:Divergent HTA methodologies across France's HAS, Germany's G-BA, and England's NICE fragment commercialization strategy requirements.
Strategic Opportunities
- Swiss and Austrian expansion:Underpenetrated ENT specialty networks in Zurich, Geneva, and Vienna present first-mover potential for integrated visualization-resection platforms.
- Single-use instrument conversion:Cross-contamination liability concerns are driving replacement cycles for reusable forceps and suction instruments in high-volume centers.
- Digital surgery integration:Navigation-augmented endoscopic workflows are converging with AI-powered anatomical mapping to enable precision resection in revision cases.
Industry Challenges
- Biocompatibility testing timelines:Extended cytotoxicity and sensitization studies under EMA guidance delay novel polymer instrument launches by 12-18 months.
- OR integration complexity:Legacy irrigation-suction towers from competing vendors resist seamless connectivity with next-generation radiofrequency generators.
- Specialized sales force requirements:Dual competency in ENT surgical workflow and capital equipment financing constrains scalable commercial hiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sinus Tissue Resection Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resectoscopes, Electrosurgical Instruments, Biopsy Forceps, Tissue Graspers End User: Hospitals, Ambulatory Surgical Centers, ENT Clinics, Research Institutes Technology: Light-Assisted Techniques, Radiofrequency, Laser Surgery, Conventional Surgery Application: Chronic Rhinosinusitis, Nasal Polyps, Sinus Tumors, Deviated Septum |
| Companies Covered | Medtronic, Stryker Corporation, B. Braun Melsungen, Integra Lifesciences, Karl Storz, Olympus Corporation, Intellus Medical, Inc., Bausch & Lomb Incorporated, Smith & Nephew, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sinus Tissue Resection Market Strategic Shifts & Innovations
Technology convergence between navigation systems and cold ablation modalities is redefining procedural standards while regulatory data requirements reshape competitive entry barriers.
Radiofrequency-based cold ablation technology is fragmenting the traditional electrocautery-dominated sinus resection landscape by enabling precise submucosal tissue removal with minimal thermal spread. German and French ambulatory surgical centers are adopting these platforms at accelerating rates for polypectomy and turbinate reduction procedures. The technology is fragmenting purchasing decisions as hospitals evaluate generator compatibility against standalone clinical outcomes.
EU Medical Device Regulation post-market surveillance obligations are elevating real-world evidence collection requirements for electrosurgical instruments and disposable tips. Manufacturers must now maintain active implant registries and periodic safety update reports beyond traditional adverse event reporting. Single-use instrument suppliers face disproportionate compliance burdens relative to reusable device incumbents with established quality management systems.
Hospital procurement committees are consolidating sinus device purchasing under centralized value-analysis frameworks that bundle capital equipment, disposables, and service contracts. Traditional distributor relationships are yielding to direct manufacturer partnerships with tier-one academic medical centers in Germany and the United Kingdom. This concentration is most visible in Bavaria and North Rhine-Westphalia, where integrated delivery networks negotiate multi-year platform commitments.
Europe Sinus Tissue Resection Market Segmentation
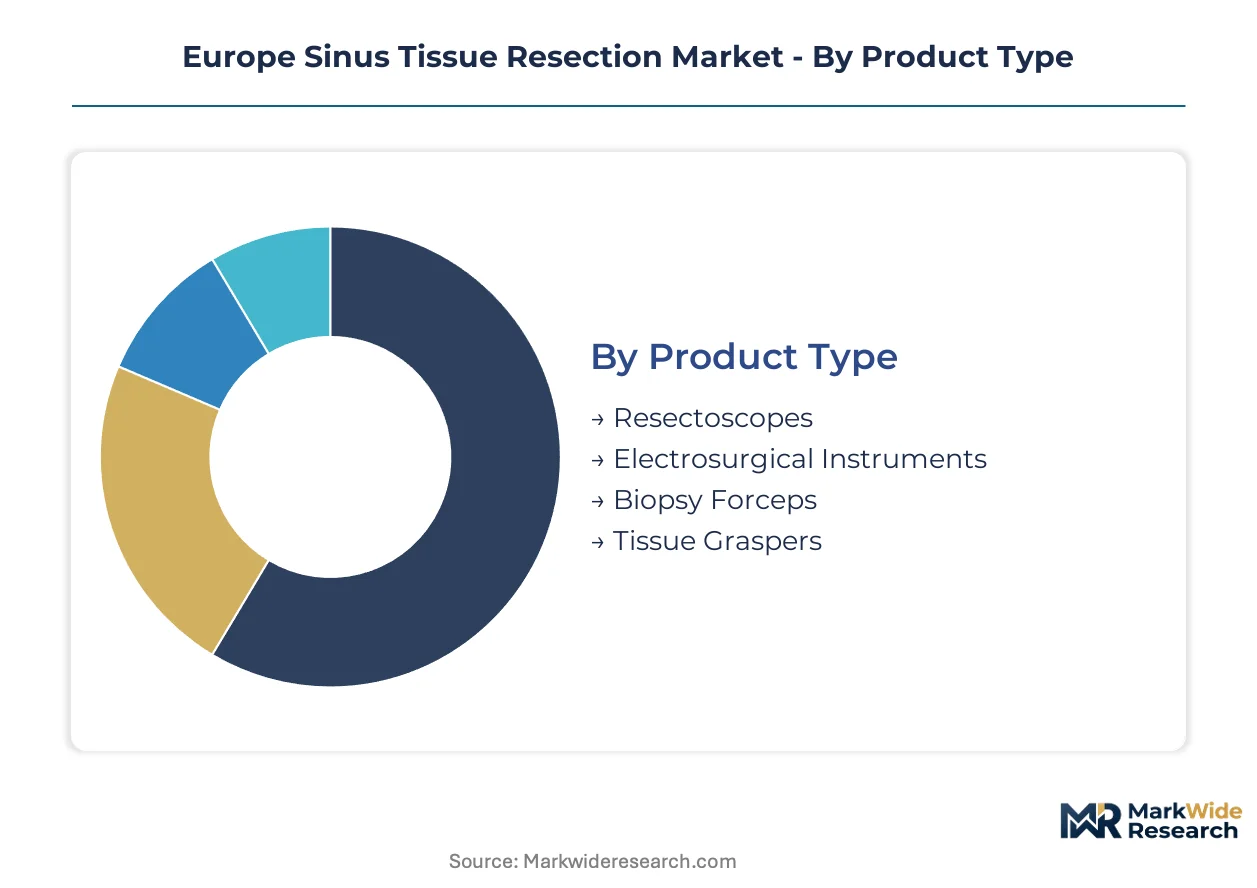
Segmentation in the Europe Sinus Tissue Resection Market reveals how procurement patterns diverge across care settings and energy modalities. Hospital procurement committees in Germany and France evaluate generator-tethered systems differently than ambulatory centers prioritizing standalone portability.
Product Type:
German and Austrian hospitals favor domestically manufactured electrosurgical platforms, while French and UK centers source more disposable instrument volumes from cross-border suppliers.
- Electrosurgical Instruments:These systems integrate reusable generators with disposable tips, enabling precise tissue cutting and coagulation through controlled electrical current. Demand concentrates in Bavarian and North Rhine-Westphalian hospital networks where bundled capital equipment contracts lock in multi-year consumable purchasing. The EU MDR's tightened biocompatibility requirements for single-use tips are extending replacement cycles for legacy generator systems.
- Resectoscopes:Powered rotary instruments with integrated suction irrigation maintain operative field clarity during polyp removal and turbinate reduction. Swiss and Austrian academic centers are expanding adoption of navigation-compatible resectoscope platforms for revision sinus surgery cases.
- Biopsy Forceps:These grasping instruments extract tissue specimens for histopathological analysis during diagnostic endoscopy procedures.
- Tissue Graspers:Articulated jaw designs enable atraumatic manipulation of delicate sinus mucosa during functional endoscopic sinus surgery.
Electrosurgical instruments command the established base. The steepest expansion runs through resectoscopes as navigation integration becomes standard in German academic centers.
End User:
Cost-tier stratification separates capital-intensive hospital installations from lean ambulatory configurations optimized for same-day discharge economics.
- Hospitals:Tertiary ENT departments in Germany, France, and the United Kingdom absorb the majority of complex revision cases and neoplastic resections. These institutions prioritize integrated visualization-resection platforms with navigation capability and comprehensive service contracts.
- Ambulatory Surgical Centers:German and French outpatient ENT facilities are capturing migratory case volume through regional anesthesia protocols and streamlined discharge pathways. Radiofrequency cold ablation platforms with reduced bleeding profiles accelerate throughput in these settings.
- ENT Clinics:Private practice settings in urban Swiss and Austrian markets perform diagnostic endoscopy and minor polypectomy procedures.
- Research Institutes:Academic medical centers in Heidelberg, Paris, and London evaluate novel energy modalities and biocompatibility profiles for next-generation instrument development.
Hospitals retain the procedural volume base. Ambulatory surgical centers are climbing the fastest as reimbursement incentives align with same-day discharge economics across German and French outpatient networks.
Technology:
Maturity gradients separate established electrocautery methods from emerging cold ablation modalities requiring new capital investment and surgeon retraining.
- Radiofrequency:Cold ablation technology enables submucosal tissue removal with minimal thermal spread to surrounding structures. French and German ambulatory centers are adopting these platforms at accelerating rates for turbinate reduction and polypectomy procedures where reduced perioperative bleeding supports enhanced recovery protocols.
- Light-Assisted Techniques:Endoscopic visualization systems with high-definition optical chains and integrated irrigation-suction towers define contemporary procedural standards. Karl Storz dominates rigid endoscope supply to academic medical centers in Germany and Switzerland through optical precision and established surgeon training programs.
- Laser Surgery:Coherent light energy enables precise mucosal ablation with minimal mechanical trauma in selected anatomical applications.
- Conventional Surgery:Traditional powered instrumentation without energy augmentation persists in cost-constrained settings and specific revision scenarios.
Light-assisted techniques anchor the installed base. Radiofrequency is gaining share fastest as cold ablation protocols reduce complications and accelerate ambulatory throughput.
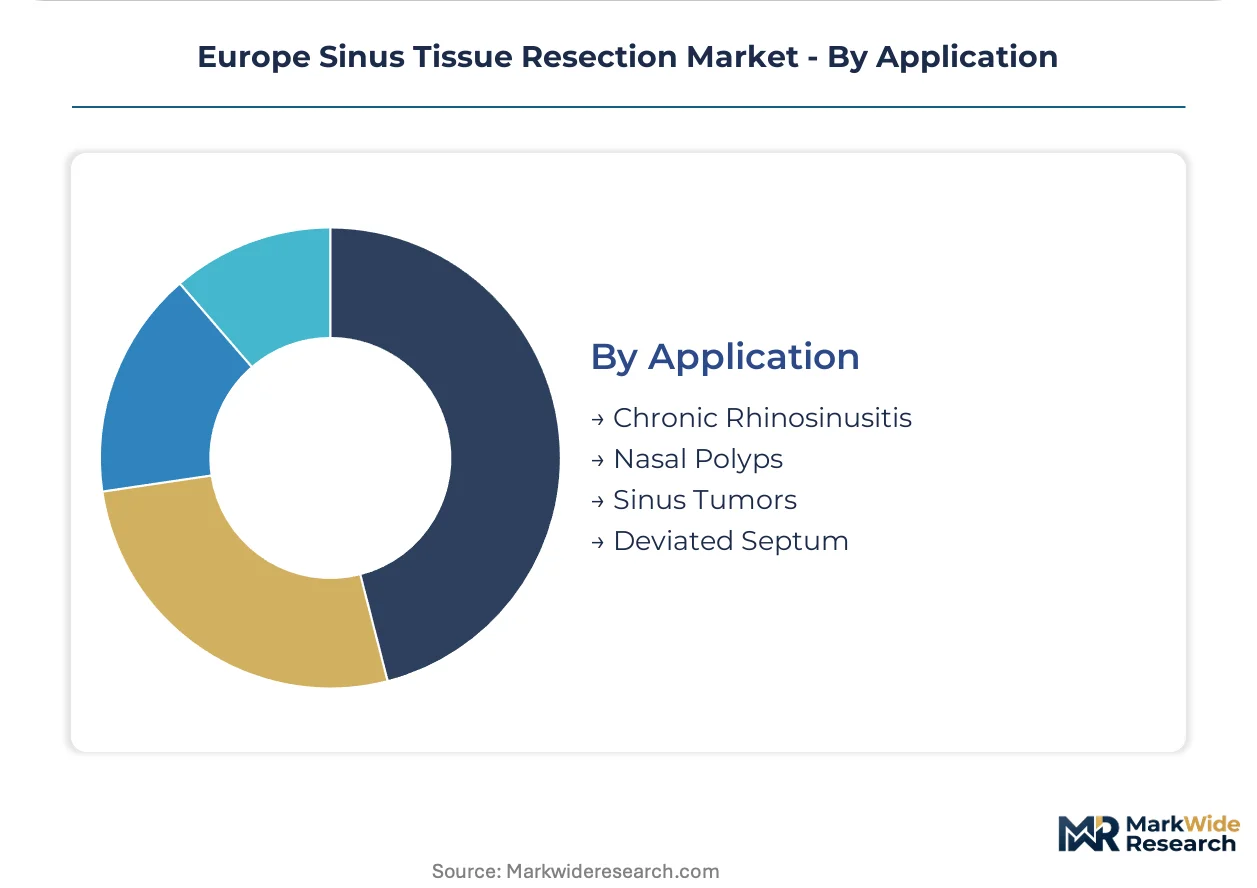
Application:
Volume concentration in inflammatory conditions contrasts with premium pricing opportunities in neoplastic indications requiring advanced navigation and margin assessment.
- Chronic Rhinosinusitis:Medically refractory inflammatory disease drives the majority of functional endoscopic sinus surgery volume across European hospital systems. German ENT specialty centers in Berlin, Munich, and Hamburg perform high caseloads with standardized stepped-care protocols.
- Nasal Polyps:Recurrent polyp disease requiring repeated surgical intervention generates sustained demand for precision resection instruments. Biologics-eligible patients with Type 2 inflammation are shifting some surgical volume to medical management, though refractory cases still require endoscopic polypectomy.
- Sinus Tumors:Neoplastic indications demand navigation-augmented resection with margin assessment and skull base reconstruction capabilities.
- Deviated Septum:Septoplasty procedures often accompany sinus surgery, utilizing similar instrumentation platforms with specialized cartilage manipulation tools.
Chronic rhinosinusitis procedures represent the volume foundation. Nasal polyp applications are expanding most quickly as biologics referral patterns and revision surgery rates elevate precision resection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany exceeds French and UK hospital systems by margins reflecting capital equipment bundling advantages and denser ENT specialty networks. Swiss and Austrian markets command premium positioning through academic medical center concentration. Southern European markets operate on compressed procurement timelines with fragmented purchasing authority.
Germany
Bavarian and North Rhine-Westphalian hospital networks drive generator-tethered electrosurgical system demand through multi-year bundled contracts. The EU MDR's tightened clinical evidence requirements filter market access through established quality management systems at German notified bodies. Berlin, Munich, and Hamburg ENT specialty centers perform high caseloads with standardized stepped-care protocols for chronic rhinosinusitis.
France
French ambulatory surgical centers capture migratory case volume through regional anesthesia protocols and streamlined same-day discharge pathways. HAS assessment methodologies determine reimbursement thresholds for novel energy platforms entering the national hospital procurement system. Paris academic medical centers evaluate navigation-augmented resection platforms for complex revision sinus surgery cases.
United Kingdom
NICE technology appraisals shape commercial viability thresholds for radiofrequency cold ablation devices in NHS hospital trusts. England's integrated care systems are consolidating sinus device purchasing under centralized value-analysis frameworks. London and Southeast tertiary ENT departments prioritize bundled capital equipment, disposables, and service contract arrangements.
Switzerland
Zurich and Geneva academic centers anchor demand for optical precision in rigid endoscope supply chains. Swissmedic maintains stringent biocompatibility testing timelines that delay novel polymer instrument launches relative to EU timelines. Basel and Lausanne research institutes evaluate next-generation energy modalities for revision surgery applications.
Austria
Vienna ENT specialty networks present first-mover potential for integrated visualization-resection platforms in underpenetrated outpatient settings. Austrian social insurance institutions maintain favorable reimbursement for outpatient sinus surgery procedures. Graz and Salzburg hospital systems are expanding adoption of minimally invasive sinus procedures through surgeon training program investments.
Europe Sinus Tissue Resection Market Key Industry Players
Concentration sits with diversified medical technology conglomerates possessing in-house electrosurgical generator development capabilities. The vendor base stratifies across three tiers: integrated platform manufacturers bundling capital equipment with consumables, specialized ENT visualization firms competing on optical precision, and instrument-only suppliers locked into third-party generator compatibility. Strategic moves center on multi-year hospital system contracts and navigation technology licensing arrangements that deepen account penetration.
Among diversified conglomerates with broad surgical portfolios, Medtronic, Stryker Corporation, and Karl Storz occupy positions reflecting distinct competitive vectors. Medtronic exemplifies the integrated platform archetype through electrosurgical portfolio breadth enabling hospital system bundling. Stryker Corporation represents the specialized ENT workflow optimization approach anchoring position through visualization system integration. Karl Storz sits within the optical precision tier dominating rigid endoscope supply relationships with academic medical centers in German-speaking markets.
| Leading Market Players |
|---|
| Medtronic |
| Stryker Corporation |
| B. Braun Melsungen |
| Integra Lifesciences |
| Karl Storz |
| Olympus Corporation |
| Intellus Medical, Inc. |
| Bausch & Lomb Incorporated |
| Smith & Nephew |
| Others |
Cost & Logistics Intelligence
EU MDR certification tiers gate both supplier qualification and price differentiation simultaneously, as CE marking under notified bodies in Germany, France, and the Netherlands creates compliance moats that stratify manufacturers into premium-validated and standard-tiers with corresponding pricing authority.
Pricing Analysis
Configured-to-order pricing for navigation-integrated platforms commands substantial premiums over standard electrosurgical configurations in German hospital networks. Pricing stratifies across premium navigation-augmented systems, standard generator-tethered platforms, and economy reusable instrument tiers based on CE marking tier and after-sales service bundling. Cost compression in standard electrosurgical consumables is intensifying because ambulatory surgical centers prioritize throughput economics over feature depth. German academic medical centers exhibit lowest price sensitivity due to bundled capital equipment contracts, while French outpatient clinics face highest pressure from HAS reimbursement thresholds.
Supply Chain Analysis
Extended lead times for biocompatibility-certified polymers and precision-machined electrosurgical tips constrain inventory flexibility across European manufacturing nodes. Supply concentrates in Germany, Switzerland, and the Netherlands for generator platforms and optical components, while single-use instrument molding draws from established medical device manufacturing corridors in Ireland and Poland. Raw material dependencies center on surgical-grade stainless steel, medical polymers, and fiber-optic cable assemblies. Single-source vulnerability persists for navigation system sensors sourced from specialized German optics suppliers. Distribution runs through direct manufacturer partnerships with tier-one hospital systems, bypassing traditional distributor layers in Bavaria and North Rhine-Westphalia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologics for chronic rhinosinusitis threaten to displace surgical volume, forcing incumbents to defend procedure relevance through outcome differentiation and ambulatory workflow capture.
For Market Incumbents: Fortify account control through multi-year service contracts embedding next-generation radiofrequency generators in German academic medical centers. Deepen backward integration into navigation software development to reduce licensing exposure. Prioritize ambulatory surgical center partnerships in France to capture case migration before biologics eligibility expands. For New Entrants and Emerging Players: Differentiate on cold ablation portability for Austrian and Swiss outpatient ENT clinics lacking capital equipment infrastructure. Target Vienna and Salzburg specialty networks where integrated platform penetration remains below German benchmarks. Pursue direct procurement relationships with ENT clinic chains rather than hospital system committees. For Investors and Strategic Acquirers: EU MDR transition completion reshapes the acquisition landscape toward quality-system-rich targets with stabilized CE marking pathways. Five-to-ten year viability favors manufacturers with in-house energy platform development over instrument-only suppliers tethered to third-party generators. Monitor G-BA reimbursement decisions for radiofrequency modalities as inflection signals for platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance under German notified bodies accelerates market access for validated quality systems. |
| Hospital System Partnership | Multi-year bundled contracts with Bavarian networks lock in consumable purchasing across replacement cycles. |
| Software Companion Development | Navigation-augmented workflows integrate with AI-powered anatomical mapping for revision case precision. |
| Reimbursement Strategy | HAS and G-BA alignment determines commercial viability for cold ablation platforms in outpatient settings. |
| Geographic Expansion | Swiss and Austrian academic centers present first-mover potential for integrated visualization-resection systems. |
Research Approach
The analysis maps electrosurgical platforms, resectoscope systems, and disposable instrument categories, each validated through ENT surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews combined with secondary validation from EMA guidance documents, notified body CE marking databases, hospital procurement records, and HTA assessment publications. Bottom-up procedure volume estimates triangulated against top-down manufacturer revenue allocations across German, French, and UK market clusters.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled technology modality, end-user setting, application indication, and regional regulatory cluster dimensions. CAGRs derived from procedure volume trajectories, price evolution assumptions, and modality substitution elasticities. Forecast inputs incorporated ambulatory migration rates, biologics penetration curves, and MDR compliance timelines without year-specific anchoring.
The analysis sits within stated boundaries; outcomes outside stable regulatory enforcement, consistent reimbursement policy, or sustained ambulatory infrastructure investment would require recalibration. Forecasts reflect documented assumptions regarding procedure volume, price trajectory, and competitive dynamics. Biologics efficacy advances, notified body capacity constraints, or reimbursement reclassification pose revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Global Endoscope Leak Detection Device Market
Endoscopy
Global Endoscopic Stricture Management Device Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Endoscopy Fluid Management Systems Market
Endoscopy
Rigid Endoscopes Market
Endoscopy
Argentina Endoscopy Devices Market
Endoscopy
Global Disposable Endoscope Market
Endoscopy
Saudi Arabia Endoscopy Devices Market
Endoscopy
Hysteroscopic Endometrial Resection Procedures Market
Endoscopy
Global Endoscopy Ultrasound Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography (ERCP) Devices Market
Endoscopy
China Endoscopy Devices Market
Endoscopy
Endoscopy Device Market
Endoscopy
Polyp Biopsy Market
Endoscopy
Global Endoscope Reprocessing Market
Endoscopy
Colonic Stents Market