
 Nanotechnology in Medical Devices Market | 2026-2036
Nanotechnology in Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology in Medical Devices Market Intelligence
The divergence between capital-intensive nanocoating production and specialized nanosensor R&D is unwinding established market hierarchies. This capability gap separates material science specialists from large, integrated device manufacturers. Medtronic leverages its vast device portfolio to embed nano-enabled features into existing cardiac and neurological product lines. In contrast, 3M specializes in advanced material science, supplying proprietary nanocoatings across the broader medical device industry.
Nanotechnology in medical devices involves the design, characterization, and application of materials at the nanoscale, typically below 100 nanometers. These engineered innovations are used to improve device biocompatibility, diagnostic precision, and therapeutic effectiveness. While nanocoatings constitute a large product segment, the highest growth is found elsewhere. Nanosensors for in-vivo biosensing and nanocarriers for targeted therapeutic delivery represent the leading edge of development and profitability.
Regulatory oversight from bodies like the United States FDA and the European Medicines Agency (EMA) is a critical market-shaping factor. Frameworks such as the EU's Medical Device Regulation (MDR) impose rigorous standards for characterization and risk assessment of nanomaterials. Successfully navigating these complex and evolving regulatory pathways for novel material compositions will determine future market leadership and access.
Market Dynamics
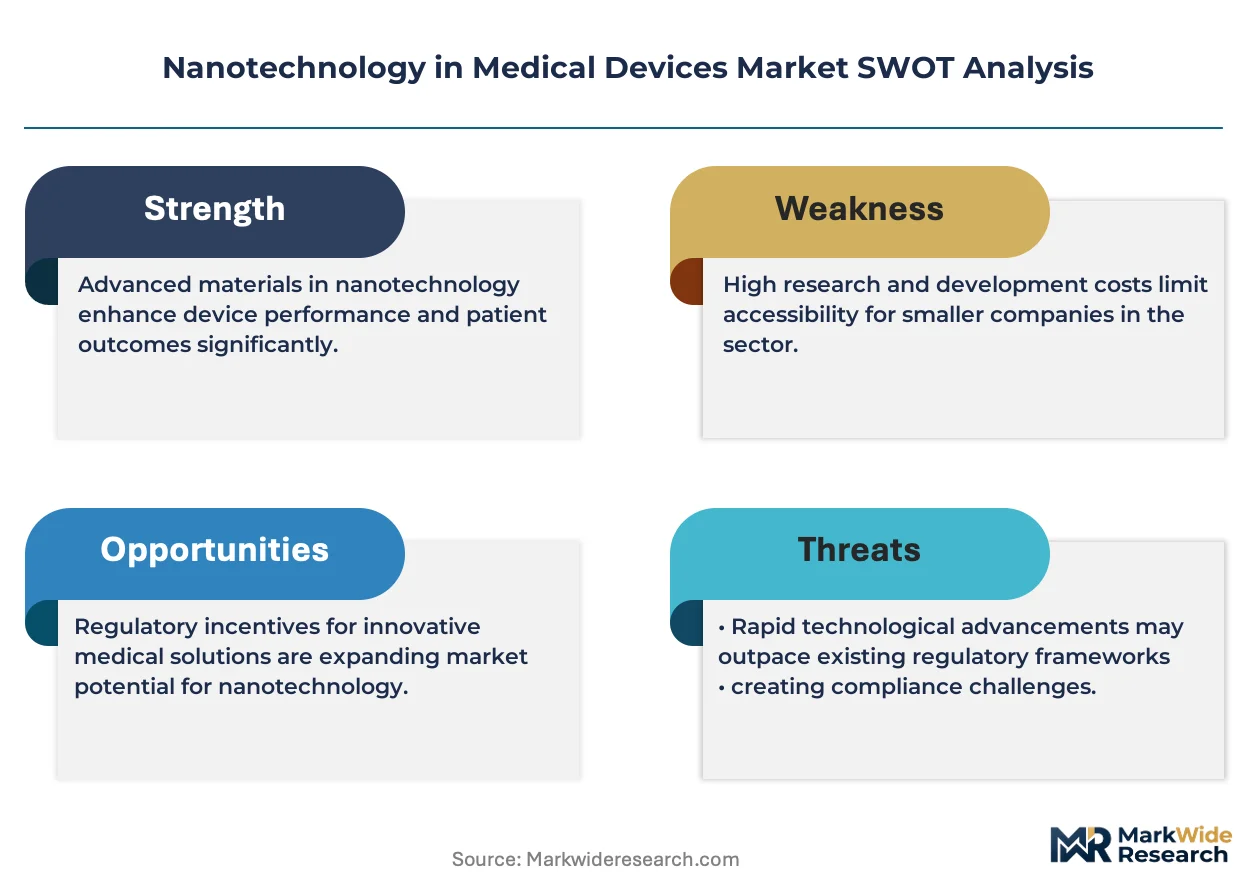
Regulatory stringency, particularly the European Union's Medical Device Regulation (MDR), is the central force shaping the market. This framework elevates requirements for nanomaterial characterization, risk assessment, and post-market surveillance, directly influencing product development timelines and R&D priorities.
Growth Catalysts
- Targeted Therapeutics:The expansion of nanocarriers for targeted drug delivery in oncology and chronic inflammatory diseases creates significant pull-through demand for advanced material compositions and formulation expertise.
- Advanced Diagnostics:Favorable breakthrough device pathways from the United States FDA are accelerating the development and commercialization of highly sensitive nanosensors for in-vivo biosensing applications.
- Demographic Shifts:Aging populations in developed economies like Japan and Germany are driving sustained demand for next-generation biocompatible implants and regenerative medicine products that incorporate nanotechnology.
Market Restraints
- Manufacturing Costs:High capital investment is required for specialized equipment used in nanocoating processes like physical vapor deposition, creating a significant barrier to entry for smaller firms.
- Regulatory Ambiguity:Evolving and sometimes unclear guidance from bodies like the EMA regarding long-term toxicity and environmental impact of novel nanomaterials can delay product approvals.
- Scalability Hurdles:Certain complex nanosensor fabrication techniques demonstrate high efficacy in laboratory settings but face significant technical challenges in scaling up to cost-effective, high-volume commercial production.
Strategic Opportunities
- Emerging Geographies:There is significant potential for market entry and expansion in countries like Brazil and India, where healthcare infrastructure is modernizing and adoption of advanced medical technologies is rising.
- Point-of-Care Diagnostics:Nano-enabled biosensors present a major opportunity for developing portable, rapid diagnostic tests for infectious diseases, moving testing from centralized labs to clinical and home settings.
- Technology Convergence:Integrating artificial intelligence with data from in-vivo nanosensors allows for the creation of predictive health monitoring systems, shifting from reactive treatment to proactive intervention.
Industry Challenges
- Specialized Talent Gaps:A scarcity of professionals with combined expertise in material science, toxicology, and regulatory affairs for nanomaterials constrains R&D and compliance efforts across the industry.
- Intellectual Property Navigation:The dense and overlapping patent landscape for foundational nanotechnologies, especially in biosensing and drug delivery, creates complex licensing negotiations and potential litigation risks.
- Standardization Deficits:A lack of globally harmonized ISO standards for the characterization, testing, and classification of medical-grade nanomaterials complicates international trade and regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotechnology in Medical Devices Market |
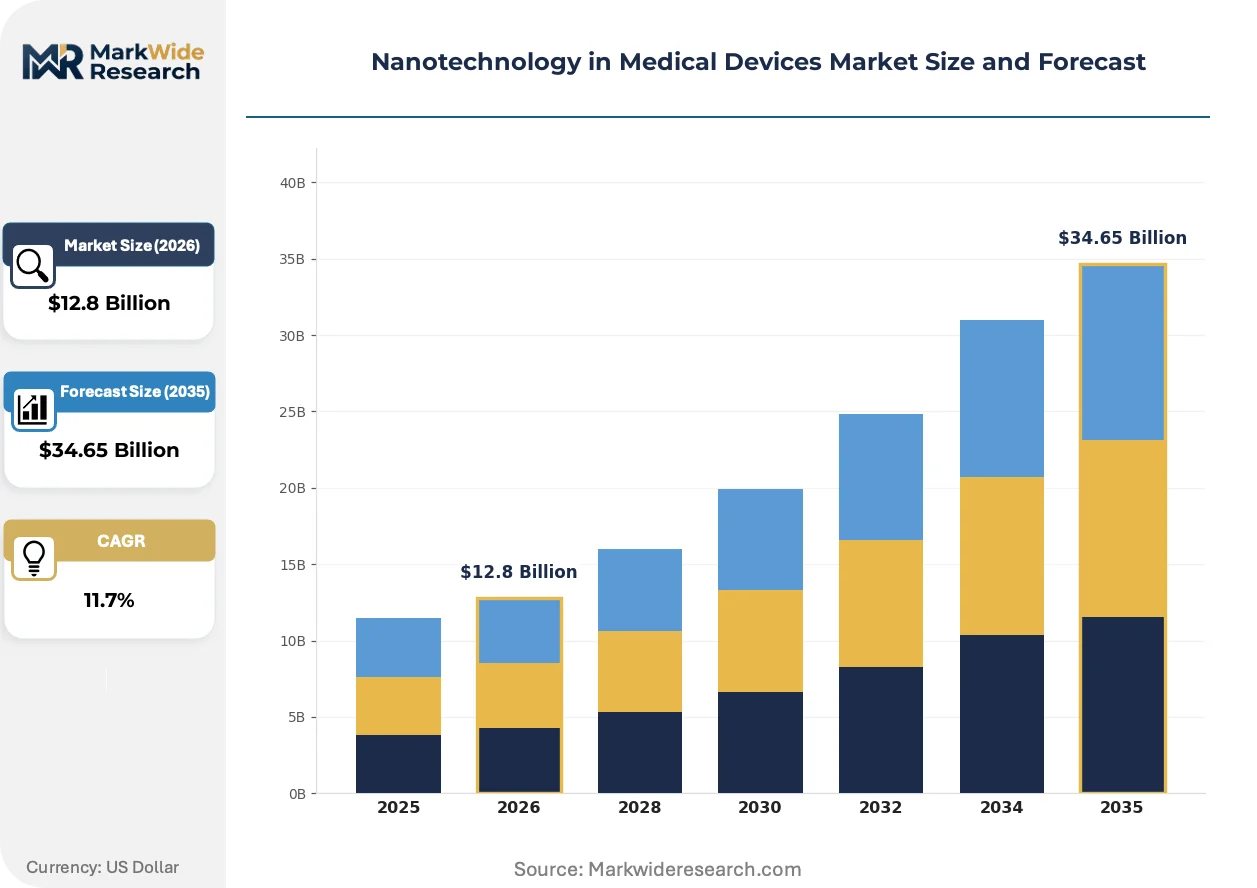
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $34.65 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanosensors, Nanocarriers, Nanoparticles, Nanocoatings End User: Hospitals, Clinics, Research Laboratories, Diagnostic Centers Technology: Surface Engineering, Drug Delivery Systems, Imaging, Regenerative Medicine Application: In Vivo Diagnostics, Therapeutic Delivery, Tissue Engineering, Biosensing |
| Companies Covered | Abbott Laboratories, Medtronic, Stryker, 3M, Smith & Nephew PLC, Zimmer Biomet, Boston Scientific Corporation, Dentsply Sirona, Starkey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology in Medical Devices Market Strategic Shifts & Innovations
Innovation is pivoting from passive surface enhancements, such as biocompatible nanocoatings, toward active, intelligent functionalities. This shift prioritizes nanomaterials that can sense, respond to, and interact with biological systems in real time, defining the next generation of medical devices.
Active nanostructures for in-vivo biosensing provide continuous, real-time monitoring of specific biomarkers directly within the patient's body. Device manufacturers in cardiology and endocrinology are the primary adopters, integrating these sensors into implants and wearables. This capability is supplanting traditional, periodic external blood tests for managing chronic conditions, enabling more dynamic and personalized treatment regimens.
Regulatory frameworks are becoming more prescriptive regarding nanomaterial lifecycles. The EU's Medical Device Regulation (MDR) imposes stringent requirements for clinical evidence and post-market surveillance on any device containing nanomaterials. This directly affects producers of nano-coated implants and drug-eluting stents, who must now invest more heavily in generating long-term safety and efficacy data to maintain market access in Europe.
A clear behavioral shift toward value-based healthcare models is altering procurement patterns for medical devices. This change pressures manufacturers to demonstrate not just device functionality but also improved patient outcomes and long-term cost-effectiveness. This trend is most visible in healthcare systems in the United States and Germany, where reimbursement decisions are increasingly tied to proven therapeutic and economic value.
Nanotechnology in Medical Devices Market Segmentation
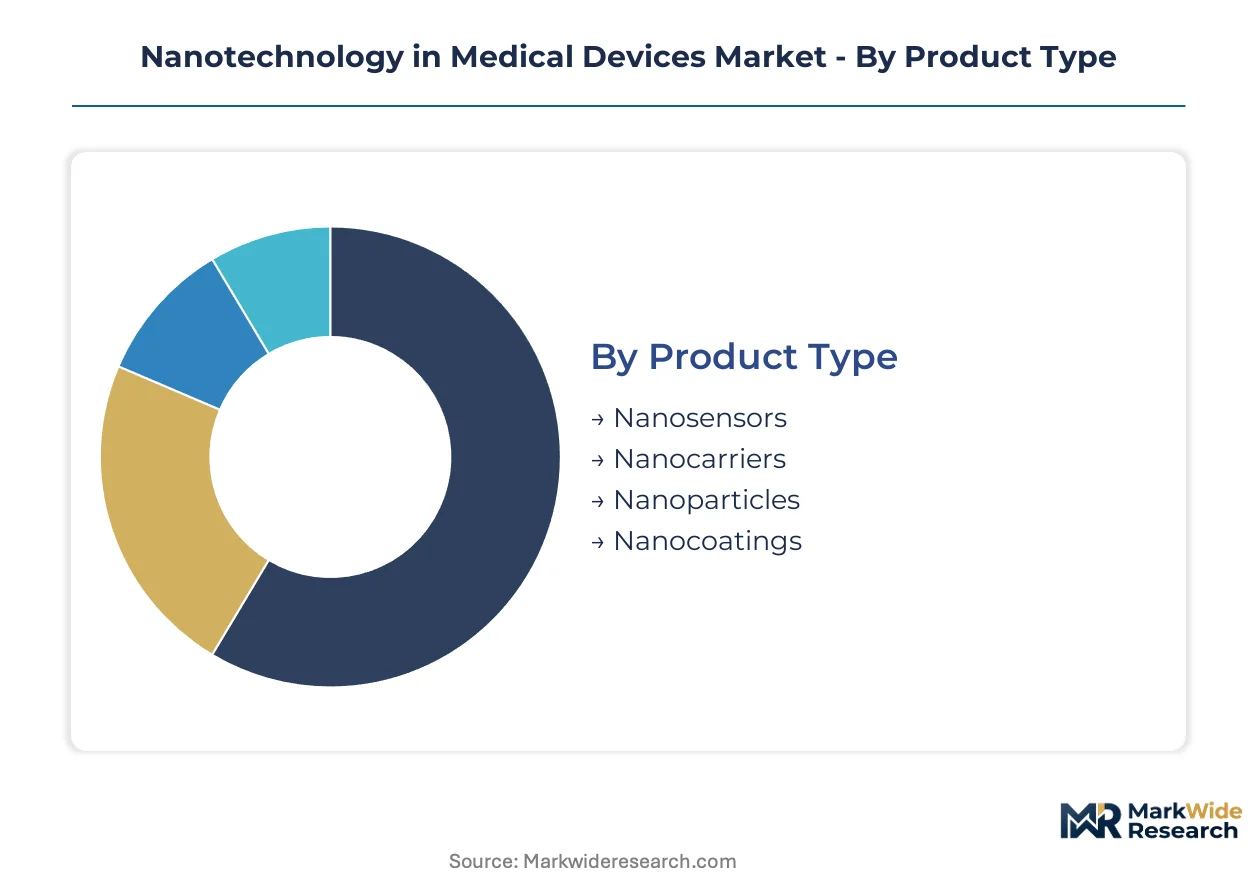
Understanding the segmentation of the nanotechnology in medical devices market reveals how technological advancements and clinical needs drive specific product development and adoption. This granular view helps identify areas of concentrated investment and emerging opportunities across the healthcare ecosystem.
Product Type:
Margin pools within product types are increasingly concentrated in advanced functionalities that offer real-time interaction with biological systems.
- Nanosensors:These devices utilize nanomaterials to detect biological or chemical signals with high sensitivity and specificity. Demand for nanosensors is concentrating in the United States and Germany for continuous glucose monitoring and cardiac rhythm management, driven by favorable breakthrough device pathways from the FDA.
- Nanocarriers:These engineered nanoparticles encapsulate and deliver therapeutic agents to specific cells or tissues, minimizing systemic toxicity. Demand for nanocarriers is prominent in oncology and chronic inflammatory diseases across Europe, propelled by the expansion of targeted drug delivery systems.
- Nanoparticles:Comprise materials engineered at the nanoscale, used for imaging contrast agents, diagnostic probes, and certain therapeutic interventions.
- Nanocoatings:Involve thin layers of nanomaterials applied to medical device surfaces to enhance biocompatibility, reduce infection risk, or improve device longevity.
The dominant share belongs to Nanocoatings, while Nanosensors are closing the gap fastest.
End User:
End-user segmentation highlights distinct procurement patterns and the varied scale of device integration across healthcare settings.
- Hospitals:These institutions are primary consumers of advanced nanotechnology-enabled medical devices, integrating them into surgical procedures, intensive care, and long-term patient management. Demand in hospitals is driven by the need for advanced diagnostic capabilities and improved therapeutic outcomes, particularly in complex interventions.
- Diagnostic Centers:Specialized facilities focused on advanced medical testing, utilizing nanotechnology for highly sensitive and rapid detection of biomarkers. Demand in diagnostic centers is concentrating in urban areas of Japan and Germany, supported by aging populations and the push for early disease detection.
- Clinics:Outpatient facilities that adopt nanotechnology for point-of-care diagnostics and minimally invasive procedures, improving patient convenience and access.
- Research Laboratories:Academic and industrial settings where fundamental research and development of novel nanomaterials and devices take place, often focusing on early-stage innovation.
Hospitals represent the largest end-user segment, with Diagnostic Centers expanding most quickly due to rising demand for rapid testing.
Technology:
Technology adoption reflects specific clinical applications, with innovations driving advancements in precision medicine and patient management.
- Drug Delivery Systems:These technologies leverage nanocarriers and other nanoscale formulations to precisely control the release and targeting of pharmaceutical agents within the body. Demand for advanced drug delivery systems is high in oncology and immunology research in the United States, driven by the push for personalized medicine.
- Regenerative Medicine:Utilizes nanotechnology to develop scaffolds, growth factor delivery systems, and cell-based therapies for tissue repair and regeneration. Demand for regenerative medicine applications is growing in Germany and Japan, supported by demographic shifts and the need for next-generation biocompatible implants.
- Surface Engineering:Involves modifying the surface properties of medical devices at the nanoscale to enhance biocompatibility, reduce friction, or prevent microbial adhesion.
- Imaging:Employs nanoparticles as contrast agents or probes to improve the resolution and sensitivity of diagnostic imaging techniques, such as MRI and CT scans.
Drug Delivery Systems command significant development focus, while Regenerative Medicine is gaining share fastest through novel tissue repair solutions.
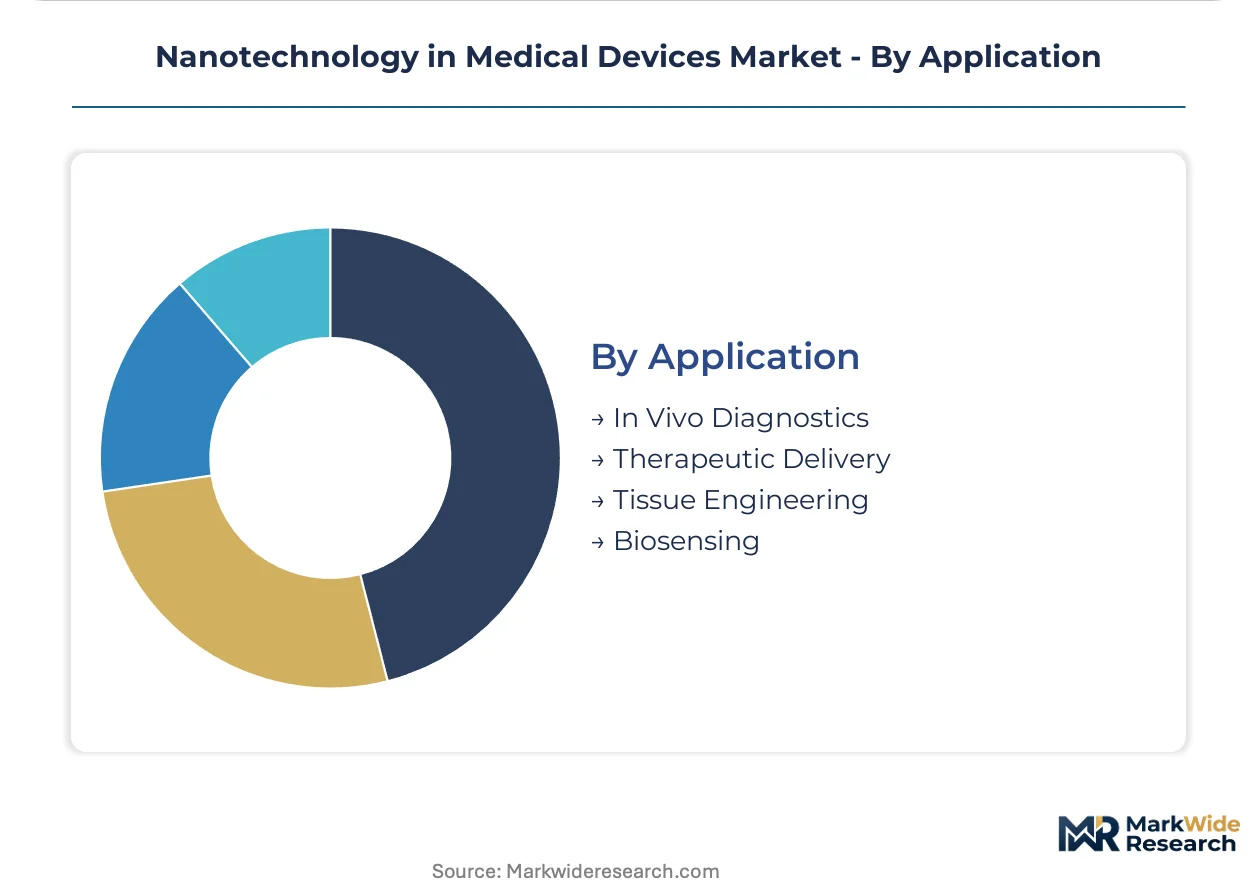
Application:
Application maturity varies, with established diagnostic uses contrasting with nascent but high-potential therapeutic interventions.
- Therapeutic Delivery:Focuses on the precise and controlled release of drugs, genes, or other therapeutic agents using nanocarriers to target specific disease sites. Demand for therapeutic delivery is expanding in chronic disease management and oncology across Europe, influenced by stringent regulatory frameworks like the EU's Medical Device Regulation (MDR).
- Biosensing:Involves the use of nanosensors for real-time, in-vivo monitoring of biological markers, providing continuous data for diagnosis and treatment adjustment. Demand for biosensing is strong in cardiology and endocrinology in the United States, driven by breakthrough device pathways and the shift towards proactive health monitoring.
- In Vivo Diagnostics:Utilizes nanotechnology for diagnostic procedures conducted inside the living body, offering enhanced sensitivity and early disease detection.
- Tissue Engineering:Applies nanotechnology to create biological substitutes that restore, maintain, or improve tissue function, particularly for orthopedic and cardiovascular repair.
Therapeutic Delivery currently holds substantial revenue, but Biosensing applications are demonstrating the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for nanotechnology in medical devices exhibits asymmetry, with established markets like the United States dictating premium pricing while emerging economies such as India focus on cost-effective solutions. This divergence influences investment flows and product development priorities across different healthcare systems. Manufacturers adapt strategies based on local reimbursement models and regulatory landscapes.
United States
Demand for advanced biosensors in the United States is driven by the shift towards proactive health monitoring and personalized medicine. Favorable breakthrough device pathways from the United States FDA accelerate commercialization for novel nanotechnology applications. Major research and development hubs in Boston and Silicon Valley attract significant venture capital for new medical device startups.
Germany
Germany's aging population sustains demand for biocompatible implants and regenerative medicine products incorporating nanotechnology. The EU's Medical Device Regulation (MDR) imposes stringent requirements for nanomaterial characterization and risk assessment. Munich and Berlin host significant R&D clusters focused on advanced material science and medical technology innovation.
Japan
Japan experiences sustained demand for next-generation biocompatible implants and advanced diagnostic technologies due to its demographic shifts. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees device approvals, emphasizing safety and efficacy for novel nanomaterials. Osaka and Kyoto are key centers for medical device manufacturing and nanotechnology research.
India
India's modernizing healthcare infrastructure creates demand for cost-effective nanotechnology solutions in medical devices. The Central Drugs Standard Control Organization (CDSCO) regulates medical devices, with evolving guidelines for nanomaterial-containing products. Bengaluru and Hyderabad are emerging as innovation hubs for medical technology and advanced materials.
Brazil
Brazil's expanding healthcare access increases demand for nanotechnology-enabled point-of-care diagnostics and therapeutic delivery systems. ANVISA, the national health surveillance agency, is developing regulatory frameworks for novel medical devices incorporating nanomaterials. São Paulo and Rio de Janeiro serve as primary centers for medical device distribution and clinical trials.
Nanotechnology in Medical Devices Market Key Industry Players
Concentration sits with large, integrated medical device manufacturers capable of extensive R&D and navigating complex regulatory pathways. The market structure exhibits a tiered consolidation, with specialized material science firms forming a crucial supply base for advanced components. Strategic archetypes include diversified device giants, niche material specialists, and emerging biosensing innovators. Dominant competitive moves involve strategic partnerships for technology co-development, targeted acquisitions of specialized startups, and significant investments in intellectual property.
Within the diversified device giant archetype, Medtronic, a U.S.-based corporation, exemplifies extensive integration of nano-enabled features into existing cardiac and neurological product lines. 3M, another U.S.-based entity, occupies a position as a specialized material science firm, supplying proprietary nanocoatings across the broader medical device industry. Abbott Laboratories, a global medical device and healthcare company, represents a significant player with investments in diagnostic technologies, including nanosensors for continuous monitoring applications. These companies leverage their scale and market presence to influence technology adoption and regulatory compliance.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Medtronic |
| Stryker |
| 3M |
| Smith & Nephew PLC |
| Zimmer Biomet |
| Boston Scientific Corporation |
| Dentsply Sirona |
| Starkey |
Cost & Logistics Intelligence
Specialization in advanced nanomanufacturing processes like physical vapor deposition underwrites supply concentration, directly impacting pricing power for foundational nanocoatings. This capital intensity creates high barriers to entry for new market participants.
Pricing Analysis
Customization-premium spreads characterize pricing for nanotechnology in medical devices, reflecting the high R&D investment and specialized manufacturing required. Value-based pricing models increasingly influence procurement decisions in the United States and Germany. Price differentiation stems from the level of customization and specific regulatory certifications, such as EU MDR compliance for novel nanomaterials. Pricing pressure intensifies for commodity nanocoatings due to increased competition. Hospitals are generally less price-sensitive for breakthrough therapeutic devices compared to clinics purchasing standard diagnostic tools.
Supply Chain Analysis
Regulatory bottlenecks, particularly stringent EU MDR requirements for nanomaterial characterization, represent a critical chokepoint for market access. Geographic supply for advanced components concentrates in research hubs within the United States and Germany. The industry relies on specialized nanomaterials and biocompatible polymers as key inputs. Single-source vulnerability for proprietary nanosensors poses a structural risk. Distribution runs through established medical device channels, including direct sales teams to hospitals and specialized distributors for clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A substitution defense is critical for incumbents in this market, as traditional diagnostic methods and therapeutic delivery systems pose a continuous threat to market share.
For Market Incumbents: Compound existing device portfolios by embedding next-generation nanosensors for real-time biosensing, leveraging established clinical relationships. Consolidate market share through strategic acquisitions of specialized material science firms that possess proprietary nanocoating technologies. This strategy mitigates the threat from emerging niche players and reinforces control over critical supply chain components. Invest heavily in navigating evolving regulatory pathways, particularly for long-term safety and efficacy data required by the EU MDR.
For New Entrants and Emerging Players: Differentiate on specialized applications, targeting unmet clinical needs in areas like personalized oncology or chronic inflammatory disease management. Focus market entry on emerging geographies such as Brazil and India, where healthcare infrastructure is modernizing and demand for advanced diagnostics is rising. A go-to-market angle emphasizing rapid, point-of-care diagnostics for infectious diseases can penetrate the under-served clinic segment.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized startups with strong intellectual property portfolios in advanced nanosensors and nanocarriers. Long-term viability hinges on companies demonstrating clear pathways for regulatory approval and scalable manufacturing. Acquisition targets should exhibit robust clinical evidence for novel material compositions. A signal to watch is the successful commercialization of a new class of in-vivo biosensors with proven long-term biocompatibility.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates market access for novel nanosensors addressing critical unmet medical needs in the United States. |
| CE Marking Pathway Investment | Secures European market access for nanotechnology-enabled implants by demonstrating rigorous EU MDR compliance. |
| Hospital System Partnership | Establishes direct procurement channels and facilitates clinical integration of advanced diagnostic devices. |
| Targeted IP Acquisition | Strengthens patent portfolios in nanocarrier technologies, protecting future drug delivery innovations. |
| Manufacturing Process Automation | Reduces per-unit costs for high-volume nanocoatings, improving margin competitiveness for Medtronic. |
Research Approach
Cross-validation between primary interviews and secondary validation anchors the qualitative findings of this market analysis. Primary research involved in-depth discussions with R&D scientists, regulatory affairs specialists, hospital procurement managers, and clinicians. Secondary data sources included FDA filings, EMA submissions, clinical trial databases, and medical device registries. This approach ensured robust bottom-up and top-down triangulation of market insights.
Sensitivity analysis informs the analytical framework, modeling market dynamics across the projection horizon. Segmentation dimensions modeled include product type, end-user, technology, application, and specific regulatory pathway adoption rates. Compound Annual Growth Rates were derived from historical data trends and projected adoption curves. Key industry-specific forecast inputs include R&D investment levels and clinical trial success rates for novel nanomaterials.
Material uncertainties — specifically evolving regulatory guidelines and new long-term safety concerns — sit outside the modeled envelope of this study. Forecasts reflect assumptions regarding technological advancements and market acceptance. Practitioners should keep alternative scenarios live as nanomaterial safety data and reimbursement policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Chordal Suture Systems Market
Medical Devices
Global Cerebrospinal Fluid Drainage Catheter Market
Medical Devices
Global Asthma and Copd Devices Market
Medical Devices
Drug Device Combination Products Market
Medical Devices
Bioresorbable Coronary Scaffolds Market
Medical Devices
Urethral Bulking System Market
Medical Devices
North America Intraocular Lens Market
Medical Devices
Urology Guidewires Market
Medical Devices
Tattoo Removal Lasers Market
Medical Devices
Band Ligators Market
Medical Devices
Medical Puncture Navigation Robot Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
High Flow Oxygen Therapy Devices Market
Medical Devices
Video-Guided Pericardial Access Device Market
Medical Devices
Hair Removal Devices Market
Medical Devices
Bone Conduction Hearing Devices Market