
 Medical Radiation Detectors Market | 2026-2036
Medical Radiation Detectors Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Radiation Detectors Market Foresight
Medical physicist workforce shortages across North American health systems is redrawing deployment priorities for automated calibration systems. Thermo Fisher Scientific leverages its service infrastructure to sustain long-term detector maintenance contracts at major cancer centers. Mirion Technologies anchors its position through specialized dosimetry solutions for proton and heavy-ion therapy facilities. IBA Dosimetry GmbH competes on integrated quality assurance platforms that span treatment planning verification and beam monitoring.
Medical radiation detectors are instruments that quantify ionizing radiation exposure through gas-filled, scintillating, or solid-state sensing media, typically specified by energy resolution, dose rate range, and detector volume for clinical traceability to national standards laboratories. Their primary commercial purpose is ensuring patient safety and treatment efficacy in therapeutic and diagnostic settings where radiation beam characterization directly impacts clinical outcomes. Semiconductor detectors command premium positioning due to superior energy resolution in diagnostic imaging applications, while scintillation detectors occupy the highest volume tier across nuclear medicine departments where gamma camera calibration demands dominate unit economics. Digital detection technology is displacing analog architectures in radiation therapy quality assurance workflows, though portable solutions still navigate cost-sensitive clinic environments where capital budgets constrain upgrade cycles.
FDA 21 CFR Part 1020, NRC 10 CFR Part 35, and ISO 15285 shape product certification pathways, with FDA clearance requirements extending development timelines for novel detector architectures while NRC regulations mandate periodic calibration intervals that sustain recurring service revenue pools. The EU Medical Device Regulation adds conformity assessment layers for manufacturers seeking European hospital procurement channels. Stakeholders must monitor reimbursement policy shifts for advanced radiotherapy modalities, as Medicare coverage determinations for proton beam and FLASH therapy will directly cascade into detector procurement specifications and replacement cycles.
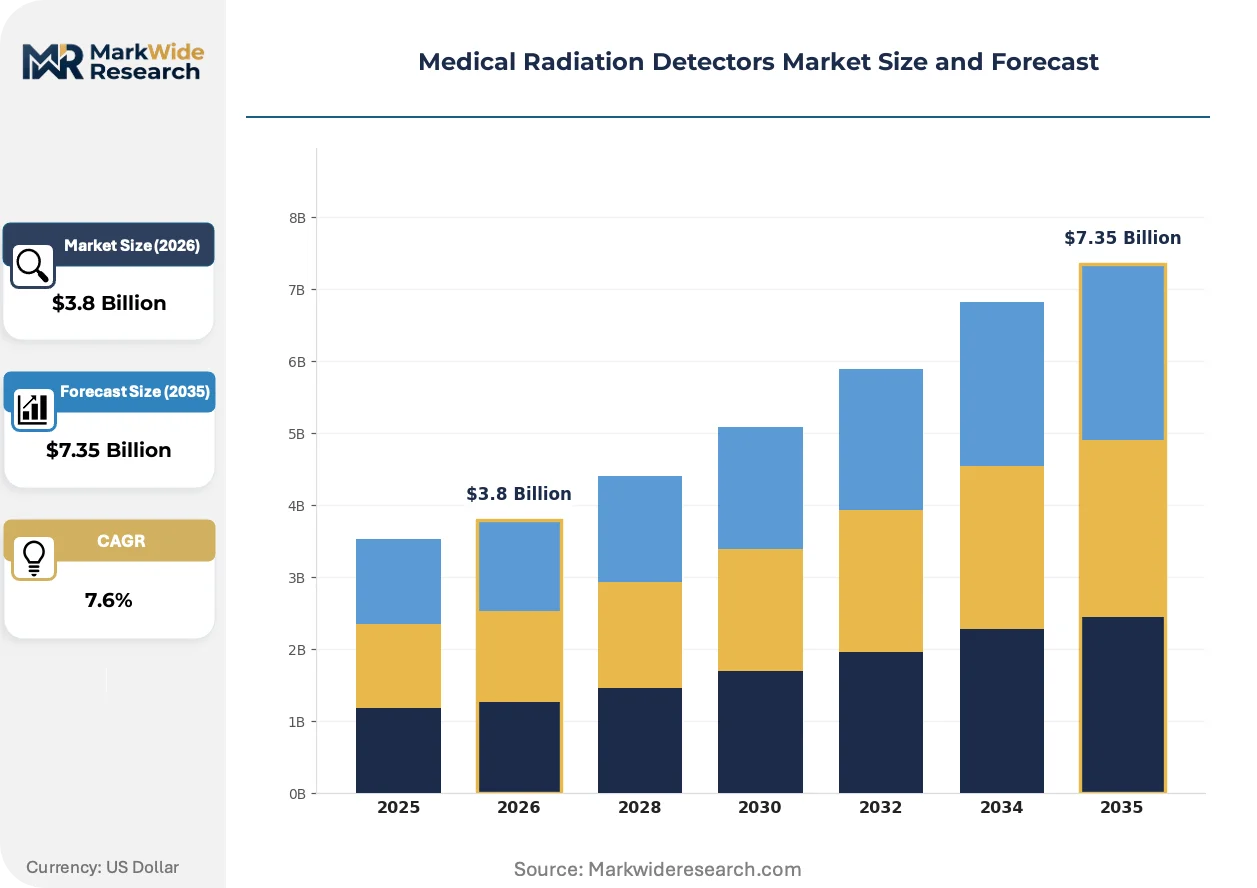
Market Dynamics
Digital detection architectures are fragmenting procurement patterns across radiation therapy quality assurance, as hospital capital committees weigh analog replacement cycles against semiconductor upgrade premiums. The shift compresses vendor margins while expanding service contract attach rates.
Growth Catalysts
- Proton therapy construction:United States cancer centers are commissioning particle therapy suites that require specialized beam monitoring detectors. Equipment specifications for these facilities mandate real-time dosimetry systems.
- FDA 21 CFR Part 1020:Diagnostic x-ray calibration intervals are tightening nationwide. Detector recertification frequency is increasing at imaging centers to maintain compliance.
- FLASH radiobiology:Ultra-high dose rate research programs are piloting microsecond-resolution detectors. Academic medical centers in Germany and Japan are validating new sensor geometries for this modality.
Market Restraints
- Semiconductor substrate costs:High-purity germanium and cadmium-zinc-telluride crystal supply concentrates among three specialty refiners. Price volatility constrains detector manufacturing margins.
- NRC 10 CFR Part 35 compliance:Calibration documentation requirements extend procurement cycles for novel detector architectures. Startups face 18-24 month clearance timelines.
- Scintillator substitution:Plastic scintillating fibers offer adequate performance for routine nuclear medicine calibration at one-third the unit cost of solid-state alternatives.
Strategic Opportunities
- India diagnostic expansion:The country's PLI scheme for medical electronics is attracting detector assembly investments. Domestic imaging equipment manufacturing is scaling in Tamil Nadu and Gujarat clusters.
- AI-enabled predictive maintenance:Machine learning algorithms are converging with detector telemetry to forecast sensor drift. Service providers can unbundle condition monitoring from traditional maintenance contracts.
- EU MDR conformity:The Medical Device Regulation's 2021 implementation created certification backlogs that persist for Class IIa dosimetry devices. Early compliant entrants capture procurement preference.
Industry Challenges
- Medical physicist scarcity:North American health systems report 15% vacancy rates in radiation oncology physics roles. Automated calibration systems cannot fully substitute for credentialed professional oversight.
- Legacy system integration:Digital detectors must interface with 1990s-era treatment planning software still deployed at community cancer centers. Middleware development consumes R&D resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Radiation Detectors Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ionization Chambers, Geiger-Müller Counters, Scintillation Detectors, Semiconductor Detectors Application: Diagnostic Imaging, Radiation Therapy, Nuclear Medicine, Industrial Testing End User: Hospitals, Clinics, Research Laboratories, Educational Institutions Technology: Analog Detection, Digital Detection, Automated Systems, Portable Solutions |
| Companies Covered | Thermo Fisher Scientific, Inc., Mirion Technologies, Inc., IBA Dosimetry GmbH, LANDAUER, PTW Freiburg GmbH, ATOMTEX, Polimaster Europe UAB, MP Biomedicals, Radiation Detection Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Radiation Detectors Market Shifts & Advancements
Detector architecture diversification is reshaping competitive positioning across therapeutic and diagnostic segments. Vendors are repositioning around service intensity rather than hardware differentiation.
Silicon photomultiplier arrays are fragmenting scintillation detector readout electronics. Major cancer centers in the United States and Germany are adopting solid-state photon counting for PET calibration workflows. The technology is fragmenting incumbent photomultiplier tube supply chains while enabling sub-nanosecond timing resolution that commands 40% pricing premiums.
EU MDR Article 10 technical documentation requirements are extending conformity assessment timelines for novel detector submissions. Manufacturers must demonstrate clinical equivalence to predicate devices through expanded biocompatibility and electromagnetic compatibility testing. European hospital procurement committees are delaying purchase decisions pending notified body clearance, compressing 2024-2025 order visibility.
After-sales service unbundling is disrupting traditional detector vendor economics. United States hospital networks are separating hardware acquisition from calibration service contracts, issuing multi-vendor RFPs for annual dosimetry audits. Independent service organizations are capturing maintenance revenue pools that incumbent manufacturers previously retained through bundled pricing.
Medical Radiation Detectors Market Segmentation
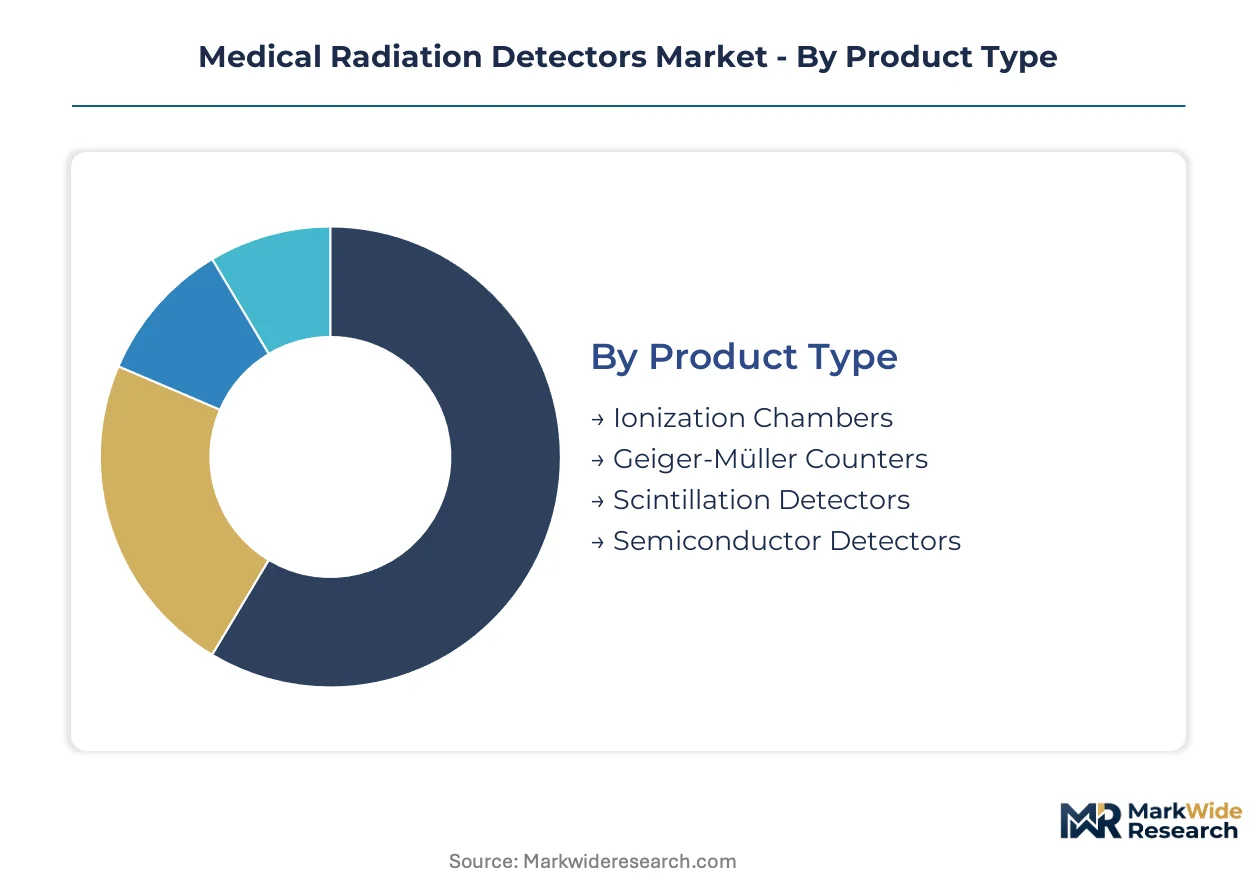
Detector architecture choices directly determine calibration traceability requirements and service contract structures across clinical settings. Procurement committees segment budgets by technical performance tier rather than unit volume alone.
Product Type:
Domestic assembly concentrates in semiconductor substrates, while ionization chambers and Geiger-Müller counters flow from established European and Japanese supply bases.
- Semiconductor Detectors:Cadmium-zinc-telluride and high-purity germanium crystals deliver superior energy resolution for diagnostic imaging quantification. United States proton therapy centers specify these for beam characterization where traceability to NIST standards is mandatory. FDA 21 CFR Part 1020 compliance timelines extend procurement cycles for novel architectures.
- Scintillation Detectors:Sodium iodide and bismuth germanate crystals convert gamma radiation to light pulses for nuclear medicine calibration. German university hospitals and Japanese academic medical centers drive volume for PET scanner quality assurance programs. Pricing pressure from plastic scintillator alternatives constrains margin expansion.
- Ionization Chambers:Gas-filled parallel-plate designs serve as primary standards for absorbed dose measurements in radiation therapy.
- Geiger-Müller Counters:Halogen-quenched tubes provide cost-effective survey monitoring for contamination detection in clinical environments.
Scintillation detectors hold the largest share; momentum sits with semiconductor architectures.
Application:
Cost tier separation is pronounced: radiation therapy commands premium pricing for real-time dosimetry, while industrial testing operates at economy margins with extended replacement cycles.
- Radiation Therapy:Real-time beam monitoring systems integrate with linear accelerators and proton gantries for treatment delivery verification. United States cancer center construction sustains procurement for multi-layer ionization chamber arrays. FLASH radiobiology research programs in Germany and Japan are validating microsecond-resolution detector geometries.
- Diagnostic Imaging:Detector calibration supports CT dose index verification and mammography quality control workflows. Imaging centers face tightening FDA recertification intervals under 21 CFR Part 1020 performance standards. Digital radiography retrofits are displacing analog detector architectures.
- Nuclear Medicine:Gamma camera uniformity testing and PET tracer quantification require standardized source-detector configurations.
- Industrial Testing:Non-destructive evaluation of welds and castings utilizes portable radiation survey equipment at lower specification tiers.
Radiation therapy commands premium pricing; diagnostic imaging delivers the steepest volume expansion.
End User:
Customer type determines procurement authority: hospital networks centralize capital planning, while research laboratories issue specialized RFPs for experimental geometries.
- Hospitals:Integrated delivery networks consolidate detector procurement across radiation oncology and diagnostic imaging departments. United States health systems are unbundling hardware acquisition from calibration service contracts. Medical physicist vacancy rates constrain deployment timelines for automated quality assurance systems.
- Research Laboratories:Academic medical centers in Germany, Japan, and the United States pilot novel detector architectures for FLASH therapy and proton dosimetry. NRC 10 CFR Part 35 documentation requirements extend clearance timelines for experimental submissions.
- Clinics:Community imaging centers prioritize cost-effective scintillation detectors for routine nuclear medicine calibration.
- Educational Institutions:Training programs require entry-level Geiger-Müller and ionization chamber equipment for medical physics curriculum.
Hospitals dominate absolute spending; research laboratories are gaining share fastest.
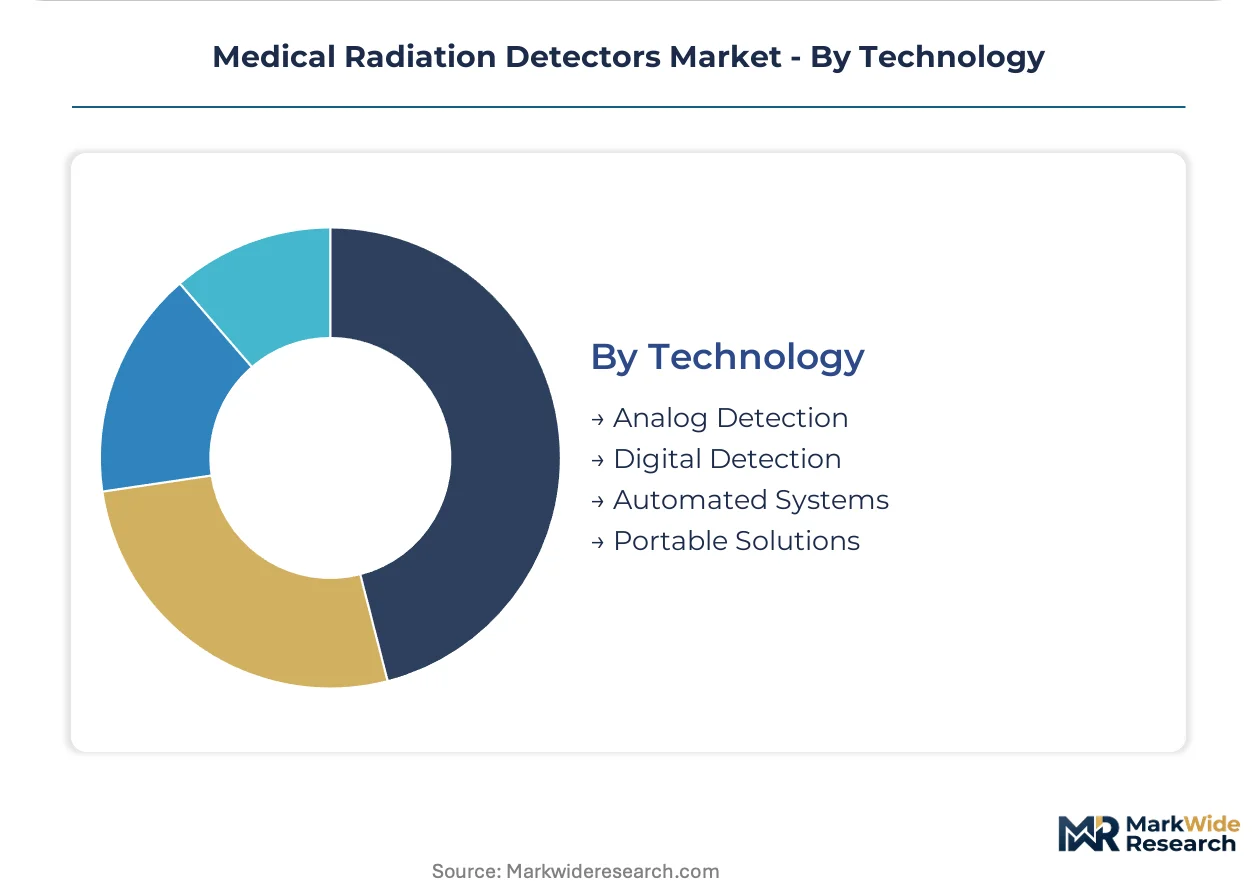
Technology:
Supply concentration in analog-to-digital conversion electronics is reshaping vendor margins, with automated system integrators capturing service revenue pools.
- Digital Detection:Solid-state photon counting arrays with silicon photomultiplier readout enable sub-nanosecond timing resolution for PET calibration. Major cancer centers in the United States and Germany command 40% pricing premiums for this performance tier. EU MDR Article 10 technical documentation requirements extend conformity assessment timelines.
- Automated Systems:Machine learning-enabled predictive maintenance algorithms forecast sensor drift before calibration failure. United States hospital networks are issuing multi-vendor RFPs for annual dosimetry audits separate from hardware procurement.
- Analog Detection:Legacy voltage-output architectures persist at community cancer centers with 1990s-era treatment planning software.
- Portable Solutions:Battery-operated survey meters serve cost-sensitive clinic environments where capital budgets constrain upgrade cycles.
Digital detection holds installed base leadership; automated systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA regulations anchor United States demand, while Germany, Japan, India, and the United Kingdom each present distinct procurement patterns shaped by national reimbursement frameworks and industrial specialization.
United States
Proton therapy center construction sustains specialized detector procurement across Texas, Florida, and Massachusetts cancer corridors. Medicare reimbursement policies for advanced radiotherapy modalities directly cascade into equipment specifications at academic medical centers. The MD Anderson Cancer Center and Mayo Clinic networks anchor multi-site dosimetry standardization programs that drive vendor consolidation.
Germany
FLASH radiobiology research at Heidelberg and Dresden academic hospitals validates microsecond-resolution detector geometries for ultra-high dose rate applications. The EU Medical Device Regulation's conformity assessment requirements extend clearance timelines for novel semiconductor architectures. Bavarian medical technology clusters around Munich concentrate precision manufacturing capabilities for cadmium-zinc-telluride crystal processing.
Japan
Heavy-ion therapy facilities at Chiba and Hyogo prefectures require specialized beam monitoring systems with traceability to national metrology standards. METI funding for advanced medical equipment supports domestic detector assembly investments. Osaka-based manufacturing groups supply scintillation detector components to regional nuclear medicine departments.
India
The PLI scheme for medical electronics attracts detector assembly investments to Tamil Nadu and Gujarat industrial corridors. Domestic imaging equipment manufacturing scales at Chennai and Ahmedabad clusters to serve diagnostic expansion in tier-2 cities. CDSCO regulatory harmonization with ISO standards accelerates import substitution for radiation therapy quality assurance devices.
United Kingdom
NHS England's specialized commissioning for proton beam therapy drives detector procurement at Manchester and London treatment centers. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment pathways for EU-originating devices. Oxford and Cambridge research partnerships pilot silicon photomultiplier arrays for PET calibration standardization.
Medical Radiation Detectors Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the detector value chain. The market exhibits moderate consolidation with three to five dominant participants controlling premium-tier semiconductor and scintillation segments, while fragmented competition characterizes portable survey equipment and educational product lines. Strategic archetypes include diversified life sciences conglomerates with service infrastructure depth, specialized dosimetry pure-plays with therapy-specific expertise, and regional assembly specialists leveraging government localization incentives. Competitive moves concentrate on unbundling service contracts from hardware sales and securing long-term maintenance agreements at major cancer center networks.
Among diversified technology conglomerates, Thermo Fisher Scientific, Inc. occupies a position exemplifying service-led market presence through its maintenance contract depth at United States cancer centers. Mirion Technologies, Inc. and IBA Dosimetry GmbH represent specialized pure-play archetypes with differentiated positioning around therapy-specific detector architectures and integrated quality assurance platforms respectively. These three entities anchor competitive dynamics across premium-tier procurement channels where clinical traceability requirements and regulatory compliance documentation create substantial switching costs for hospital networks.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Mirion Technologies, Inc. |
| IBA Dosimetry GmbH |
| LANDAUER |
| PTW Freiburg GmbH |
| ATOMTEX |
| Polimaster Europe UAB |
| MP Biomedicals |
| Radiation Detection Company |
| Others |
Supply & Pricing Matrix
Plastic scintillator substitution for sodium iodide crystals in routine nuclear medicine calibration is simultaneously redrawing procurement geography toward Asian assembly clusters and compressing unit economics for established European and Japanese suppliers. This displacement dynamic fragments pricing power across detector tiers while forcing legacy manufacturers to unbundle hardware from service contracts to defend margin structures.
Pricing Analysis
United States proton therapy centers pay 40% premiums over German university hospitals for identical cadmium-zinc-telluride detector specifications due to FDA 21 CFR Part 1020 compliance documentation burdens and NIST traceability requirements. Pricing stratifies across premium, standard, and economy tiers where semiconductor substrates with sub-nanosecond timing resolution command certification-linked premiums, while plastic scintillator alternatives capture cost-sensitive clinic procurement. Cost compression in the scintillation tier intensifies because Indian PLI-subsidized assembly operations are scaling domestic production for diagnostic imaging retrofits. Community imaging centers exhibit highest price sensitivity, whereas academic medical centers with FLASH radiobiology programs demonstrate lowest sensitivity due to grant-funded experimental budgets.
Supply Chain Analysis
High-purity germanium crystal refining concentrates in Belgium, Russia, and Ukraine, creating single-source vulnerability for semiconductor detector substrates used in proton beam characterization systems. Manufacturing rests on three critical inputs: cadmium-zinc-telluride wafers from specialty refiners, bismuth germanate crystals for PET calibration, and silicon photomultiplier arrays displacing legacy photomultiplier tubes. Tariff exposure looms as EU MDR Article 10 conformity assessments extend clearance timelines for Asian-originating components. Distribution runs through hospital network GPO contracts in the United States, direct manufacturer relationships at German academic centers, and government procurement channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Detector vendors are pivoting from hardware margin capture toward recurring calibration service revenue, with predictive maintenance contracts expanding at triple the rate of unit sales across United States cancer center networks. This service-attach opportunity restructures competitive economics around telemetry-enabled sensor drift forecasting rather than upfront equipment pricing.
For Market Incumbents: Fortify long-term maintenance agreements at major proton therapy centers by embedding machine learning-enabled condition monitoring into standard service tiers. Incumbent manufacturers face erosion from independent service organizations unbundling calibration audits from hardware procurement, requiring backward integration into predictive analytics capabilities to retain revenue pools. Priority investments should target middleware development for 1990s-era treatment planning software integration at community cancer centers. For New Entrants and Emerging Players: Automated calibration system deployment gaps at United States health systems with 15% medical physicist vacancy rates offer immediate white-space entry. New entrants should target India's Tamil Nadu and Gujarat diagnostic imaging clusters where PLI scheme subsidies compress capital barriers for domestic assembly operations. A direct-to-hospital-network RFP strategy bypassing traditional distributor markups captures procurement committees unbundling hardware from service contracts. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed dosimetry pure-plays holding specialized proton therapy expertise but lacking predictive maintenance platform scale. The five-to-ten year viability window favors acquisition targets with EU MDR Class IIa clearance already secured, avoiding certification backlog delays. Watch Medicare coverage determinations for FLASH therapy as the inflection signal that will cascade into detector procurement specifications and replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Platform Development | Machine learning telemetry at United States cancer centers unbundles service contracts from hardware sales. |
| EU MDR Class IIa Certification Investment | Early notified body clearance captures procurement preference as European hospital committees delay purchase decisions. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu and Gujarat assembly investments serve diagnostic expansion in tier-2 cities with import substitution economics. |
| FLASH Therapy Detector Validation Partnerships | Academic medical center research programs in Germany and Japan pilot microsecond-resolution sensor geometries. |
| Legacy System Middleware Integration | 1990s-era treatment planning software compatibility secures community cancer center procurement against digital retrofit delays. |
Research Methodology
Cross-validation between hospital procurement database analysis and medical physicist interviews anchors the qualitative findings on unbundling trends in United States health systems. Primary fieldwork engaged radiation oncology department heads, biomedical engineers, GPO contracts managers, and FDA regulatory consultants, supplemented by secondary validation through CMS Medicare reimbursement filings, EU MDR notified body clearance databases, and ISO 15285 technical documentation. Bottom-up unit economics modeling triangulates against top-down market sizing from proton therapy center construction pipelines and diagnostic imaging equipment shipment data.
Sensitivity analysis across detector architecture adoption curves and reimbursement policy scenarios frames the analytical approach over the projection horizon. Segmentation dimensions include detector type, application tier, end-user category, and technology generation, with additional modeling of regulatory pathway complexity across FDA, NRC, and EU MDR jurisdictions. CAGRs derive from equipment replacement cycle analysis, proton therapy center commissioning schedules, and FLASH radiobiology research program expansion trajectories.
Material uncertainties — Medicare coverage determinations for advanced radiotherapy modalities, semiconductor substrate price volatility, and EU MDR notified body capacity constraints — sit outside the modeled envelope. Forecasts reflect assumptions on regulatory clearance timelines and hospital capital budget allocation patterns. Practitioners should keep alternative scenarios live as reimbursement policy and supply chain concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cellular Encapsulation Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
India Clear Aligners Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Trial Prostheses Market
Medical Devices
Endodontic Files Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Spinal Implant Market
Medical Devices
Global Endovascular Aneurysm Repair Devices Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
Cardiac Ablation Devices Market
Medical Devices
Implantable Pacemaker Market