
 Craniomaxillofacial Implants Market | 2026-2036
Craniomaxillofacial Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Craniomaxillofacial Implants Market Intelligence
The EU Medical Device Regulation (MDR) is repositioning compliance requirements for permanent implantable devices across European markets. Stryker Corporation leverages its broad trauma portfolio to sustain leadership in cranial fixation systems. Zimmer Biomet anchors its position through specialized titanium mesh geometries for complex orbital reconstructions. Medtronic competes with integrated navigation and implant platforms that streamline surgical workflow in neurosurgical units.
Craniomaxillofacial implants comprise metallic and biocompatible polymer devices engineered to restore structural integrity and function to the skull, facial skeleton, and mandible, typically manufactured from titanium alloys or polyetheretherketone via CNC milling or electron-beam additive processes to achieve patient-specific anatomical fit with tensile strengths exceeding 900 MPa. Their primary purpose is to stabilize bone segments, correct congenital or acquired deformities, and enable osseointegration following traumatic injury, oncologic resection, or developmental anomaly. Titanium plates and screws dominate procedural volume due to established biomechanical performance and intraoperative malleability, while polyetheretherketone patient-specific implants represent the fastest-expanding material segment as surgeons prioritize radiolucency and thermal stability in complex cranial defect repair. Trauma reconstruction applications command substantial margin pools because emergency protocols limit price sensitivity and require rapid implant availability across hospital networks.
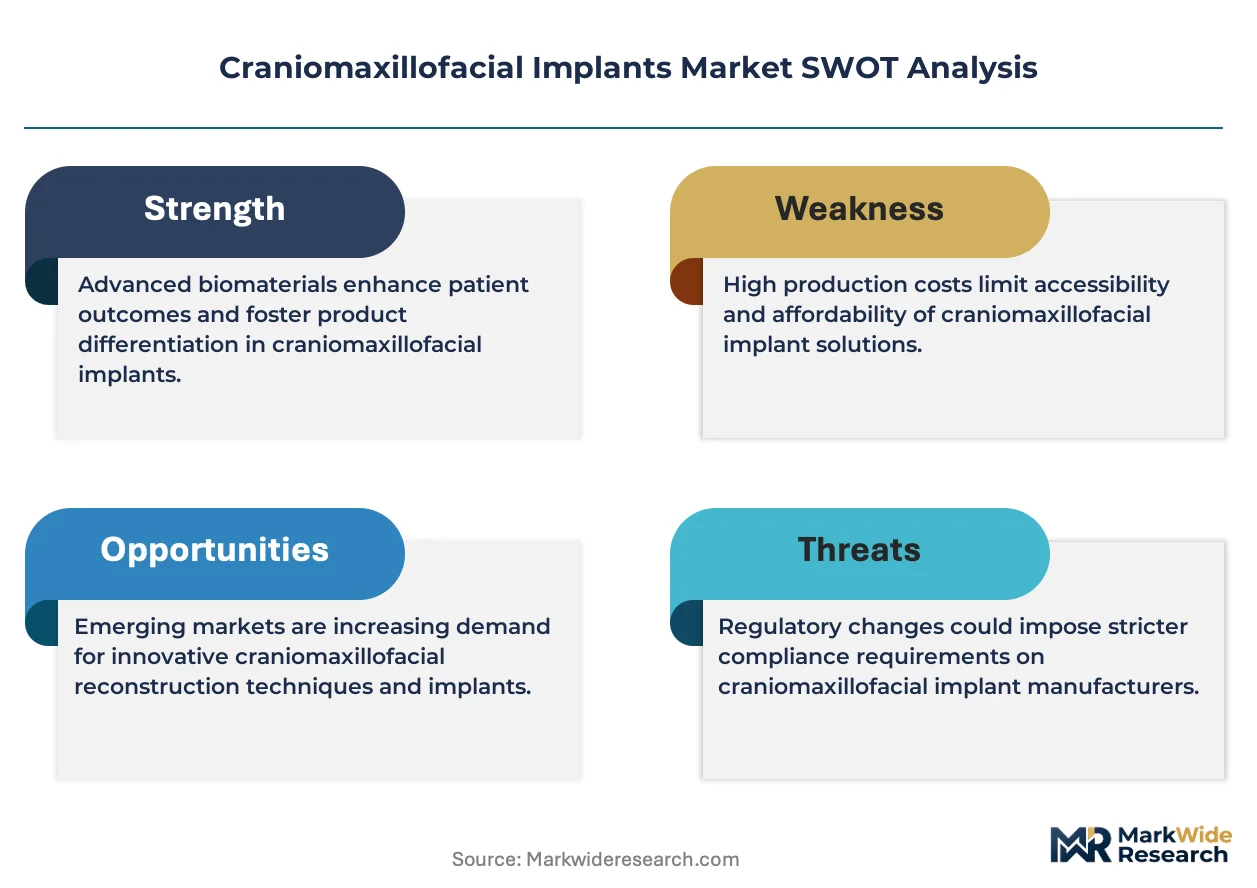
The FDA's 510(k) clearance framework and the EU MDR's clinical evidence requirements for Class III implantable devices shape product development timelines, post-market surveillance obligations, and market access pathways for manufacturers. ISO 5832 standards for surgical implant materials establish baseline metallurgical and biocompatibility benchmarks that titanium and polymer formulations must satisfy before commercialization. Stakeholders must monitor evolving reimbursement policies for patient-specific additive-manufactured implants as health technology assessment bodies weigh cost-effectiveness against improved surgical precision and reduced revision rates.
Market Dynamics
Patient-specific additive manufacturing is compressing production cycles for titanium cranial plates while simultaneously fragmenting procurement authority from centralized hospital purchasing toward individual neurosurgical units.
Growth Catalysts
- 510(k) Pathway Modernization:The FDA's streamlined review framework for 3D-printed medical devices accelerates regulatory clearance timelines for electron-beam melted titanium implants.
- Trauma Volume Concentration:Specialized hospitals in the United States, Germany, and Japan generate sustained procedural demand through established Level I trauma center networks.
- PEEK Material Properties:Polyetheretherketone's radiolucency and thermal stability expand indications for complex orbital and cranial defect reconstructions.
Market Restraints
- Titanium Powder Supply Concentration:Spherical titanium-6 aluminum-4 vanadium powder production clusters among a limited set of plasma atomization specialists, creating input cost volatility.
- EU MDR Compliance Burden:The Medical Device Regulation's clinical evidence requirements for Class III permanent implants extend development timelines and surveillance obligations.
- Revision Surgery Economics:Biomechanical limitations in load-bearing mandibular applications sustain substitution risk from autologous bone grafting in select oncologic cases.
Strategic Opportunities
- Ambulatory Surgical Center Expansion:Outpatient cranial fixation procedures in the United States create channel diversification beyond traditional hospital-based procurement.
- Navigation-Implant Convergence:Intraoperative surgical planning software integration with patient-specific implant design compresses operative time and improves fit accuracy.
- Japan Reimbursement Tailwind:METI's health technology assessment frameworks increasingly recognize additive-manufactured devices for premium procedural reimbursement.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Electron-beam melting and selective laser sintering operations require specialized metallurgical expertise that outpaces current vocational training pipeline output.
- Biocompatibility Certification Complexity:ISO 5832 compliance testing for novel titanium alloy formulations extends preclinical validation timelines.
- Legacy ERP Integration Friction:Patient-specific implant workflows strain hospital inventory management systems designed for standard SKU-based procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Craniomaxillofacial Implants Market |
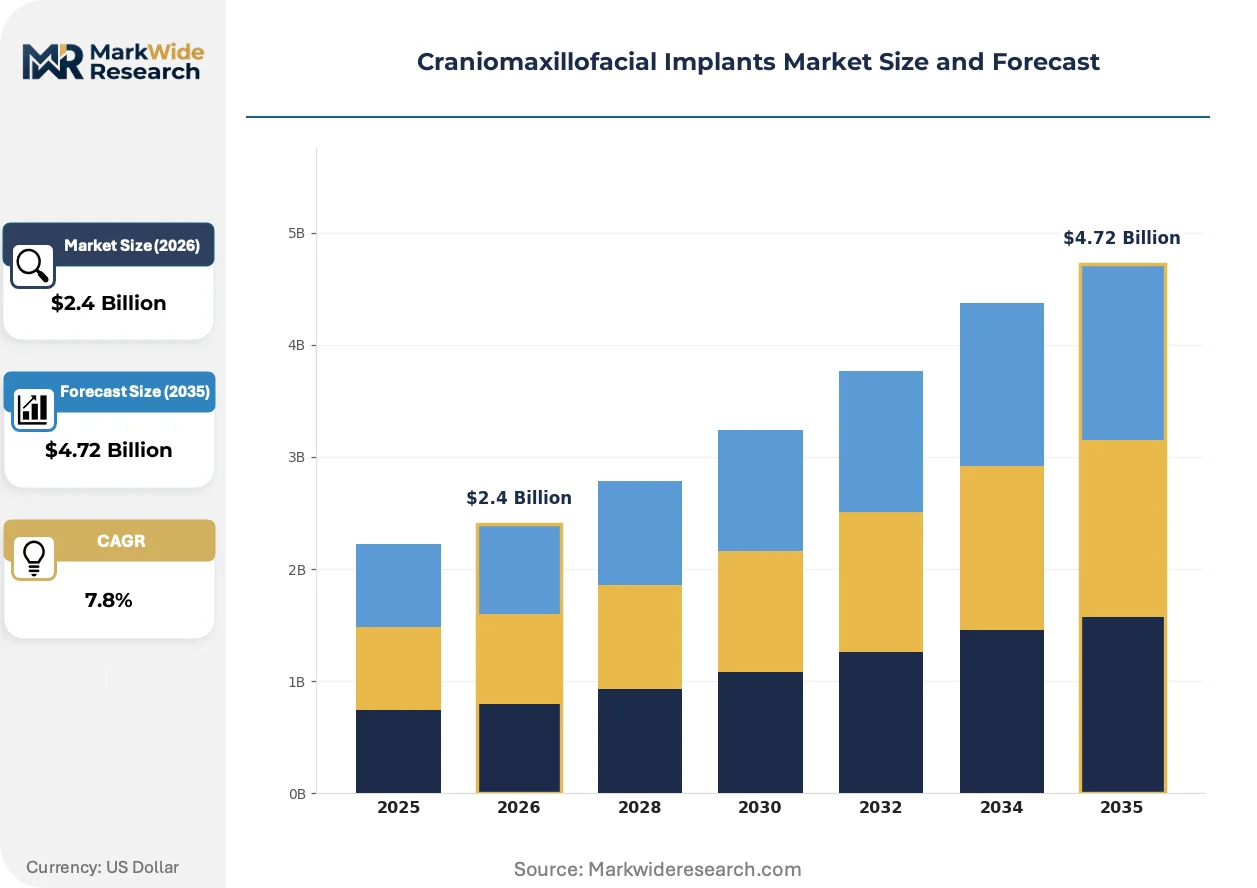
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Screws, Meshes, Distraction Devices, Fixators, Pins Material: Titanium, Hydroxyapatite, Polyetheretherketone, Bone Cement, Bioceramics, Polymethylmethacrylate Application: Orthognathic Surgery, Trauma Reconstruction, Cranial Defect Repair, Temporomandibular Joint Reconstruction, Congenital Deformities, Oncologic Reconstruction End User: Maxillofacial Surgeons, Plastic Surgery Units, Dental Clinics, Rehabilitation Centers, Specialized Hospitals, Ambulatory Surgical Centers |
| Companies Covered | Stryker Corporation, Zimmer Biomet, Medtronic, Johnson & Johnson Services, Inc., KLS Martin Group, Medartis AG, Integra LifeSciences, Aesculap Implant Systems, OsteoMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Craniomaxillofacial Implants Market Strategic Shifts & Innovations
Digital surgical planning tools and advanced manufacturing methods are compressing the gap between diagnostic imaging and implant deployment, reshaping how cranial reconstruction procedures are prepared and executed.
Electron-beam additive manufacturing of titanium lattice structures is electrifying the production economics of patient-specific cranial plates. Neurosurgical units at academic medical centers are adopting these implants for complex defect reconstructions at accelerating rates. The technology is electrifying traditional CNC milling's dominance in mid-volume case categories.
The EU MDR's post-market surveillance requirements for permanent implantable devices mandate systematic clinical follow-up data collection. Manufacturers must establish robust vigilance systems to track long-term osseointegration outcomes. Class III cranial fixation systems face the steepest compliance adaptation burden, driving consolidation among smaller European device firms.
Hospital procurement departments are unbundling after-sales technical support from implant pricing, treating surgical planning assistance as a separately negotiated service line. Specialized distributors are displacing traditional broad-line medical device vendors in complex cranial reconstruction accounts. This pattern concentrates in German and Japanese markets where surgeon training and case support carry premium valuation.
Craniomaxillofacial Implants Market Segmentation
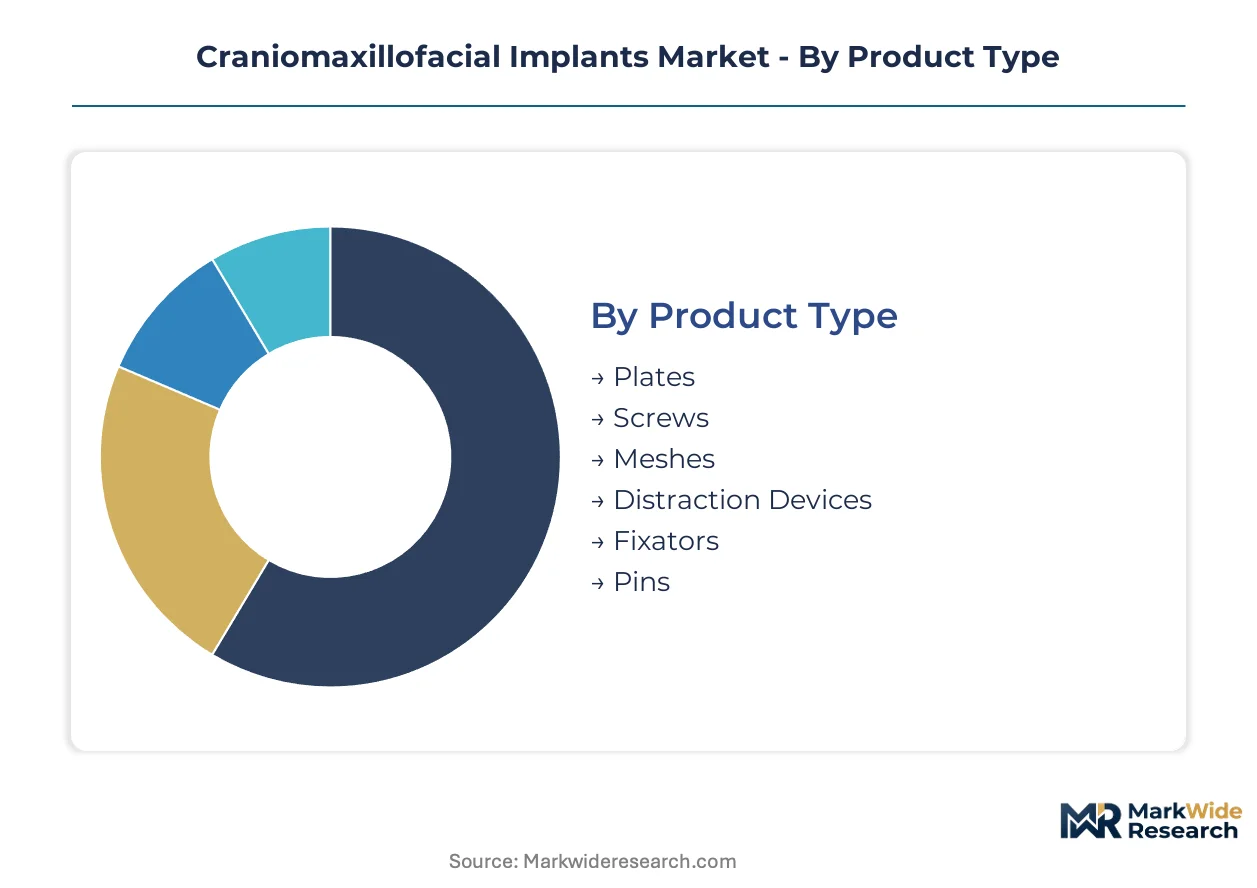
Craniomaxillofacial implant segmentation reveals how procedural complexity, material science advances, and care setting economics fragment purchasing authority across hospital networks. Understanding these divisions exposes where premium pricing holds and where commoditization pressures concentrate.
Product Type:
Standalone fixation hardware dominates standalone trauma procedures, while integrated plate-screw systems embed into navigation-guided cranial reconstructions at academic centers.
- Plates:Titanium plates with thickness profiles from 0.3mm to 2.0mm provide structural rigidity for mandibular continuity restoration. Demand clusters at Level I trauma centers in the United States and Germany where emergency protocols prioritize rapid implant availability over cost negotiation.
- Screws:Self-tapping cortical screws with optimized thread pitch distribute masticatory loads across osteotomy sites. Japanese neurosurgical units favor micro-screw configurations under 1.5mm diameter for pediatric cranial vault reconstructions.
- Meshes:Titanium mesh with hexagonal pore geometry enables intraoperative contouring for complex orbital floor defects.
- Distraction Devices:Internal mandibular distractors with activation arms permit gradual bone lengthening in congenital micrognathia cases.
- Fixators:External cranial fixation frames stabilize unstable fractures pending definitive reconstruction.
- Pins:Trocar-tipped pins secure temporary maxillomandibular fixation during orthognathic surgery.
Plates lead volumes today; meshes are gaining share fastest.
Material:
Cost tier stratification separates premium patient-specific formulations from standard catalog items, with reimbursement bandwidth determining clinical adoption.
- Titanium:Ti-6Al-4V ELI alloy delivers tensile strength exceeding 900 MPa with fatigue resistance for load-bearing mandibular applications. German trauma networks specify electron-beam melted titanium for complex cranial defects, accepting premium pricing for improved osseointegration surfaces.
- Hydroxyapatite:Sintered calcium phosphate ceramic coating accelerates bone apposition on implant surfaces. Japanese orthopedic centers favor hydroxyapatite-coated plates in elderly patients with compromised bone density.
- Polyetheretherketone:Radiolucent PEEK enables postoperative CT imaging without artifact interference in cranial defect repair.
- Bone Cement:Polymethylmethacrylate variants provide immediate fixation in palliative oncologic reconstructions.
- Bioceramics:Resorbable calcium phosphate compositions eliminate secondary removal surgery in pediatric populations.
- Polymethylmethacrylate:Custom-milled PMMA cranioplasty plates serve cost-sensitive markets with adequate biocompatibility profiles.
Titanium commands revenue concentration; PEEK expands most quickly.
Application:
Procedure urgency and reconstructive complexity determine margin structure, with emergency trauma sustaining premium pricing against elective orthognathic volumes.
- Orthognathic Surgery:LeFort I osteotomy fixation with rigid internal plates corrects dentofacial deformities through predictable skeletal repositioning. Ambulatory surgical centers in the United States are expanding orthognathic case volumes as anesthesia protocols shorten length of stay.
- Trauma Reconstruction:Panfacial fracture management requires comprehensive plating systems with intraoperative adaptability. German trauma networks mandate 24-hour implant availability, compressing procurement negotiation leverage.
- Cranial Defect Repair:Patient-specific titanium cranioplasty restores vault integrity following decompressive craniectomy.
- Temporomandibular Joint Reconstruction:Alloplastic joint prostheses replace failed autologous grafts in revision scenarios.
- Congenital Deformities:Distraction osteogenesis devices enable gradual correction of craniosynostosis and hemifacial microsomia.
- Oncologic Reconstruction:Free flap fixation plates stabilize vascularized bone transfers following ablative tumor surgery.
Trauma reconstruction leads procedural volumes; cranial defect repair climbs the fastest.
End User:
Customer type fragmentation distributes purchasing influence across specialized surgical units, academic departments, and outpatient facilities with divergent technical support requirements.
- Maxillofacial Surgeons:OMFS specialists command case selection authority for complex mandibular reconstructions, specifying plate thickness and screw length profiles. United States academic medical centers concentrate high-volume oncologic cases requiring navigation-integrated implant systems.
- Plastic Surgery Units:Craniofacial fellowship-trained plastic surgeons prioritize aesthetic outcomes in orbital and nasal reconstructions. Japanese cosmetic surgery centers drive demand for PEEK implants in secondary rhinoplasty with structural grafting.
- Dental Clinics:Oral surgeons in outpatient settings perform dentoalveolar trauma fixation with limited plating inventories.
- Rehabilitation Centers:Post-acute facilities manage prosthetic rehabilitation following implant-supported reconstruction.
- Specialized Hospitals:Dedicated craniofacial centers consolidate complex case referrals and implant procurement negotiation.
- Ambulatory Surgical Centers:Freestanding ASCs in the United States are expanding cranial fixation case volumes as reimbursement frameworks recognize outpatient safety profiles.
Specialized hospitals anchor procurement volumes today; ambulatory surgical centers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cranial reconstruction techniques trace their modern lineage to Swiss-German trauma surgery innovations of the 1950s, with titanium plating systems first commercialized in Basel and subsequently refined through United States military medical research during Vietnam-era combat casualty management.
United States
Level I trauma center networks in Baltimore, Houston, and Los Angeles generate concentrated procedural demand for emergency cranial fixation hardware. The FDA's 510(k) pathway modernization accelerates clearance timelines for electron-beam melted titanium implants from domestic additive manufacturing facilities. Academic medical centers in Boston and San Francisco anchor patient-specific implant adoption through integrated surgical navigation platforms.
Germany
Industrial clusters in Tuttlingen and Freiburg sustain precision machining heritage for CNC-milled titanium plates serving panfacial trauma reconstruction. The EU MDR's clinical evidence requirements for Class III permanent implants extend surveillance obligations for manufacturers headquartered in Baden-Württemberg. Munich trauma networks mandate 24-hour implant availability, compressing procurement negotiation leverage for hospital purchasing consortia.
Japan
Tokyo and Osaka metropolitan areas concentrate neurosurgical case volumes for complex cranial defect repair using patient-specific formulations. METI's health technology assessment frameworks increasingly recognize additive-manufactured devices for premium procedural reimbursement. Kobe medical device manufacturing clusters specialize in micro-screw configurations under 1.5mm diameter for pediatric cranial vault reconstructions.
Switzerland
Basel and Zurich anchor European headquarters for multinational trauma portfolio companies with heritage in cranial fixation system development. Swissmedic maintains stringent vigilance requirements for permanent implantable devices that shape post-market surveillance investments. The Jura Arc precision manufacturing corridor supplies specialized titanium powder feedstock to electron-beam melting operations across Alpine medical technology clusters.
United Kingdom
London and Birmingham academic medical centers drive navigation-integrated cranial reconstruction case volumes through specialized neurosurgical units. The Medicines and Healthcare products Regulatory Agency enforces EU MDR-equivalent standards for Class III implantable devices in the post-Brexit regulatory framework. Cambridge medical technology incubators cultivate digital surgical planning software that converges with patient-specific implant design workflows.
Craniomaxillofacial Implants Market Key Industry Players
Capital-heavy producers with captive additive manufacturing facilities compete with asset-light designers outsourcing electron-beam melting operations to specialized foundries. Market structure concentrates around diversified trauma portfolio companies, mid-cap craniofacial specialists, and emerging patient-specific implant pure-plays. Three archetypes dominate: integrated navigation-implant platform vendors, titanium powder-to-implant vertically integrated manufacturers, and digital surgical planning software licensors. Competitive dynamics center on regulatory clearance velocity for 3D-printed devices and surgeon training program deployment across academic medical center networks.
Among diversified trauma portfolio companies, Stryker Corporation and Zimmer Biomet occupy positions as scale-driven anchors with broad international distribution infrastructure. Medtronic represents the integrated navigation-implant platform archetype, exemplifying convergence between intraoperative surgical planning software and patient-specific hardware deployment. These three companies sit within distinct competitive vectors—trauma portfolio breadth, material science specialization, and digital-physical integration—rather than direct product-for-product substitution.
| Leading Market Players |
|---|
| Stryker Corporation |
| Zimmer Biomet |
| Medtronic |
| Johnson & Johnson Services, Inc. |
| KLS Martin Group |
| Medartis AG |
| Integra LifeSciences |
| Aesculap Implant Systems |
| OsteoMed |
| Others |
Cost & Logistics Intelligence
Electron-beam additive manufacturing of titanium lattice structures compresses per-unit production costs for patient-specific cranial plates while concentrating powder feedstock sourcing among plasma atomization specialists in the Jura Arc corridor. This dual transformation simultaneously expands margin pools for manufacturers with captive additive facilities and exposes price volatility risks where spherical Ti-6Al-4V powder contracts reset quarterly.
Pricing Analysis
Three-tier pricing structure across premium patient-specific, standard catalog, and economy PMMA levels stratifies the market by customization depth and regulatory certification tier. Price differentiation hinges on FDA 510(k) clearance status and electron-beam melting surface finish grades, with premium tiers commanding substantial markups for osseointegration-optimized lattice geometries. Cost compression in standard titanium plate categories is intensifying as German trauma networks consolidate procurement through hospital purchasing consortia. Emergency trauma reconstruction applications exhibit the lowest price sensitivity due to 24-hour availability mandates, while ambulatory surgical center orthognathic volumes negotiate hardest on per-procedure implant bundles.
Supply Chain Analysis
Direct-to-hospital channels handle specialized neurosurgical unit demand for patient-specific implants, while distributor networks serve catalog trauma hardware to Level I centers. Geographic supply concentration clusters in Switzerland for precision titanium powder, Germany for CNC-milled plates, and Japan for micro-screw configurations under 1.5mm diameter. Raw material dependencies rest on spherical Ti-6Al-4V ELI alloy feedstock, electron-beam melting equipment from specialized OEMs, and hydroxyapatite ceramic coatings from sintering specialists. Single-source vulnerability in plasma atomization capacity for medical-grade titanium powder creates structural risk where qualified suppliers number fewer than five globally. Distribution runs through specialized craniofacial distributors displacing broad-line vendors in complex reconstruction accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through additive manufacturing cost curves and premium-tier shifts toward patient-specific PEEK formulations. Electron-beam melting yield improvements and METI reimbursement recognition for custom implants justify selective capacity investment.
For Market Incumbents: Anchor trauma portfolio breadth against navigation-implant convergence threats by deepening backward integration into titanium powder supply and securing exclusive electron-beam melting capacity in the Jura Arc corridor. Defend against mid-cap craniofacial specialists through surgeon training program deployment at academic medical centers and GPO contract lock-in across German hospital purchasing consortia. For New Entrants and Emerging Players: Digital surgical planning software licensing offers the most penetrable entry vector, with white-space concentration in navigation-implant workflow integration for United States ambulatory surgical centers. Target Japan's pediatric cranial vault reconstruction segment where micro-screw demand outpaces domestic supply and METI frameworks recognize premium additive-manufactured devices. Pursue hospital system partnership models that unbundle surgical planning assistance from hardware pricing. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light patient-specific implant designers lacking captive additive manufacturing facilities. Long-term viability favors vertically integrated producers with electron-beam melting operations and FDA 510(k) clearance velocity. The signal to watch is EU MDR vigilance system deployment costs driving consolidation among smaller European device firms without post-market surveillance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| 510(k) Pathway Modernization | FDA streamlined review accelerates clearance timelines for electron-beam melted titanium implants from domestic facilities. |
| Navigation-Implant Platform Integration | Intraoperative surgical planning software convergence compresses operative time and improves patient-specific fit accuracy. |
| EU MDR Vigilance System Investment | Post-market surveillance infrastructure satisfies Class III permanent implant requirements and extends competitive moats. |
| Ambulatory Surgical Center Partnership | Outpatient cranial fixation volume expansion diversifies channel mix beyond traditional hospital-based procurement. |
| Titanium Powder Backward Integration | Captive plasma atomization capacity insulates against spherical Ti-6Al-4V feedstock price volatility and supply interruption. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with neurosurgeons, maxillofacial surgeons, hospital purchasing committee members, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up implant volume modeling and top-down trauma reconstruction procedure estimates were triangulated to constrain forecast variance.
Comparable-period anchoring calibrated the projection horizon against historical reference periods spanning pre-COVID baseline, pandemic disruption, and recovery normalization phases. Segmentation dimensions modeled include product type, material formulation, application urgency, and end-user facility category across the analysis window. CAGRs were derived from procedure volume elasticity to trauma incidence rates and additive manufacturing capacity expansion curves. Forecast inputs incorporated electron-beam melting yield improvement trajectories and METI health technology assessment recognition timelines for patient-specific devices.
The model assumes a particular technology adoption path; alternative pathways for selective laser sintering versus electron-beam melting would alter the outlook for titanium implant surface properties and production economics. Forecasts reflect assumptions regarding EU MDR compliance cost absorption and spherical titanium powder supply concentration that could revise under trade restriction or qualification failure scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Angiography Devices Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Baby Ear Thermometer Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
India Respiratory Devices Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Breast Prosthesis Market
Medical Devices
US Intrauterine Devices Market
Medical Devices
Global Neurovascular Guidewires Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Global Active Implantable Medical Devices Market